
 United States Chocolate Market | 2026-2036
United States Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Chocolate Market Analytics
FDA Food Safety Modernization Act certification timelines for imported cacao is collapsing, compressing market access windows for smaller processors. Mars Incorporated leverages vertical integration from bean sourcing through retail distribution to sustain cost advantages across mass-market segments. The Hershey Company anchors its position through deep channel control in convenience and drugstore networks. Mondelez International competes on R&D intensity, particularly in reduced-sugar and clean-label formulations.
Chocolate comprises roasted and ground cacao seeds combined with cocoa butter, sugar, and emulsifiers, typically specified at minimum cocoa mass thresholds that define product category. Its primary commercial purpose spans confectionery, baking applications, and premium gifting occasions where fat content and particle size distribution determine mouthfeel quality. Milk Chocolate retains the largest volume share though structural margin pools have shifted toward Dark Chocolate as cocoa percentage becomes a consumer signaling mechanism. Specialty Shops within the Distribution Channel dimension capture disproportionate value per unit, while Online Stores represent the fastest-growing access point for artisan and subscription formats.
FDA standards for added sugar disclosure and USDA organic certification requirements shape permissible health claims and retail placement eligibility. State-level sugar-sweetened beverage taxes in jurisdictions like Philadelphia and Seattle extend to certain chocolate products, forcing reformulation or pricing recalibration. Stakeholders must monitor evolving FDA guidance on cacao origin labeling and anticipate whether California's Proposition 65 expansion will impose heavy metal disclosure obligations on dark chocolate positioned for antioxidant marketing.
Market Dynamics
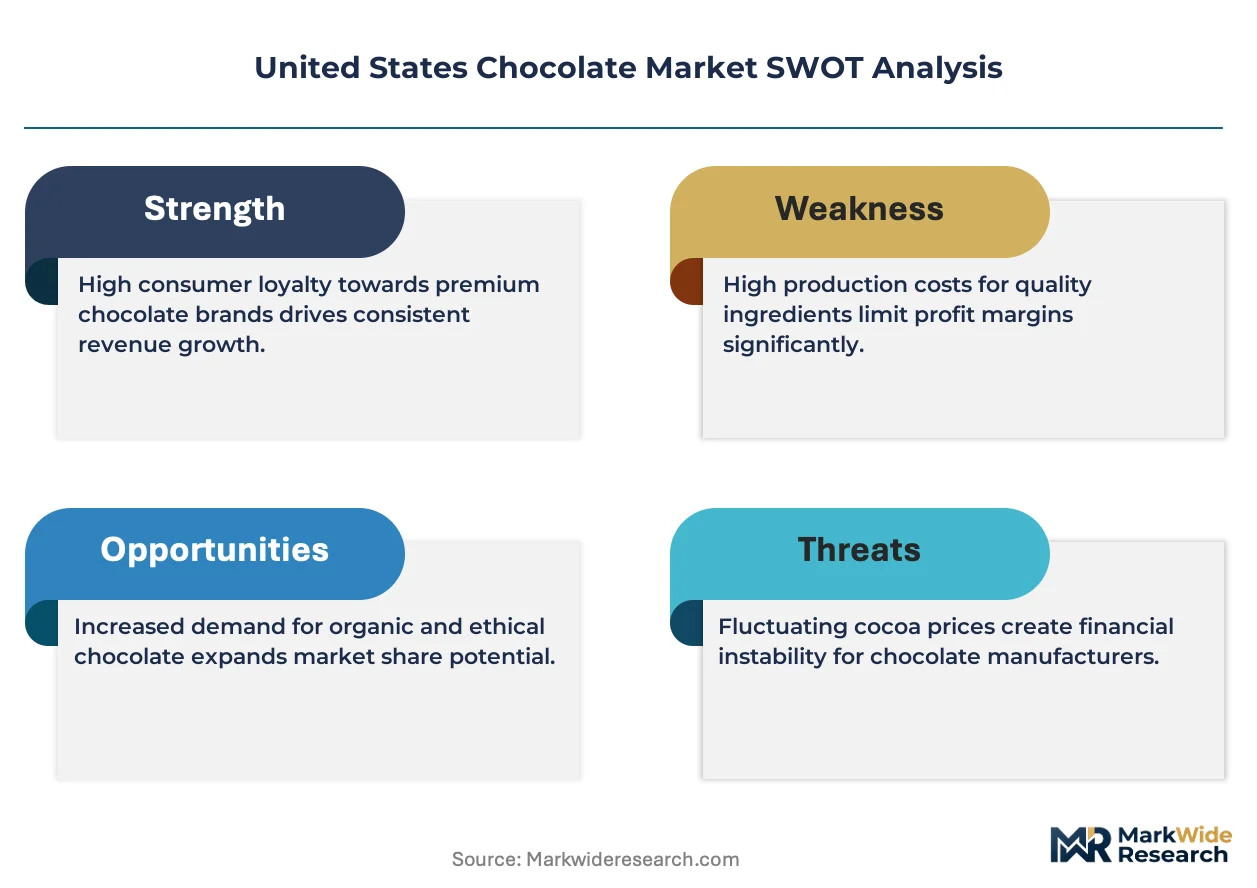
FDA Food Safety Modernization Act certification timelines for imported cacao are compressing market access windows, forcing processors to accelerate compliance investments or exit the supply base entirely. This regulatory pressure intersects with state-level sugar tax expansion to reshape formulation priorities across mass and premium tiers.
Growth Catalysts
- Specialty retail channel expansion:Direct-to-consumer and subscription formats in California and the Northeast corridor are pulling premium volume away from conventional grocery. These channels reward origin storytelling and small-batch credentials.
- FDA added sugar disclosure mandates:Front-of-pack labeling requirements are accelerating clean-label reformulation across milk chocolate portfolios. Brands that preempt compliance capture shelf placement advantages in health-forward retail banners.
- Bean-to-bar processing technology:Small-scale roasting and winnowing equipment is democratizing craft production. Regional processors in Oregon and Vermont are deploying these systems to shorten supply chains and capture margin pools previously held by importers.
Market Restraints
- Cocoa butter price volatility:Input cost swings from West African supply disruptions compress margins for processors without forward contracting capabilities. Mass-market producers face particular pressure as they cannot pass through increases to price-sensitive segments.
- FDA import certification bottlenecks:Collapsing timelines for foreign supplier verification are excluding smaller origin processors from the US market. Cacao from Ecuador and Peru faces particular documentation hurdles.
- Plant-based fat substitution:Oat and coconut oil formulations in confectionery applications are capturing functional chocolate occasions outside strict regulatory definitions. These alternatives bypass cocoa butter cost exposure entirely.
Strategic Opportunities
- Antioxidant positioning in dark chocolate:California Proposition 65 disclosure requirements around heavy metals have created a compliance moat for tested, certified-clean products. Brands that invest in cadmium and lead screening can command shelf space in natural retail.
- Food service operator adoption:Premium gifting and seasonal confectionery programs are expanding in hotel and restaurant channels. These operators seek portion-controlled formats with origin credentials for dessert and amenity applications.
- USDA organic certification pipeline:Supply-constrained organic cacao is attracting contract premiums from processors building certified portfolios. Vertical integration into Ecuadorian and Dominican organic cooperatives secures allocation.
Industry Challenges
- FSMA compliance talent scarcity:Qualified food safety managers with foreign supplier verification expertise command premium compensation. Mid-size processors in the Midwest face particular recruitment friction against coastal competitors.
- Legacy ERP integration with traceability platforms:Blockchain and mass-balance tracking systems require data architecture upgrades that strain IT budgets. Smaller craft producers delay adoption despite retail buyer mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Chocolate Market |
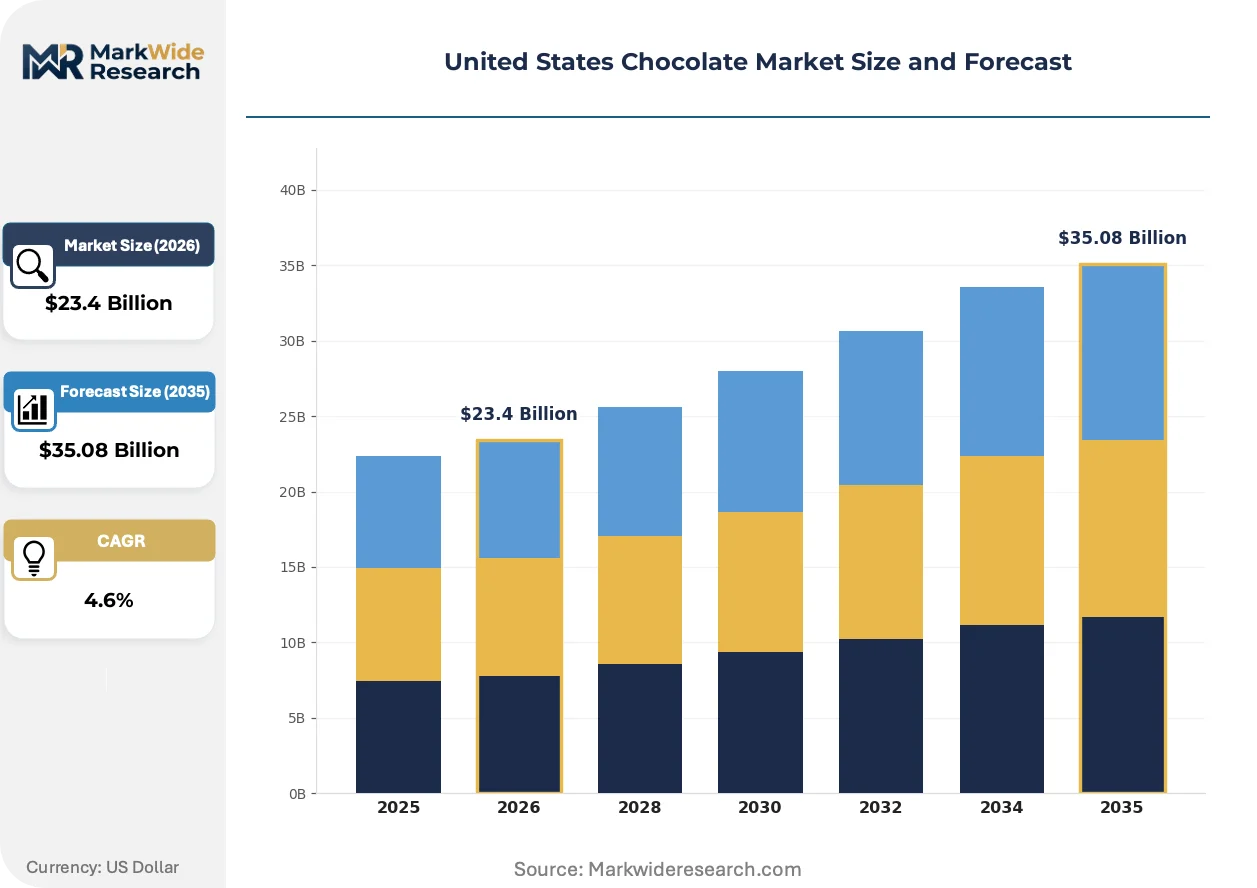
| Market Size in 2026 | $23.4 Billion |
| Market Size in 2035 | $35.08 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Food Service, Confectionery Manufacturers, Bakeries Packaging Type: Bars, Boxes, Bins, Callets Distribution Channel: Supermarkets, Online Stores, Specialty Shops, Convenience Stores |
| Companies Covered | Mondelez International, Tootsie Roll Industries, Mars Incorporated, Candy Club Holdings Limited, Rocky Mountain Chocolate Factory, The Hershey Company, Chocoladefabriken Lindt & Sprüngli AG, Nestle S.A., Ferrero Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Chocolate Market Evolving Landscape
Formulation science and supply chain digitization are splitting the market into distinct technical tiers. Processors must now choose between capital-intensive precision processing and lean, origin-focused craft positioning.
Precision conching and particle size engineering is bifurcating the premium segment. Large-scale manufacturers in Pennsylvania and Illinois are deploying laser diffraction and rheology-controlled systems to achieve sub-20-micron particle distributions at industrial volume. This capability is compressing the traditional craft advantage in mouthfeel quality while enabling clean-label milk chocolate with reduced fat content.
FDA guidance on cacao origin labeling is tightening disclosure requirements for "single-origin" claims. The agency's 2023 draft guidance on geographical indication enforcement is forcing brands to substantiate farm-level provenance or retreat to broader regional designations. Dark chocolate positioned above 70% cocoa mass faces the highest scrutiny, as antioxidant marketing invites closer examination of supply chain representations.
Subscription and direct-to-consumer channels are displacing specialty retail as the primary discovery mechanism for artisan brands. California-based operators pioneered this shift, with Northeast consumers now matching their adoption velocity. These buyers prioritize transparency portals showing farmgate pricing and fermentation protocols over traditional shelf presence, compressing the role of distributor intermediaries in premium segment access.
United States Chocolate Market Segmentation
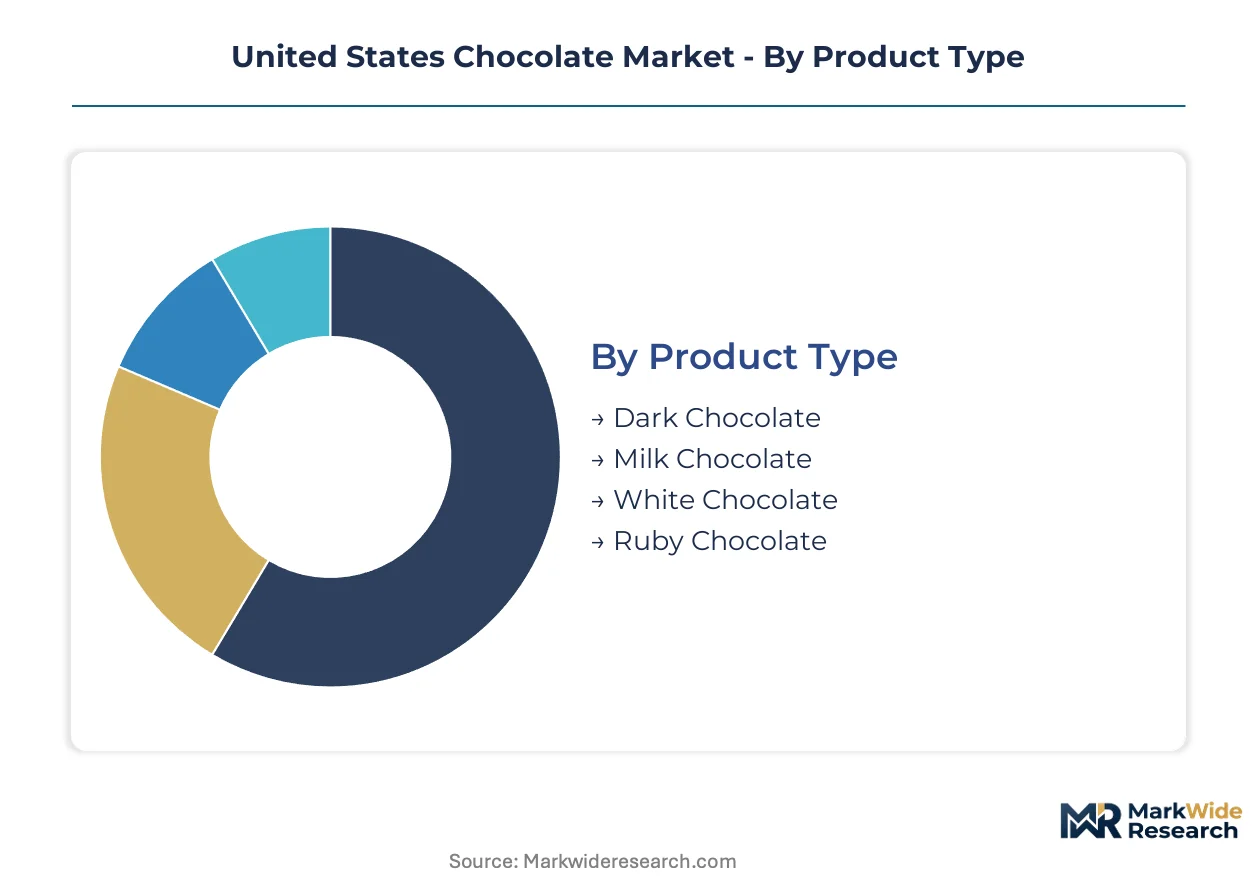
Segmentation in the United States chocolate market reveals how regulatory pressure and channel evolution concentrate value capture. Each dimension exposes distinct margin pools and compliance burdens that reshape competitive positioning across domestic processors.
Product Type:
Domestic production dominates milk and dark chocolate volumes, while ruby chocolate remains import-dependent from European and Asian processors. Export-led segments face compressed FDA certification windows that favor established multinationals with dedicated compliance infrastructure.
- Dark Chocolate:Cocoa mass thresholds above 70% define this category, with particle size distribution and fat content determining premium positioning. California and Northeast consumers drive demand through specialty retail channels where antioxidant claims require Proposition 65 heavy metal compliance. FDA scrutiny of origin labeling intensifies as single-origin marketing proliferates.
- Milk Chocolate:Formulations balance cocoa solids with dairy powder and cocoa butter to achieve characteristic mouthfeel at scale. Pennsylvania and Illinois production clusters supply mass-market volume through convenience and drugstore networks. Added sugar disclosure mandates accelerate reformulation toward reduced-sugar variants.
- White Chocolate:Cocoa butter base without cocoa solids occupies confectionery and baking applications.
- Ruby Chocolate:Proprietary cacao variety processing yields pink coloration without added dyes, currently limited by patent-controlled supply.
Milk chocolate holds the largest share; momentum sits with dark chocolate as cocoa percentage becomes a consumer signaling mechanism.
End User:
Cost tier stratification separates commodity volume from premium value capture, with food service operators demanding portion-controlled formats and origin credentials.
- Retail Consumers:Direct purchase for personal consumption and gifting occasions spans impulse, seasonal, and premium segments. California and Northeast corridor buyers disproportionately drive specialty and subscription channel adoption.
- Food Service:Hotels, restaurants, and institutional operators source portion-controlled formats with fermentation protocol transparency for dessert and amenity programs.
- Confectionery Manufacturers:Industrial buyers of couverture and callets for further processing into finished goods.
- Bakeries:Artisan and commercial baking operations requiring specific viscosity and tempering characteristics.
Retail consumers command the largest volume base; food service is climbing the fastest as premium gifting programs expand.
Packaging Type:
Volume concentration in bars and callets reflects manufacturing scale economies, while boxes capture disproportionate value per unit in gifting occasions.
- Bars:Standard format for retail and food service distribution, with mold design and portion sizing differentiating premium from mass positioning.
- Boxes:Assortment packaging for seasonal and premium gifting commands shelf placement investment in specialty retail.
- Bins:Bulk formats for food service and manufacturing procurement.
- Callets:Disc-shaped couverture optimized for industrial melting and tempering operations.
Bars hold the largest share; boxes are gaining share fastest through direct-to-consumer subscription expansion.
Distribution Channel:
Supply concentration in coastal metropolitan markets shapes channel performance, with digital infrastructure enabling geographic arbitrage for artisan brands.
- Supermarkets:Mass-market volume concentration with slotting fee barriers favoring multinationals with trade marketing budgets.
- Online Stores:Discovery mechanism for artisan and subscription formats displacing specialty retail intermediaries.
- Specialty Shops:Curated selection rewarding origin storytelling and small-batch credentials in California and Northeast urban clusters.
- Convenience Stores:Impulse and immediate consumption occasions with limited SKU breadth.
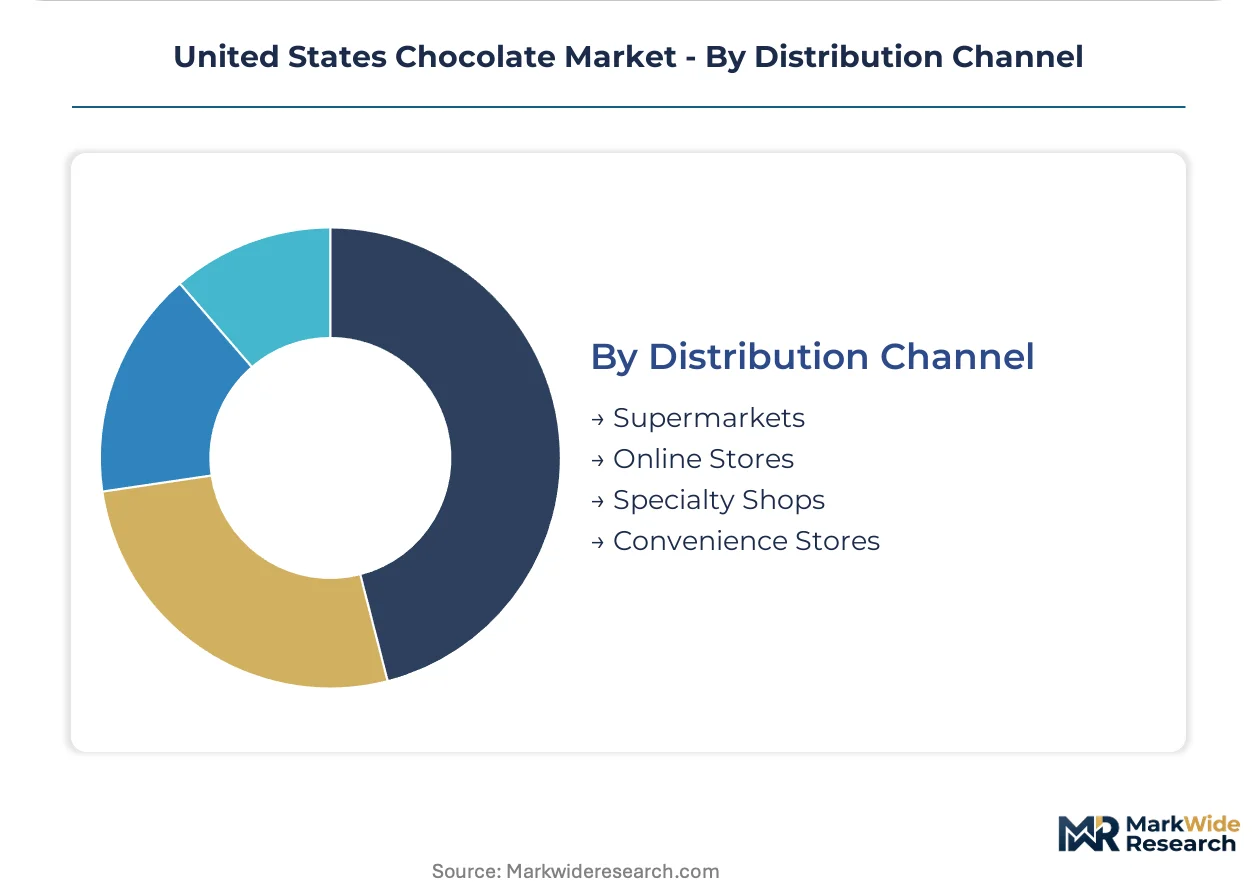
Supermarkets hold the largest share; online stores are expanding most quickly as transparency portals replace shelf presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium chocolate buyers cluster in coastal metropolitan markets where specialty retail density and direct-to-consumer infrastructure enable artisan brand discovery. FDA labeling mandates and state sugar taxes create divergent compliance burdens across jurisdictions. Production and distribution infrastructure concentrates in legacy manufacturing corridors and emerging craft processing clusters.
California
Los Angeles and San Francisco metropolitan areas drive premium dark chocolate adoption through specialty retail and subscription channels. Proposition 65 heavy metal disclosure requirements impose testing burdens on antioxidant-positioned products above 70% cocoa mass. Bean-to-bar processors in Oakland and Santa Cruz deploy small-scale roasting equipment to shorten supply chains and capture margin pools.
Northeast Corridor
New York, Boston, and Philadelphia urban clusters match California's velocity in direct-to-consumer chocolate adoption. Philadelphia's sugar-sweetened beverage tax extends to certain confectionery products, forcing reformulation or pricing adjustments. Specialty retail concentration in Manhattan and Brooklyn rewards origin storytelling and fermentation protocol transparency.
Pennsylvania
Hershey and surrounding counties anchor mass-market milk chocolate production through legacy manufacturing infrastructure. FDA added sugar disclosure mandates accelerate clean-label reformulation across conventional portfolios. The Hershey Company maintains deep channel control in convenience and drugstore networks throughout the state.
Illinois
Chicago-area production facilities supply industrial chocolate volumes to national confectionery and baking markets. Precision conching and particle size engineering capabilities enable sub-20-micron distributions at industrial scale. Mass-market producers face margin pressure from cocoa butter price volatility without premium-tier pricing power.
Oregon and Vermont
Portland and Burlington craft chocolate clusters leverage regional food culture credibility for national distribution. Small-scale winnowing and roasting equipment democratizes production for artisan entrants. These processors capture value through origin credentials and transparency portals showing farmgate pricing rather than conventional retail shelf presence.
United States Chocolate Market Competitive Landscape
Player mix skews toward vertically integrated multinationals with dedicated compliance infrastructure and regional craft specialists with origin-focused positioning. The market exhibits a bifurcated structure where scale-driven manufacturers compete on cost and distribution depth while artisan producers compete on provenance and transparency. Strategic archetypes include bean-to-bar craft operators, industrial couverture suppliers, and mass-market retail brands. Dominant competitive moves encompass backward integration into cacao sourcing and channel diversification into direct-to-consumer formats.
Among multinational confectionery conglomerates, Mars Incorporated, Mondelez International, and The Hershey Company exemplify distinct strategic positions. Mars Incorporated occupies a position emphasizing captive supply chain control from origin through retail. Mondelez International represents R&D-intensive formulation capabilities particularly in reduced-sugar variants. The Hershey Company anchors the mass-market tier through trade marketing investment and convenience channel penetration. These three entities collectively illustrate how scale, integration depth, and channel focus separate competitive outcomes in a regulated, input-cost-volatile environment.
| Leading Market Players |
|---|
| Mondelez International |
| Tootsie Roll Industries |
| Mars Incorporated |
| Candy Club Holdings Limited |
| Rocky Mountain Chocolate Factory |
| The Hershey Company |
| Chocoladefabriken Lindt & Sprüngli AG |
| Nestle S.A. |
| Ferrero Group |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for imported cacao beans concentrate margin pressure on processors lacking forward-contracting capabilities, binding pricing power to supply chain control depth. FDA certification timeline compression for foreign suppliers rewards integrated operators with captive sourcing infrastructure while squeezing spot-market participants.
Pricing Analysis
Cost-plus contracts indexed to ICE cocoa futures dominate processor-producer agreements, with premiums attaching to certified organic and single-origin grades. Three-tier pricing structure across premium, standard, and economy levels differentiates by cocoa mass percentage and provenance documentation. Pricing pressure stems from West African supply disruptions and cocoa butter cost volatility. Mass-market milk chocolate buyers exhibit highest price sensitivity; dark chocolate subscribers in California and the Northeast corridor show lowest sensitivity.
Supply Chain Analysis
Côte d'Ivoire and Ghana anchor global cacao bean production, while Ecuador and Peru supply specialty-grade organic volumes. Cocoa butter, cocoa powder, and emulsifier inputs draw from West African and Southeast Asian processing hubs. Single-source vulnerability concentrates in Ivorian supply corridors exposed to political instability and climate disruption. Distribution runs through Pennsylvania and Illinois manufacturing clusters to national retail networks, with direct-to-consumer channels bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSMA compliance expertise scarcity constrains mid-size processor expansion, creating acquisition premiums for certified operators with foreign supplier verification infrastructure. The capability gap separates integrated multinationals from craft producers seeking retail placement.
For Market Incumbents: Compound channel control advantages by deepening convenience and drugstore network penetration while accelerating clean-label reformulation ahead of FDA added sugar disclosure mandates. Bean-to-bar entrants threaten premium positioning; defend through precision conching investments that replicate craft mouthfeel at industrial scale. Backward integration into Ecuadorian organic cooperatives secures supply allocation. For New Entrants and Emerging Players: Lead with transparency portals showing farmgate pricing and fermentation protocols to capture direct-to-consumer subscribers in Portland and Burlington craft clusters. Food service operators seeking portion-controlled formats with origin credentials represent underpenetrated white space. Subscription discovery mechanisms displace specialty retail intermediaries as the primary access point. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and input cost volatility favor scaled operators with dedicated FSMA infrastructure. Target acquisition archetype: regional craft processors with established organic certification and existing retail buyer relationships. The signal to watch is FDA guidance finalization on cacao origin labeling enforcement, which would accelerate compliance-driven M&A.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cacao Sourcing | Captures supply-constrained USDA organic premiums and secures allocation from Ecuadorian cooperatives. |
| Precision Conching Technology Deployment | Enables sub-20-micron particle distributions that compress craft mouthfeel advantages at industrial volume. |
| Direct-to-Consumer Channel Expansion | Bypasses distributor markups while transparency portals replace traditional shelf presence for discovery. |
| Clean-Label Reformulation Investment | Preempts FDA added sugar disclosure mandates and captures placement in health-forward retail banners. |
| Proposition 65 Compliance Certification | Creates testing moat for cadmium and lead screening that commands natural retail shelf space. |
Research Methodology
A spread of perspectives from bean-to-bar processors, food service procurement directors, specialty retail buyers, and FDA compliance consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through USDA organic certification databases, FDA import refusal data, and Nielsen retail audit information. Bottom-up volume modeling triangulated against top-down category spend analysis.
Segmentation dimensions modeled span product type, end user, packaging format, and distribution channel across the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift velocity. Cocoa butter price volatility indices and FSMA certification timeline trends informed scenario weighting.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement intensity or abrupt cocoa supply disruption would require recalibration. Forecasts reflect documented assumptions regarding consumer adoption of transparency portals and state sugar tax expansion patterns. Recalibration cycles align with material shifts in regulatory guidance finalization and West African supply corridor stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Infused Fruits Jellies Market
Confectionery
Low Calorie Sweets Market
Confectionery
North America Gummy Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Mooncake Market
Confectionery
South Korea Chocolate Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Europe Confectionery Market
Confectionery
Caramel Chocolate Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
India Chocolate Market
Confectionery
Italy Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Low-Fat Sweets Market