
 Cruciate Ligament Repair Procedures Market | 2026-2036
Cruciate Ligament Repair Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Cruciate Ligament Repair Procedures Market Analysis
The EU Medical Device Regulation (MDR) is pivoting procurement standards toward enhanced biocompatibility documentation and post-market surveillance across European orthopedic supply chains. Stryker leverages its integrated sports medicine portfolio to sustain hospital system contracts. Arthrex differentiates through specialized arthroscopic device development and surgeon training ecosystems. Zimmer Biomet anchors European distribution through CE-marked implant lines and established orthopedic surgeon relationships.
Cruciate ligament repair procedures encompass surgical interventions that reconstruct torn anterior or posterior cruciate ligaments using autograft, allograft, or synthetic materials to restore knee joint stability and function. These interventions typically employ arthroscopic visualization with tunnel drilling accuracy within 1-2 millimeters to ensure proper graft placement and mechanical loading. Implants represent the most mature revenue segment, while robotic-assisted surgery delivery modes capture the fastest procedural growth trajectory due to precision improvements. Hospitals retain the dominant end-user position, though sports medicine facilities are expanding capacity for outpatient ACL repairs.
FDA 510(k) pathways and EU MDR conformity assessments shape product entry timelines and clinical evidence requirements for cruciate ligament devices across North America and Europe. ISO 13485 quality management standards and ASTM F2077 biomechanical testing protocols govern graft tensile strength validation and implant fatigue resistance. Stakeholders must monitor reimbursement code revisions for outpatient robotic-assisted procedures and biologic graft add-on payments.
Market Dynamics
Robotic-assisted surgical platforms are compressing tunnel placement tolerances below one millimeter, forcing orthopedic device manufacturers to recalibrate their arthroscopic instrument portfolios around precision-integrated delivery systems rather than standalone implants.
Growth Catalysts
- Youth sports participation:High school and collegiate athletics programs across the United States are expanding roster sizes and competition schedules, generating sustained patient flow into sports medicine clinics for acute ACL ruptures.
- Biologic graft pathways:FDA 510(k) clearance frameworks for decellularized allograft materials are compressing premarket review timelines, accelerating commercialization of next-generation scaffold products.
- Outpatient migration:Ambulatory surgery centers in Texas, Florida, and California are building dedicated orthopedic suites, capturing procedure volume previously hospitalized.
Market Restraints
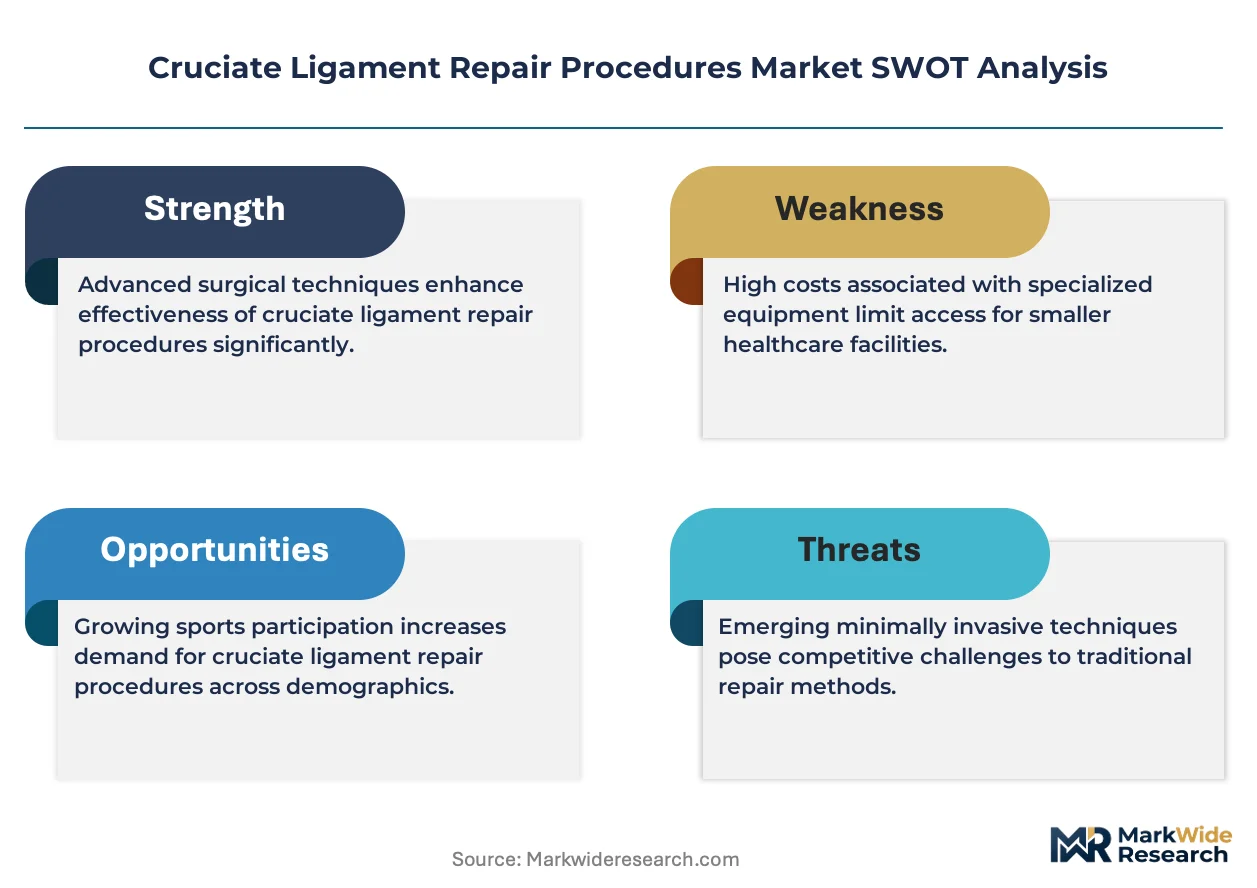
- Allograft supply concentration:Tissue bank networks in the southeastern United States control the majority of patellar tendon and Achilles allograft processing capacity, creating single-source vulnerability.
- Polymer degradation limits:Synthetic ligament materials face fatigue failure thresholds below ten-year survival benchmarks, restricting their application in younger patient cohorts.
- EU MDR documentation burdens:Enhanced biocompatibility testing requirements and post-market surveillance obligations are extending conformity assessment timelines for European market entry.
Strategic Opportunities
- India sports medicine infrastructure:Private hospital chains in Mumbai, Delhi, and Bangalore are investing in arthroscopy suites, creating first-mover positioning for procedure training and device supply.
- Hybrid biologic-synthetic grafts:Convergence of collagen scaffolds with braided polyethylene terephthalate cores offers mechanical strength plus biological integration.
- Remote rehabilitation integration:Digital physical therapy platforms are embedding sensor-based range-of-motion tracking into postoperative care protocols.
Industry Challenges
- Arthroscopic technician scarcity:Operating room staff with specialized training in fluid management systems and camera calibration are concentrated in major metropolitan medical centers.
- Legacy EHR interoperability:Robotic surgical platforms generate proprietary kinematic data formats that resist integration with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cruciate Ligament Repair Procedures Market |
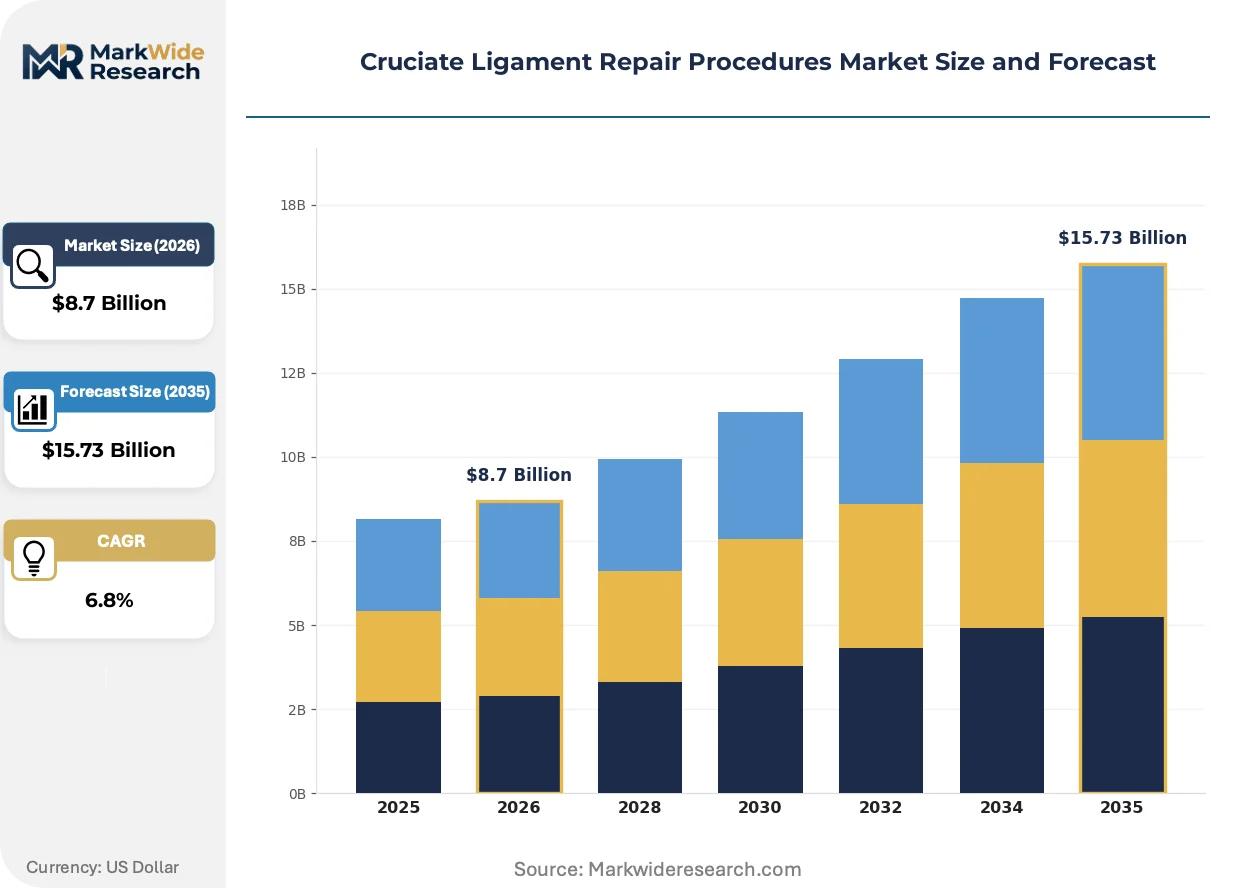
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
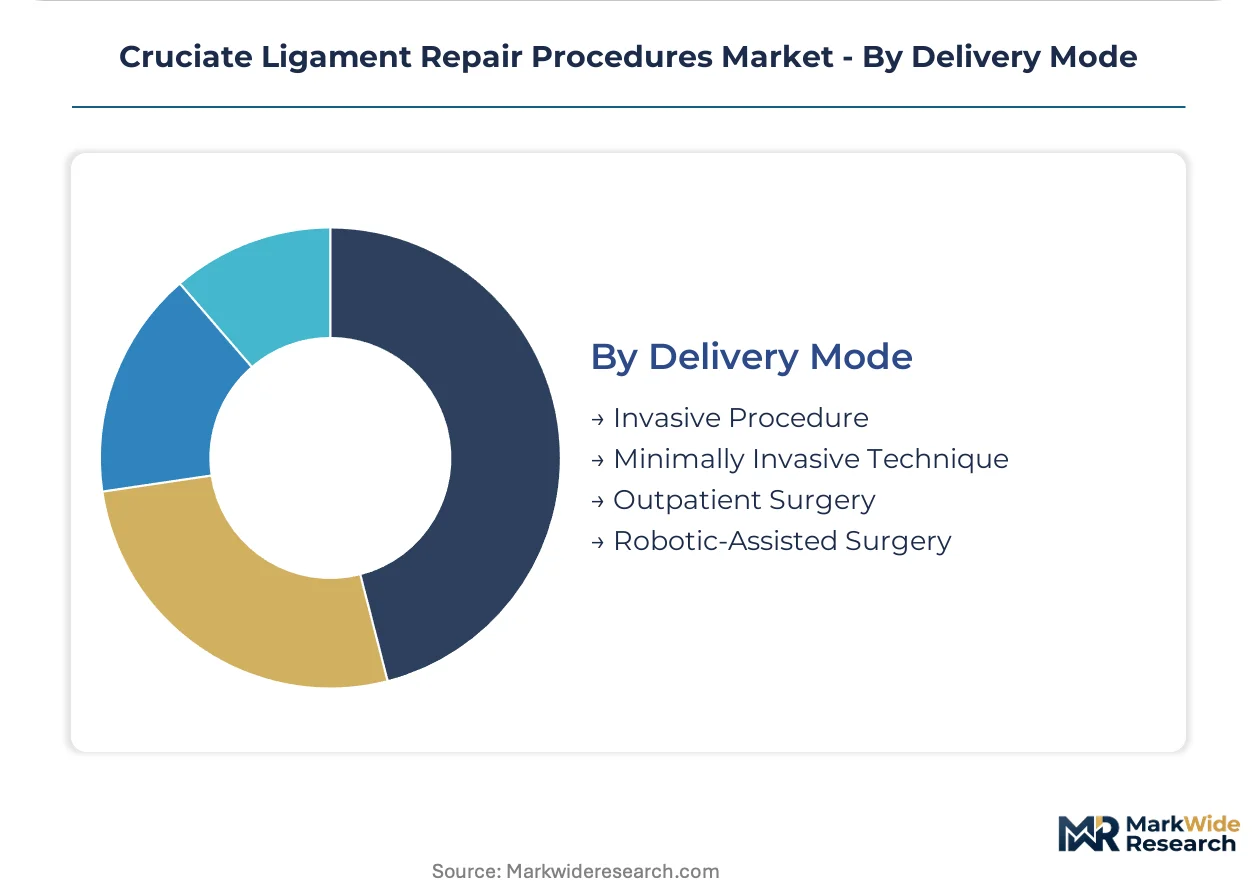
| Segmentation | Product Type: Arthroscopic Devices, Surgical Instruments, Implants, Grafts Application: ACL Repair, PCL Repair, Multi-Ligament Reconstruction, Meniscus Repair End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Sports Medicine Facilities Delivery Mode: Invasive Procedure, Minimally Invasive Technique, Outpatient Surgery, Robotic-Assisted Surgery |
| Companies Covered | Zimmer Biomet, Stryker, Smith+Nephew, Arthrex, CONMED Corporation, Johnson & Johnson (DePuy Synthes), B. Braun, Medtronic, Karl Storz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cruciate Ligament Repair Procedures Market Emerging Trajectories
Navigation-enabled drilling systems and patient-specific graft sizing algorithms are redistributing competitive advantage toward data-integrated surgical workflows rather than hardware-only vendors.
Patient-specific instrumentation derived from preoperative MRI segmentation is rewriting the standard of care for tunnel trajectory planning. Academic medical centers in Boston and Pittsburgh are adopting these 3D-printed guides at accelerating rates. The technology is compressing operative time and reducing revision rates, forcing instrument manufacturers to develop compatible drill guide portfolios.
EU MDR post-market clinical follow-up requirements are mandating ten-year implant surveillance registries for cruciate ligament devices. Manufacturers must now allocate resources to longitudinal data collection infrastructure. High-volume orthopedic hospitals in Germany and the Netherlands are responding by consolidating purchasing around suppliers with established traceability systems.
Self-referral patterns among Division I athletes are shortening the interval between injury and surgical consultation. Sports medicine clinics affiliated with university athletic departments in North Carolina and Michigan are capturing these patients directly, bypassing traditional primary care and emergency department channels. This behavioral shift is concentrating procedure volume in vertically integrated care networks.
Cruciate Ligament Repair Procedures Market Segmentation
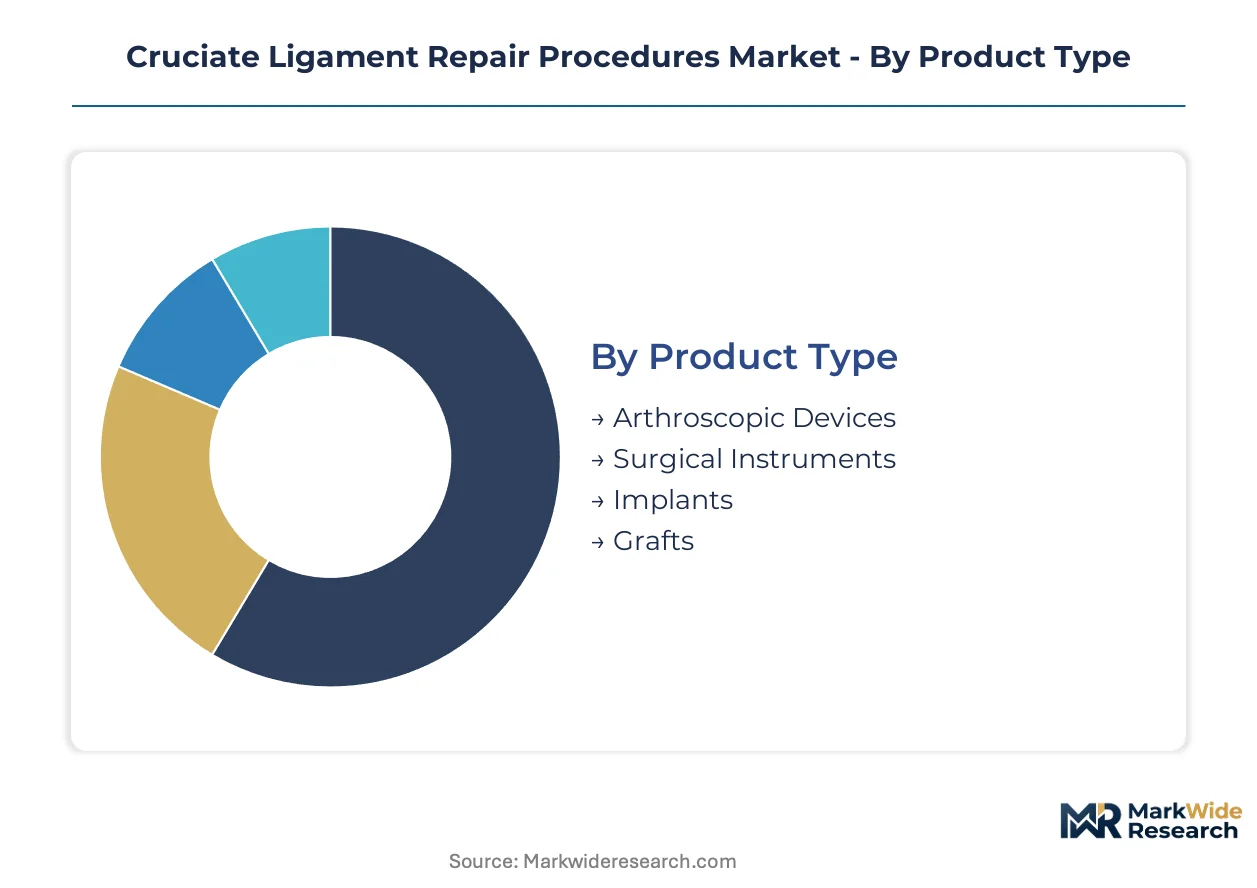
Segmentation in cruciate ligament repair procedures reveals how technological sophistication, care setting economics, and patient acuity reshape procurement priorities across the orthopedic supply chain. Understanding these divisions exposes where device manufacturers must align R&D investment with shifting clinical workflows and reimbursement incentives.
Product Type:
Technical specifications around visualization, fixation strength, and biocompatibility define competitive positioning across the hardware portfolio.
- Arthroscopic Devices:Camera systems and fluid management consoles deliver high-definition visualization through 2.7mm to 4.0mm portals. Demand concentrates in academic medical centers in Boston and Pittsburgh where complex multi-ligament cases require superior optical clarity. The shift toward 4K resolution and narrow-band imaging is forcing upgrade cycles at hospitals with aging 1080p fleets.
- Implants:Interference screws, suture anchors, and cortical fixation buttons manufactured from PEEK, titanium, or bioabsorbable polymers secure graft tunnel fixation. Sports medicine facilities in Texas and Florida are standardizing on titanium-alloy constructs for their fatigue resistance in high-activity patient cohorts. Bioabsorbable options face slower uptake due to inflammatory response concerns in published literature.
- Surgical Instruments:Drill guides, reamers, and tunnel dilators machined to sub-millimeter tolerances enable accurate graft placement. German orthopedic hospitals favor modular instrument sets compatible with multiple fixation philosophies.
- Grafts:Patellar tendon, hamstring, and quadriceps autografts plus processed allograft tissues provide biological scaffolds for ligament regeneration. Southeastern US tissue banks control the majority of allograft processing capacity.
Mature deployment sits with Implants. Newer deployment is concentrated in Arthroscopic Devices.
Application:
Procedure complexity and revision risk stratify instrumentation requirements and reimbursement tiers across the clinical spectrum.
- ACL Repair:Anterior cruciate ligament reconstruction represents the highest-volume indication, employing single-bundle or anatomic double-bundle techniques with autograft preference in patients under 25. Orthopedic clinics affiliated with NCAA Division I programs in North Carolina and Michigan capture these cases through direct athlete referral channels, bypassing traditional emergency department triage. Patient-specific instrumentation derived from MRI segmentation is compressing operative times and reducing tunnel malposition rates.
- Multi-Ligament Reconstruction:Combined ACL, PCL, and collateral ligament injuries demand extended operative time, specialized retractor systems, and staged rehabilitation protocols. Tertiary referral centers in Germany and the Netherlands maintain dedicated multi-ligament teams due to complexity concentration.
- PCL Repair:Posterior cruciate ligament injuries occur less frequently, often involving high-energy trauma mechanisms that require distinct tibial inlay or transtibial tunnel approaches.
- Meniscus Repair:Concomitant meniscal procedures accompany 60-80% of cruciate reconstructions, driving all-inside repair device utilization.
Volume leadership belongs to ACL Repair. Technical complexity is expanding fastest in Multi-Ligament Reconstruction.
End User:
Capital intensity and case mix economics determine which settings can absorb robotic platform investments versus traditional arthroscopy suites.
- Hospitals:Inpatient facilities retain complex revision cases, multi-ligament reconstructions, and polytrauma patients requiring overnight observation. German orthopedic hospitals are consolidating purchasing around suppliers with established EU MDR traceability systems to satisfy post-market surveillance mandates.
- Sports Medicine Facilities:Dedicated orthopedic ambulatory centers in Texas, Florida, and California are building procedure-specific suites to capture outpatient ACL volume. These settings prioritize rapid turnover and same-day discharge protocols.
- Orthopedic Clinics:Private practice groups leverage surgeon reputation and direct patient access to maintain case volume in competitive metropolitan markets.
- Rehabilitation Centers:Postoperative physical therapy providers are embedding digital range-of-motion tracking into recovery protocols, creating data integration demands with surgical EMR systems.
Case volume concentrates in Hospitals. Capacity expansion is accelerating most quickly in Sports Medicine Facilities.
Delivery Mode:
Precision requirements and reimbursement differentiation are redistributing competitive advantage toward integrated surgical workflows rather than hardware-only positioning.
- Robotic-Assisted Surgery:Navigation-enabled platforms compress tunnel placement tolerances below one millimeter through haptic feedback and real-time kinematic tracking. Academic medical centers in Pittsburgh and Boston are adopting these systems at accelerating rates, forcing instrument manufacturers to develop compatible drill guide portfolios. Proprietary data formats from robotic systems resist integration with legacy hospital information systems, creating interoperability friction.
- Minimally Invasive Technique:Standard arthroscopic approaches through 2-3 portals remain the workhorse method, with technique refinements in anatomic footprint restoration driving outcomes improvement.
- Outpatient Surgery:Ambulatory migration is capturing uncomplicated primary ACL cases previously hospitalized, supported by regional anesthesia protocols and enhanced recovery pathways.
- Invasive Procedure:Open reconstruction techniques persist in revision settings with severe tunnel osteolysis or hardware failure requiring extensile exposure.
Established practice centers on Minimally Invasive Technique. Technology investment is concentrating most heavily in Robotic-Assisted Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and Pittsburgh anchor the highest concentration of robotic-assisted cruciate ligament procedures, with academic medical centers in these metros driving adoption of navigation-enabled surgical platforms and patient-specific instrumentation derived from MRI segmentation protocols.
United States
NCAA Division I athletic programs in North Carolina and Michigan generate direct patient flow into university-affiliated sports medicine clinics, bypassing traditional emergency department triage. FDA 510(k) clearance pathways for decellularized allograft materials accelerate commercialization timelines for next-generation scaffold products. Ambulatory surgery centers in Texas and Florida are building dedicated orthopedic suites to capture outpatient ACL volume previously hospitalized.
Germany
Tertiary referral centers in Germany maintain dedicated multi-ligament reconstruction teams due to case complexity concentration across the country. EU MDR post-market clinical follow-up requirements mandate ten-year implant surveillance registries, forcing manufacturers to allocate resources to longitudinal data collection infrastructure. High-volume orthopedic hospitals in the Netherlands and Germany are consolidating purchasing around suppliers with established traceability systems.
India
Private hospital chains in Mumbai, Delhi, and Bangalore are investing in arthroscopy suites, creating first-mover positioning for procedure training and device supply expansion. The country's national pharmaceutical regulator oversees biologic graft material approvals through pathways that remain less burdensome than EU or US frameworks. Sports medicine infrastructure development concentrates in metropolitan corridors where rising middle-class participation in cricket and football drives injury volumes.
Japan
PMDA regulatory frameworks govern biologic graft approvals with emphasis on long-term safety documentation that extends premarket review timelines relative to FDA pathways. METI industrial policy supports domestic medical device manufacturing through targeted incentives for precision instrumentation. Academic medical centers in the Kanto region around Tokyo are adopting patient-specific instrumentation for tunnel trajectory planning at accelerating rates.
Australia
TGA oversight of orthopedic implants requires biomechanical testing validation against ISO 13485 quality management standards before market authorization. Sports medicine clinics in Sydney and Melbourne are embedding digital physical therapy platforms with sensor-based range-of-motion tracking into postoperative care protocols. Australian Rules Football and rugby participation rates sustain patient flow for acute cruciate ligament ruptures across the southeastern population corridor.
Cruciate Ligament Repair Procedures Market Vendor Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with integrated sports medicine portfolios. Three to five multinational device manufacturers control the majority of hospital system contracts through bundled instrument and implant offerings. Strategic archetypes include precision-integrated delivery system specialists, biologic graft material innovators, and robotic platform integrators. Dominant competitive moves encompass portfolio diversification around navigation-enabled workflows and backward integration into tissue processing capabilities.
Among US-based diversified orthopedic manufacturers, Stryker and Zimmer Biomet exemplify the integrated portfolio archetype, while Arthrex represents the specialized arthroscopic device and surgeon training ecosystem model. Stryker leverages its breadth to sustain hospital system contracts across multiple fixation philosophies. Zimmer Biomet anchors European distribution through CE-marked implant lines and established orthopedic surgeon relationships. Arthrex differentiates through concentrated investment in arthroscopic visualization technology and proprietary education infrastructure.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| Smith+Nephew |
| Arthrex |
| CONMED Corporation |
| Johnson & Johnson (DePuy Synthes) |
| B. Braun |
| Medtronic |
| Karl Storz |
| Others |
Supply Flow & Price Mechanics
EU MDR biocompatibility documentation mandates gate qualified supply access and premium-tier pricing for cruciate ligament devices, forcing manufacturers to absorb testing costs or forfeit high-margin European hospital contracts. Southeastern US tissue bank concentration around allograft processing creates asymmetric pricing power that propagates through implant supply tiers.
Pricing Analysis
Value-based pricing anchors on surgical throughput and revision-free outcomes, with robotic-assisted platforms commanding premium positioning against conventional arthroscopic suites. Three-tier pricing structure across premium navigation-enabled systems, standard minimally invasive instrument sets, and economy-grade fixation devices stratifies by certification grade and after-sales training bundling. Pricing pressure stems from ambulatory surgery center procurement consolidation in Texas and Florida demanding volume discounts. Sports medicine facilities exhibit highest price sensitivity due to capital constraint, while academic medical centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
India's phased domestic medical device manufacturing incentives under PLI scheme provisions are reshaping sourcing patterns for precision instrumentation. Geographic supply concentration clusters in Germany for arthroscopic visualization systems, the United States for biologic allograft tissues, and Japan for high-tolerance surgical instruments. Raw material dependencies center on medical-grade titanium alloys, PEEK polymers, and decellularized collagen matrices. Single-source vulnerability pervades southeastern US tissue bank networks controlling patellar tendon allograft processing. Distribution runs through orthopedic-focused GPOs and direct hospital system contracts with consolidated procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cruciate ligament repair market sits in a technology-transition phase, with robotic-assisted surgical platforms displacing legacy arthroscopic-only workflows across high-volume academic centers.
For Market Incumbents: Anchor hospital system loyalty through backward integration into tissue processing capabilities and exclusive robotic platform service agreements. Consolidate procurement relationships by bundling navigation-enabled drill guides with long-term implant supply contracts. Threat from specialized arthroscopic device developers with concentrated surgeon training ecosystems demands counterinvestment in proprietary education infrastructure. Priority lever rests on CE-marked portfolio breadth to satisfy EU MDR traceability mandates consolidating German and Dutch purchasing decisions. For New Entrants and Emerging Players: Private hospital chains in Mumbai, Delhi, and Bangalore represent the most penetrable buyer archetype, with arthroscopy suite buildouts outpacing established vendor relationships. Target first-mover positioning through procedure training partnerships and localized device supply agreements. White-space opportunity concentrates in hybrid biologic-synthetic graft development, where collagen scaffold and braided polyethylene convergence remains underdeveloped. Go-to-market angle should emphasize regulatory pathway efficiency relative to EU MDR timelines. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for decellularized allograft materials is the leading indicator that biologic graft innovators will command valuation premiums. Long-term viability favors precision-integrated delivery system specialists with data-integrated surgical workflows over hardware-only vendors. Acquisition target archetype encompasses robotic platform integrators with proprietary kinematic tracking and compatible instrument portfolios. Signal to watch: consolidation of multi-ligament reconstruction case volume in tertiary referral centers with dedicated surgical teams.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments govern European market entry timelines for cruciate ligament fixation devices. |
| Hospital System Partnership | Bundled instrument and implant offerings secure multi-year contracts with consolidated orthopedic procurement committees. |
| Software Companion Development | Digital physical therapy platforms with sensor-based range-of-motion tracking embed into postoperative care protocols. |
| Reimbursement Strategy | Outpatient robotic-assisted procedure code revisions determine ambulatory surgery center adoption economics. |
| Backward Integration | In-house tissue processing capabilities insulate against southeastern US allograft supply concentration risks. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries, complemented by interviews with orthopedic surgeons, sports medicine clinic administrators, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 audit records, and ASTM biomechanical testing protocols. Bottom-up procedure volume modeling and top-down market sizing triangulated across geographic clusters and product segments.
Cross-reference between historical implant utilization patterns and expert panel input on robotic adoption trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, application complexity, end-user setting economics, and delivery mode precision tier. CAGRs derived from procedure volume elasticity to sports participation demographics and capital equipment replacement cycles. Industry-specific inputs included NCAA athlete injury incidence tracking and ambulatory surgery center capacity buildout pipelines.
Revisions become necessary when FDA biologic graft pathway timelines shift, EU MDR post-market surveillance mandates intensify, or robotic platform interoperability standards crystallize. Forecasts reflect documented assumptions on reimbursement stability and tissue bank network consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Hallux Rigidus Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Septic Arthritis Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Kyphosis Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Spinal Stenosis Market