
 Orthopedic Repair Market | 2026-2036
Orthopedic Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Repair Market Analytics
Hospital purchasing of orthopedic repair systems is consolidating around integrated delivery networks and group purchasing organizations. Stryker leverages its broad implant portfolio to anchor multi-year supply contracts with major health systems. Zimmer Biomet competes through specialized robotics platforms that differentiate its knee and hip reconstruction offerings.
Orthopedic repair encompasses surgical interventions and implantable devices that restore musculoskeletal function through mechanical fixation, biological substitution, or regenerative stimulation; titanium alloy screws and plates achieve tensile strengths exceeding 900 MPa while porous-coated implants promote osseointegration within twelve weeks of implantation. Bone grafts and orthobiologics command premium positioning due to their role in accelerating fusion and reducing revision rates, while arthroscopy and soft tissue repair procedures expand fastest as outpatient migration shifts volumes toward ambulatory surgical centers. Minimally invasive techniques and biodegradable materials attract R&D investment because they align with payer pressure to reduce hospital stays and eliminate secondary removal surgeries.
FDA 510(k) clearances govern U.S. market access for implantable devices, while EMA MDR requirements enforce stricter clinical evidence standards across European member states and Japan's PMDA maintains distinct quality system regulations for foreign manufacturers. These frameworks elevate compliance costs but simultaneously protect incumbents with established regulatory infrastructure. Stakeholders must monitor how CMS procedural reimbursement adjustments and EU Green Deal material sourcing rules reshape manufacturing location decisions and supply chain economics.
Market Dynamics
Hospital procurement consolidation under value-based care frameworks is compressing supplier margins while favoring vendors with integrated implant-robotics-biologics portfolios capable of anchoring multi-year enterprise contracts.
Growth Catalysts
- Aging demographics in developed economies:Germany, Japan, and the United States exhibit expanding patient pools requiring joint replacement and spinal fusion procedures, driving implantable device volumes through Medicare and statutory health insurance reimbursement.
- FDA 510(k) clearance pathway:The streamlined premarket notification process accelerates biologics and implant commercialization, reducing time-to-revenue for manufacturers with predicate device strategies.
- Osseointegration surface engineering:Porous titanium coatings and hydroxyapatite treatments reduce fusion timelines from twenty-four weeks to twelve weeks, improving patient throughput and surgical economics for ambulatory surgical centers.
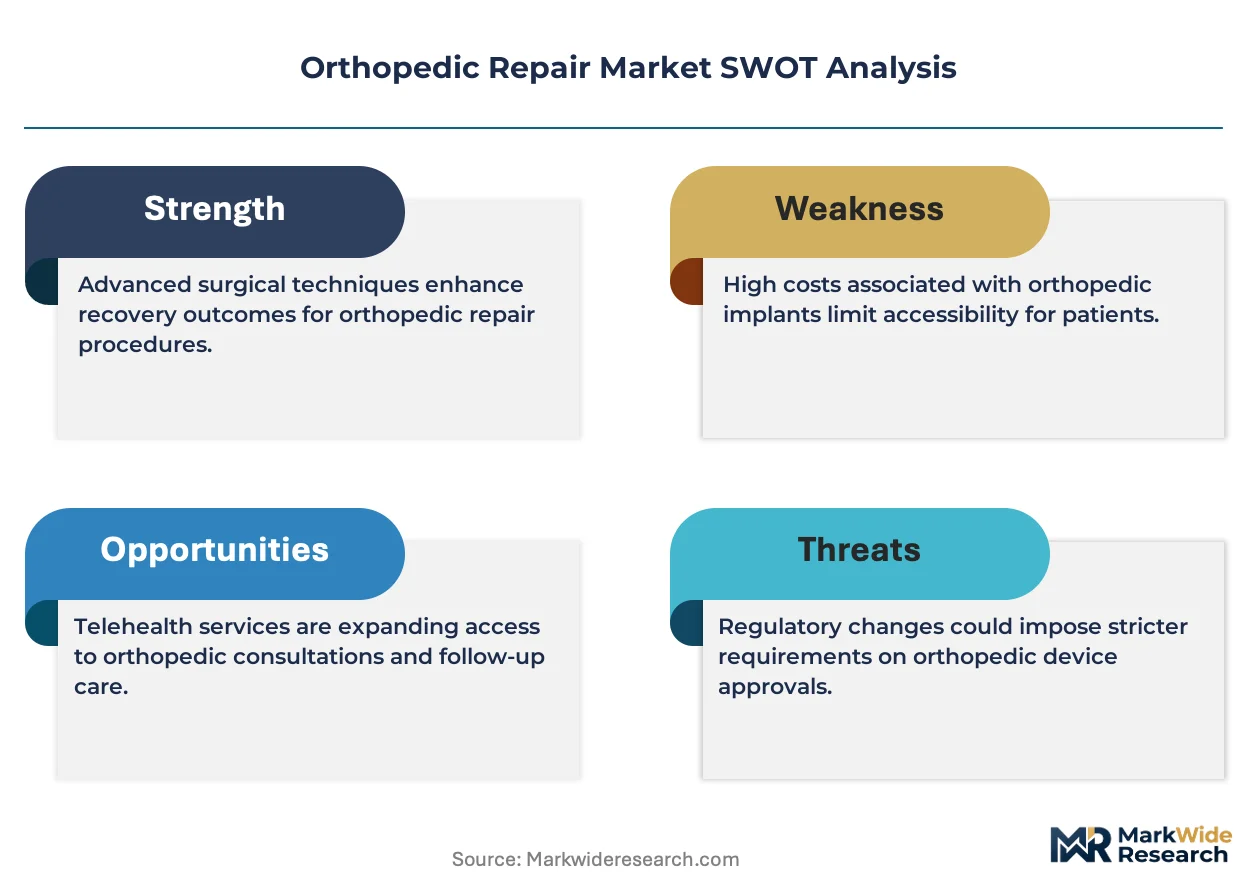
Market Restraints
- Titanium alloy input cost volatility:Aerospace and defense demand for Ti-6Al-4V creates periodic spot price spikes that compress orthopedic implant gross margins without corresponding reimbursement adjustments.
- EMA MDR clinical evidence requirements:Stricter post-market surveillance and clinical data mandates extend European market entry timelines and elevate compliance expenditures for foreign manufacturers lacking established notified body relationships.
- Biodegradable polymer performance limitations:Poly-L-lactic acid and polyglycolic acid constructs exhibit insufficient tensile strength for load-bearing applications, restricting their deployment to non-weight-bearing fixation and suture anchor applications.
Strategic Opportunities
- Outpatient migration to ambulatory surgical centers:CMS procedural reimbursement parity for select joint replacements in United States ASCs creates volume capture opportunities for implant vendors with compact, sterile-packaged instrument sets.
- EU Green Deal material sourcing rules:Carbon footprint disclosure requirements and circular economy mandates favor European manufacturers with localized titanium recycling and additive manufacturing capabilities.
- Digital surgical planning convergence:Preoperative CT-to-implant matching software combined with patient-specific instrumentation reduces operative time and revision risk, opening premium positioning for vendors with integrated data platforms.
Industry Challenges
- Orthopedic surgeon training bottlenecks:Robotics-assisted procedure credentialing requires specialized fellowship pathways and proctored case volumes, constraining adoption velocity for platform-dependent implant systems.
- Legacy ERP integration with hospital supply chain systems:Implant vendors must maintain EDI connectivity with disparate health system procurement platforms, elevating IT infrastructure costs and contract implementation timelines.
- Patent thickets around porous surface geometries:Extensive intellectual property holdings by incumbent manufacturers create licensing friction for entrants developing competitive osseointegration technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Repair Market |
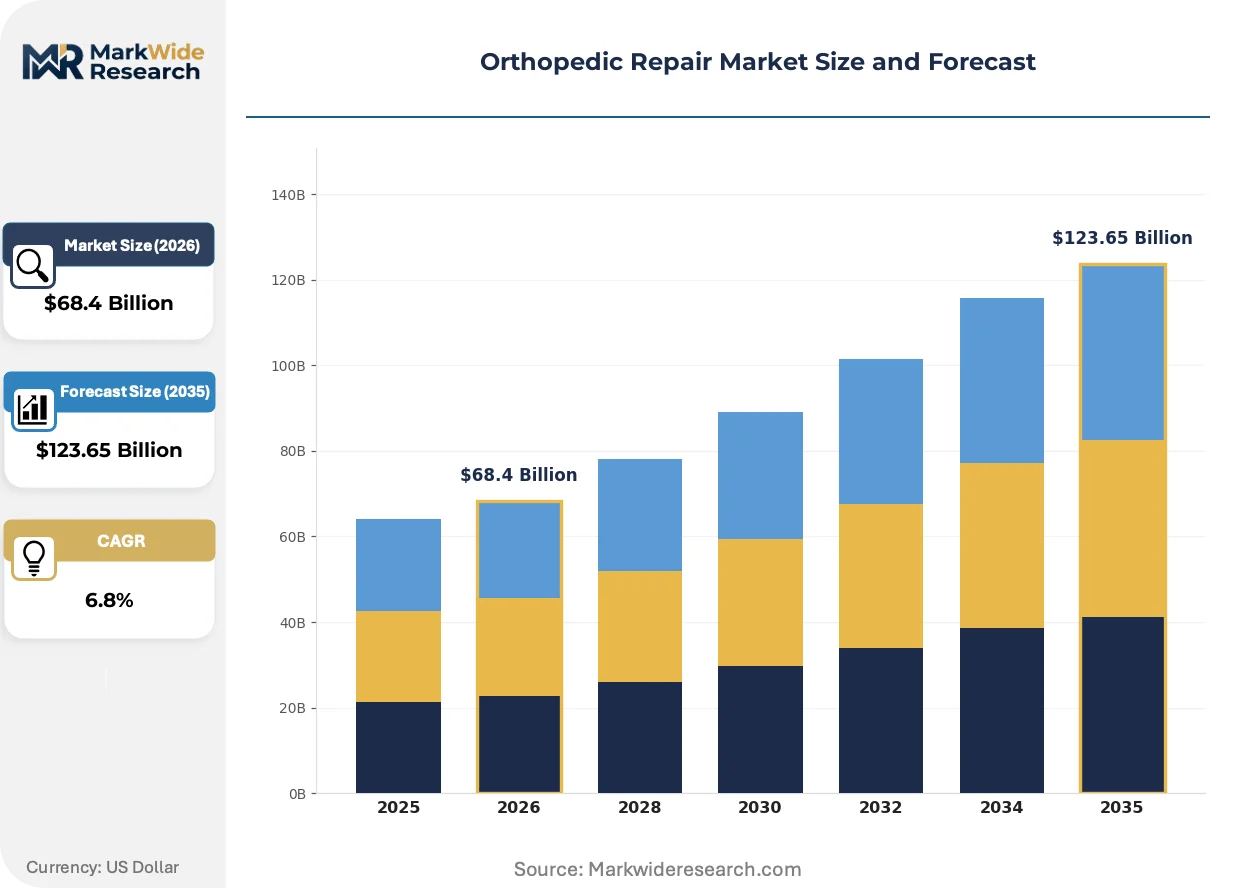
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Orthobiologics, Screws, Plates End User: Hospitals, Ambulatory Surgical Centers, Clinics, Rehabilitation Centers Procedure Type: Arthroscopy, Joint Replacement, Fracture Repair, Soft Tissue Repair Technology: Biodegradable Materials, 3D Printing, Minimally Invasive Techniques, Stem Cell Therapy |
| Companies Covered | Stryker, Zimmer Biomet, Johnson & Johnson MedTech, Smith & Nephew, Arthrex, DePuy Synthes, Medtronic, Globus Medical, Enovis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Repair Market Evolving Landscape
Digitalization of surgical workflows and materials science breakthroughs are compressing procedure times while expanding the treatable patient population through personalized implant geometries and bioresorbable fixation alternatives.
Additive manufacturing of patient-specific titanium implants is rewriting orthopedic supply chain economics. Large academic medical centers in the United States and Germany now commission custom acetabular cups and spinal cages with topology-optimized lattice structures. This capability eliminates sterile instrument tray sterilization costs and reduces operative inventory, compressing total procedure economics while enabling anatomical reconstructions previously excluded from standard implant sizing.
Japan's PMDA has tightened quality system regulations for foreign manufacturers, requiring on-site inspections and Japanese-language technical documentation that extend registration timelines. Domestic implant producers leverage this friction to defend market position against multinational entrants. European and North American vendors respond by establishing Tokyo-based regulatory affairs subsidiaries and contracting with local clinical research organizations to generate Japan-specific efficacy data.
Integrated delivery networks now unbundle implant procurement from instrumentation and biologics, creating separate contracting vehicles for each category. Major United States health systems negotiate implant prices through group purchasing organizations while sourcing robotics platforms through direct OEM relationships. This bifurcation pressures vendors with bundled pricing models and rewards those with modular, category-specific contract structures visible in California and Texas hospital network tenders.
Orthopedic Repair Market Segmentation
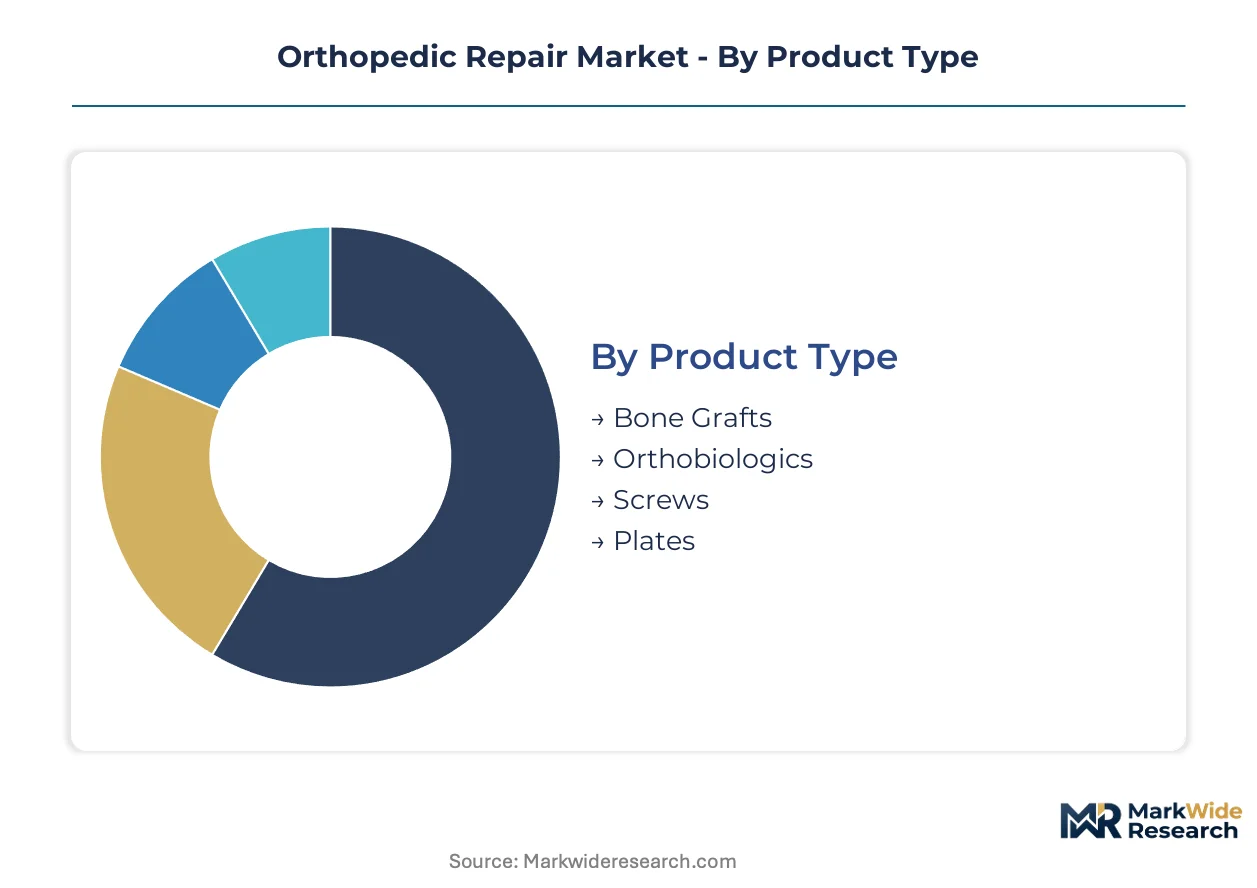
Orthopedic repair segmentation reveals divergent procurement patterns across clinical settings and technological maturity tiers. Product type and end-user categories capture the bulk of revenue concentration, while procedure type and technology dimensions expose where innovation investments are clustering.
Product Type:
Purchasing volume splits between commodity fixation hardware and premium biological substitutes, with procurement committees weighing reimbursement rates against clinical outcomes.
- Bone Grafts:Autograft and allograft matrices command premium positioning in spinal fusion and trauma applications. United States hospital systems concentrate demand through group purchasing organizations that negotiate volume-based contracts with synthetic and demineralized bone matrix suppliers.
- Orthobiologics:Platelet-rich plasma, bone morphogenetic proteins, and mesenchymal stem cell concentrates accelerate osseointegration timelines. Germany's statutory health insurance framework reimburses select biologics at differentiated rates, concentrating adoption in academic medical centers with established regenerative medicine protocols.
- Screws:Titanium alloy and stainless steel cortical and cancellous fixation devices anchor fracture repair economics.
- Plates:Reconstruction and compression plates span anatomical applications from mandibular to pelvic fixation.
Screws lead volumes today; orthobiologics is gaining share fastest.
End User:
Site-of-care migration is fragmenting purchasing authority across integrated delivery networks and independent ambulatory operators.
- Hospitals:Inpatient joint replacement and complex trauma procedures sustain implant volumes through Medicare reimbursement. Major United States health systems consolidate procurement under value-based care contracts that bundle device costs with episode payments.
- Ambulatory Surgical Centers:CMS procedural reimbursement parity for select knee and hip replacements in United States ASCs is capturing outpatient volumes. Compact sterile-packaged instrument sets from vendors with modular contract structures win tenders in California and Texas network expansions.
- Clinics:Orthopedic and sports medicine practices perform minor fracture repairs and soft tissue injections.
- Rehabilitation Centers:Post-operative recovery facilities drive demand for external fixation and bracing accessories.
Hospitals dominate revenue today; ambulatory surgical centers are expanding most quickly.
Procedure Type:
Reimbursement intensity and technical complexity create distinct equipment and consumable requirements across surgical categories.
- Joint Replacement:Total knee and hip arthroplasty procedures consume the highest implant value per case. Japan's aging demographic concentrates demand for revision surgeries, where porous-coated titanium stems and ceramic bearings command premium positioning.
- Arthroscopy:Knee and shoulder minimally invasive procedures are migrating fastest to outpatient settings. Ambulatory surgical centers in Germany favor disposable shaver blades and radiofrequency wands that eliminate reprocessing costs.
- Fracture Repair:Trauma fixation with plates, screws, and intramedullary nails sustains emergency department volumes.
- Soft Tissue Repair:Rotator cuff and ACL reconstruction with suture anchors and interference screws expands in sports medicine.
Joint replacement captures the steepest revenue per procedure; arthroscopy shows the strongest volume trajectory.
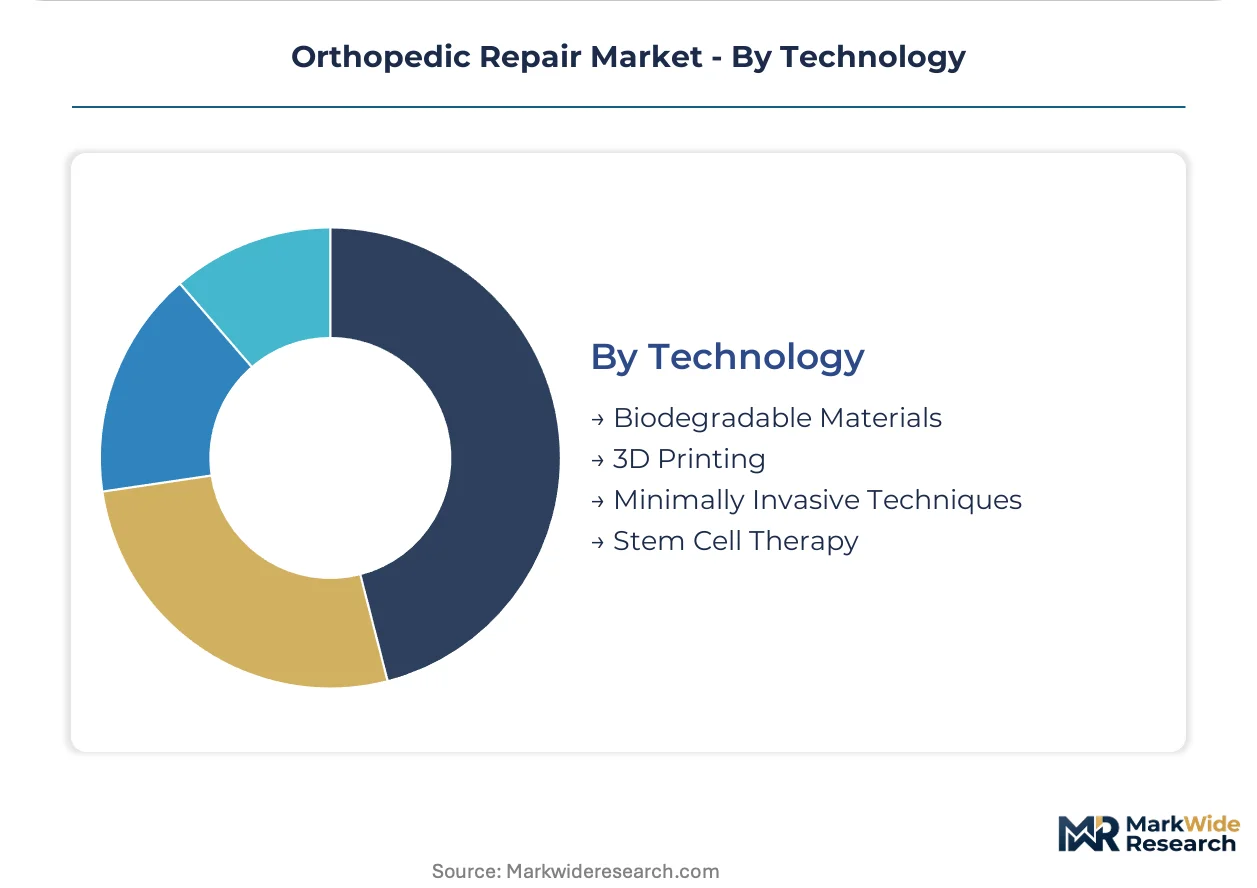
Technology:
R&D allocation clusters around materials science breakthroughs and digital surgical integration, with regulatory pathways determining commercialization velocity.
- Minimally Invasive Techniques:Percutaneous fixation and muscle-sparing approaches reduce hospital stays and accelerate ambulatory migration. FDA 510(k) clearances for navigated drilling systems and expandable implants are shortening United States time-to-market for vendors with predicate device strategies.
- 3D Printing:Patient-specific titanium implants with topology-optimized lattice structures are rewriting supply chain economics. Large academic medical centers in Germany now commission custom spinal cages that eliminate sterile tray sterilization costs.
- Biodegradable Materials:Poly-L-lactic acid and polyglycolic acid constructs target non-weight-bearing fixation.
- Stem Cell Therapy:Autologous and allogeneic cellular products face evolving EMA MDR clinical evidence requirements.
Minimally invasive techniques anchor current adoption; 3D printing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance framework reimburses orthobiologics at differentiated rates, while Japan's aging demographic concentrates demand for revision joint surgeries with premium implant specifications.
United States
Medicare reimbursement sustains inpatient joint replacement volumes through bundled payment models. FDA 510(k) clearances accelerate commercialization timelines for predicate device strategies. Major health systems in California and Texas consolidate procurement under value-based care contracts that anchor multi-year supply agreements.
Germany
Statutory health insurance reimbursement differentiates orthobiologic rates, concentrating adoption in academic medical centers with regenerative medicine protocols. EMA MDR requirements enforce stricter clinical evidence standards than predecessor directives. Large university hospitals in Berlin and Munich commission custom 3D-printed spinal cages with topology-optimized lattice structures.
Japan
Aging demographics drive revision joint replacement volumes where porous-coated titanium stems command premium positioning. PMDA quality system regulations require on-site inspections and Japanese-language technical documentation that extend registration timelines. Domestic producers in Tokyo and Osaka leverage regulatory friction to defend market position against multinational entrants.
United Kingdom
NHS procurement frameworks emphasize episode cost reduction through outpatient migration and ambulatory surgical center expansion. MHRA post-Brexit regulatory alignment with EMA MDR maintains clinical evidence requirements for market access. Orthopedic networks in Greater London and the Midlands pilot patient-specific instrumentation combined with preoperative CT-to-implant matching software.
China
Expanding middle-class demand and government healthcare infrastructure investment drive joint replacement volume growth. NMPA medical device registration requirements enforce quality system audits for foreign manufacturers. Domestic implant producers in Beijing and Shanghai capture share through localized manufacturing and hospital procurement relationships.
Orthopedic Repair Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across implant, robotics, and biologics categories. The market structure tilts toward consolidation where integrated portfolios anchor enterprise contracts, yet mid-tier specialists retain share through procedure-specific differentiation. Three archetypes dominate: full-spectrum implant-robotics-biologics integrators, robotics-platform specialists, and orthobiologic pure-plays. Competitive moves concentrate on M&A for technology tuck-ins and strategic partnerships for ASC distribution access.
Within the full-spectrum integrator tier, Stryker and Zimmer Biomet occupy positions defined by portfolio breadth and robotics anchoring. Stryker exemplifies the diversified conglomerate archetype with multi-year supply contract leverage across major United States health systems. Zimmer Biomet represents the robotics-platform specialist model, differentiating through knee and hip reconstruction offerings. Johnson & Johnson MedTech sits within the same tier as a diversified healthcare conglomerate with orthopedic repair exposure.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson MedTech |
| Smith & Nephew |
| Arthrex |
| DePuy Synthes |
| Medtronic |
| Globus Medical |
| Enovis |
| Others |
Value Network & Pricing Analysis
Ti-6Al-4V titanium alloy spot price volatility cascades through orthopedic implant manufacturing, compressing gross margins for vendors locked into multi-year hospital contracts while rewarding producers with backward integration into aerospace-grade scrap recycling and additive manufacturing feedstock operations.
Pricing Analysis
Capacity additions in China's titanium sponge production are reshaping price floors for raw material inputs, yet FDA 510(k) clearance costs and EMA MDR clinical evidence requirements sustain premium tiers for predicate-device vendors. Three-tier pricing structure across premium, standard, and economy levels separates robotic-integrated implant systems from conventional instrumentation and commodity fixation hardware. Cost compression in standard-tier plates and screws is intensifying because group purchasing organizations consolidate hospital procurement volumes. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers with bundled payment contracts show lowest sensitivity to per-unit implant costs.
Supply Chain Analysis
Instrument tray refurbishment and implant remanufacturing flows are emerging as cost-recovery channels for hospitals managing sterilization economics. Supply concentration rests on China for titanium sponge, the United States for precision forging, and Germany for additive manufacturing equipment. Raw material dependencies center on aerospace-grade titanium alloy, surgical-grade cobalt-chrome, and hydroxyapatite coatings. Single-source vulnerability around electron beam melting machines constrains patient-specific implant scaling. Distribution runs through group purchasing organization contracts for hospital systems and direct vendor relationships for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic repair has transitioned into a late-cycle quality market where revision joint replacement volumes and premium porous-coated implant specifications now outpace primary procedure growth as the demand anchor.
For Market Incumbents: Acquire ASC-focused instrument set portfolios to anchor outpatient migration capture. Consolidate sterile packaging and compact tray designs through tuck-in acquisitions of specialized logistics providers. Robotics-assisted platform dependency threatens vendors lacking fellowship-trained surgeon networks; defend through proctored credentialing program expansion and academic medical center robotics fellowship sponsorships. For New Entrants and Emerging Players: Direct-to-ASC distribution partnerships bypass GPO contract lock-in for established vendors. White-space targets include patient-specific 3D-printed spinal cages for German university hospitals and bioresorbable interference screws for sports medicine clinics. The most penetrable segment is independent ambulatory surgical centers in Texas and California seeking modular contract structures separate from robotics platform bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with orthobiologic pure-plays possessing EMA MDR clinical data packages and Japan PMDA quality system certifications. Long-term viability hinges on regulatory moat depth rather than manufacturing scale alone. Target acquisition archetype: mid-cap specialists with predicate-device 510(k) clearances and established notified body relationships in Europe. Signal to watch: CMS procedural reimbursement expansion for shoulder and ankle replacements in ASC settings.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Platform Integration | Stryker and Zimmer Biomet anchor hospital contracts through Mako and ROSA system bundling with knee implant volumes. |
| Patient-Specific Instrumentation | Preoperative CT-to-implant matching software reduces operative time and revision risk for academic medical centers. |
| Biologics Regulatory Pathway | FDA 510(k) clearances for bone morphogenetic proteins accelerate commercialization timelines versus PMA requirements. |
| Ambulatory Surgical Center Partnership | Compact sterile-packaged instrument sets win California and Texas network tenders seeking modular contract structures. |
| Additive Manufacturing Scale-Up | Topology-optimized titanium lattice implants eliminate tray sterilization costs for German university hospital commissions. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down implant shipment tracking forms the analytical core of this study. Primary interviews with orthopedic surgeons, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EMA MDR submission records, and hospital procurement tender documents. Triangulation across clinician utilization patterns and manufacturer revenue disclosures ensures segmentation accuracy.
Historical trendline analysis of joint replacement procedure volumes, implant average selling prices, and regulatory approval timelines established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user site of care, procedure category, and technology maturity tier. CAGRs derive from procedure volume forecasts weighted by reimbursement intensity and implant value per case, with robotics adoption curves and biologics penetration rates as orthopedic-specific forecast inputs.
Titanium alloy commodity price spikes, EMA MDR clinical evidence requirement extensions, and CMS procedural reimbursement category revisions are the dominant revision risks to forecast assumptions. Practitioners should monitor aerospace defense demand shifts, notified body capacity constraints, and ASC payment parity expansion for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Orthopedics Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Tendon Repair Market
Orthopedics
Podiatry Services Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Rickets Market