
 Osteoarthritis Treatment Market | 2026-2036
Osteoarthritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Osteoarthritis Treatment Market Outlook
The EU Green Deal is rebalancing pharmaceutical manufacturing priorities toward sustainable active-ingredient synthesis and reduced solvent waste in European production facilities. Pfizer Inc. leverages its global manufacturing scale to secure corticosteroid supply chains across multiple continents. Sanofi anchors its osteoarthritis portfolio through sustained R&D investment in biologic pain modulators. Novartis AG differentiates via specialized ophthalmic-to-orthopedic technology transfer capabilities in hyaluronic acid formulation science.
Osteoarthritis treatment encompasses pharmacological and non-pharmacological interventions targeting cartilage degradation, synovial inflammation, and joint-space narrowing, with hyaluronic acid injections requiring molecular weights between 500 and 6,000 kDa to achieve viscoelastic properties matching native synovial fluid. The primary commercial purpose is to delay arthroplasty and preserve mobility in aging populations. NSAIDs occupy the largest revenue pool due to decades of generic penetration and physician familiarity, though disease-modifying osteoarthritis drugs represent the fastest-expanding category as regulatory pathways mature for structure-modifying claims. Injectable delivery modes sustain premium pricing relative to oral formulations, particularly in hospital and clinic settings where administration can be supervised.
The FDA maintains stringent efficacy thresholds for symptomatic slow-acting drugs in osteoarthritis, while the EMA's Committee for Medicinal Products for Human Use demands radiographic joint-space narrowing data for disease-modification labeling. Health Canada and the PMDA in Japan enforce bioequivalence standards for generic NSAIDs that limit rapid commoditization of established molecules. Stakeholders must monitor how evolving payer evidence requirements for patient-reported outcome measures reshape formulary positioning across Medicare, national health services, and private insurance networks.
Market Dynamics
Hospital systems are consolidating ambulatory joint-care programs around supervised injection protocols, compressing the traditional specialist-referral pathway and concentrating volume in integrated delivery networks that can credential advanced practice providers for intra-articular procedures.
Growth Catalysts
- Medicare reimbursement expansion:The Centers for Medicare & Medicaid Services maintains favorable outpatient payment rates for viscosupplementation administered in hospital outpatient departments, sustaining procedural volume.
- EMA accelerated assessment pathways:The Committee for Medicinal Products for Human Use has streamlined review timelines for disease-modifying osteoarthritis drugs demonstrating structure-modifying effects on radiographic joint-space narrowing.
- Hyaluronic acid molecular engineering:Advances in fermentation-based production of ultra-high molecular weight polymers above 6,000 kDa are extending intra-articular residence time and reducing injection frequency.
Market Restraints
- Rooster comb raw material concentration:Over 70% of pharmaceutical-grade hyaluronic acid derives from avian tissue processing facilities concentrated in China and France, exposing supply chains to avian influenza quarantine protocols.
- FDA efficacy threshold rigidity:The Division of Anesthesiology, Critical Care, and Addiction Products maintains stringent symptomatic benefit requirements that have blocked multiple symptomatic slow-acting drug candidates from reaching the US market.
- Generic NSAID commoditization:Bioequivalence standards enforced by Health Canada and the PMDA have enabled rapid substitution of oral diclofenac and naproxen formulations, eroding branded pricing power.
Strategic Opportunities
- Japan's super-aged demographic:The Ministry of Health, Labour and Welfare has expanded reimbursement for hyaluronic acid sequences to three injections per knee per year, creating volume expansion in the world's oldest population.
- Combination biologic-corticosteroid formulations:Convergence of sustained-release depot technology with anti-nerve growth factor antibodies offers the prospect of single-injection multi-month efficacy.
- Direct-to-employer contracting:Self-insured Fortune 500 employers are negotiating carve-out arrangements for orthopedic episodes, bypassing traditional payer formularies for high-cost injectables.
Industry Challenges
- Patient-reported outcome standardization:The Western Ontario and McMaster Universities Osteoarthritis Index and Knee Injury and Osteoarthritis Outcome Score require harmonization for cross-trial comparability, complicating health technology assessment submissions to NICE and ICER.
- Cold-chain distribution complexity:Biologic pain modulators requiring 2-8°C storage throughout the last-mile to ambulatory surgery centers demand capital investment in validated thermal packaging and real-time temperature monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteoarthritis Treatment Market |
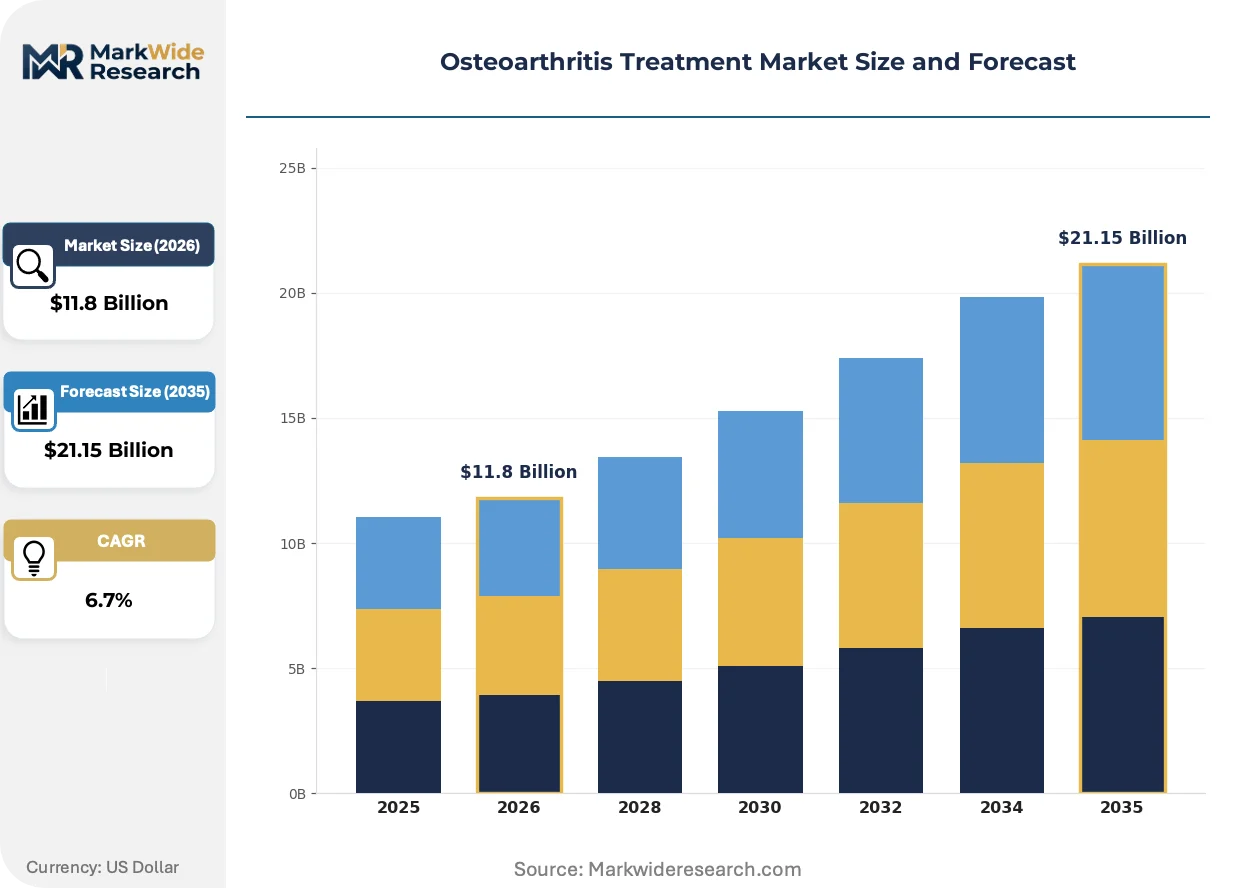
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Corticosteroids, Hyaluronic Acid Injections, Disease-Modifying Osteoarthritis Drugs Delivery Mode: Oral, Injectable, Topical, Transdermal End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Stage of Disease: Mild, Moderate, Severe, Advanced |
| Companies Covered | Pfizer Inc., Sanofi, Novartis AG, Bayer AG, Zimmer Biomet, GlaxoSmithKline, AbbVie Inc., Eli Lilly and Company, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteoarthritis Treatment Market Strategic Shifts
Injectable delivery platforms are absorbing the majority of R&D investment as developers pursue extended-duration formulations that reduce the total cost of care while preserving mobility in aging cohorts.
Cross-linked hyaluronic acid hydrogels with tunable degradation profiles are absorbing physician preference in academic medical centers. Orthopedic surgeons at major US teaching hospitals have shifted toward single-injection formulations despite higher per-procedure cost. The technology is absorbing volume from three-injection sequences by reducing clinic scheduling burden and patient copay accumulation.
The EU Green Deal's pharmaceutical sustainability framework is forcing reformulation of active-ingredient synthesis routes. European manufacturing facilities must demonstrate 30% solvent waste reduction by 2030 to maintain operating licenses. German and Swiss production sites are retrofitting continuous-flow reactors to replace batch processing for corticosteroid intermediates.
Self-referral patterns among Medicare Advantage enrollees are fragmenting traditional gatekeeper relationships. Patients in Florida and Arizona retirement corridors increasingly access direct-access physical therapy and injection clinics without primary care authorization. This bypass phenomenon concentrates in markets with high Medicare Advantage penetration and weak specialist network controls.
Osteoarthritis Treatment Market Segmentation
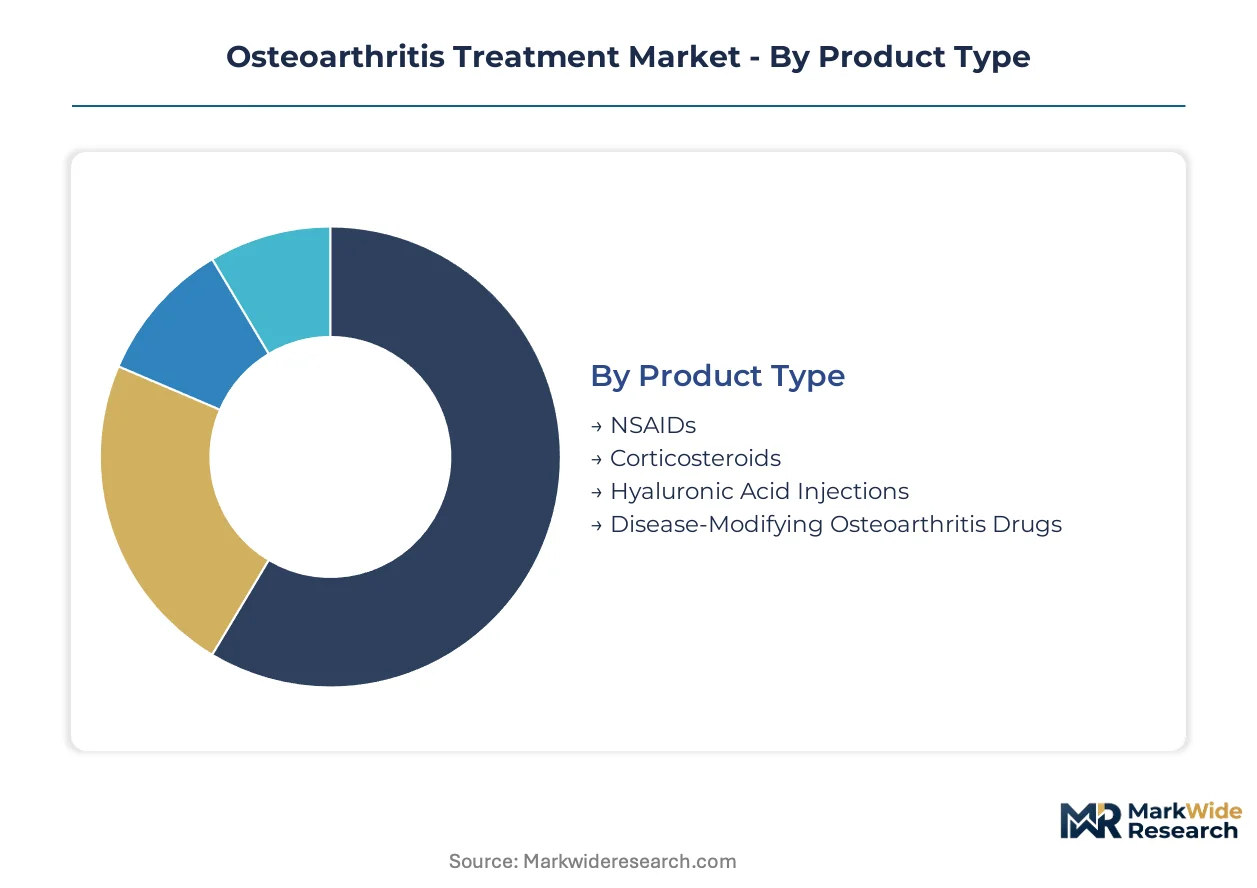
Segmentation in osteoarthritis treatment reveals divergent margin structures across pharmacological categories. Injectable modalities command premium pricing against oral generics, while disease-stage stratification determines reimbursement intensity and procedural intervention thresholds.
Product Type:
Volume concentration sits with oral NSAIDs, yet margin capture favors injectable and biologic categories where formulation complexity erects competitive barriers.
- NSAIDs:Oral diclofenac and naproxen formulations dominate prescription volume through decades of physician familiarity and favorable tiering on Medicare Part D formularies. Demand concentrates in retail pharmacy channels where generic substitution protocols have compressed branded pricing power to single-digit percentage points above commodity cost.
- Hyaluronic Acid Injections:Intra-articular viscosupplementation requires molecular weights between 500 and 6,000 kDa to achieve viscoelastic properties matching native synovial fluid. Medicare reimbursement for hospital outpatient viscosupplementation in the United States sustains procedural volume despite mixed clinical evidence in systematic reviews.
- Corticosteroids:Triamcinolone and methylprednisolone depot formulations provide rapid anti-inflammatory relief through intra-articular or periarticular delivery.
- Disease-Modifying Osteoarthritis Drugs:Structure-modifying candidates targeting cartilage degradation pathways remain in late-stage development pipelines.
Today's leader: NSAIDs. Tomorrow's challenger: Disease-Modifying Osteoarthritis Drugs.
Delivery Mode:
Route of administration determines site-of-care economics and patient compliance profiles across the treatment continuum.
- Injectable:Intra-articular delivery sustains premium pricing through 40-60% gross margins on hyaluronic acid and corticosteroid formulations. Hospital outpatient departments in the United States capture favorable Medicare reimbursement differentials versus physician office settings.
- Oral:Tablets and capsules account for the majority of prescription volume through retail pharmacy distribution. Bioequivalence standards enforced by Health Canada and the PMDA in Japan enable rapid generic substitution.
- Topical:Diclofenac gels and patches target localized joint pain with reduced systemic exposure. Demand concentrates in Germany and the United Kingdom where national formularies restrict oral NSAID duration.
- Transdermal:Fentanyl and buprenorphine patches address severe pain in advanced disease stages where oral bioavailability is compromised.
Injectable modalities anchor current revenue. Oral formulations face steepest price erosion.
End User:
Care setting fragmentation is accelerating as Medicare Advantage plans and self-insured employers experiment with direct-to-patient models.
- Hospitals:Integrated delivery networks credential advanced practice providers for supervised injection protocols, compressing traditional specialist-referral pathways. Ambulatory surgery centers in Florida and Arizona retirement corridors capture Medicare Advantage volume through direct-access contracts.
- Clinics:Rheumatology and orthopedic group practices concentrate hyaluronic acid injection volume where in-house dispensing privileges apply.
- Home Care:Oral NSAID and topical analgesic administration shifts to patient-managed settings with telehealth monitoring.
- Rehabilitation Centers:Physical therapy co-location with injection services creates bundled episode opportunities for orthopedic episodes.
Hospital systems defend procedural margin. Clinics gain share through convenience positioning.
Stage of Disease:
Disease severity stratification determines intervention intensity and surgical candidacy thresholds.
- Mild:Exercise therapy and oral NSAIDs constitute first-line management with lowest per-patient cost. Patient-reported outcome measures including the Western Ontario and McMaster Universities Osteoarthritis Index guide treatment escalation decisions.
- Moderate:Hyaluronic acid sequences and intra-articular corticosteroids bridge toward surgical intervention. Japan's Ministry of Health, Labour and Welfare expanded reimbursement to three injections per knee annually.
- Severe:Biologic pain modulators and sustained-release formulations target patients with radiographic joint-space narrowing who have exhausted conventional pharmacotherapy.
- Advanced:Total joint arthroplasty becomes cost-effective when quality-adjusted life year thresholds are met.
Moderate-stage therapies generate current procedure volume. Severe-stage biologics represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern osteoarthritis treatment industry traces its commercial origins to post-war pharmaceutical development in the United States, where intra-articular corticosteroid formulations first achieved regulatory clearance and established the procedural foundation for supervised joint-care delivery.
United States
Medicare Advantage penetration in Florida and Arizona retirement corridors drives direct-access clinic volume outside traditional referral networks. The FDA's Division of Anesthesiology, Critical Care, and Addiction Products maintains stringent efficacy thresholds for symptomatic slow-acting drug candidates. Hospital outpatient departments in Texas and California capture favorable reimbursement differentials for viscosupplementation procedures.
Japan
The world's oldest population sustains procedural demand for hyaluronic acid sequences expanded to three injections per knee annually. The PMDA enforces bioequivalence standards for generic NSAIDs that limit rapid commoditization of established molecules. Manufacturing clusters in the Kansai region concentrate fermentation-based production of ultra-high molecular weight polymers.
Germany
National formulary restrictions on oral NSAID duration redirect demand toward topical diclofenac gels and patches. The EU Green Deal mandates 30% solvent waste reduction by 2030 for pharmaceutical manufacturing facilities. Production sites in Baden-Württemberg are retrofitting continuous-flow reactors to replace batch processing for corticosteroid intermediates.
China
Over 70% of pharmaceutical-grade hyaluronic acid derives from avian tissue processing facilities concentrated in coastal provinces. The NMPA regulates molecular weight specifications for intra-articular formulations between 500 and 6,000 kDa. Supply chains face exposure to avian influenza quarantine protocols affecting rooster comb raw material concentration.
Switzerland
Specialized ophthalmic-to-orthopedic technology transfer capabilities anchor hyaluronic acid formulation science development. Swissmedic oversees specialized manufacturing licenses for extended-duration injectable platforms. Basel-area research clusters concentrate biologic pain modulator pipeline activity targeting nerve growth factor pathways.
Osteoarthritis Treatment Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and molecular engineering sophistication. The market structure consolidates around three archetypes: global pharmaceutical conglomerates with diversified pain portfolios, specialized orthopedic device manufacturers with injection platform expertise, and mid-scale biotech developers targeting disease-modification claims. Dominant competitive moves include strategic partnerships for cold-chain distribution infrastructure and technology licensing for sustained-release depot formulations.
Within the global pharmaceutical tier, Pfizer Inc. and Sanofi exemplify scale-driven supply chain anchoring across multiple continents, while Novartis AG occupies a position bridging specialized formulation science with cross-therapeutic technology transfer. These three entities represent the concentration of manufacturing scale and R&D investment shaping competitive dynamics in injectable and biologic categories.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Novartis AG |
| Bayer AG |
| Zimmer Biomet |
| GlaxoSmithKline |
| AbbVie Inc. |
| Eli Lilly and Company |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
Medicare reimbursement compression for outpatient viscosupplementation procedures in the United States is forcing manufacturers to absorb cost increases from fermentation-based hyaluronic acid production while maintaining hospital procurement relationships. This demand-side pressure concentrates margin defense in molecular engineering capabilities that extend injection intervals and reduce per-patient lifetime costs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates single-injection cross-linked hydrogels from multi-sequence formulations and commodity corticosteroid depots. Price differentiation rests on molecular weight certification and residence time duration, with academic medical centers showing lowest sensitivity and retail pharmacy channels facing steepest cost compression from generic NSAID substitution protocols. Margins are tightening in oral formulations due to bioequivalence enforcement by Health Canada and the PMDA.
Supply Chain Analysis
Cold-chain logistics costs for biologic pain modulators requiring 2-8°C storage are restructuring distribution economics to ambulatory surgery centers. Pharmaceutical-grade hyaluronic acid draws from avian tissue processing in China and France alongside fermentation clusters in Japan and Switzerland, exposing networks to avian influenza quarantine protocols. Single-source vulnerability concentrates in rooster comb raw material concentration exceeding seventy percent. Distribution runs through integrated delivery networks credentialing advanced practice providers for intra-articular procedures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA accelerated approval pathways for disease-modifying therapies are restructuring clinical trial investment and reshaping competitive entry costs.
For Market Incumbents: Anticipate formulary exclusion risk from Medicare Advantage direct-access contracting by securing exclusive hospital system partnerships for supervised injection protocols. Deepen backward integration into fermentation-based polymer production to defend margin position against avian supply disruptions. Prioritize R&D investment in sustained-release depot technology that reduces clinic scheduling burden. For New Entrants and Emerging Players: EU Green Deal solvent waste mandates in Germany open a window for continuous-flow reactor technology licensing to European manufacturing facilities. Target Japan's expanded three-injection reimbursement sequences as the most penetrable geography for ultra-high molecular weight formulations. Pursue direct-to-employer carve-out arrangements with self-insured Fortune 500 employers bypassing traditional payer networks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized orthopedic device manufacturers possessing injection platform expertise and ophthalmic-to-orthopedic technology transfer capabilities. Long-term viability favors entities with demonstrated cold-chain infrastructure and disease-modification pipeline candidates. Watch for FDA Division of Anesthesiology efficacy threshold relaxations as inflection signal for symptomatic slow-acting drug category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA accelerated assessment for structure-modifying claims compresses review timelines for radiographic joint-space narrowing data. |
| Manufacturing Scale-Up | Fermentation-based production of polymers above 6,000 kDa extends intra-articular residence time and reduces injection frequency. |
| Hospital System Partnership | Integrated delivery networks credentialing advanced practice providers concentrate procedural volume outside traditional referral pathways. |
| Reimbursement Strategy | Medicare outpatient payment rate defense sustains viscosupplementation volume in hospital outpatient departments. |
| Pipeline Diversification | Combination biologic-corticosteroid formulations with anti-nerve growth factor antibodies target multi-month efficacy from single injection. |
Study Parameters
Multiple input streams — formulary database analysis, hospital procurement contract review, and regulatory filing examination — were reconciled with primary interviews across drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement data. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Data-stream reconciliation across product type, delivery mode, end user, and disease stage segmentation generated volume and value outputs over the projection horizon. CAGRs were derived from procedure volume trends, reimbursement rate trajectories, and pipeline probability-adjusted revenue forecasting. Molecular weight specification changes and injection frequency reduction curves served as industry-specific forecast inputs.
Revisions become necessary when avian influenza quarantine protocols disrupt hyaluronic acid raw material supply, FDA efficacy thresholds shift for symptomatic slow-acting drugs, or Medicare reimbursement rates compress for outpatient procedures. Forecasts reflect assumptions about regulatory pathway maturation and payer evidence requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Bone Spur Market
Orthopedics
Kyphosis Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
US Arthritis Market
Orthopedics
Tendon Repair Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Podiatry Services Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Rickets Market