
 Deaver Retractor Market | 2026-2036
Deaver Retractor Market Size, Share, and Industry Trends Forecast 2026-2036
Deaver Retractor Market Analytics
ISO 13485 certification is bifurcating the competitive landscape between qualified surgical instrument manufacturers and unaccredited suppliers. Integra LifeSciences leverages its vertically integrated manufacturing footprint across multiple North American facilities. Becton, Dickinson and Company anchors its position through sustained R&D investment in advanced metallic alloys for retractor construction. Sklar differentiates by specializing in handcrafted stainless steel instruments with established distribution through hospital purchasing cooperatives.
A Deaver retractor is a broad, curved handheld surgical instrument with a flat blade measuring 25–50 mm in width, designed to retract large tissue masses and organs during deep abdominal and thoracic procedures. The instrument derives its functional performance from blade curvature radius and handle ergonomics that reduce surgeon fatigue during prolonged operations. Stainless steel instruments dominate current procurement volumes due to established sterilization compatibility and cost amortization across thousands of reuse cycles, while titanium variants command premium positioning in neurosurgery applications where non-magnetic properties prove essential. Ambulatory surgical centers represent the fastest-growing end user segment as outpatient procedure migration accelerates instrument demand outside traditional hospital settings.
FDA 510(k) premarket notification requirements govern instrument biocompatibility and cleaning validation, while the EU Medical Device Regulation imposes stricter clinical evidence standards for reusable surgical devices entering European markets. Health Canada and TGA maintain parallel conformity assessment pathways that manufacturers must navigate for multi-jurisdictional product registration. Stakeholders must monitor evolving sterilization validation protocols and single-use competitive threats when allocating capital between durable instrument platforms and disposable alternatives.
Market Dynamics
ISO 13485 certification requirements are bifurcating the Deaver retractor supplier base, creating procurement preference for accredited manufacturers while elevating compliance costs for smaller instrument workshops. This structural filter concentrates hospital purchasing power toward vertically integrated producers with captive metallurgy and sterilization validation capabilities.
Growth Catalysts
- FDA 510(k) material traceability mandates:Biocompatibility documentation requirements are accelerating hospital replacement cycles for legacy instrument inventories lacking certified provenance.
- Ambulatory surgical centers:Outpatient migration toward same-day abdominal procedures is expanding addressable instrument demand beyond traditional hospital operating theaters.
- Titanium alloy adoption:Non-magnetic properties essential for neurosurgery and MRI-compatible suites are commanding premium positioning and expanding application scope.
Market Restraints
- Nickel price volatility:Stainless steel feedstock costs fluctuate with commodity markets, compressing margin predictability for mid-tier instrument fabricators.
- Single-use retractor substitution:Polymer-based disposable alternatives eliminate sterilization overhead and are capturing share in high-turnover outpatient settings.
- EU MDR clinical evidence thresholds:Stricter reusable device documentation requirements are extending registration timelines and freezing European market entry for non-compliant suppliers.
Strategic Opportunities
- Health Canada parallel review pathways:Synchronized FDA-Health Canada submissions reduce regulatory duplication for North American market access.
- Robotic-assisted surgery integration:Retractor designs compatible with da Vinci and competing surgical robotics platforms open procedural automation segments.
- Direct-to-ASC distribution:Bypassing hospital purchasing cooperatives through specialized ambulatory supply contracts captures margin otherwise lost to group purchasing organization fees.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlogs delay quality management system approvals, freezing production authorization for new market entrants.
- Sterilization validation protocol evolution:Shifting from steam to hydrogen peroxide vapor methods requires instrument redesign and requalification investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deaver Retractor Market |
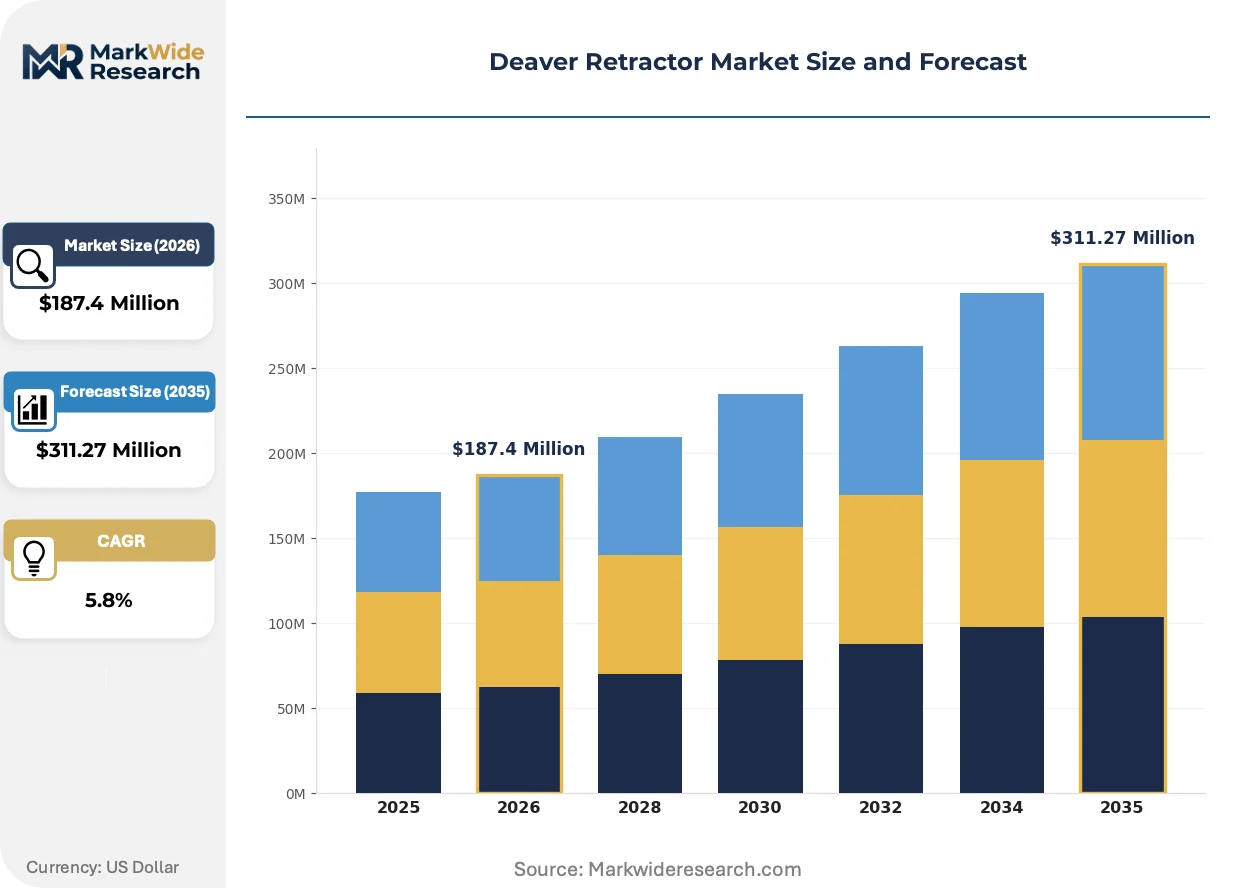
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Retractors, Lifting Retractors, Self-Retaining Retractors, Pediatric Retractors Material: Stainless Steel, Titanium, Plastic, Composite End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Application: General Surgery, Orthopedic Surgery, Cardiothoracic Surgery, Neurosurgery |
| Companies Covered | Integra LifeSciences, Becton, Dickinson and Company, Teleflex Incorporated, Medline Industries Inc., Sklar, Electro Surgical Instrument Co., STERIS Instrument Management Services, Surtex Instruments, Invuity Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deaver Retractor Market Evolving Landscape
Electropolished surface finishing and modular handle systems are displacing legacy instrument architectures. These advances reduce protein adhesion and enable surgeon-specific ergonomic configuration.
Laser-sintered titanium retractor blanks are miniaturizing production lot sizes. Academic medical centers in the United States are commissioning patient-specific curvature profiles for complex hepatobiliary reconstructions. This distributed manufacturing model compresses instrument procurement cycles from months to weeks.
EU MDR Article 10 clinical evaluation requirements are elevating post-market surveillance burdens. Reusable surgical instrument manufacturers must maintain systematic literature reviews and vigilance reporting systems. European notified bodies are prioritizing review resources toward high-risk device categories, extending retractor certification timelines.
Hospital value analysis committees are consolidating vendor panels around multi-year instrument service agreements. Group purchasing organizations are unbundling retractor procurement from comprehensive surgical sets. This preference shift concentrates purchasing power among suppliers with captive repair and refurbishment infrastructure.
Deaver Retractor Market Segmentation
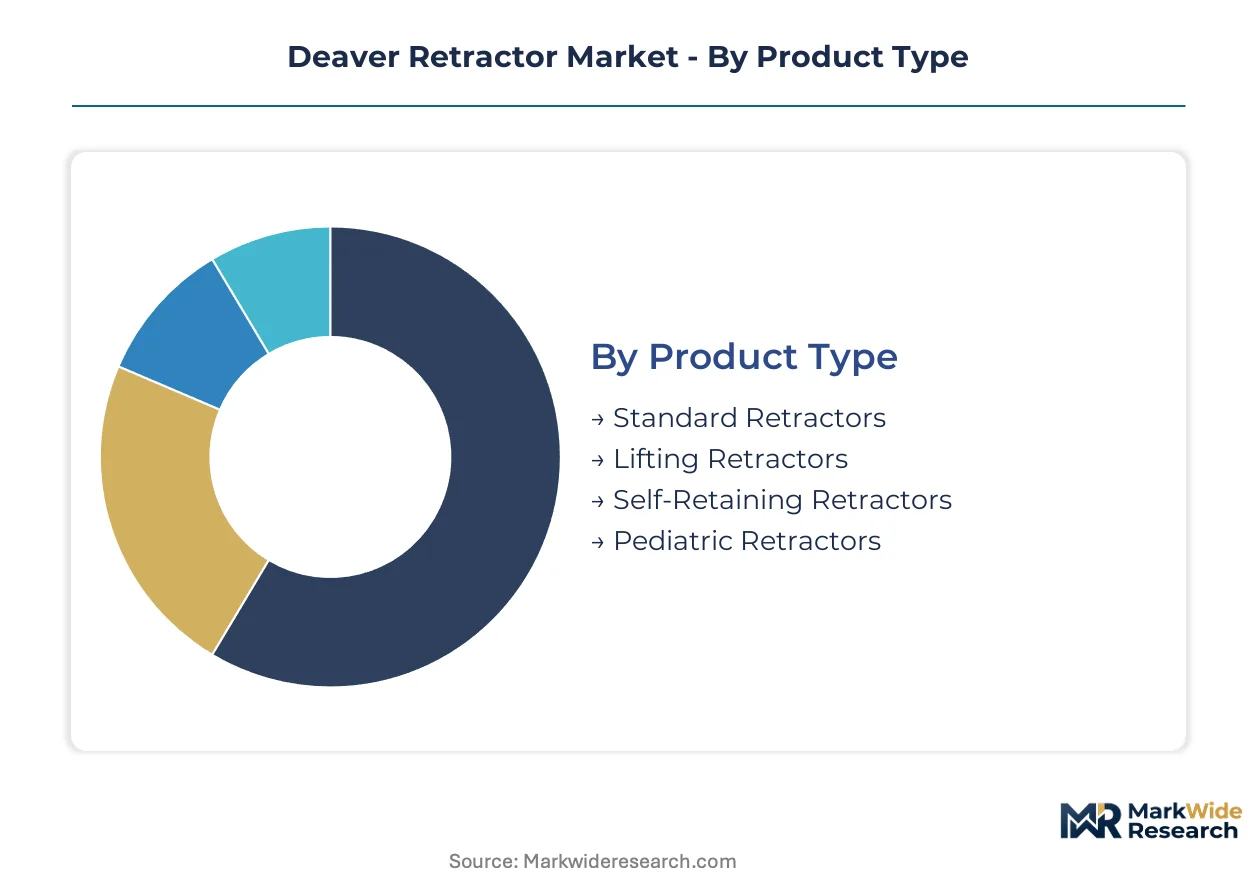
Deaver retractor procurement patterns diverge sharply across surgical settings, with material specifications and automation compatibility driving vendor selection. Hospital value analysis committees now segment purchasing decisions by sterilization throughput and procedure-specific ergonomic requirements rather than traditional instrument categorization alone.
Product Type:
Margin pools concentrate in self-retaining variants where mechanical complexity commands premium positioning against commoditized handheld alternatives.
- Standard Retractors:Handheld broad-blade instruments with fixed curvature profiles dominate procurement volumes across high-throughput general surgery departments. Demand concentrates in United States academic medical centers performing open abdominal procedures, constrained by surgeon preference for tactile feedback over mechanical assistance.
- Self-Retaining Retractors:Ratchet-locking mechanisms with adjustable blade positioning reduce operative team size requirements during prolonged thoracic exposures. United States hospitals with robotic surgery programs are rotating these into hybrid open-minimally invasive workflows, capturing margin through reduced nursing labor allocation.
- Lifting Retractors:Elevated mechanical advantage designs target bariatric and hepatobiliary reconstructions requiring sustained tissue elevation.
- Pediatric Retractors:Miniaturized blade profiles with reduced tissue contact area serve neonatal and infant surgical populations.
Standard retractors hold installed capacity. Self-retaining retractors are rotating up the share rankings.
Material:
Cost tier stratification separates aerospace-grade titanium from commodity stainless procurement, with composite intermediates capturing ambulatory price sensitivity.
- Stainless Steel:Electropolished 400-series alloys with validated steam sterilization compatibility amortize acquisition costs across thousands of reuse cycles. United States hospital purchasing cooperatives negotiate multi-year supply agreements around this grade, though nickel price volatility compresses fabricator margins unpredictably.
- Titanium:Non-magnetic Ti-6Al-4V alloys enable MRI-compatible neurosurgery suites and eliminate magnetic field interference during image-guided procedures. United States academic centers with intraoperative MRI capabilities are mandating titanium for all retractor classes, expanding application scope beyond traditional neurosurgical boundaries.
- Plastic:Polymer single-use variants eliminate sterilization validation overhead for high-turnover outpatient settings.
- Composite:Carbon-fiber reinforced polymers bridge weight reduction with structural rigidity for robotic-assisted platforms.
Stainless steel dominates unit volume. Titanium is climbing the fastest among premium material tiers.
End User:
Customer type determines distribution channel economics, with direct-to-ASC contracts bypassing GPO fee structures entirely.
- Hospitals:Integrated delivery networks with captive sterile processing departments amortize capital instrument investments across procedure mix. United States systems with value-based contracts are consolidating vendor panels around multi-year service agreements incorporating repair and refurbishment infrastructure.
- Ambulatory Surgical Centers:Freestanding outpatient facilities performing same-day abdominal procedures are expanding addressable instrument demand beyond traditional operating theaters. United States ASC chains are rotating toward disposable polymer alternatives to eliminate sterilization capital expenditure, gaining share fastest among end-user categories.
- Clinics:Office-based surgical suites with limited procedure volumes favor rental and reprocessing service models.
- Research Institutions:Academic laboratories with cadaveric training programs require specialized curvature profiles for surgical education.
Hospitals retain procurement volume leadership. Ambulatory surgical centers are gaining share fastest through outpatient migration.
Application:
Procedure complexity dictates instrument specification, with cardiothoracic and neurosurgical applications commanding specialized metallurgy and surface finishing.
- General Surgery:Open abdominal procedures including colectomy, hepatectomy, and trauma laparotomy constitute baseline demand for standard blade configurations. United States community hospitals with high cholecystectomy and hernia repair volumes are rotating procurement toward modular handle systems enabling surgeon-specific ergonomic customization.
- Neurosurgery:Cranial and spinal exposures requiring non-ferromagnetic instrumentation for intraoperative MRI compatibility mandate titanium construction. United States tertiary referral centers with advanced imaging suites are expanding titanium retractor adoption across all blade sizes, displacing legacy stainless inventories.
- Orthopedic Surgery:Deep soft tissue retraction during joint arthroplasty and spine fusion procedures favors robust blade geometry.
- Cardiothoracic Surgery:Sternotomy and thoracotomy exposures require extended blade lengths with reinforced structural profiles.
General surgery holds installed base dominance. Neurosurgery is rotating up the share rankings through imaging suite expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate procurement authority for complex abdominal instrumentation. Hospital purchasing cooperatives in Germany and Japan exert parallel influence over metallic alloy specifications. Tertiary referral networks in Australia and Canada complete the demand cluster through specialized neurosurgical and cardiothoracic programs.
United States
FDA 510(k) material traceability mandates accelerate replacement cycles for legacy instrument inventories lacking certified provenance. Academic medical centers performing complex hepatobiliary reconstructions commission patient-specific curvature profiles through laser-sintered titanium production. The Cleveland Clinic and Mayo Clinic surgical networks anchor demand concentration for MRI-compatible titanium variants across all blade configurations.
Germany
EU MDR Article 10 clinical evaluation requirements elevate post-market surveillance burdens for reusable surgical instrument manufacturers. Notified bodies prioritize review resources toward high-risk device categories, extending retractor certification timelines. The Tuttlingen surgical instrument cluster maintains fabrication density for electropolished stainless steel instruments serving European hospital systems.
Japan
PMDA conformity assessment pathways parallel FDA review structures for multi-jurisdictional product registration. METI industrial policy supports domestic titanium alloy processing capabilities for non-magnetic neurosurgical applications. The Osaka-Kobe medical device manufacturing corridor concentrates precision machining capacity for modular handle systems.
Australia
TGA parallel review pathways with FDA reduce regulatory duplication for North American market access. Intraoperative MRI suite expansion at tertiary referral centers mandates titanium construction across all retractor classes. The Melbourne biomedical precinct anchors procurement concentration for robotic-assisted surgery compatible instrument designs.
Canada
Health Canada sterilization validation protocols evolve toward hydrogen peroxide vapor methods, requiring instrument redesign and requalification investment. Provincial health authorities consolidate vendor panels around multi-year instrument service agreements. The Toronto-Waterloo medical technology corridor concentrates distribution infrastructure for direct-to-ASC supply contracts.
Deaver Retractor Market Competitive Landscape
Player mix skews toward vertically integrated surgical instrument manufacturers with captive metallurgy and sterilization validation capabilities. ISO 13485 certification bifurcates the supplier base, elevating compliance costs for smaller instrument workshops while concentrating hospital purchasing power. Three archetypes dominate: multi-facility conglomerates with diversified medical device portfolios, specialized handcrafted instrument workshops, and polymer-based disposable specialists. Competitive moves center on M&A for regulatory capability acquisition and strategic partnerships for robotic platform integration.
Within the premium-tier vector, Integra LifeSciences exemplifies vertically integrated manufacturing with multiple North American production facilities. Becton, Dickinson and Company anchors a position through sustained investment in advanced metallic alloys for retractor construction. Sklar occupies a specialized niche representing handcrafted stainless steel instrument workshops with established distribution through hospital purchasing cooperatives.
| Leading Market Players |
|---|
| Integra LifeSciences |
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| Medline Industries Inc. |
| Sklar |
| Electro Surgical Instrument Co. |
| STERIS Instrument Management Services |
| Surtex Instruments |
| Invuity Inc. |
| Others |
Value Network & Pricing Analysis
Captive metallurgy capacity in Germany and the United States anchors price floors for electropolished stainless steel instruments, while ISO 13485 certification compliance costs stratify supplier tiers. Scale economies at vertically integrated manufacturers compress per-unit overhead across thousands of reuse cycles, concentrating procurement power among accredited producers with in-house sterilization validation.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation govern stainless steel instrument procurement, protecting fabricators from commodity volatility while capping margin expansion. Three-tier pricing structure across titanium premium, stainless standard, and polymer economy levels reflects certification grade and sterilization throughput requirements. Price erosion runs through mid-tier stainless variants as ambulatory surgical centers rotate toward disposable polymer alternatives. Group purchasing organizations exhibit highest price sensitivity through consolidated volume negotiations, while academic medical centers with intraoperative MRI suites demonstrate lowest sensitivity for non-magnetic titanium construction.
Supply Chain Analysis
Tuttlingen precision machining cluster throughput constraints create chokepoint risk for European electropolished instrument supply. Manufacturing concentrates in Germany, the United States, and Japan, with feedstock draws from Swedish specialty steel mills and Russian titanium sponge processors. Single-source vulnerability in aerospace-grade Ti-6Al-4V alloy supply threatens premium tier production continuity. Distribution runs through hospital purchasing cooperatives and direct-to-ASC contracts, bypassing traditional medical-surgical distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) material traceability mandates constitute a regulatory inflection disrupting legacy instrument provenance systems, favoring accredited suppliers with documented metallurgy chains. This disruption accelerates replacement cycles and consolidates procurement authority among compliant manufacturers.
For Market Incumbents: Fortify ISO 13485 certification moats through captive auditor relationships and accelerated quality management system recertification. Invest in backward integration into titanium alloy processing to offset Russian feedstock exposure. Defend against single-use polymer substitution by bundling refurbishment services into multi-year hospital contracts. For New Entrants and Emerging Players: FDA-Health Canada parallel review fast-track offers expedited North American market access without redundant submission cycles. Target ambulatory surgical center direct contracts to bypass group purchasing organization fee structures. Pursue laser-sintered titanium patient-specific curvature as a differentiated entry vector into academic medical center procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated instrument manufacturers with captive metallurgy and sterilization validation infrastructure. Long-term viability hinges on robotic-assisted surgery platform compatibility and MRI-suite expansion trends. Watch intraoperative MRI installation rates at United States tertiary referral centers as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management system accreditation unlocks hospital procurement panel eligibility and GPO contract access. |
| Laser-Sintered Titanium Production | Additive manufacturing compresses patient-specific instrument lead times from months to weeks for hepatobiliary centers. |
| Direct-to-ASC Distribution Buildout | Bypassing hospital purchasing cooperatives captures margin otherwise lost to administrative fee structures. |
| Robotic Platform Integration | da Vinci-compatible retractor designs open procedural automation segments beyond traditional open surgery. |
| Hydrogen Peroxide Vapor Sterilization Requalification | Redesign investment maintains instrument compatibility with evolving Health Canada validation protocols. |
Research Methodology
Cross-validation between hospital purchasing committee interviews and GPO contract database analysis anchors the qualitative findings. Primary fieldwork engaged biomedical engineers, sterile processing directors, GPO contracts managers, and academic surgeons across United States and German hospital systems. Secondary sources encompassed FDA 510(k) filings, EU MDR notified body guidance documents, Health Canada sterilization validation protocols, and specialty steel trade flow data. Bottom-up instrument procurement volume estimates triangulate against top-down surgical procedure forecasts.
Sensitivity analysis across nickel price scenarios, outpatient migration rates, and regulatory timeline variations stress-tests projection robustness. Segmentation modeling spans product type, material grade, end-user facility, and application specialty dimensions across the projection horizon. CAGRs derive from instrument replacement cycle analysis, procedure volume elasticity, and premium material adoption curve fitting. Forecast inputs incorporate sterilization throughput capacity, robotic surgery platform penetration, and intraoperative MRI suite expansion trajectories.
Underlying assumptions cover FDA material traceability enforcement continuity and EU MDR notified body capacity normalization, with deviation risk concentrated in commodity price volatility and single-use substitution acceleration. Practitioners should keep alternative scenarios live as sterilization protocol evolution and ambulatory surgical center reimbursement policies shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Manifolds Market
Medical Devices
Struts Implants Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Pectus Bar System Market
Medical Devices
Laryngoscopes Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market
Medical Devices
Global Blood Transfusion Devices Market
Medical Devices
Trocars Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Unilateral Biportal Endoscopy Market