
 Kyphosis Market | 2026-2036
Kyphosis Market Size, Share, and Industry Trends Forecast 2026-2036
Kyphosis Market Outlook
Hospital procurement of surgical implants is expanding as aging populations across developed economies drive spinal deformity corrections. Medtronic leverages its integrated spine portfolio to dominate thoracolumbar fixation systems. Stryker competes through its proprietary navigation platforms for deformity correction. NuVasive anchors its position with lateral access technologies that reduce procedural invasiveness.
Kyphosis denotes an excessive anterior curvature of the thoracic spine exceeding 40 degrees Cobb angle, typically managed through posterior spinal fusion using pedicle screw-rod constructs, vertebral compression fracture repair with bone cement augmentation, or bracing protocols for progressive deformities in skeletally immature patients. Surgical treatment commands the largest revenue share due to hardware costs and operating room utilization, while rehabilitation devices represent the fastest-expanding category as payors push for shortened acute care stays. Orthotic braces retain stable demand in pediatric scoliosis-kyphosis overlap populations, though margin pools favor implantable segments.
The FDA regulates kyphosis hardware through 510(k) premarket notification and PMA pathways, with EU MDR CE marking requirements tightening clinical evidence standards for long-term implantable devices. ISO 14155 governs clinical investigation conduct across jurisdictions, while CMS national coverage determinations shape hospital capital allocation for advanced spine surgery technologies. Stakeholders must monitor evolving real-world evidence requirements and reimbursement parity between inpatient and outpatient surgical settings.
Market Dynamics
Medicare reimbursement parity between inpatient and outpatient spine surgery is compressing hospital capital allocation cycles and forcing device manufacturers to demonstrate same-day discharge economics.
Growth Catalysts
- Aging Demographics:Japan's super-aged population and Germany's 65-plus cohort expansion are generating surgical volumes for thoracolumbar deformity correction that outpace general orthopedic growth.
- EU MDR CE Marking:The tightened clinical evidence standards for long-term implantables are paradoxically accelerating consolidation among manufacturers with robust post-market surveillance infrastructure.
- Minimally Invasive Access:Lateral and oblique lumbar interbody fusion techniques are reducing blood loss and recovery times, expanding surgical candidacy to frail patients previously managed conservatively.
Market Restraints
- Titanium Alloy Cost Volatility:Spinal implant raw material prices fluctuate with aerospace demand cycles, squeezing gross margins for hardware manufacturers without captive supply agreements.
- Supply Concentration:Precision machining of multi-axial pedicle screws concentrates among German and Swiss contract manufacturers, creating single-source vulnerabilities for mid-tier device firms.
- Biologics Substitution:Bone morphogenetic protein-2 and synthetic graft alternatives are displacing autograft harvesting in fusion procedures, eroding traditional hardware-anchored surgical workflows.
Strategic Opportunities
- India's Tier-2 Cities:Underpenetrated urban centers like Pune and Kochi lack dedicated spine surgery infrastructure, creating first-mover advantages for training-intensive deformity correction programs.
- Remote Patient Monitoring:Wearable posture sensors and automated brace compliance trackers are converging with telehealth platforms to enable post-surgical surveillance outside traditional rehabilitation facilities.
- CMS Innovation Center Models:Bundled payment pilots for lumbar fusion are creating financial incentives for hospitals to adopt value-engineered implant portfolios and standardized care pathways.
Industry Challenges
- Surgeon Training Bottlenecks:Complex three-column osteotomy techniques require fellowship-level expertise that residency programs inadequately produce, constraining procedural capacity expansion.
- 510(k) Predicate Drift:FDA clearance pathways rely on increasingly obsolete device comparisons, forcing manufacturers to pursue costly de novo or PMA routes for novel deformity correction systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kyphosis Market |
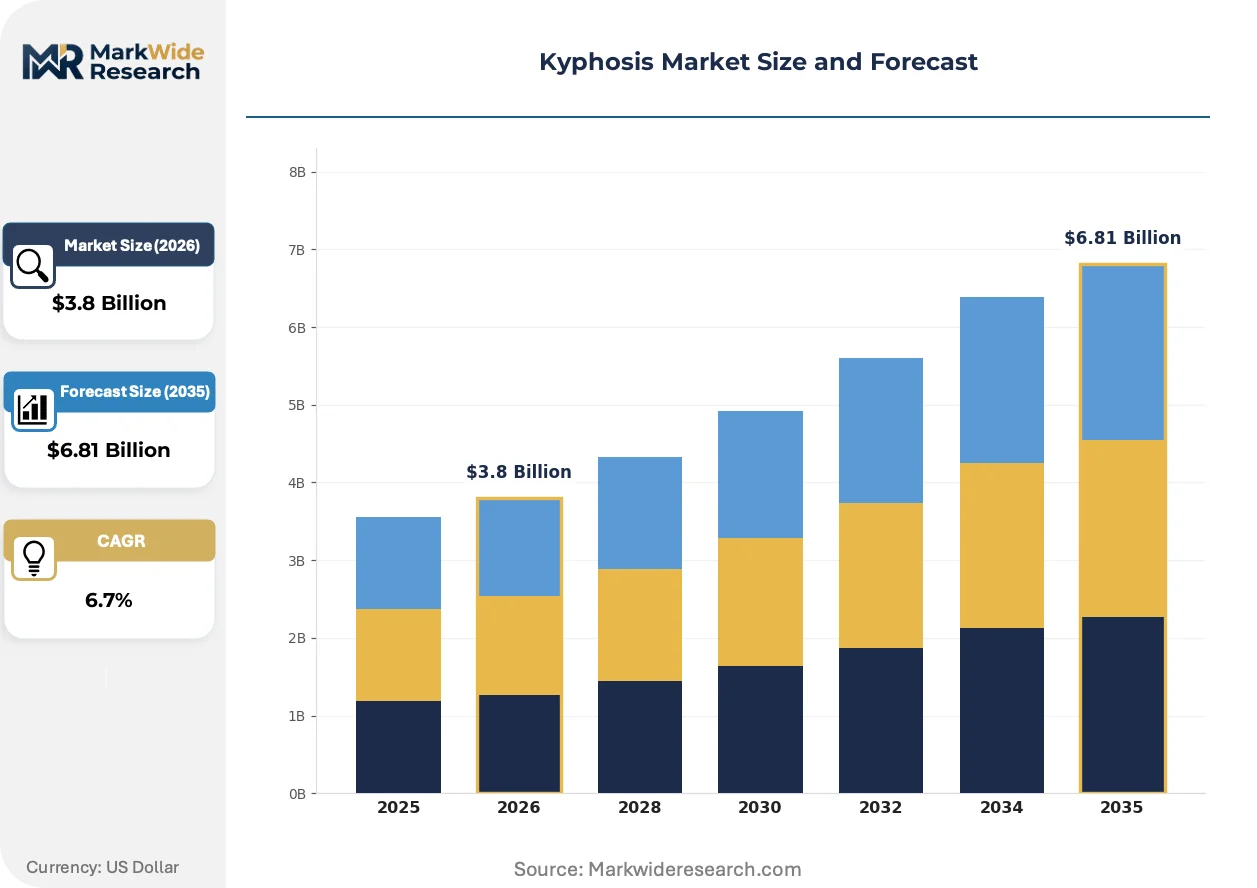
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Treatment, Rehabilitation Devices, Orthotic Braces, Medication End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Treatment Approach: Non-Surgical, Surgical, Physiotherapy, Pain Management Age Group: Pediatrics, Adults, Seniors, Others |
| Companies Covered | Medtronic, Stryker, NuVasive, Zimmer Biomet, Johnson & Johnson, Boston Orthotics & Prosthetics, Globus Medical, Amneal Pharmaceuticals, Teva Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kyphosis Market Strategic Shifts
Robotic navigation and patient-specific implant design are displacing freehand screw placement as the default surgical standard, compressing the learning curve for complex deformity correction.
Patient-matched titanium 3D-printed interbody cages now integrate porous lattice structures that mimic trabecular bone stiffness. Academic medical centers in the United States and South Korea are adopting these constructs for revision fusion cases with severe endplate destruction. This manufacturing shift is converging with preoperative planning software to eliminate intraoperative trialing and reduce operative time.
EU MDR's enhanced post-market surveillance requirements for Class III implantables are extending clinical follow-up obligations to ten years. Device manufacturers must now fund registry participation and periodic safety update reports. Small-cap spine firms without European commercial infrastructure are exiting the market, concentrating CE-marked portfolios among multinationals with dedicated regulatory affairs divisions.
Hospital purchasing committees are consolidating vendor contracts around single-source spine platforms that bundle navigation, implants, and biologics. Independent surgeons and smaller health systems lose negotiating leverage as procurement centralizes at integrated delivery network headquarters. This concentration is most visible in the United States, where Catholic health systems and for-profit chains now dominate implant selection authority.
Kyphosis Market Segmentation
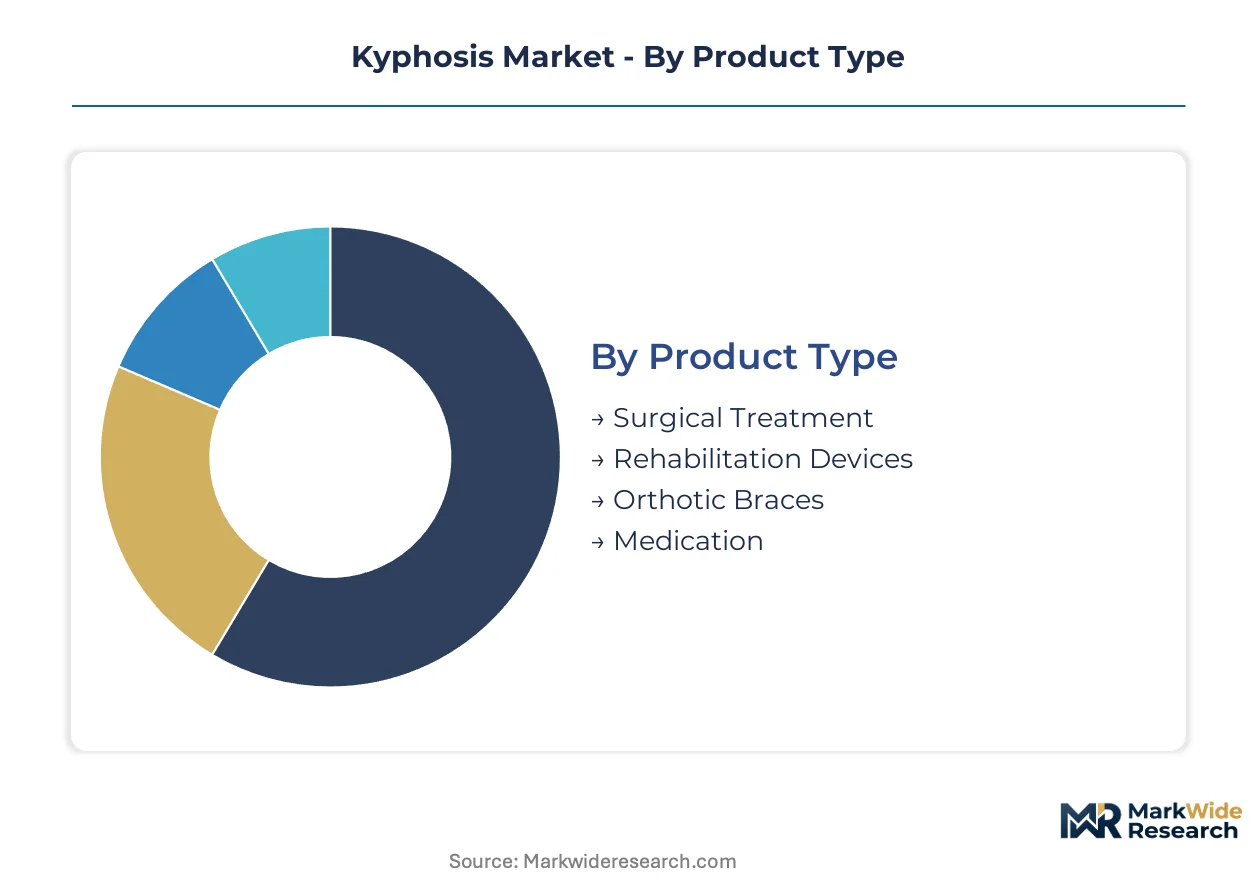
Kyphosis treatment pathways diverge sharply by patient frailty, deformity severity, and reimbursement environment. Procurement patterns across these segments reveal where hardware margins concentrate versus where volume expansion occurs.
Product Type:
Hospital purchasing committees allocate capital differently based on whether the intervention requires implantable hardware, durable medical equipment, or pharmaceutical protocols.
- Surgical Treatment:Posterior spinal fusion with pedicle screw-rod constructs and vertebral compression fracture repair with bone cement augmentation dominate hospital revenue. Demand concentrates in United States academic medical centers where Medicare reimbursement for minimally invasive spine surgery continues evolving.
- Rehabilitation Devices:Wearable posture sensors and automated brace compliance trackers enable post-surgical surveillance outside traditional facilities. Germany's statutory health insurance funds are expanding coverage for these technologies to shorten acute care stays.
- Orthotic Braces:Thoracolumbosacral orthoses retain stable demand in pediatric scoliosis-kyphosis overlap populations, though margin pools favor implantable segments.
- Medication:Analgesics and anti-osteoporotic agents serve conservative management protocols, particularly in Japan where super-aged patients often preclude surgical candidacy.
Surgical Treatment leads volumes today; Rehabilitation Devices are gaining share fastest.
End User:
Site-of-care economics reshape vendor relationships, with integrated delivery networks centralizing purchasing authority away from individual physicians.
- Hospitals:Inpatient and outpatient surgical departments command the largest capital allocation for navigation platforms, robotic systems, and implant inventories. United States Catholic health systems and for-profit chains now dominate implant selection authority through consolidated vendor contracts.
- Clinics:Ambulatory surgery centers capture migrating procedural volume as Medicare reimbursement parity compresses hospital capital allocation cycles.
- Rehabilitation Centers:Post-acute facilities manage bracing protocols and physiotherapy regimens, particularly for progressive deformities in skeletally immature patients.
- Home Care:Remote patient monitoring through telehealth platforms is expanding surveillance capabilities for post-operative kyphosis patients in South Korea's aging metropolitan regions.
Hospitals retain the dominant procurement position; Clinics are climbing the fastest as outpatient migration accelerates.
Treatment Approach:
Clinical decision-making balances deformity progression risk against patient comorbidity profiles, with minimally invasive techniques expanding surgical candidacy.
- Surgical:Three-column osteotomy and lateral interbody fusion techniques reduce blood loss and recovery times. Surgeon training bottlenecks constrain procedural capacity expansion despite aging demographic demand in Germany and Japan.
- Non-Surgical:Bracing and observation protocols manage progressive deformities in skeletally immature patients, with orthotic compliance tracking improving outcomes.
- Physiotherapy:Schroth method and core stabilization programs address postural kyphosis, particularly in adolescent populations where skeletal growth remains incomplete.
- Pain Management:Epidural steroid injections and radiofrequency ablation serve degenerative kyphosis patients in United States Medicare populations where surgical risk exceeds benefit.
Surgical approaches command the steepest expansion trajectory; Non-Surgical protocols retain the largest treated population.
Age Group:
Pathophysiology and treatment tolerance vary dramatically across developmental stages, driving distinct product configurations and clinical workflows.
- Seniors:Osteoporotic compression fractures and degenerative sagittal imbalance drive vertebral augmentation and short-segment fusion demand. Japan's super-aged population generates surgical volumes that outpace general orthopedic growth.
- Adults:Post-traumatic and iatrogenic deformities require complex revision reconstruction, with patient-matched 3D-printed interbody cages addressing severe endplate destruction.
- Pediatrics:Scheuermann's disease and congenital kyphosis necessitate growth-friendly instrumentation or bracing protocols, with FDA 510(k) pathways accelerating commercialization of expandable rod systems.
- Others:Neuromuscular and syndromic kyphosis populations require multidisciplinary management across orthopedic and genetic specialties.
Seniors dominate current procedural volume; Pediatrics shows the most rapid technology innovation uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where kyphosis device manufacturers establish production and commercial infrastructure, with cost-of-compliance gaps between jurisdictions driving facility location decisions and market entry sequencing.
United States
Medicare reimbursement parity between inpatient and outpatient spine surgery is compressing hospital capital allocation cycles across the Southeast and Southwest. FDA 510(k) clearance pathways for thoracolumbar devices accelerate commercialization timelines for manufacturers targeting the ambulatory surgery center migration. Academic medical centers in Boston and Houston dominate complex three-column osteotomy volumes.
Germany
The statutory health insurance system's expansion of rehabilitation device coverage is shortening acute care stays for thoracolumbar deformity patients in Bavaria and North Rhine-Westphalia. EU MDR CE marking requirements for Class III implantables are extending clinical follow-up obligations to ten years. Precision machining clusters around Stuttgart and Solingen concentrate multi-axial pedicle screw production for European supply.
Japan
Super-aged demographic profiles are generating surgical volumes for vertebral compression fracture repair that outpace general orthopedic growth in Kanto and Kansai regions. PMDA regulatory frameworks govern long-term implantable device approvals with post-market surveillance mandates. Tokyo and Osaka academic hospitals anchor adoption of patient-matched 3D-printed interbody cages for revision fusion cases.
South Korea
Aging metropolitan populations in Seoul and Busan are expanding demand for minimally invasive lateral access techniques that reduce blood loss and recovery times. MFDS oversight of spinal implant registrations aligns with ISO 14155 clinical investigation standards. Seoul National University Hospital and Asan Medical Center drive adoption of robotic navigation platforms for deformity correction.
India
Underpenetrated spine surgery infrastructure in Pune, Kochi, and other Tier-2 cities is creating first-mover advantages for training-intensive deformity correction programs. CDSCO medical device regulations are tightening import licensing requirements for implantable hardware. Apollo Hospitals and Max Healthcare networks in Delhi-NCR and Mumbai are consolidating procurement authority for navigation platforms and implant inventories.
Kyphosis Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals dominating implantable hardware while regional fabricators capture orthotic brace production. Hospital purchasing committees are consolidating vendor contracts around single-source spine platforms that bundle navigation, implants, and biologics. Three strategic archetypes define positioning: full-portfolio integrators, navigation-technology specialists, and focused biologics suppliers. Competitive moves concentrate on M&A for regulatory infrastructure and capacity expansion in precision machining.
Among full-portfolio integrators, Medtronic and Stryker exemplify the integrated spine platform approach that dominates thoracolumbar fixation procurement decisions. NuVasive occupies a distinct position within the minimally invasive access archetype, representing lateral technique specialization that reduces procedural invasiveness. These three entities anchor the competitive structure through their respective navigation, implant, and access technology combinations.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| NuVasive |
| Zimmer Biomet |
| Johnson & Johnson |
| Boston Orthotics & Prosthetics |
| Globus Medical |
| Amneal Pharmaceuticals |
| Teva Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Precision machining specialists concentrated in Stuttgart and Solingen anchor cost structures across implant tiers, with German labor premiums widening spreads between premium navigation-integrated systems and standard pedicle screw constructs sold into price-sensitive Indian and Southeast Asian markets.
Pricing Analysis
Distributor markups on spinal implants range from 30-45% for multi-axial pedicle screws, with direct-to-hospital contracts commanding steeper discounts for high-volume integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, robotic navigation bundling, and titanium alloy grade. Cost compression in standard-tier hardware is intensifying because contract manufacturers in Germany face aerospace demand competition for precision CNC capacity. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with bundled payment contracts show lowest.
Supply Chain Analysis
Freight costs for temperature-controlled titanium alloy shipments from German mills to Swiss finishing facilities add 8-12% to landed component costs, compressing margins for mid-tier device firms without captive logistics. Supply concentrates in Germany, Switzerland, and the United States for precision-machined spinal implants, with raw material dependencies spanning titanium sponge from Russia and Kazakhstan, cobalt-chrome alloys from South Africa, and biologics carriers from recombinant protein facilities in Ireland and Singapore. Single-source vulnerability concentrates in German multi-axial screw machining. Distribution runs through specialty orthopedic distributors in North America and direct hospital contracts in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in kyphosis hardware hinges on automation of titanium machining and premium-tier shift toward patient-matched 3D-printed interbody cages with porous lattice structures.
For Market Incumbents: Acquire precision machining capacity in Baden-Württemberg to secure captive supply of multi-axial pedicle screws against aerospace demand competition. Invest in EU MDR post-market surveillance infrastructure to extend CE-marked portfolio longevity as small-cap competitors exit. Biologics substitution threatens hardware-anchored workflows; deepen integration into synthetic graft and BMP-2 adjuvant portfolios to defend procedural bundling. For New Entrants and Emerging Players: Begin with remote patient monitoring platforms for post-surgical kyphosis surveillance, targeting South Korean and German reimbursement expansions for wearable posture sensors. India's Tier-2 cities present the most penetrable geography, with Pune and Kochi lacking dedicated deformity correction infrastructure. Partner with Apollo or Max Healthcare networks for training-intensive surgeon education programs as the go-to-market anchor. For Investors and Strategic Acquirers: Hospital systems with captive GPO contracts are the most active acquirer in this space, consolidating vendor selection authority away from independent surgeons. Target mid-cap spine firms with EU MDR transition completion and 510(k) predicate libraries for revision fusion hardware. Watch CMS Innovation Center bundled payment pilot expansion as the inflection signal for same-day discharge economics adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Extended ten-year surveillance obligations filter small-cap competitors from European markets. |
| Hospital System Partnership | Catholic health networks and for-profit chains centralize implant selection authority. |
| Software Companion Development | Preoperative planning platforms eliminate intraoperative trialing for patient-matched cages. |
| Reimbursement Strategy | Medicare parity between inpatient and outpatient settings reshapes capital allocation cycles. |
| FDA 510(k) Submission | Predicate drift forces de novo routes for novel deformity correction navigation systems. |
Study Parameters
Multiple input streams — hospital procurement database analysis, surgeon and biomedical engineer interviews, and CMS reimbursement filing review — were reconciled against secondary validation from FDA 510(k) clearances, EU MDR CE marking registries, and ISO 14155 clinical investigation records. Primary discussions engaged spine surgeons, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at thoracolumbar device manufacturers. Bottom-up procedure volume estimates triangulated with top-down hardware revenue analysis across the analysis window.
Historical implant shipment data cross-referenced against expert panel input on minimally invasive adoption curves shaped the projection framework. Segmentation dimensions modeled include product type, end-user site of care, treatment approach invasiveness, and patient age group pathology. CAGRs derived from logistic diffusion curves for robotic navigation penetration and linear extrapolation for established fusion hardware categories. Forecast inputs incorporated EU MDR transition timelines and CMS bundled payment pilot geographic expansion patterns.
Several conditions sit outside the modeled scope, including unforeseen alloy price shocks, abrupt FDA guidance shifts on 510(k) predicate acceptability, and surgeon training pipeline disruptions. Forecasts reflect documented assumptions about reimbursement parity evolution and MDR surveillance cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Podiatry Services Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Orthopedics Market
Orthopedics
Costochondritis Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Tendon Repair Market
Orthopedics
Elbow Stiffness Market