
 Hips and Knees Reconstructive Market | 2026-2036
Hips and Knees Reconstructive Market Size, Share, and Industry Trends Forecast 2026-2036
Hips and Knees Reconstructive Market Foresight
Switzerland is reconfiguring its precision manufacturing base for orthopedic components, drawing specialist suppliers into the Rhine corridor. Zimmer Biomet leverages its integrated instrumentation ecosystem to control surgical workflow economics. Stryker anchors its position through robotics-assisted knee platforms that tighten operating room integration. Smith & Nephew differentiates via cementless hip systems targeting younger patient cohorts seeking longer implant lifespans.
Hips and knees reconstructive devices encompass total and partial joint replacement systems, comprising femoral stems, acetabular cups, tibial trays, and articulating surfaces engineered from cobalt-chrome alloys, titanium plasma-sprayed substrates, and cross-linked polyethylene liners. These devices restore biomechanical function in degenerated joints, with primary implantation targeting osteoarthritis and secondary intervention addressing periprosthetic fracture or aseptic loosening. Knee implants dominate procedural volume due to higher osteoarthritis prevalence in weight-bearing joints, while revision implants command premium pricing as surgical complexity escalates. Patient-specific technology, guided by preoperative CT segmentation and additive manufacturing of cutting jigs, is displacing conventional instrumentation in high-volume centers.
FDA 510(k) premarket notification and EU MDR conformity assessment govern commercial access, with notified body capacity constraints in Europe extending certification timelines for novel implant designs. Japan's PMDA Shonin approval pathway requires domestic clinical bridging studies, creating regional entry barriers for non-established manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions as evidence requirements for long-term survivorship data intensify, forcing portfolio prioritization decisions across hip, knee, and revision franchises.
Market Dynamics
Patient-specific instrumentation is virtualizing preoperative planning workflows, compressing operating room time and displacing conventional cutting jigs across high-volume orthopedic centers.
Growth Catalysts
- FDA 510(k) Pathway:Streamlined premarket notification accelerates implant iterations for cobalt-chrome femoral stems and cross-linked polyethylene liners, shortening commercialization cycles for established manufacturers.
- Aging Demographics:Germany, Japan, and the United States exhibit concentrated procedure volume growth as populations over 65 drive primary hip and knee replacement demand.
- Additive Manufacturing:Titanium plasma-sprayed substrates produced via electron beam melting enable porous acetabular cup geometries that improve osseointegration outcomes.
Market Restraints
- Cobalt-Chrome Alloy Volatility:Raw material price swings for medical-grade alloys compress margin stability across implant manufacturers dependent on specialized metallurgical supply.
- Notified Body Bottlenecks:EU MDR conformity assessment capacity constraints extend certification timelines for novel implant designs, freezing product pipeline advancement.
- Revision Complexity Premium:Secondary intervention procedures require specialized instrumentation and extended surgical time, limiting addressable patient pools for high-complexity implants.
Strategic Opportunities
- Cementless Hip Expansion:Younger patient cohorts seeking extended implant lifespans create white space for porous-coated femoral stems and biologic fixation surfaces.
- Robotics-Assisted Platforms:Operating room integration of autonomous cutting guides and real-time ligament balancing tightens surgical precision and captures premium pricing.
- Japanese PMDA Bridging:Domestic clinical study requirements for Shonin approval create defensive moats for established players willing to invest in regional evidence generation.
Industry Challenges
- Orthopedic Surgeon Training:Robotics platform adoption requires specialized credentialing programs that strain hospital education budgets and extend technology rollout timelines.
- Legacy Instrumentation Retirement:Conventional cutting jig inventories and sterilization protocols create transition friction as hospitals phase toward patient-specific additive-manufactured guides.
- EU MDR Technical Documentation:Enhanced clinical evidence requirements for long-term survivorship data force portfolio prioritization decisions across hip, knee, and revision franchises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hips and Knees Reconstructive Market |
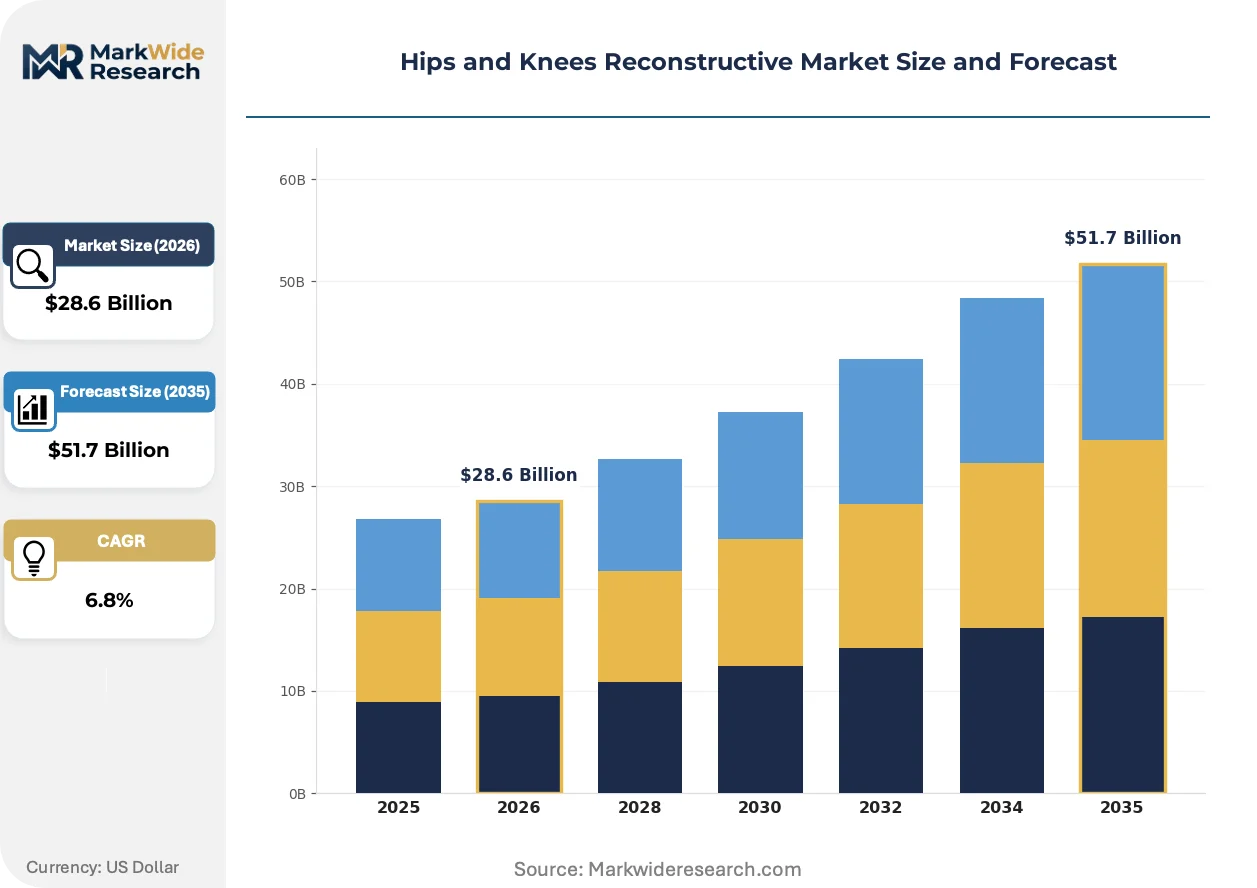
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hip Implants, Knee Implants, Revision Implants, Surgical Instruments End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Surgical Centers Technology: Cemented, Cementless, Hybrid, Patient-Specific Material: Titanium, Stainless Steel, Polyethylene, Coated Alloys |
| Companies Covered | Zimmer Biomet, Stryker, Smith & Nephew, Johnson & Johnson, Exactech, MicroPort Scientific Corporation, B. Braun, CONMED Corporation, Enovis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hips and Knees Reconstructive Market Shifts & Advancements
Preoperative CT segmentation and additive manufacturing are collapsing the traditional boundary between implant production and surgical planning, enabling mass customization at previously unattainable scale.
Patient-specific instrumentation is virtualizing conventional workflow economics. Preoperative CT segmentation generates additive-manufactured cutting jigs matched to individual anatomy. High-volume orthopedic centers in Switzerland and Germany are adopting these systems to reduce operating room time and instrument sterilization burden. This technology is virtualizing the economics of conventional instrumentation, compressing capital equipment requirements and displacing reusable tray logistics.
EU MDR conformity assessment is restructuring competitive access. Enhanced clinical evidence requirements and notified body capacity constraints extend certification timelines for novel implant designs. Manufacturers with established technical documentation and quality management systems capture relative advantage. Revision implant portfolios face particular scrutiny as long-term survivorship data demands intensify.
Hospital procurement patterns are gravitating toward integrated platform contracts. Single-vendor robotics and instrumentation ecosystems tighten operating room standardization and reduce vendor management complexity. Academic medical centers in the United States and Japan are consolidating supplier relationships around comprehensive surgical workflow solutions. This concentration privileges manufacturers with breadth across primary implants, revision systems, and enabling technologies.
Hips and Knees Reconstructive Market Segmentation
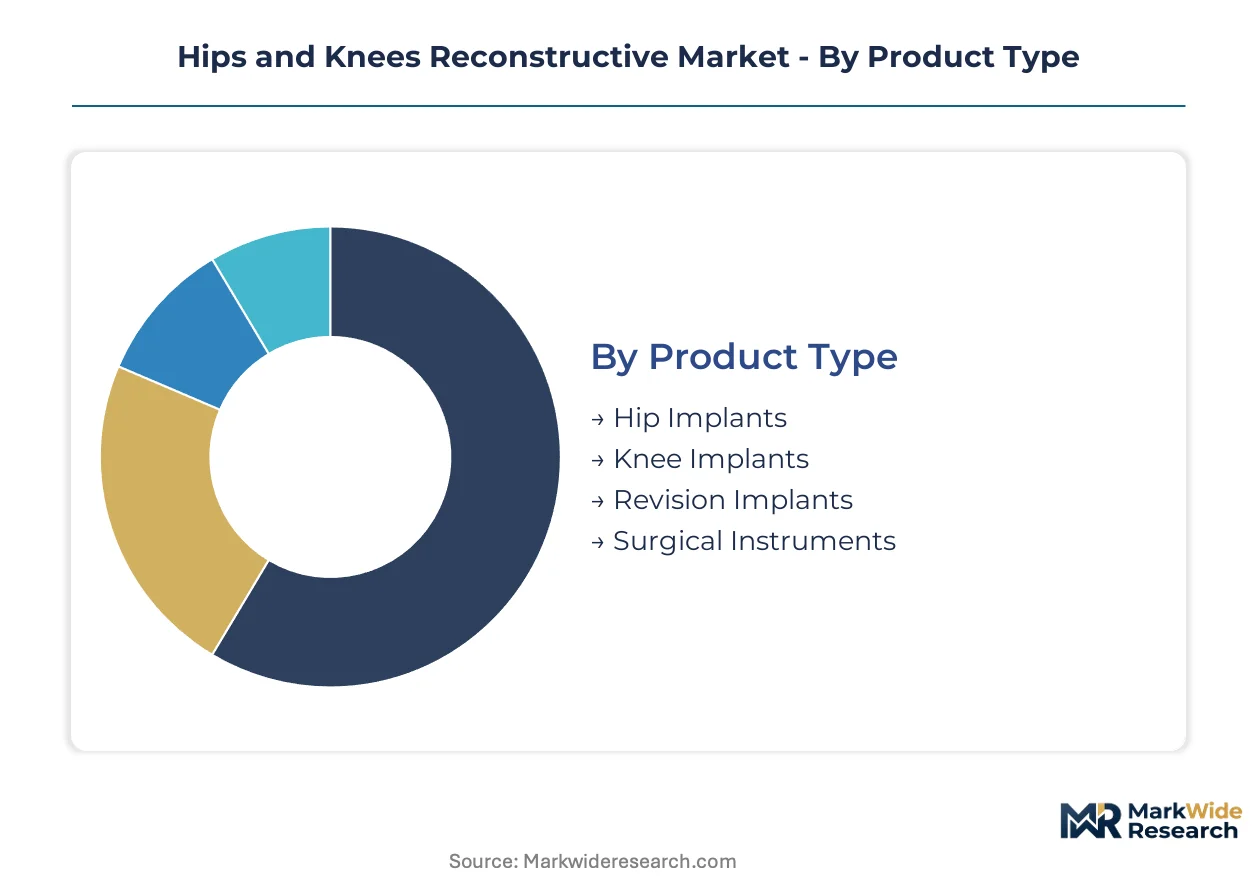
Segmentation in hips and knees reconstructive devices reveals divergent margin profiles and replacement cycles across implant categories. Product type and material composition drive fundamentally different inventory turnover and pricing dynamics, while end-user channel and fixation technology determine adoption velocity and regulatory pathway complexity.
Product Type:
Cycle times vary dramatically across implant categories, with primary procedures turning inventory faster than revision systems and instrumentation carrying the shortest depreciation schedules.
- Hip Implants:Femoral stems and acetabular cups fabricated from cobalt-chrome alloys and titanium substrates address osteoarthritis in the ball-and-socket joint. Demand clusters in Germany and Japan where aging populations and reimbursement density support high-volume arthroplasty programs.
- Knee Implants:Tibial trays, femoral components, and polyethylene liners dominate procedural volume due to higher osteoarthritis prevalence in weight-bearing joints. United States orthopedic clinics are expanding knee replacement capacity faster than hip programs, driven by outpatient surgical center migration.
- Revision Implants:Specialized stems, augments, and constrained liners command extended surgical time and premium positioning. FDA 510(k) pathways for revision systems require augmented clinical evidence compared to primary implants.
- Surgical Instruments:Reusable cutting jigs, reamers, and alignment guides face displacement pressure from patient-specific additive-manufactured alternatives. Sterilization logistics and tray management burden hospitals toward disposable instrumentation contracts.
Knee implants anchor the volume base while patient-specific instrumentation gains share at the steepest rate.
End User:
Channel economics separate high-acuity hospital settings from ambulatory facilities on reimbursement capture and capital equipment requirements.
- Orthopedic Clinics:Specialized facilities concentrate arthroplasty volume and drive adoption of robotics-assisted platforms. Switzerland's Rhine corridor clinics are integrating precision-manufactured instrumentation from regional suppliers.
- Hospitals:Academic medical centers in the United States and Japan consolidate supplier relationships around comprehensive surgical workflow solutions spanning primary and revision implants. EU MDR compliance documentation requirements favor established vendor partnerships.
- Rehabilitation Centers:Post-acute facilities influence implant selection through readmission outcome data and patient-reported satisfaction metrics. Cementless fixation systems with faster early mobilization protocols attract procurement attention.
- Surgical Centers:Ambulatory settings are capturing migrating knee replacement volume as anesthesia protocols and rapid discharge pathways mature. United States outpatient procedural growth is outpacing inpatient admission trends.
Hospitals retain the highest absolute implant consumption while surgical centers expand their addressable procedure mix most aggressively.
Technology:
Fixation approach and customization level stratify across patient age, bone quality, and surgeon training investment.
- Cemented:Polymethyl methacrylate bone cement provides immediate fixation stability in osteoporotic bone and elderly patient cohorts. German and Japanese registries document extensive long-term survivorship data supporting continued utilization.
- Cementless:Porous-coated titanium and cobalt-chrome surfaces enable biologic osseointegration for younger patients seeking extended implant longevity. Younger patient demand for longer functional lifespans is accelerating cementless hip stem adoption.
- Hybrid:Cemented stem with cementless cup combinations optimize fixation strategy by anatomic component. Hybrid constructs balance immediate stability against long-term biologic fixation goals.
- Patient-Specific:Preoperative CT segmentation generates additive-manufactured cutting jigs matched to individual anatomy. High-volume centers in Switzerland and Germany are adopting these systems to compress operating room time and reduce instrument sterilization burden.
Cemented technology dominates current procedural volume while patient-specific systems are climbing the fastest on workflow efficiency gains.
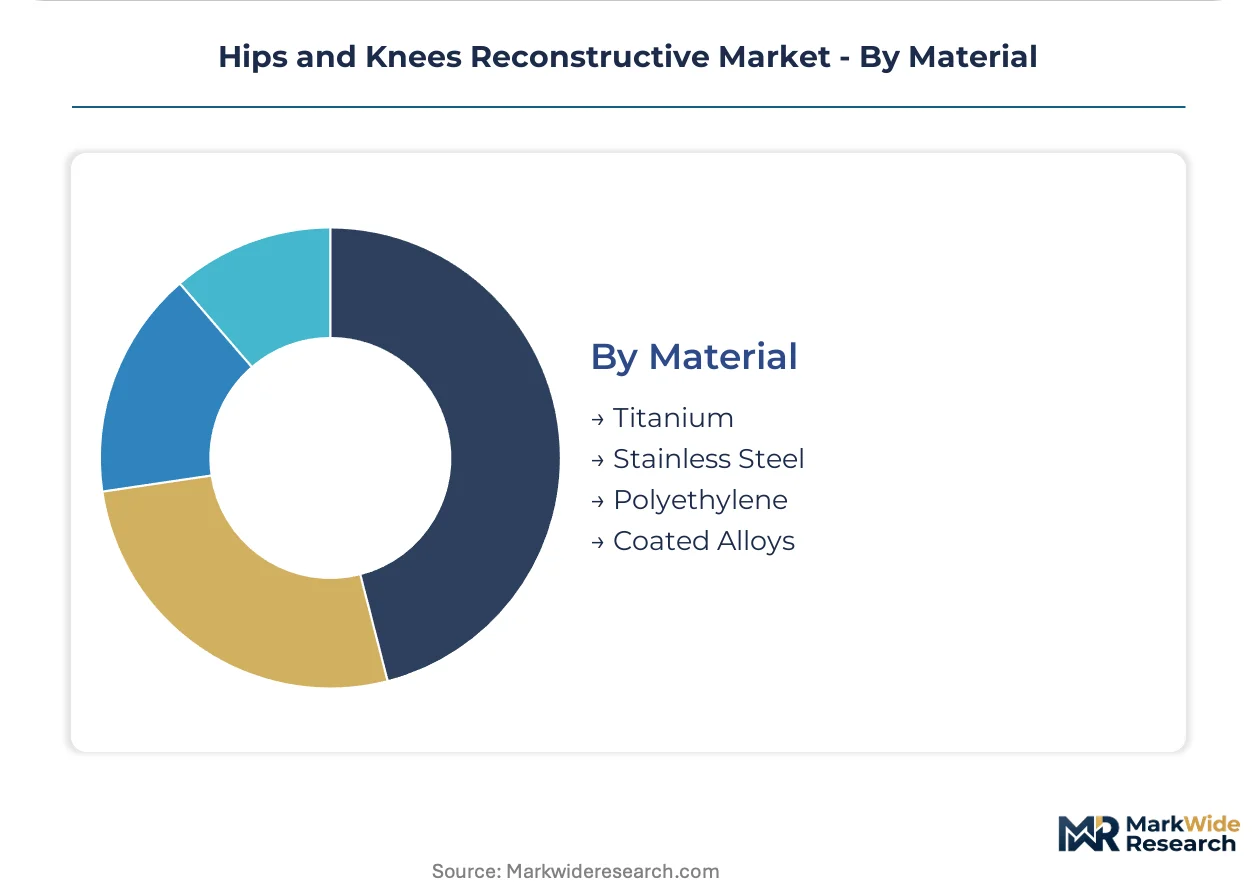
Material:
Metallurgical and polymer selection drives wear characteristics, imaging compatibility, and supply chain concentration.
- Titanium:Plasma-sprayed and porous-coated titanium substrates enable osseointegration in cementless applications. Electron beam melting additive manufacturing is expanding porous acetabular cup geometries.
- Stainless Steel:Lower-cost alloy option for provisional and trauma applications where long-term implantation is not anticipated. Stainless steel provisional components address periprosthetic fracture stabilization.
- Polyethylene:Cross-linked ultra-high molecular weight polyethylene liners reduce wear debris generation in articulating surfaces. Vitamin E-stabilized formulations are extending oxidative resistance.
- Coated Alloys:Hydroxyapatite and porous titanium coatings enhance bone-implant interface biology. Coated femoral stems target younger patient segments seeking extended functional duration.
Titanium and polyethylene combinations anchor material consumption while coated alloy systems are gaining share fastest on cementless expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision manufacturing for orthopedic implants concentrates in the Swiss-German corridor, with specialist suppliers clustering around Basel and Freiburg to serve high-volume arthroplasty centers. This supply-side density shapes competitive access across European and North American markets.
United States
Outpatient surgical centers are capturing migrating knee replacement volume as rapid discharge pathways mature. FDA 510(k) premarket notification streamlines implant iterations for established manufacturers. Academic medical centers in Boston and the Mayo Clinic corridor consolidate supplier relationships around comprehensive surgical workflow solutions.
Germany
Aging demographics over 65 drive concentrated procedure volume growth in hip and knee arthroplasty. EU MDR conformity assessment requirements extend certification timelines for novel implant designs. The Rhine-Neckar and Bavarian industrial clusters host precision machining suppliers serving porous acetabular cup manufacturers.
Japan
PMDA Shonin approval pathways require domestic clinical bridging studies, creating regional entry barriers for non-established manufacturers. Registry-documented long-term survivorship data supports continued cemented fixation utilization. Tokyo and Osaka academic medical centers anchor high-volume arthroplasty programs with integrated robotics platforms.
Switzerland
The Basel-Rhine corridor is reconfiguring its precision manufacturing base for orthopedic components, drawing specialist suppliers from across the Alpine region. Swissmedic regulatory alignment with EU MDR streamlines dual-market certification for implant manufacturers. Zurich and Geneva orthopedic clinics are expanding cementless hip adoption among younger patient cohorts.
Hips and Knees Reconstructive Market Competitive Landscape
Integrated platform vendors and specialized component fabricators split the market between comprehensive surgical workflow providers and focused implant specialists. The vendor base exhibits moderate consolidation, with scale advantages accruing to manufacturers spanning primary implants, revision systems, and enabling technologies. Three strategic archetypes dominate: diversified orthopedic conglomerates with robotics ecosystems, mid-scale implant specialists with regional regulatory depth, and precision manufacturing subcontractors feeding branded OEMs. Competitive moves center on operating room integration contracts and patient-specific instrumentation partnerships that displace conventional cutting jig economics.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker occupy positions as archetypal platform vendors, while Smith & Nephew exemplifies the specialized implant specialist with focused differentiation strategies. These three companies represent contrasting approaches to surgical workflow capture, with each anchoring distinct competitive vectors in hip, knee, and revision franchise development.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker |
| Smith & Nephew |
| Johnson & Johnson |
| Exactech |
| MicroPort Scientific Corporation |
| B. Braun |
| CONMED Corporation |
| Enovis |
| Others |
Supply & Pricing Matrix
Cobalt-chrome alloy concentration in German metallurgical suppliers anchors margin pools downstream with implant manufacturers, while FDA 510(k) clearance tiers stratify pricing power across primary and revision device categories.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing stratification across premium, standard, and economy implant levels, with vitamin E-stabilized polyethylene liners and porous titanium stems commanding quality-grade premiums. Pricing pressure stems from cobalt-chrome raw material volatility compressing margin stability for mid-tier manufacturers. Hospital GPOs exhibit acute price sensitivity in primary knee and hip implants, while revision systems face muted sensitivity due to surgical complexity and limited supplier alternatives.
Supply Chain Analysis
Precision machining contract manufacturers cluster along the Swiss-German Rhine corridor, with specialist suppliers in Basel and Freiburg holding capacity for porous acetabular cup geometries. Electron beam melting feedstock draws from German and Austrian titanium powder specialists, while cross-linked polyethylene resin sources from US and Japanese polymer compounders. Single-source vulnerability concentrates in medical-grade cobalt-chrome forging capacity. Distribution runs through hospital GPO contracts and orthopedic clinic direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as patient-specific instrumentation virtualizes conventional workflow economics, creating niches for additive manufacturing specialists and regional precision fabricators outside established platform ecosystems.
For Market Incumbents: Build regulatory documentation moats through EU MDR technical dossier depth and FDA 510(k) predicate accumulation. Consolidate robotics-assisted platform contracts with academic medical centers in the United States and Japan to lock out emerging instrumentation competitors. Cementless hip portfolio expansion counters margin pressure from commoditized primary knee implants. For New Entrants and Emerging Players: Build out patient-specific additive manufacturing capabilities targeting high-volume orthopedic centers in Switzerland and Germany seeking sterilization burden reduction. Capture white space in cementless femoral stem biologic fixation surfaces for younger patient cohorts. Pursue hospital system partnerships emphasizing operating room time compression rather than implant price competition. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale implant specialists with established PMDA Shonin approval pathways and porous coating intellectual property. Long-term viability hinges on robotics ecosystem integration or defensible regional regulatory depth. Watch for inflection signals in outpatient surgical center knee replacement volume migration rates.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body capacity constraints favor manufacturers with pre-built clinical evidence dossiers. |
| Robotics-Assisted Platform Integration | Stryker and Zimmer Biomet tighten operating room standardization through autonomous cutting guides. |
| Cementless Hip Portfolio Expansion | Smith & Nephew targets younger patients seeking extended implant functional lifespans. |
| Patient-Specific Instrumentation Partnerships | Additive manufacturing of CT-derived cutting jigs displaces conventional reusable tray logistics. |
| Japanese PMDA Bridging Study Commitment | Domestic clinical evidence requirements create defensive moats against non-established entrants. |
Research Methodology
The analysis maps hip implants, knee implants, revision systems, and patient-specific instrumentation, each validated through orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary sources including FDA 510(k) filings, EU MDR notified body documentation, Japanese PMDA Shonin approval records, hospital procurement databases, and arthroplasty registry survivorship data. Bottom-up implant volume estimates triangulated against top-down market value reconstructions.
Assumptions held surgical volume growth trajectories, regulatory pathway timelines, and raw material cost structures fixed across the projection horizon, while varying robotics adoption rates and outpatient migration speeds. Segmentation dimensions modeled include product type, fixation technology, material composition, and end-user channel. CAGRs derived from implant procedure volume elasticities to aging demographic shifts and reimbursement density indices.
Stress conditions across cobalt-chrome alloy price volatility, notified body certification delays, and robotics platform training bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with revision triggers tied to regulatory divergence or supply chain restructuring. Quarterly review of outpatient surgical center admission trends and EU MDR approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Tendon Repair Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Global Osteoarthritis Therapeutics Market