
 Athletic Knee Treatment Market | 2026-2036
Athletic Knee Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Athletic Knee Treatment Market Analytics
ISO 13485 certification for medical device quality management is redrawing competitive boundaries in athletic knee treatment. Stryker leverages its vertically integrated implant manufacturing to sustain premium positioning across hospital systems. Zimmer Biomet anchors its presence in sports medicine through specialized arthroscopy portfolios, while Arthrex competes aggressively on surgeon training and education programs.
Athletic knee treatment encompasses surgical and non-surgical interventions for ligament, meniscal, and cartilage injuries sustained during competitive or recreational sports activity, typically involving biocompatible polymers, titanium alloys, or autologous biological matrices engineered to restore joint kinematics under cyclic loading conditions. Orthotics and braces capture stable recurring revenue from preventive care protocols, whereas regenerative therapies represent the fastest-expanding margin pool as platelet-rich plasma and cell-based approaches displace repeat surgical interventions. Delivery through telehealth channels is gaining structural traction for post-operative monitoring and remote physiotherapy guidance.
FDA 510(k) clearances govern market entry for implantable devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking access across European markets. ISO 14155 standards for clinical investigation of medical devices further shape trial design and approval timelines for novel knee treatment modalities. Stakeholders must weigh regulatory pathway complexity against reimbursement velocity when prioritizing geographic expansion and product development pipelines.
Market Dynamics
FDA 510(k) clearance velocity is compressing commercialization timelines for implantable knee devices, while EU MDR clinical evidence requirements are lengthening European access routes. This regulatory asymmetry is fragmenting go-to-market strategies across major jurisdictions.
Growth Catalysts
- Bundesliga Rehabilitation Infrastructure:German professional football clubs operate dedicated knee treatment centers that standardize advanced physiotherapy protocols and drive demand for premium arthroscopy equipment.
- Telehealth Post-Operative Monitoring:Remote physiotherapy guidance platforms are expanding patient reach beyond traditional clinic boundaries, particularly in rural and suburban catchment areas.
- FDA 510(k) Pathway:The streamlined predicate device framework accelerates orthopedic implant commercialization in the United States compared to de novo review processes.
Market Restraints
- Titanium Alloy Input Concentration:Surgical implant supply chains depend on concentrated raw material sourcing, exposing manufacturers to price volatility and geopolitical supply interruptions.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates extensive clinical investigation data for CE marking, extending approval timelines and elevating compliance costs for novel knee treatment modalities.
- Autologous Therapy Substitution:Patient-derived biological treatments are capturing share from synthetic implantables in meniscal repair applications, pressuring traditional hardware revenue pools.
Strategic Opportunities
- India Sports Medicine Penetration:Underdeveloped specialist infrastructure in tier-two Indian cities creates whitespace for arthroscopy training centers and equipment distribution partnerships.
- ISO 13485 Certification Arbitrage:Quality management certification gaps among regional competitors enable first-mover advantage for certified manufacturers entering emerging European markets.
- Wearable-Physiotherapy Convergence:Motion-sensing orthotics combined with AI-guided rehabilitation protocols are opening subscription-based remote monitoring revenue streams.
Industry Challenges
- Arthroscopy Specialist Training Bottlenecks:Surgeon education programs for minimally invasive knee procedures face capacity constraints, limiting procedure volume expansion regardless of equipment availability.
- ISO 14155 Trial Design Complexity:Clinical investigation standards for medical devices impose rigorous protocol requirements that extend study durations and elevate development costs for novel treatment approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Athletic Knee Treatment Market |
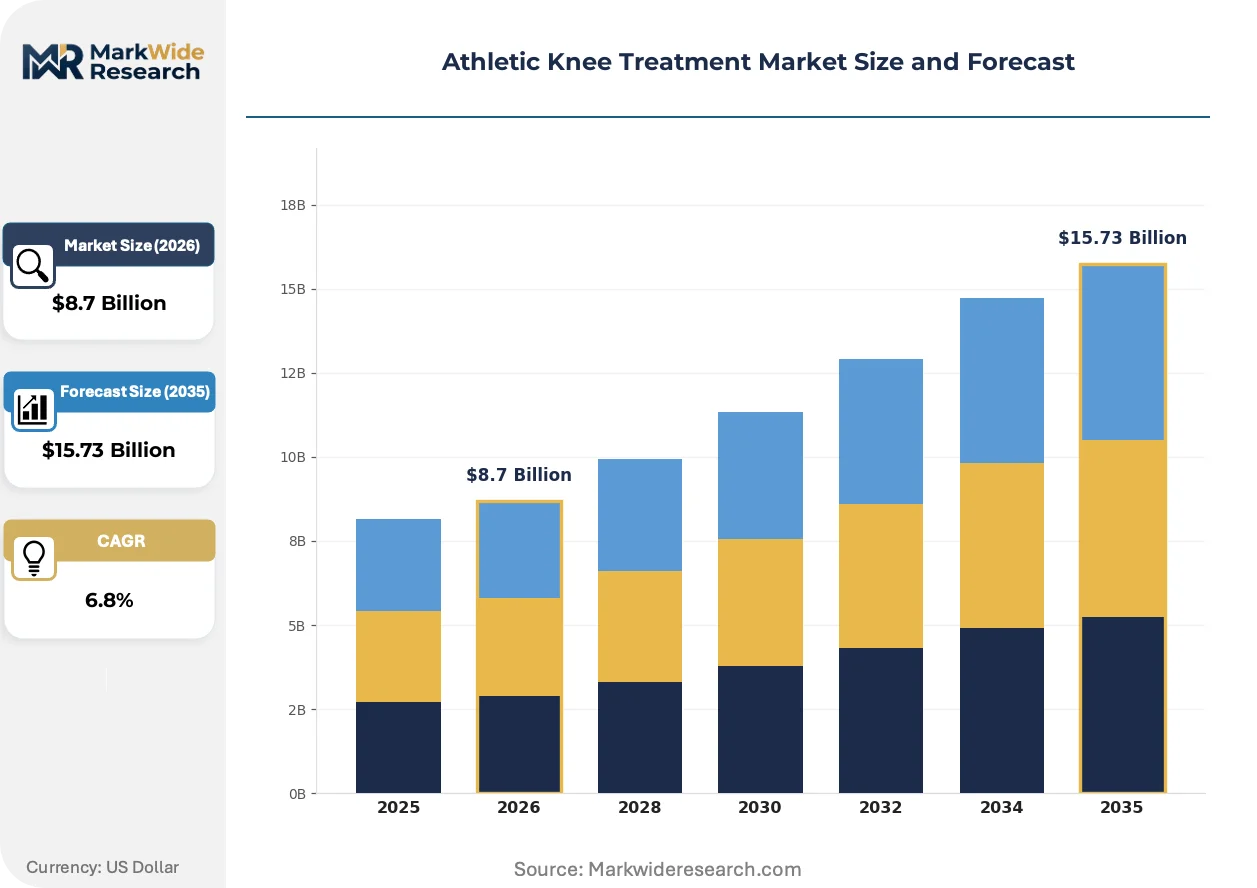
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotics, Braces, Surgical Implants, Regenerative Therapies Delivery Mode: In-Clinic, Home-Based, Hospital, Telehealth End User: Professional Athletes, Recreational Users, Physiotherapy Centers, Sports Teams Application: Injury Recovery, Pain Management, Rehabilitation, Preventive Care |
| Companies Covered | Stryker, Smith & Nephew, Zimmer Biomet, Arthrex, Johnson & Johnson, Medtronic, CONMED, Enovis, Bauerfeind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Athletic Knee Treatment Market Evolving Landscape
Biological regeneration approaches are fragmenting the traditional surgical hardware paradigm, while digital delivery channels are restructuring post-treatment care economics. These shifts are compressing incumbent revenue models and opening alternative margin pools.
Cell-based cartilage repair therapies are bifurcating the knee treatment landscape between mechanical replacement and biological restoration. Academic medical centers in Germany and the United States are piloting matrix-induced autologous chondrocyte implantation at expanding volumes. This technology is bifurcating patient selection criteria and reimbursement pathways, creating parallel treatment tracks based on age and activity level rather than injury severity alone.
EU MDR post-market surveillance requirements are intensifying clinical follow-up obligations for implantable knee devices. Manufacturers must now maintain extended patient registries and periodic safety reporting that elevates ongoing compliance expenditure. Sports medicine divisions with existing ISO 13485 quality infrastructure are absorbing these costs more efficiently than smaller competitors, accelerating consolidation pressure across European markets.
Professional sports franchises are internalizing physiotherapy capabilities that previously outsourced to independent clinics. Bundesliga clubs and NBA franchises now operate captive rehabilitation facilities with dedicated equipment procurement budgets. This concentration is visible most acutely in Germany and the United States, where team-owned medical infrastructure commands premium pricing for preventive brace and orthotic supply contracts.
Athletic Knee Treatment Market Segmentation
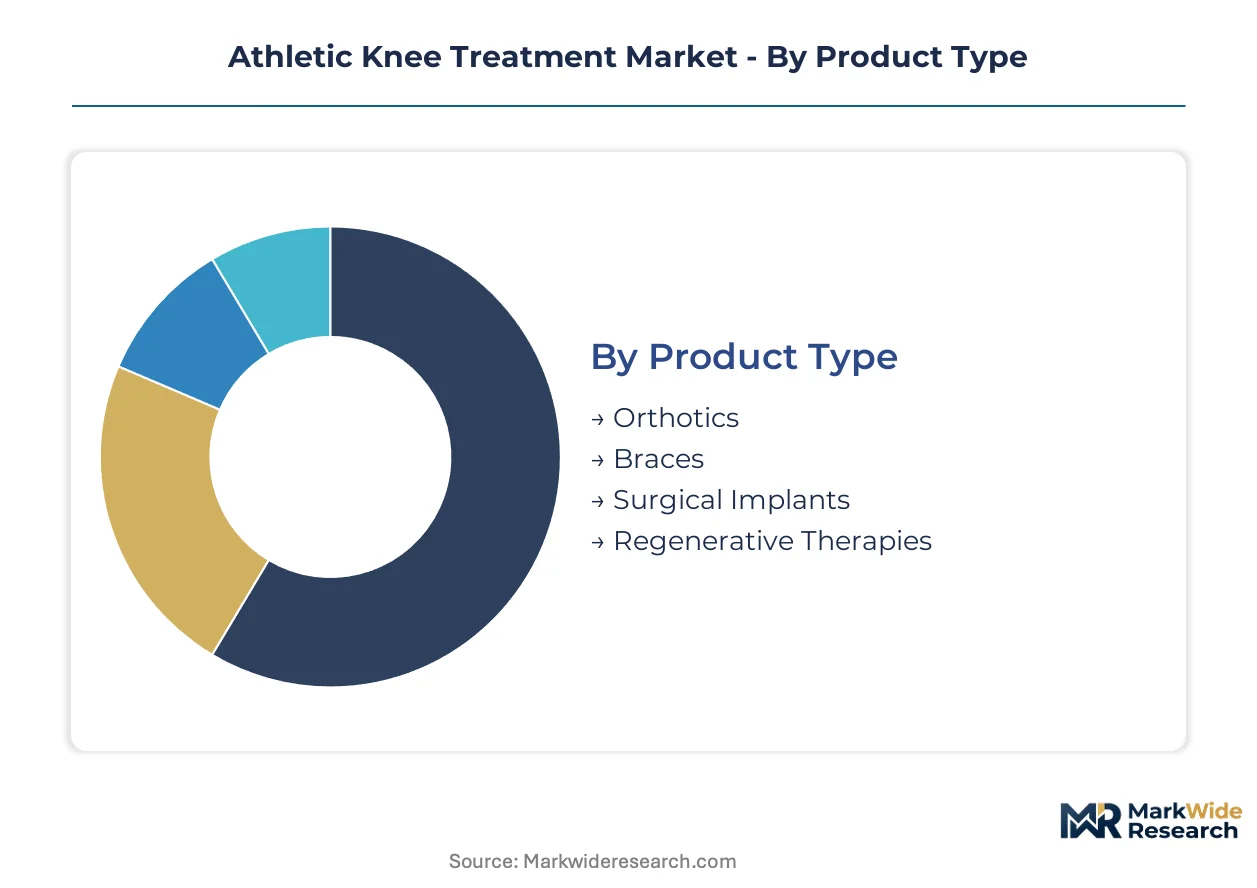
Segmentation in athletic knee treatment reveals distinct procurement patterns across product categories, with professional sports franchises and hospital systems driving divergent channel preferences. Understanding these splits enables targeted positioning against reimbursement pathways and regulatory requirements.
Product Type:
Channel mix varies sharply: orthotics and braces flow predominantly through retail and direct-to-consumer platforms, while surgical implants and regenerative therapies route through hospital purchasing committees and specialist clinics.
- Surgical Implants:Titanium alloy and biocompatible polymer constructs engineered for ligament reconstruction and meniscal repair. Demand concentrates in German Bundesliga medical centers and US hospital systems with dedicated sports medicine divisions, where surgeon training programs and predicate device familiarity accelerate adoption cycles.
- Regenerative Therapies:Platelet-rich plasma and cell-based biological matrices for cartilage restoration. Academic medical centers in Germany and the United States pilot matrix-induced autologous chondrocyte implantation at expanding volumes, with reimbursement pathways bifurcating around patient age and activity level criteria.
- Orthotics:Preventive brace systems capturing recurring revenue from sports team procurement contracts and retail channels.
- Braces:Functional and prophylactic support devices distributed through physiotherapy centers and direct sports franchise supply agreements.
By volume, braces and orthotics lead. By growth pace, regenerative therapies are climbing the fastest.
Delivery Mode:
Cost tier stratification separates premium in-clinic surgical services from economy home-based monitoring, with telehealth emerging as a mid-tier hybrid.
- Telehealth:Remote physiotherapy guidance platforms with AI-driven motion analysis. Rural and suburban catchment areas in the United States drive adoption, where specialist clinic density remains insufficient for post-operative monitoring demands.
- In-Clinic:Specialist-administered arthroscopy and injection therapies. German physiotherapy centers and US sports medicine clinics anchor volume, with ISO 13485-certified facilities commanding premium reimbursement rates.
- Home-Based:Patient-administered exercise protocols and wearable-guided rehabilitation.
- Hospital:Inpatient surgical procedures and complex multi-ligament reconstructions.
By patient reach, telehealth is expanding most quickly. By revenue per encounter, hospital delivery retains the highest unit economics.
End User:
Application intensity varies: professional athletes demand rapid-return protocols, while recreational users prioritize cost containment and convenience access.
- Professional Athletes:Time-sensitive recovery mandates with captive team medical infrastructure. Bundesliga clubs and NBA franchises operate dedicated rehabilitation facilities with direct equipment procurement budgets, bypassing traditional distributor channels.
- Sports Teams:Organizational purchasing of preventive and therapeutic devices across roster populations. German professional football clubs standardize advanced physiotherapy protocols, creating concentrated demand for premium arthroscopy equipment.
- Recreational Users:Individual consumers accessing retail orthotics and outpatient clinic services.
- Physiotherapy Centers:Independent and hospital-affiliated rehabilitation facilities serving mixed patient populations.
By procurement concentration, sports teams lead. By absolute user base, recreational users dominate.
Application:
Maturity differentiation separates established injury recovery protocols from emerging preventive care categories with unstandardized reimbursement.
- Injury Recovery:Post-traumatic surgical and non-surgical interventions for ligament and meniscal damage. German knee rehabilitation centers and US academic medical centers drive protocol standardization, with FDA 510(k) clearance velocity compressing commercialization timelines for implantable devices.
- Preventive Care:Prophylactic bracing and biomechanical screening to reduce injury incidence. Professional sports franchises in Germany and the United States internalize these capabilities, creating captive demand for motion-sensing orthotics and AI-guided training protocols.
- Rehabilitation:Structured physiotherapy programs restoring function after surgical or non-surgical treatment.
- Pain Management:Non-operative interventions addressing chronic joint symptoms and inflammatory conditions.
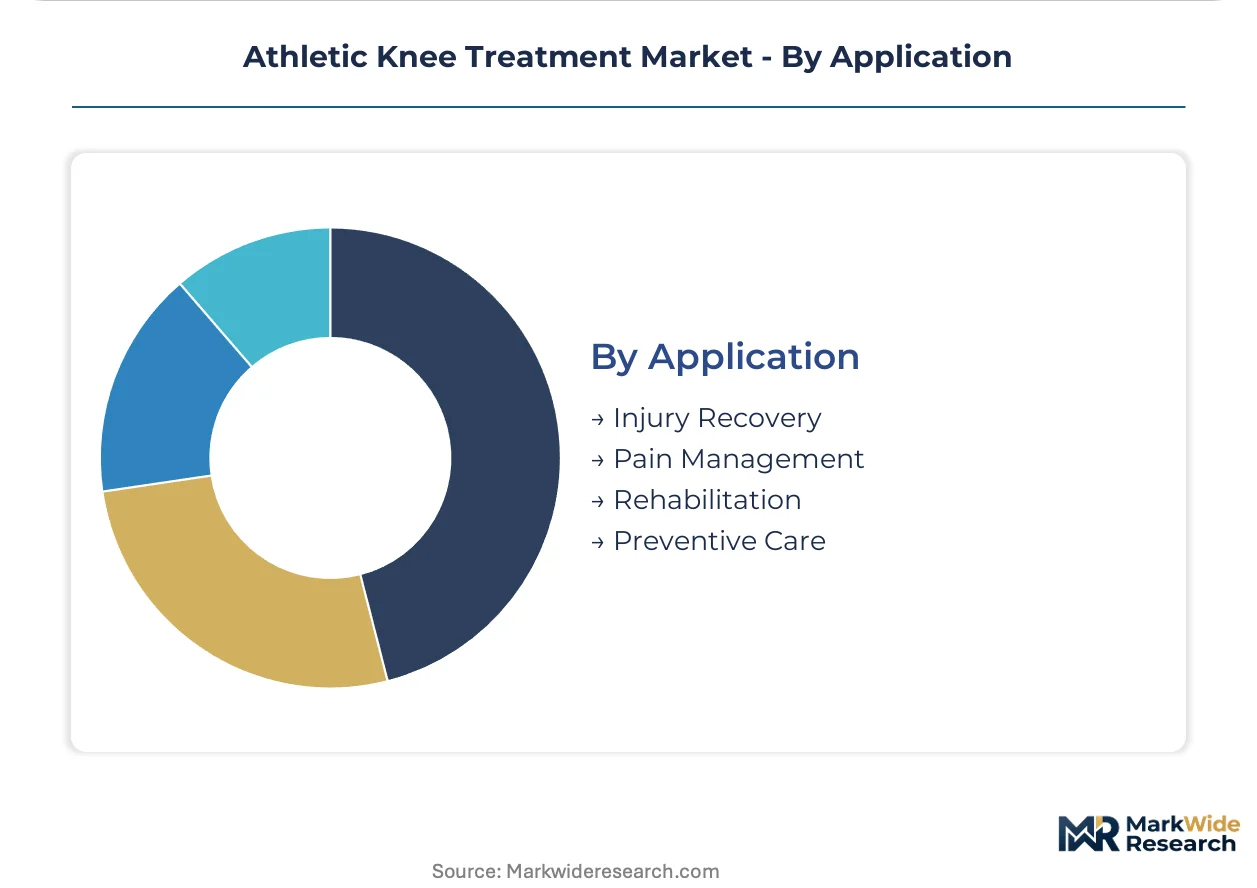
By procedure volume, injury recovery leads. By margin expansion potential, preventive care shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional sports franchises and hospital systems concentrate procurement across distinct geographic clusters. Buyer archetypes split between team-owned medical infrastructure in Germany and the United States, academic medical centers in select European markets, and emerging specialist networks in Asia-Pacific.
United States
NBA franchises and collegiate athletic programs drive demand for captive rehabilitation facilities. FDA 510(k) clearance velocity compresses commercialization timelines for implantable devices. Academic medical centers in Boston and Stanford anchor matrix-induced autologous chondrocyte implantation trials.
Germany
Bundesliga clubs operate dedicated knee treatment centers with standardized physiotherapy protocols. EU MDR post-market surveillance requirements intensify clinical follow-up obligations for implant manufacturers. Munich and Düsseldorf host concentrated arthroscopy training infrastructure serving Central European markets.
India
Tier-two cities present whitespace for arthroscopy training centers amid underdeveloped specialist infrastructure. CDSCO regulates medical device imports and domestic manufacturing under evolving quality frameworks. Mumbai and Bangalore clusters attract sports medicine equipment distribution partnerships targeting recreational user expansion.
Japan
Aging recreational athlete populations sustain demand for conservative treatment modalities. PMDA oversees orthopedic device approval with distinct clinical evidence requirements from Western regulators. Tokyo-Osaka corridor concentrates physiotherapy center networks with ISO 13485-certified facility penetration.
Australia
Australian Rules Football and rugby league franchises internalize physiotherapy capabilities. TGA medical device regulations align with international harmonization frameworks while maintaining local conformity assessment requirements. Sydney and Melbourne sports medicine clusters pilot telehealth post-operative monitoring platforms.
Athletic Knee Treatment Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with integrated sports medicine divisions. Market structure concentrates around three to five vertically integrated manufacturers controlling implant supply chains. Strategic archetypes separate premium-tier implant specialists, mid-market arthroscopy platform providers, and regenerative therapy entrants. Competitive moves center on surgeon training program expansion and ISO 13485 certification arbitrage in emerging European markets.
Among diversified orthopedic manufacturers, Stryker, Zimmer Biomet, and Arthrex occupy distinct positioning vectors. Stryker represents vertically integrated implant manufacturing with hospital system penetration. Zimmer Biomet anchors sports medicine presence through specialized arthroscopy portfolios. Arthrex exemplifies surgeon education-centric competitive positioning with training program intensity.
| Leading Market Players |
|---|
| Stryker |
| Smith & Nephew |
| Zimmer Biomet |
| Arthrex |
| Johnson & Johnson |
| Medtronic |
| CONMED |
| Enovis |
| Bauerfeind |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles for titanium alloy bar stock concentrate pricing power with German and US implant manufacturers possessing backward-integrated forging capacity, while spot-market buyers absorb volatility through quarterly cost-plus adjustments indexed to London Metal Exchange titanium pricing.
Pricing Analysis
Cost-plus contracts with London Metal Exchange titanium indexation dominate procurement for surgical implant manufacturers. Pricing stratifies across ISO 13485-certified premium tier, predicate-device standard tier, and commodity orthotic economy tier. Price erosion runs through the standard tier as cell-based therapies capture meniscal repair volume from synthetic implants. Recreational users accessing retail braces exhibit highest price sensitivity; captive Bundesliga procurement shows lowest sensitivity due to time-critical recovery mandates.
Supply Chain Analysis
Germany and the United States anchor precision titanium alloy forging and biocompatible polymer extrusion for implantable knee devices. Raw material sourcing draws from concentrated titanium sponge suppliers in Japan and Kazakhstan, plus medical-grade UHMWPE resin from Belgium and the Netherlands. Single-source vulnerability concentrates in titanium alloy bar stock qualified for FDA 510(k) predicate matching. Distribution runs through hospital purchasing committees for implants, direct franchise supply agreements for preventive braces, and retail channels for consumer orthotics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
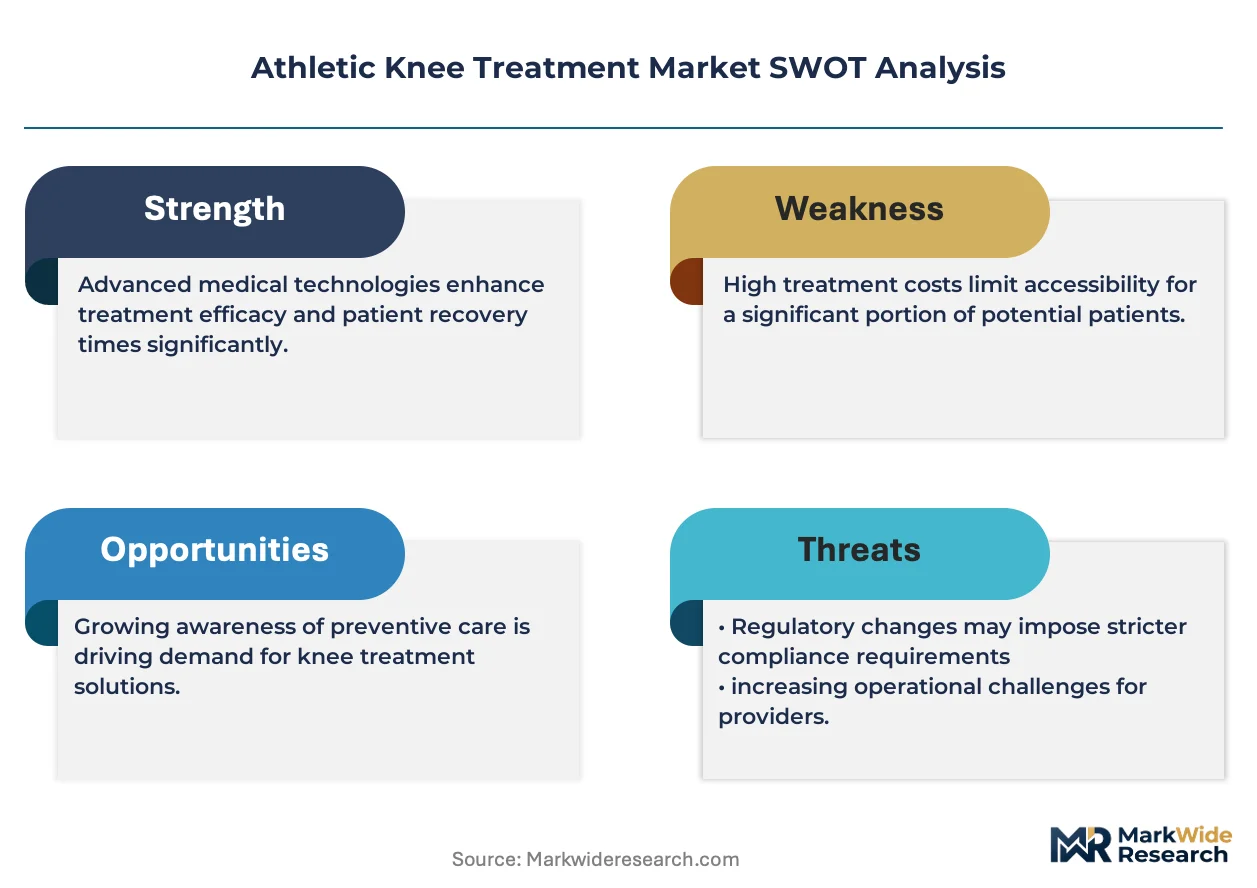
Early-cycle expansion characterizes this market as regenerative therapies displace repeat surgical interventions and professional sports franchises internalize captive rehabilitation infrastructure.
For Market Incumbents: Shield arthroscopy revenue pools by accelerating surgeon training program capacity expansion in Germany and the United States, where specialist bottlenecks limit procedure volume growth regardless of equipment availability. Deepen backward integration into titanium alloy forging to offset raw material price volatility and predicate-device matching requirements. For New Entrants and Emerging Players: ISO 13485 certification fast-tracks in emerging European markets create first-mover positioning against regional competitors lacking quality management infrastructure. Target tier-two Indian cities for arthroscopy training center partnerships, where underdeveloped specialist infrastructure creates whitespace for equipment distribution and education revenue. For Investors and Strategic Acquirers: Long-term, this sits as a biological-regeneration play because cell-based cartilage therapies are bifurcating patient selection criteria and reimbursement pathways away from mechanical replacement. Watch matrix-induced autologous chondrocyte implantation reimbursement decisions by German and US payers as the inflection signal for regenerative therapy margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device pathway compresses US commercialization timelines versus de novo review. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend European access but raise competitive barriers. |
| Hospital System Partnership | German Bundesliga medical centers and US academic hospitals anchor premium implant volume. |
| Software Companion Development | AI-guided physiotherapy protocols enable subscription-based remote monitoring revenue streams. |
| Reimbursement Strategy | Cell-based therapy coding decisions by CMS and German statutory insurers determine regenerative adoption velocity. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body filings, and hospital procurement contract disclosures preceded structured interviews with orthopedic surgeons, sports medicine physiotherapists, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from ISO certification registries, professional sports franchise medical infrastructure disclosures, and titanium alloy trade flow data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Variance decomposition across product type, delivery mode, end user, and application segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level procedure volume growth, pricing trajectory assumptions, and mix-shift toward regenerative therapies. Forecast inputs incorporated Bundesliga club medical infrastructure expansion plans, FDA 510(k) clearance velocity trends, and telehealth reimbursement policy evolution.
Decision-makers should treat outputs as directional under sustained professional sports franchise investment in captive rehabilitation facilities and stable FDA predicate device pathway access; material deviation in either assumption would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Osgood-Schlatter Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Genu Recurvatum Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Hallux Rigidus Market
Orthopedics
United States Orthopedic Braces and Support Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Orthopedic Repair Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Swollen Knee Treatment Market
Orthopedics
Global Foot Drop Treatment Market