
 Osgood-Schlatter Market | 2026-2036
Osgood-Schlatter Market Size, Share, and Industry Trends Forecast 2026-2036
Osgood-Schlatter Market Outlook
Single-source procurement of tibial tubercle braces and immobilization devices is consolidating around orthopedic distributors with direct hospital contracts. Breg leverages its established channel relationships with youth sports medicine programs to sustain premium positioning. Pfizer competes through analgesic and anti-inflammatory formulations tailored to adolescent dosing protocols. Össur anchors the European market with carbon-fiber bracing engineered for active pediatric patients.
Osgood-Schlatter disease manifests as traction apophysitis of the tibial tuberosity caused by repetitive quadriceps contraction through the patellar tendon on the secondary ossification center, typically presenting in children aged nine to fourteen during peak growth velocity. The condition demands products combining mechanical offloading with compliance-friendly designs for skeletally immature patients. Bracing and physiotherapy equipment command the deepest margin pools as parents prioritize non-surgical pathways, while pain management medications face formulary compression from generic NSAID saturation. Surgical implants occupy a narrow niche reserved for refractory cases with persistent osseous fragmentation, limiting addressable volume despite premium pricing.
FDA 510(k) clearance requirements govern tibial tubercle braces and orthopedic supports marketed in the United States, while the EU Medical Device Regulation mandates clinical evidence for pediatric Class IIa devices sold in Europe. ISO 13485 certification has become table stakes for contract manufacturers serving both markets, with notified bodies scrutinizing biocompatibility testing for prolonged skin contact in adolescent populations. Stakeholders must monitor evolving CMS coverage determinations for remote therapeutic monitoring in physical therapy, as reimbursement expansion would reshape competitive economics for digital rehabilitation platforms targeting Osgood-Schlatter home exercise programs.
Market Dynamics
Reimbursement pathway revisions under CMS and private payors are redirecting patient flows toward conservative management protocols, compressing surgical volumes while expanding brace and physiotherapy demand across pediatric orthopedic networks.
Growth Catalysts
- EU Medical Device Regulation pediatric mandates:Clinical evidence requirements for Class IIa devices are accelerating investment in skeletally-immature-specific designs, pulling innovation budgets toward compliant bracing platforms.
- Youth sports medicine center specialization:Dedicated tibial tubercle stress injury programs in Germany are creating referral concentration that standardizes diagnostic protocols and device procurement.
- Carbon-fiber composite engineering:Lightweight, compliance-friendly materials are extending daily wear tolerance among active adolescent patients, reducing treatment abandonment rates.
Market Restraints
- Generic NSAID saturation:Formulary compression on pain management medications is eroding branded analgesic margins and limiting pharmaceutical investment in adolescent-specific dosing research.
- Notified body bottlenecks:ISO 13485 certification scrutiny for prolonged skin contact biocompatibility is extending European market entry timelines for contract manufacturers.
- Surgical implant volume ceiling:Refractory case thresholds reserve premium hardware for persistent osseous fragmentation, capping addressable surgical volume regardless of pricing power.
Strategic Opportunities
- Remote therapeutic monitoring expansion:CMS coverage determination evolution for physical therapy digital platforms would reshape competitive economics for home exercise program delivery.
- Pediatric orthopedic clinic direct contracting:Single-source procurement consolidation around distributors with hospital contracts creates channel control leverage for brace and immobilization device suppliers.
- Active patient compliance engineering:Sports-optimized carbon-fiber bracing for skeletally immature athletes addresses the untreated gap between rigid medical devices and performance demands.
Industry Challenges
- Pediatric biocompatibility testing capacity:Prolonged skin contact validation for adolescent populations requires specialized toxicology expertise that contract manufacturers struggle to source.
- Orthopedic distributor consolidation:Channel concentration around direct hospital contract holders is squeezing mid-tier brace suppliers without established youth sports medicine relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osgood-Schlatter Market |
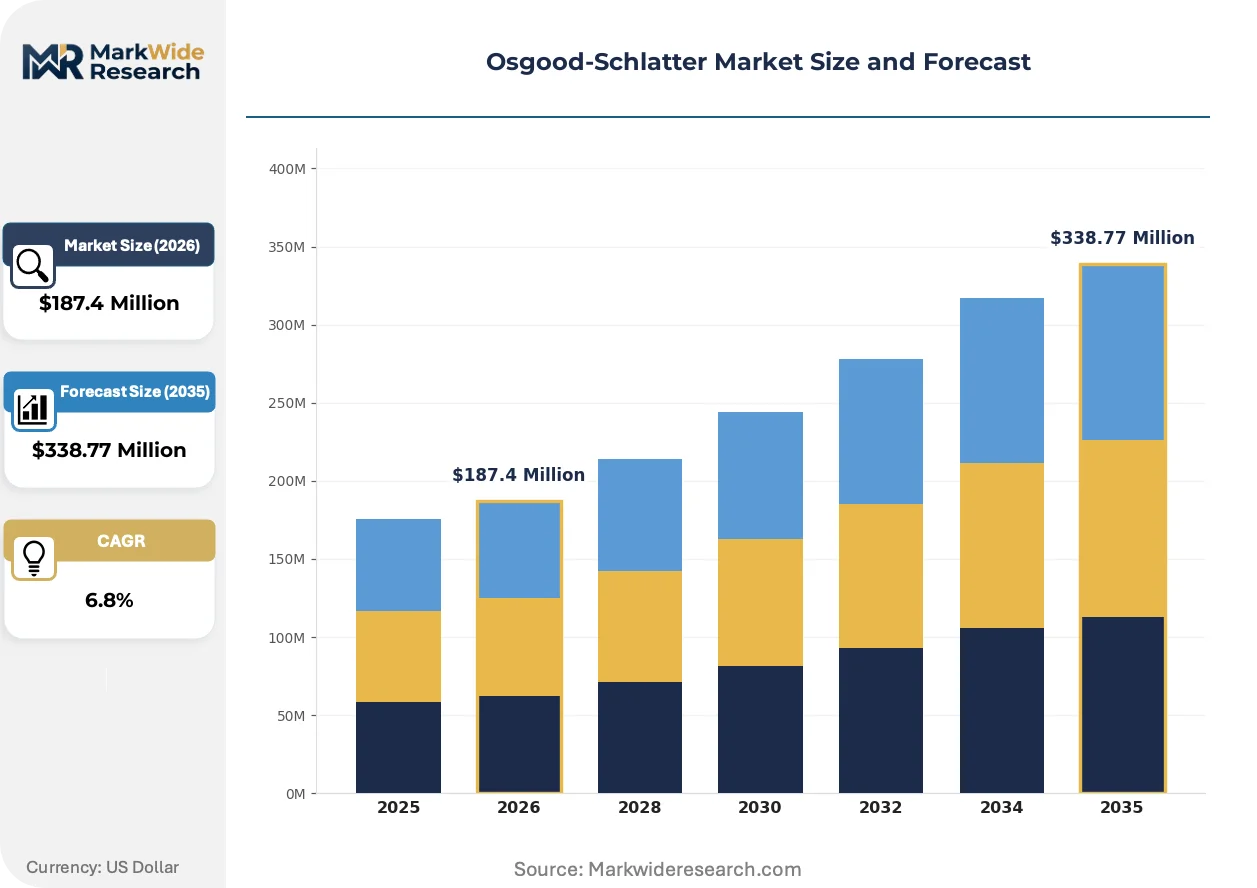
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Physical Therapy, Orthopedic Surgery, Pain Management, Rehabilitation End User: Athletes, Children, Adolescents, Healthcare Professionals Product Type: Bracing, Physiotherapy Equipment, Medication, Surgical Implants Application: Post-Injury Care, Pain Relief, Muscle Strengthening, Injury Prevention |
| Companies Covered | Breg, Daiichi Sankyo Company, Pfizer, Stryker Corporation, Össur, DJO Global, Bayer Healthcare Pharmaceuticals, AliMed, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osgood-Schlatter Market Strategic Shifts
Digital rehabilitation platforms and advanced material engineering are converging to reshape how traction apophysitis is managed outside surgical settings, with reimbursement policy accelerating the shift toward monitored home-based care.
Carbon-fiber bracing engineered for active pediatric patients is consolidating market preference among youth sports medicine programs. German specialized centers have adopted these lightweight platforms as standard protocol. The technology is consolidating procurement decisions around durability-to-weight performance metrics that rigid alternatives cannot match.
FDA 510(k) clearance pathways for tibial tubercle orthopedic supports are tightening evidentiary standards for skeletally immature populations. Device sponsors now face expanded biocompatibility documentation requirements. Pediatric brace manufacturers are responding by front-loading clinical validation budgets before submission.
Parent-driven demand for non-surgical pathways is compressing traditional specialist referral timelines. Families now initiate direct inquiries to pediatric orthopedic clinics with device preferences already formed through sports medicine network discussions. This behavioral shift concentrates most visibly in United States markets where high-deductible plans amplify out-of-pocket cost sensitivity.
Osgood-Schlatter Market Segmentation
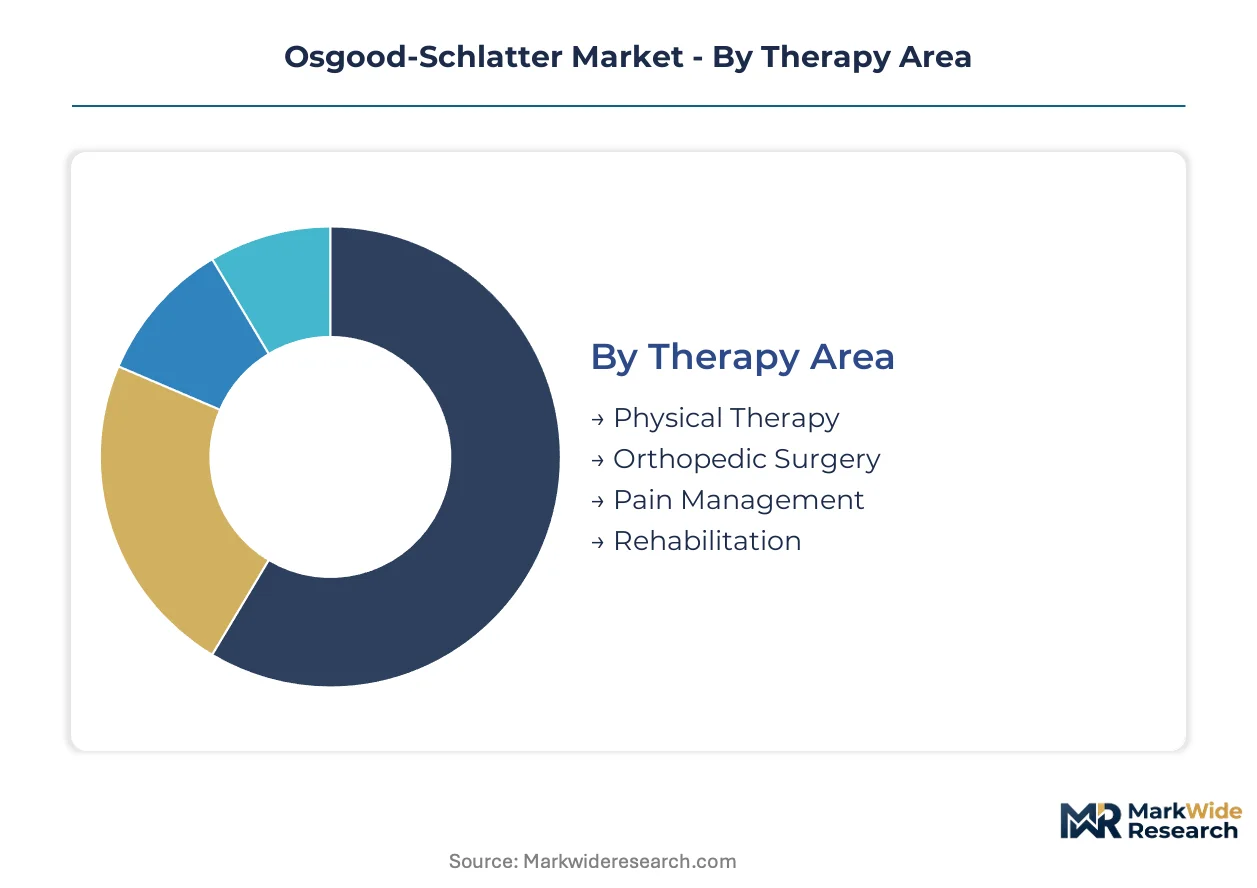
Traction apophysitis management demands precise alignment between product specifications and patient developmental stage. Segmentation reveals how procurement decisions diverge across clinical settings, with conservative protocols commanding procurement volume while surgical interventions retain premium positioning.
Therapy Area:
Reimbursement pathway structure determines which clinical disciplines capture patient volume.
- Physical Therapy:Protocols emphasize quadriceps flexibility and hamstring strengthening to reduce patellar tendon traction. CMS coverage expansion for remote therapeutic monitoring is pulling adolescent patients toward supervised home exercise programs in United States pediatric orthopedic networks.
- Orthopedic Surgery:Arthroscopic ossicle excision and tibial tubercleplasty address refractory cases with persistent fragmentation. German youth sports medicine centers have established standardized surgical thresholds that limit intervention to failure of twelve-month conservative management.
- Pain Management:Topical NSAID formulations and activity modification counseling dominate first-line intervention. Generic ibuprofen saturation has compressed branded analgesic margins across European formularies.
- Rehabilitation:Structured return-to-sport protocols integrate bracing with progressive loading regimens. Demand concentrates in Australia and Canada where sports medicine physiotherapists hold direct referral authority.
Volume sits with Physical Therapy; growth tilts toward Rehabilitation.
End User:
Compliance tolerance and anatomical maturation shape device specification requirements.
- Adolescents:Peak growth velocity patients aged twelve to fourteen require adjustable bracing accommodating rapid femoral and tibial dimension changes. Carbon-fiber platforms engineered for daily school and sports wear are gaining preference fastest among active patient populations.
- Children:Pre-pubertal patients aged nine to eleven present with atypical bilateral presentation requiring family-centered education protocols. Parental procurement decisions in United States high-deductible plans prioritize durable medical equipment with multi-season adjustability.
- Athletes:Competitive youth soccer and basketball participants demand sport-specific bracing that preserves range of motion. German specialized centers have built dedicated tibial tubercle stress injury programs for this cohort.
- Healthcare Professionals:Pediatric orthopedic surgeons and sports medicine physicians drive implant and advanced bracing prescriptions. Direct-to-clinic contracting by orthopedic distributors concentrates procurement influence among hospital-affiliated specialists.
Volume sits with Adolescents; growth tilts toward Athletes.
Product Type:
Margin structure inverts between high-volume conservative devices and low-volume surgical hardware.
- Bracing:Patellar tendon straps and hinged knee orthoses provide mechanical offloading during quadriceps contraction. ISO 13485-certified contract manufacturers in Ireland and Switzerland supply carbon-fiber composites optimized for prolonged adolescent skin contact.
- Physiotherapy Equipment:Resistance bands, balance platforms, and cryotherapy systems support home exercise program compliance. Digital rehabilitation platforms with remote monitoring capabilities are reshaping competitive economics pending CMS coverage determinations.
- Medication:Oral and topical NSAIDs address inflammatory pain without altering mechanical loading. Formulary compression has shifted prescribing toward generic ibuprofen and naproxen in United States and European markets.
- Surgical Implants:Suture anchors and tibial tubercle screws address osseous fragmentation in refractory cases. Premium pricing applies to small addressable volumes reserved for failed conservative management.
Volume sits with Bracing; growth tilts toward Physiotherapy Equipment.
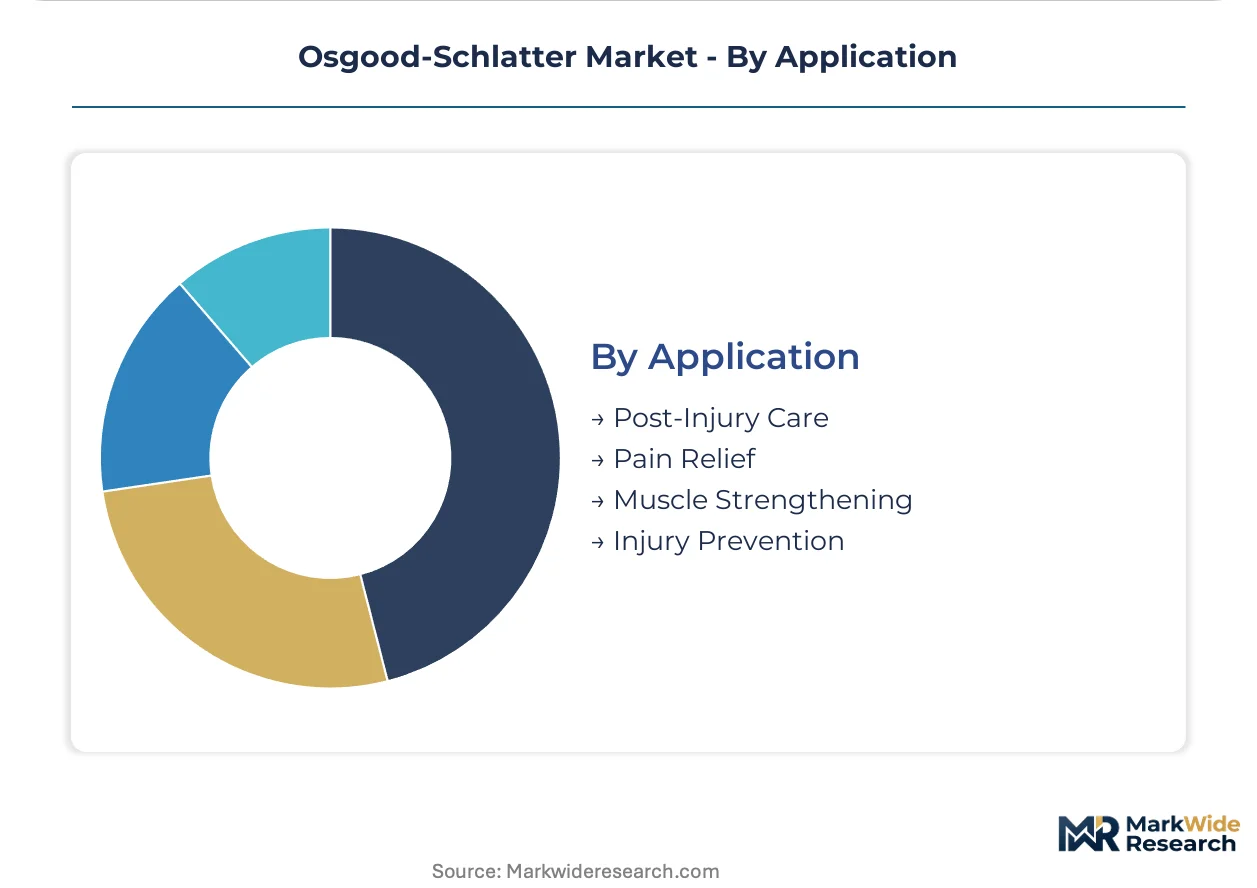
Application:
Clinical objective determines whether intervention prioritizes symptom control or functional restoration.
- Pain Relief:Immediate symptom reduction through activity modification, cryotherapy, and pharmacologic intervention. Parent-driven demand for non-surgical pathways has compressed traditional specialist referral timelines in United States markets.
- Muscle Strengthening:Eccentric quadriceps loading and hamstring flexibility protocols address biomechanical contributors. German specialized centers have standardized progressive resistance protocols as mandatory before surgical consideration.
- Post-Injury Care:Structured rehabilitation following acute exacerbation or surgical intervention. Remote therapeutic monitoring platforms are extending supervised care into home settings where geographic access to pediatric orthopedic clinics is limited.
- Injury Prevention:Pre-season screening and load management for high-risk youth athletes. Australian sports medicine programs have implemented patellar tendon load monitoring for adolescent basketball academies.
Volume sits with Pain Relief; growth tilts toward Injury Prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon-fiber composite feedstock suppliers in Germany anchor European bracing production for skeletally immature patients. Japanese precision polymer manufacturers supply patellar tendon strap substrates to Asian contract manufacturers. United States medical-grade silicone sourcing supports pediatric skin-contact device fabrication.
United States
Pediatric orthopedic clinics in Texas and California drive brace procurement volume through direct hospital contracts. CMS reimbursement pathway revisions redirect patient flows toward conservative management protocols, expanding physiotherapy device demand. The Greater Boston sports medicine corridor concentrates youth athlete diagnostic centers adopting remote therapeutic monitoring platforms.
Germany
Specialized youth sports medicine centers in Bavaria and North Rhine-Westphalia have built dedicated tibial tubercle stress injury programs. EU Medical Device Regulation pediatric mandates for Class IIa devices accelerate investment in skeletally-immature-specific bracing designs. The Stuttgart medical technology cluster hosts ISO 13485-certified contract manufacturers supplying carbon-fiber composites.
Japan
PMDA oversight of pediatric orthopedic devices maintains stringent biocompatibility documentation requirements for prolonged skin contact products. The Kanto region around Tokyo concentrates sports medicine physiotherapy practices with direct referral authority for adolescent athletes. Osaka-based polymer suppliers provide lightweight strap substrates optimized for humid climate tolerance.
Australia
Sports medicine physiotherapists in New South Wales and Victoria hold direct referral authority for Osgood-Schlatter rehabilitation protocols. TGA registration requirements for Class IIa medical devices align with ISO 13485 certification standards. Melbourne pediatric orthopedic networks implement pre-season patellar tendon load monitoring for youth basketball academies.
United Kingdom
NHS England commissioning frameworks prioritize conservative management pathways for traction apophysitis, compressing surgical volumes. The London Southeast corridor concentrates private pediatric orthopedic clinics serving high-deductile plan families seeking rapid specialist access. Midlands-based distributors consolidate single-source procurement contracts for hospital-affiliated youth sports programs.
Osgood-Schlatter Market Competitive Environment
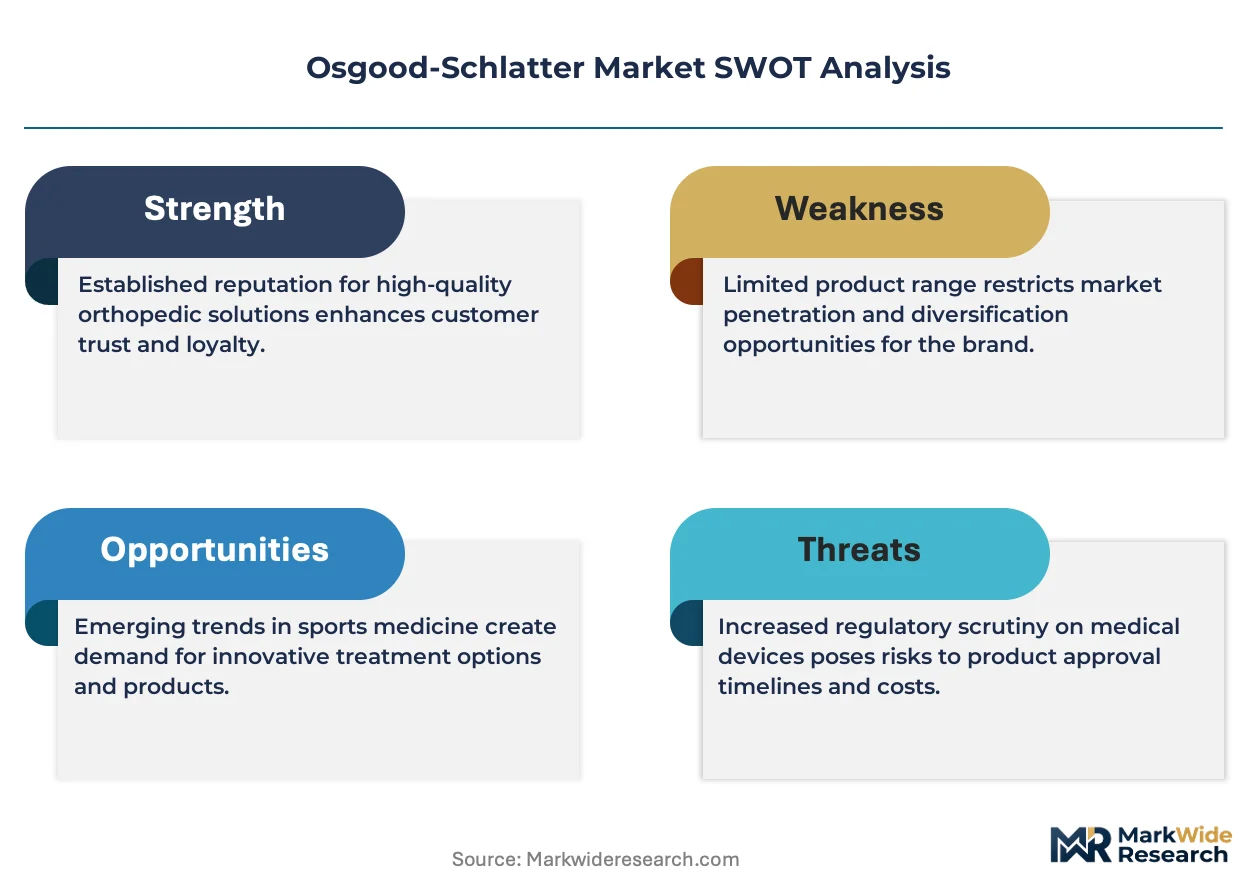
Global majors compete with regional champions across distribution channel control and pediatric-specific product portfolios. The vendor base stratifies into three tiers: multinational orthopedic conglomerates with hospital system contracts, specialized brace manufacturers with sports medicine relationships, and generic pharmaceutical suppliers facing formulary compression. Strategic moves concentrate on direct-to-clinic contracting consolidation and carbon-fiber material engineering differentiation.
Among established orthopedic device suppliers, Breg and Össur occupy positions within the premium bracing tier, while Pfizer anchors pharmaceutical analgesic supply. These three exemplify divergent competitive archetypes: Breg represents channel-integrated distributors with youth sports program relationships, Össur exemplifies European-engineered carbon-fiber specialists, and Pfizer sits within the branded NSAID segment confronting generic saturation pressures.
| Leading Market Players |
|---|
| Breg |
| Daiichi Sankyo Company |
| Pfizer |
| Stryker Corporation |
| Össur |
| DJO Global |
| Bayer Healthcare Pharmaceuticals |
| AliMed |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Captive integration into carbon-fiber composite manufacturing anchors supply security for pediatric brace producers while simultaneously defending premium pricing tiers against commodity substitution. German contract manufacturers with in-house polymer weaving capabilities command margin premiums that outsourced assembly operations in Eastern Europe cannot replicate, particularly under EU Medical Device Regulation pediatric mandates requiring documented biocompatibility validation.
Pricing Analysis
Warranty and multi-season adjustability bundling separates premium carbon-fiber bracing from unbundled economy patellar tendon straps. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and pediatric-specific biocompatibility testing investment. Cost compression in economy tiers is intensifying because generic NSAID saturation redirects patient spending toward durable medical equipment. Parental procurement decisions in United States high-deductible plans demonstrate highest price sensitivity, while German youth sports medicine centers exhibit lowest sensitivity due to institutional procurement budgets.
Supply Chain Analysis
Domestic-content mandates under EU Medical Device Regulation are reshaping sourcing toward ISO 13485-certified contract manufacturers in Ireland, Switzerland, and Germany. Raw material flows draw from Japanese precision polymer suppliers for strap substrates, German carbon-fiber weavers for composite cores, and United States medical-grade silicone providers for skin-contact interfaces. Single-source vulnerability concentrates in carbon-fiber prepreg supply from Stuttgart-area specialists. Distribution runs through orthopedic distributors with direct hospital contracts, bypassing traditional retail channels for pediatric orthopedic clinic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Medical Device Regulation pediatric mandates for Class IIa devices erect a cost-of-compliance barrier that consolidates market share among incumbent manufacturers with established notified body relationships and front-loaded clinical validation budgets.
For Market Incumbents: Cement channel control through exclusive direct-to-clinic contracting with United States pediatric orthopedic networks, defending against mid-tier brace suppliers lacking established youth sports medicine relationships. Prioritize backward integration into carbon-fiber composite weaving to secure supply continuity under German domestic-content preferences. Expand biocompatibility testing capacity for prolonged adolescent skin contact validation before notified body scrutiny intensifies. For New Entrants and Emerging Players: Begin with digital rehabilitation platforms targeting remote therapeutic monitoring reimbursement expansion, the most penetrable segment pending CMS coverage determination evolution. Target Australian sports medicine physiotherapists with direct referral authority for Osgood-Schlatter rehabilitation protocols. Pursue software-as-a-service subscription models with home exercise program delivery, avoiding capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational orthopedic conglomerates seeking pediatric-specific bracing portfolios and hospital system contract access. Long-term viability favors contract manufacturers with ISO 13485 certification and established notified body relationships over pure-play brace designers lacking regulatory infrastructure. Watch CMS coverage determinations for remote therapeutic monitoring as the inflection signal reshaping competitive economics for digital rehabilitation platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation pediatric mandates accelerate investment in skeletally-immature-specific bracing designs. |
| Hospital System Partnership | Direct-to-clinic contracting with pediatric orthopedic networks consolidates procurement influence among specialist distributors. |
| Software Companion Development | Digital rehabilitation platforms with remote monitoring capabilities reshape home exercise program delivery economics. |
| Backward Integration | In-house carbon-fiber composite weaving secures supply continuity under German domestic-content preferences. |
| Reimbursement Strategy | CMS coverage expansion for remote therapeutic monitoring redirects patient flows toward supervised conservative management. |
Study Parameters
Independent corroboration across pediatric orthopedic surgeons, sports medicine physicians, hospital procurement managers, and biomedical engineers underwrites the qualitative findings. Primary interviews with GPO contracts managers and orthopedic distributor executives combined with secondary validation from FDA 510(k) filings, CMS coverage determination databases, EU Medical Device Regulation notified body documentation, and hospital procurement contract records establish evidentiary grounding. Bottom-up patient volume modeling and top-down market sizing triangulate across conservative management protocol adoption rates and surgical intervention thresholds.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions modeled include therapy area, end user developmental stage, product type, and application objective, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derive from procedure volume projections calibrated to youth sports participation trends and reimbursement pathway evolution. Forecast inputs incorporate carbon-fiber composite cost trajectories and pediatric biocompatibility testing capacity expansion.
Underlying measurement precision varies by segment; bracing and physiotherapy equipment carry tighter precision than surgical implants given volume concentration and procurement data availability. Forecasts reflect documented assumptions regarding CMS coverage determination timelines and EU Medical Device Regulation enforcement consistency. Unanticipated regulatory acceleration or notified body capacity constraints could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Genu Recurvatum Market
Orthopedics
US Arthritis Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Anti-Osteoporosis Therapy and Fracture Healing Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Rickets Market
Orthopedics
Europe Extremity Reconstruction Market
Orthopedics
Septic Arthritis Market
Orthopedics
Orthopedics Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
ACL Reconstruction Market
Orthopedics
Kyphosis Market