
 Global Osteoarthritis Therapeutics Market | 2026-2036
Global Osteoarthritis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Osteoarthritis Therapeutics Market Foresight
Outcome-based reimbursement for maintenance dosing regimens is hardening as the dominant commercial model in osteoarthritis care. Pfizer Inc. leverages its established primary care infrastructure to sustain volume leadership in oral nonsteroidal anti-inflammatory drugs across multiple geographies. Johnson & Johnson anchors its position through orthopedic clinic partnerships that integrate device and pharmaceutical protocols. Eli Lilly and Company differentiates via biologic therapy pipelines targeting structural joint preservation rather than symptomatic relief alone.
Osteoarthritis therapeutics comprise pharmacological agents designed to modulate pain, inflammation, and structural degeneration in synovial joints, with hyaluronic acid formulations requiring specific molecular weight thresholds between 500 and 6,000 kDa to achieve viscosupplementation efficacy. These products serve the core purpose of delaying joint replacement surgery and preserving mobility in weight-bearing joints. Nonsteroidal anti-inflammatory drugs occupy the largest revenue pool due to generic availability and broad prescriber familiarity, while biologic therapies represent the fastest-expanding segment driven by unmet need for disease modification. Intra-articular injection delivery commands premium pricing relative to oral administration, reflecting procedural reimbursement codes and specialist administration requirements.
FDA, EMA, and Japan's PMDA each enforce distinct evidentiary standards for structure-modifying claims, creating fragmented development pathways that delay multi-region launches. The EU Green Deal and REACH frameworks additionally constrain excipient sourcing and manufacturing site selection for European supply. Stakeholders must monitor regulatory divergence on biomarker endpoints versus radiographic progression criteria as the central strategic variable shaping portfolio prioritization and partnership terms.
Market Dynamics
Accelerated approval pathways at FDA and EMA are compressing development timelines for disease-modifying osteoarthritis drugs, forcing sponsors to pre-negotiate biomarker endpoints before Phase II initiation.
Growth Catalysts
- EMA's PRIME designation:The scheme grants enhanced regulatory support for therapies demonstrating disease-modifying potential, reducing time-to-market for qualified candidates in European markets.
- Hospital outpatient biologic administration:Ambulatory surgical centers in the United States are expanding intra-articular injection capacity, creating procedural volume pull-through for viscosupplementation and biologic therapies.
- Japan's super-aged society:PMDA reimbursement reforms for knee osteoarthritis interventions align pharmaceutical and surgical benefit categories, accelerating physician adoption of combination therapy protocols.
Market Restraints
- Hyaluronic acid raw material concentration:Fermentation-derived sodium hyaluronate supply clusters in Chinese manufacturing hubs, exposing formulation sponsors to geopolitical supply disruptions and purity variability.
- Structure-modifying evidentiary standards:FDA requires 24-month radiographic joint space narrowing data for disease-modifying claims, doubling trial costs relative to symptomatic efficacy endpoints.
- Oral NSAID generic substitution:Broad prescriber familiarity with ibuprofen and naproxen formulations limits pricing power for novel non-opioid analgesics in primary care settings.
Strategic Opportunities
- Germany's DiGA pathway:Digital therapeutics for osteoarthritis self-management qualify for statutory health insurance reimbursement, creating companion software opportunities alongside pharmaceutical protocols.
- Combination device-drug platforms:Convergence of sustained-release hydrogel carriers with arthroscopic delivery systems enables depot formulations reducing injection frequency from quarterly to semi-annual administration.
- India's outpatient clinic expansion:Tier-2 and Tier-3 cities are developing specialist orthopedic capacity underserved by joint replacement infrastructure, creating demand for intermediate surgical delay therapies.
Industry Challenges
- Biomarker assay standardization:Urinary C-terminal cross-linked telopeptide and serum cartilage oligomeric matrix protein measurements lack harmonized reference ranges across clinical trial sites, complicating pooled analysis.
- Legacy EHR integration:Hospital systems require custom interface development to capture patient-reported outcome measures alongside procedural billing codes for value-based contract reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Osteoarthritis Therapeutics Market |
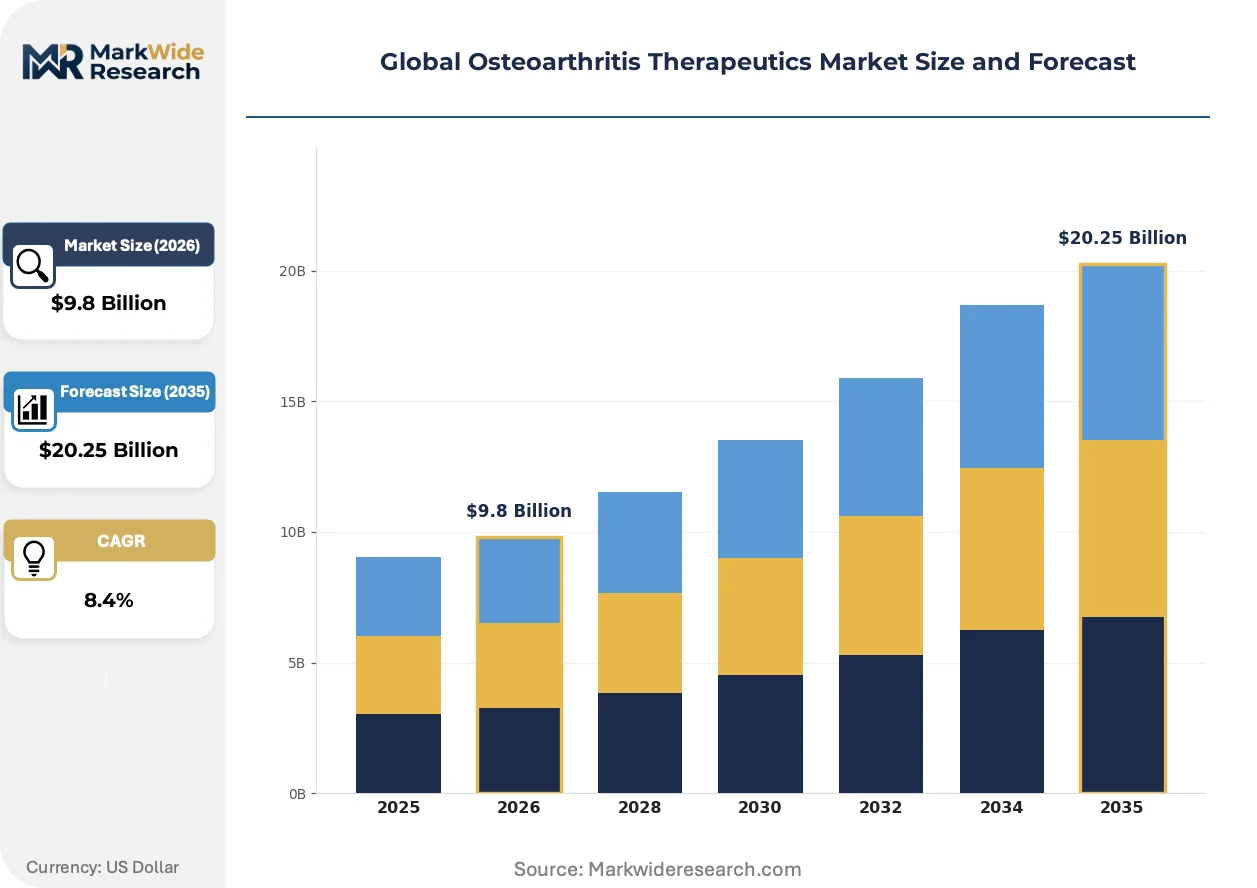
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonsteroidal Anti-Inflammatory Drugs, Corticosteroids, Hyaluronic Acid, Disease-Modifying Osteoarthritis Drugs, Biologic Therapies Therapy Area: Knee Osteoarthritis, Hip Osteoarthritis, Hand Osteoarthritis, Spine Osteoarthritis, Ankle Osteoarthritis End User: Orthopedic Clinics, Rheumatology Centers, Ambulatory Surgical Centers, Geriatric Care Facilities Delivery Mode: Oral Administration, Intra-Articular Injection, Topical Application, Transdermal Patches |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Novartis AG, AbbVie Inc., Sanofi, Bayer AG, GlaxoSmithKline plc, Eli Lilly and Company, Anika Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Osteoarthritis Therapeutics Market Shifts & Advancements
Biologic therapy pipelines are pivoting from cytokine inhibition to cartilage anabolic stimulation, reframing competitive advantage around structural preservation rather than symptomatic control.
Platelet-rich plasma formulations with defined platelet concentration thresholds are consolidating clinical trial design across academic medical centers. Orthopedic surgeons at major US teaching hospitals specify leukocyte-poor preparations at 1.5-3x baseline platelet counts, compressing protocol variability that previously confounded meta-analyses. This standardization is consolidating reimbursement negotiations around discrete CPT code categories rather than experimental therapy exemptions.
REACH Article 33 disclosure requirements for substances of very high concern are reshaping excipient sourcing strategies for European supply chains. Manufacturers must now document full supply chain provenance for hyaluronic acid fermentation media components, particularly animal-derived peptones. Small and mid-size formulation sponsors are responding by qualifying synthetic peptone alternatives and dual-sourcing fermentation capacity across non-EU jurisdictions.
Patient cost-sharing for chronic therapy regimens is compressing adherence to prescribed dosing intervals in commercial insurance plans. High-deductible health plans in the United States drive discontinuation after initial injection series, prompting specialty pharmacies to develop financial assistance navigation services. This behavioral shift is most visible in Medicare Part D enrollment patterns, where supplemental gap coverage determines persistence on hyaluronic acid maintenance protocols.
Global Osteoarthritis Therapeutics Market Segmentation
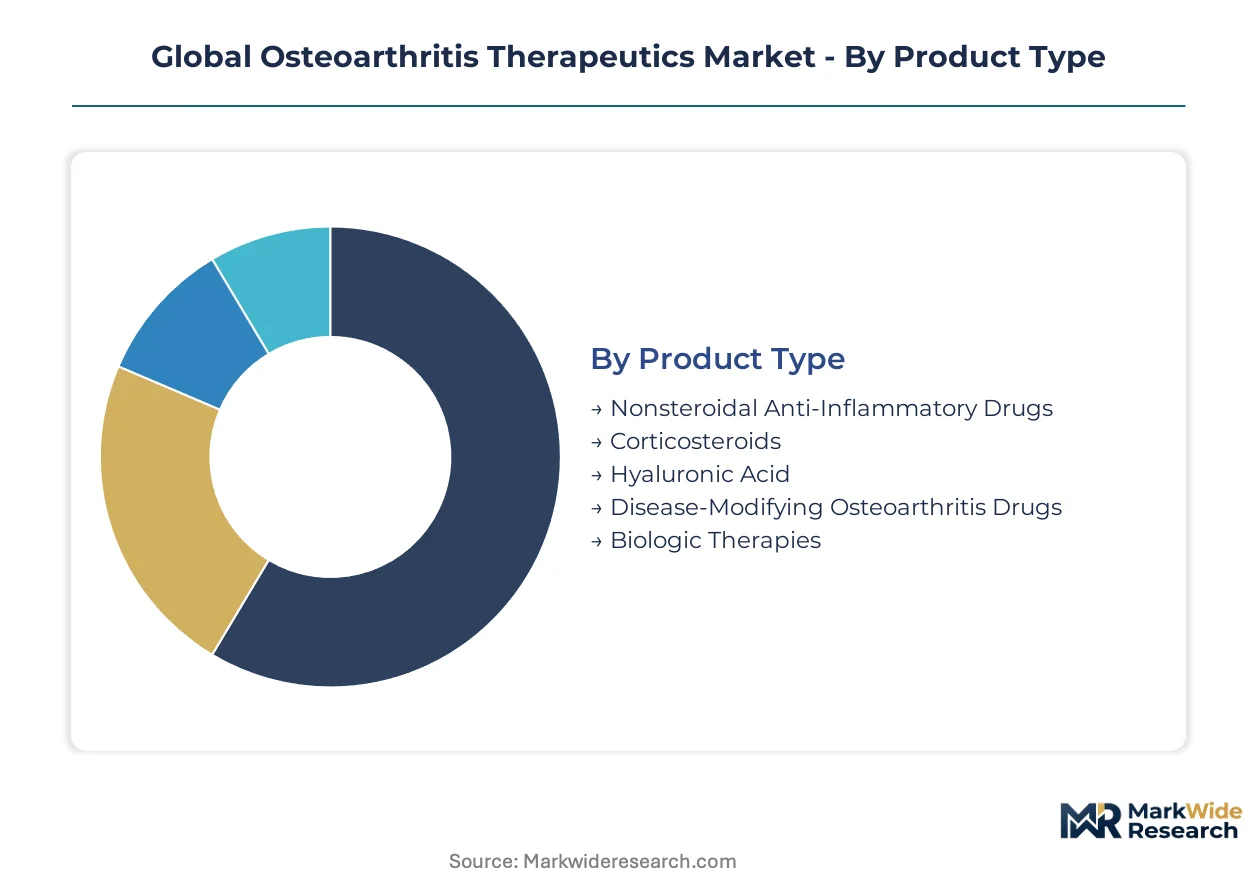
Segmentation in osteoarthritis therapeutics reveals distinct procurement patterns across product categories, with standalone oral agents dominating primary care volumes while embedded biologic systems command hospital outpatient premiums. Understanding these structural divides enables precise positioning across reimbursement tiers and prescriber workflows.
Product Type:
Integration depth varies sharply: oral NSAIDs and topical agents function as standalone prescriptions, while biologic therapies and viscosupplementation require embedded administration infrastructure.
- Nonsteroidal Anti-Inflammatory Drugs:Oral formulations of ibuprofen, naproxen, and celecoxib constitute the foundational prescription layer. Demand concentrates in United States primary care networks and German statutory health insurance formularies, constrained by generic substitution protocols that compress branded pricing power.
- Biologic Therapies:Monoclonal antibodies and cell-based interventions targeting inflammatory cytokines or cartilage anabolism represent the technology frontier. Japanese orthopedic clinics and US academic medical centers drive adoption, propelled by PMDA and FDA accelerated approval pathways for disease-modifying claims.
- Hyaluronic Acid:Viscosupplementation formulations require molecular weight thresholds between 500 and 6,000 kDa for efficacy.
- Corticosteroids:Intra-articular triamcinolone and methylprednisolone serve as intermediate intervention before surgical referral.
- Disease-Modifying Osteoarthritis Drugs:Emerging pipeline candidates target structural preservation endpoints rather than symptomatic relief alone.
Nonsteroidal Anti-Inflammatory Drugs lead volumes today; Biologic Therapies are gaining share fastest.
Therapy Area:
Cost tier segmentation governs reimbursement intensity, with large-joint interventions commanding premium procedural codes versus small-joint management protocols.
- Knee Osteoarthritis:The dominant addressable population, characterized by weight-bearing mechanical stress and established hyaluronic acid injection reimbursement. United States Medicare Part D and Japan's long-term care insurance system structure benefits around knee-specific procedural volumes.
- Hip Osteoarthritis:Surgical delay therapies face anatomical access challenges that limit intra-articular injection feasibility. German orthopedic networks and UK NHS hip preservation programs concentrate demand for oral disease-modifying candidates.
- Hand Osteoarthritis:Topical diclofenac and capsaicin formulations dominate this segment.
- Spine Osteoarthritis:Facet joint interventions and epidural approaches define the therapeutic paradigm.
- Ankle Osteoarthritis:Post-traumatic etiology predominates, with sports medicine clinics driving specialized care.
Knee Osteoarthritis captures the largest revenue pool; Hip Osteoarthritis presents the steepest expansion trajectory as disease-modifying pipelines mature.
End User:
Customer type segmentation determines procurement authority, with hospital-affiliated sites controlling biologic access versus independent clinics managing oral therapy volumes.
- Orthopedic Clinics:Physician-owned practices and hospital outpatient departments integrating device and pharmaceutical protocols. United States ambulatory surgical center joint ventures and Japan's clinic-based specialist networks concentrate procedural pull-through.
- Ambulatory Surgical Centers:Medicare-certified facilities expanding intra-articular injection capacity to capture same-day procedural reimbursement. US site-of-care shift policies accelerate volume migration from hospital settings.
- Rheumatology Centers:Academic medical center departments managing complex polyarticular presentations.
- Geriatric Care Facilities:Long-term care pharmacies and nursing home medical directors coordinate oral NSAID stewardship.
Orthopedic Clinics lead volumes today; Ambulatory Surgical Centers are climbing the fastest as site-of-care economics reshape referral patterns.
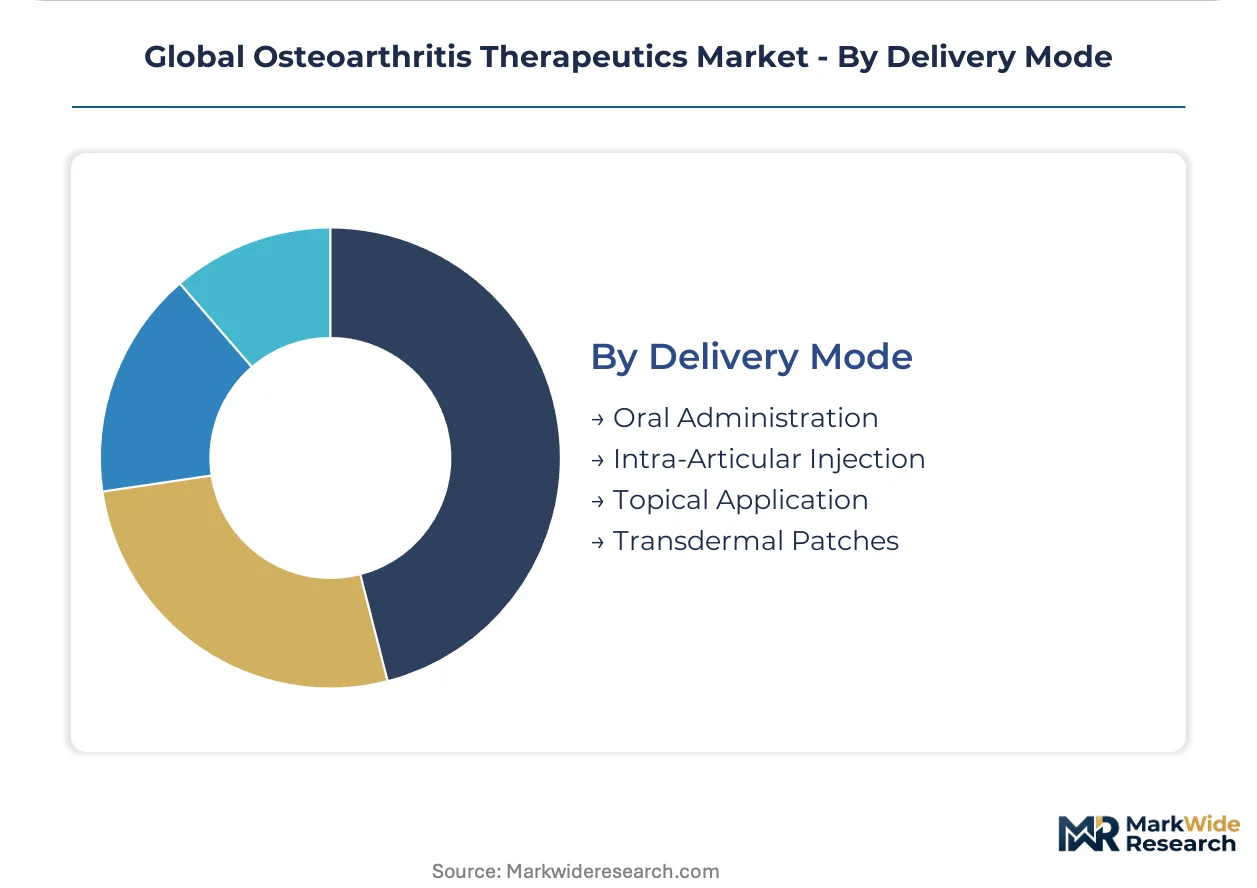
Delivery Mode:
Margin structure diverges by administration complexity, with parenteral routes capturing procedural premiums versus oral and topical commoditization.
- Intra-Articular Injection:Direct joint delivery of corticosteroids, hyaluronic acid, and biologic agents requiring ultrasound or fluoroscopic guidance. German orthopedic practices and US specialty pharmacies coordinate prior authorization navigation for these high-cost interventions.
- Oral Administration:Systemic absorption through gastrointestinal tract defines the accessibility baseline. Indian tier-2 city general practitioners and US Medicare Advantage formularies drive volume through broad prescriber familiarity.
- Topical Application:Localized diclofenac and capsaicin formulations for hand and knee surface access.
- Transdermal Patches:Sustained-release NSAID delivery systems with limited osteoarthritis-specific labeling.
Oral Administration leads volumes today; Intra-Articular Injection is gaining share fastest on procedural reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany deploy divergent reimbursement architectures for osteoarthritis interventions, while Japan's PMDA accelerates disease-modifying drug approvals faster than FDA timelines. These regulatory asymmetries fragment multi-region launch sequencing and reshape where sponsors prioritize clinical investment.
United States
Medicare Part D supplemental gap coverage determines patient persistence on hyaluronic acid maintenance protocols, with high-deductible commercial plans driving discontinuation after initial injection series. FDA requires 24-month radiographic joint space narrowing data for disease-modifying claims, doubling trial costs relative to symptomatic endpoints. Ambulatory surgical centers in Texas and Florida are expanding intra-articular injection capacity to capture same-day procedural reimbursement.
Germany
Statutory health insurance formularies concentrate demand for oral NSAIDs, while the DiGA pathway creates statutory reimbursement for digital therapeutics as pharmaceutical companions. EMA's PRIME designation grants enhanced regulatory support for disease-modifying candidates, compressing time-to-market for qualified therapies. Orthopedic networks in Bavaria and North Rhine-Westphalia integrate device and pharmaceutical protocols through clinic-hospital joint ventures.
Japan
PMDA reimbursement reforms align pharmaceutical and surgical benefit categories for knee osteoarthritis, accelerating physician adoption of combination therapy protocols. The super-aged society concentrates demand in orthopedic clinics across the Kanto and Kansai regions. Long-term care insurance structures benefits around knee-specific procedural volumes, creating predictable revenue pools for maintenance dosing regimens.
India
Tier-2 and Tier-3 cities are developing specialist orthopedic capacity underserved by joint replacement infrastructure, creating demand for intermediate surgical delay therapies. CDSCO regulatory pathways for biologic therapies remain less harmonized with FDA standards, complicating multi-region development strategies. Outpatient clinic expansion in Maharashtra and Gujarat concentrates procedural pull-through for viscosupplementation.
United Kingdom
NHS hip preservation programs concentrate demand for oral disease-modifying candidates where intra-articular injection access is anatomically constrained. NICE technology appraisals impose distinct evidentiary standards from FDA and EMA, requiring separate health economic submissions. Academic medical centers in London and the Midlands are standardizing platelet-rich plasma protocols around leukocyte-poor preparations.
Global Osteoarthritis Therapeutics Market Competitive Landscape
Top-tier vendors anchor primary care and hospital outpatient channels, while mid-cap specialists concentrate on intra-articular delivery systems and biologic formulations. The market structure reflects pharmaceutical conglomerates competing against device-drug convergence platforms and pure-play viscosupplementation sponsors. Three archetypes dominate: diversified pharma giants with NSAID volume leadership, orthopedic-focused integrators combining device and pharmaceutical protocols, and biologic pipeline developers targeting structural preservation endpoints. Competitive moves center on hospital outpatient department partnerships and site-of-care expansion into ambulatory surgical centers.
Within the diversified pharmaceutical tier, Pfizer Inc. and Johnson & Johnson occupy positions reflecting established primary care infrastructure and orthopedic clinic integration capabilities respectively. Eli Lilly and Company represents the biologic pipeline archetype, with development focus reframed around cartilage anabolic stimulation rather than cytokine inhibition. These three entities exemplify how competitive advantage is consolidating around channel control, procedural integration, and disease-modifying scientific differentiation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| AbbVie Inc. |
| Sanofi |
| Bayer AG |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Anika Therapeutics Inc. |
| Others |
Supply & Pricing Matrix
Fermentation-derived sodium hyaluronate production is displacing extraction-based methods, simultaneously compressing unit costs for viscosupplementation formulations and concentrating supply authority within Chinese bioprocessing hubs. This technological transition creates asymmetric pricing power between formulation sponsors with captive fermentation capacity and those dependent on spot market procurement.
Pricing Analysis
Capacity additions in Chinese bioprocessing hubs are reshaping price floors for hyaluronic acid raw materials, forcing tiered pricing stratification across premium molecular weight grades, standard clinical formulations, and economy generic alternatives. Price differentiation hinges on FDA master file status and REACH Article 33 compliance certification, with branded sponsors commanding premiums while Indian and Southeast Asian manufacturers compete on volume scale. Cost compression in oral NSAID categories is intensifying because of ibuprofen and naproxen generic saturation, making primary care networks the most price-sensitive buyer segment while hospital outpatient departments show lowest sensitivity due to procedural reimbursement insulation.
Supply Chain Analysis
Direct-to-hospital channels handle biologic therapy demand, while specialty pharmacy distribution manages maintenance dosing regimens for ambulatory patients. Geographic supply concentration centers on China for fermentation-derived sodium hyaluronate, the United States for monoclonal antibody fill-finish capacity, and Germany for excipient manufacturing. Raw material dependencies include animal-derived peptones for fermentation media, high-purity water systems, and chromatography resins for downstream purification. Single-source vulnerability in Chinese sodium hyaluronate clusters exposes formulation sponsors to geopolitical disruption and purity variability risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Osteoarthritis Therapeutics Market functions as a stable compounder anchored by irreversible demographic shifts toward super-aged societies in Japan, Germany, and the United States.
For Market Incumbents: To counter biologic pipeline entrants targeting structural preservation endpoints, Pfizer Inc. and Johnson & Johnson should deepen orthopedic clinic partnership networks and accelerate site-of-care expansion into ambulatory surgical centers. Vertical integration into hyaluronic acid fermentation capacity insulates margin structures from Chinese supply volatility. For New Entrants and Emerging Players: Enter via India's tier-2 and tier-3 outpatient clinic networks, where joint replacement infrastructure underdevelopment creates white-space demand for intermediate surgical delay therapies. Target combination device-drug platforms integrating sustained-release hydrogel carriers with arthroscopic delivery systems, leveraging Germany's DiGA pathway for digital therapeutic companions as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play viscosupplementation sponsors lacking disease-modifying pipeline options. Long-term viability across the analysis window favors entities with FDA or EMA accelerated approval pathway experience and established hospital outpatient department contracts. Watch PMDA reimbursement reform implementation as the signal indicating inflection toward combination therapy protocol adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA's 24-month radiographic endpoint requirement structures trial investment thresholds for disease-modifying claims. |
| Hospital System Partnership | Orthopedic clinic joint ventures in Texas and Florida secure procedural volume pull-through for intra-articular therapies. |
| Manufacturing Scale-Up | Fermentation capacity expansion in non-Chinese jurisdictions reduces REACH Article 33 supply chain concentration risk. |
| Software Companion Development | Germany's DiGA pathway enables statutory reimbursement for osteoarthritis self-management digital therapeutics. |
| Pipeline Diversification | Cartilage anabolic stimulation programs differentiate from saturated cytokine inhibition competitive sets. |
Research Methodology
Bottom-up orthopedic clinic and hospital outpatient department modeling reconciled against top-down pharmaceutical manufacturing and distribution tracking forms the analytical core. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers were validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Triangulation between prescriber-reported outcome measures and claims-based utilization patterns ensures segmentation accuracy across therapy areas and delivery modes.
Input-output matrices map patient population incidence, treatment line progression rates, and dosing persistence patterns against manufacturing capacity and pricing dynamics throughout the forecast period. Segmentation dimensions include product type, therapy area, end user, and delivery mode, with regional regulatory clusters modeled separately. CAGRs derive from elasticity-adjusted volume projections and price trajectory assumptions, incorporating PMDA reimbursement reform timing and EMA PRIME designation acceleration effects as industry-specific forecast inputs.
Inputs from FDA, EMA, and PMDA regulatory filings were available through the study window; gaps in real-world evidence for disease-modifying biomarker endpoints introduce uncertainty bands around structural preservation pipeline valuations. Forecasts reflect assumptions regarding accelerated approval pathway utilization rates, site-of-care shift velocities, and hyaluronic acid supply chain stability. Periodic stress-testing of base assumptions is recommended against biomarker assay standardization progress and hospital EHR integration adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Tendon Repair Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Europe Bone Metastasis Market
Orthopedics
Canine Orthopedics Market
Orthopedics
Septic Arthritis Market
Orthopedics
ACL Reconstruction Market
Orthopedics
US Arthritis Market
Orthopedics
Rickets Market
Orthopedics
Kyphosis Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Skeletal Deformation Correction Market