
 Europe Extremity Reconstruction Market | 2026-2036
Europe Extremity Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Extremity Reconstruction Market Analytics
Hospital procurement in Europe is fragmenting as national tender systems diverge on implant reimbursement criteria. Stryker Corporation leverages its direct-to-hospital logistics network across Germany and France. Zimmer Biomet Holdings anchors its position through specialized shoulder and ankle portfolios tailored to European orthopedic protocols. Smith & Nephew plc competes via advanced wound care integration with extremity hardware placements.
Europe extremity reconstruction encompasses surgical restoration of hand, wrist, elbow, shoulder, foot, and ankle function through metallic implants, biologic grafts, and external fixation systems, typically manufactured from titanium alloys or resorbable polymers to achieve osseointegration and load-bearing stability. The primary purpose is restoring mobility and skeletal alignment following trauma, degenerative joint disease, or congenital deformity. Titanium-based fixation devices command the deepest margin pools due to material biocompatibility and premium pricing power, while biologics represent the fastest-expanding material category as surgeons adopt bone void fillers and synthetic grafts. Ambulatory surgery centers are capturing volume share from traditional hospitals across the Netherlands and Scandinavia, reshaping end-user economics.
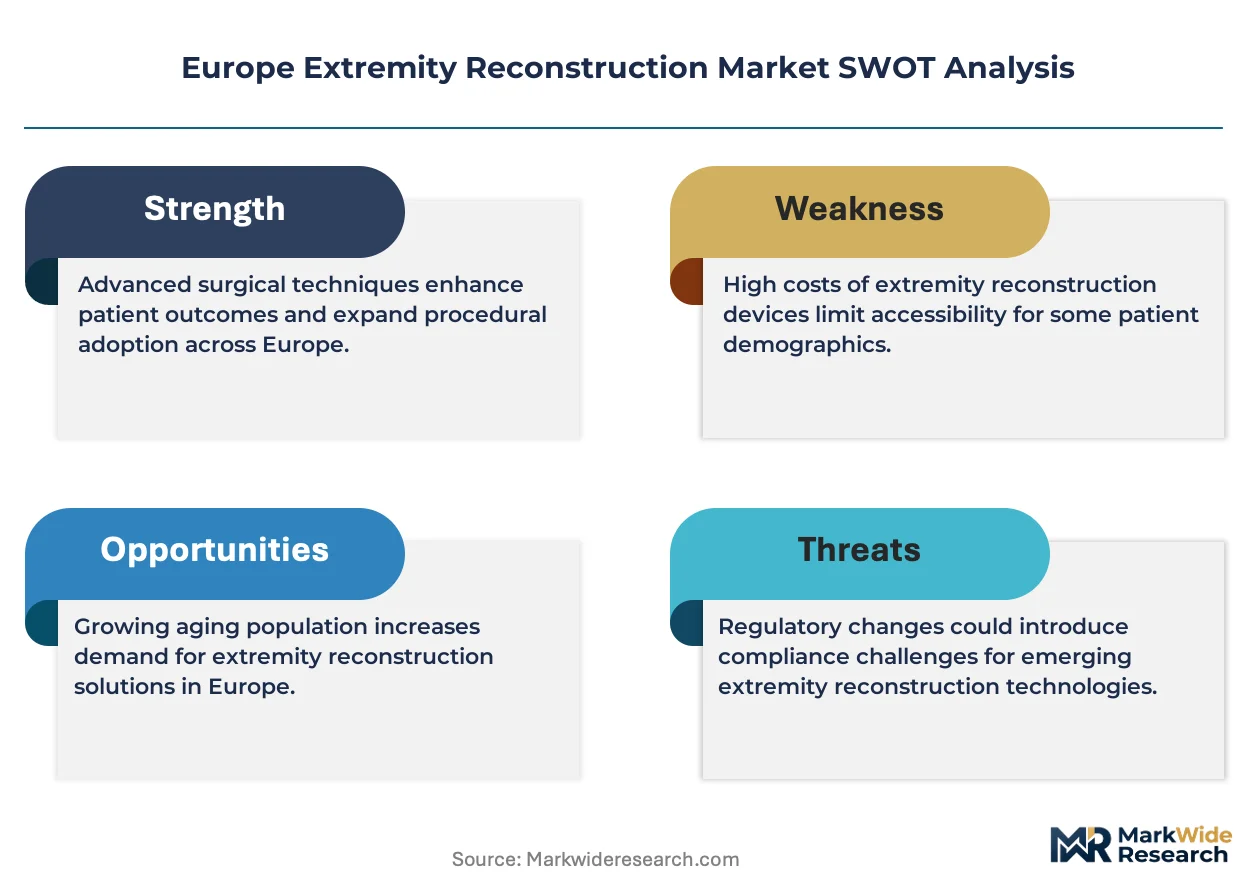
EMA medical device regulation and the EU Medical Device Regulation framework impose stringent clinical evidence requirements for implantable extremity devices, extending approval timelines but elevating barriers against lower-tier competitors. CE marking conformity assessments under notified body supervision determine market access across all EU member states. The EU Green Deal sustainability mandates are beginning to pressure manufacturers on implant packaging waste and supply chain carbon disclosure. Stakeholders must monitor how national health technology assessment bodies in Italy and Spain calibrate reimbursement for next-generation patient-specific implants versus standard off-the-shelf systems.
Market Dynamics
EU Medical Device Regulation (MDR) compliance timelines are compressing product launch cycles across European orthopedic manufacturers, forcing accelerated clinical evidence generation and notified body engagement strategies.
Growth Catalysts
- Aging demographics:France and the United Kingdom exhibit expanding patient pools requiring ankle and shoulder reconstruction procedures, driving procedural volume growth in tertiary hospitals.
- EMA biocompatibility standards:Tightened implant material requirements elevate clinical confidence in titanium-based fixation systems, accelerating surgeon adoption of premium-tier devices.
- Ambulatory surgery center expansion:Netherlands and Scandinavian healthcare systems are redirecting extremity procedures to outpatient settings, creating new volume channels for specialized implant suppliers.
Market Restraints
- Titanium alloy supply concentration:Raw material sourcing depends on a limited supplier base concentrated in Eastern European smelting operations, exposing manufacturers to input price volatility.
- MDR clinical evidence requirements:Extended approval timelines under notified body supervision delay product commercialization and increase regulatory compliance costs.
- Biologic graft substitution:Synthetic bone void fillers and resorbable polymer alternatives threaten metallic implant volume in select trauma and revision applications.
Strategic Opportunities
- Patient-specific implants:Italy and Spain present underpenetrated markets for 3D-printed, anatomically matched extremity hardware tailored to individual bone morphology.
- EU Green Deal alignment:Sustainability mandates on packaging waste and carbon disclosure create first-mover advantages for manufacturers with circular supply chain credentials.
- Wound care integration:Convergence of advanced soft-tissue management with extremity hardware placement opens bundled procedure economics in German orthopedic clinics.
Industry Challenges
- Notified body capacity constraints:CE marking assessment backlogs under MDR implementation strain product launch schedules and commercial planning.
- Surgeon training standardization:Variable adoption rates for novel fixation techniques across European training programs limit uniform procedure expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Extremity Reconstruction Market |
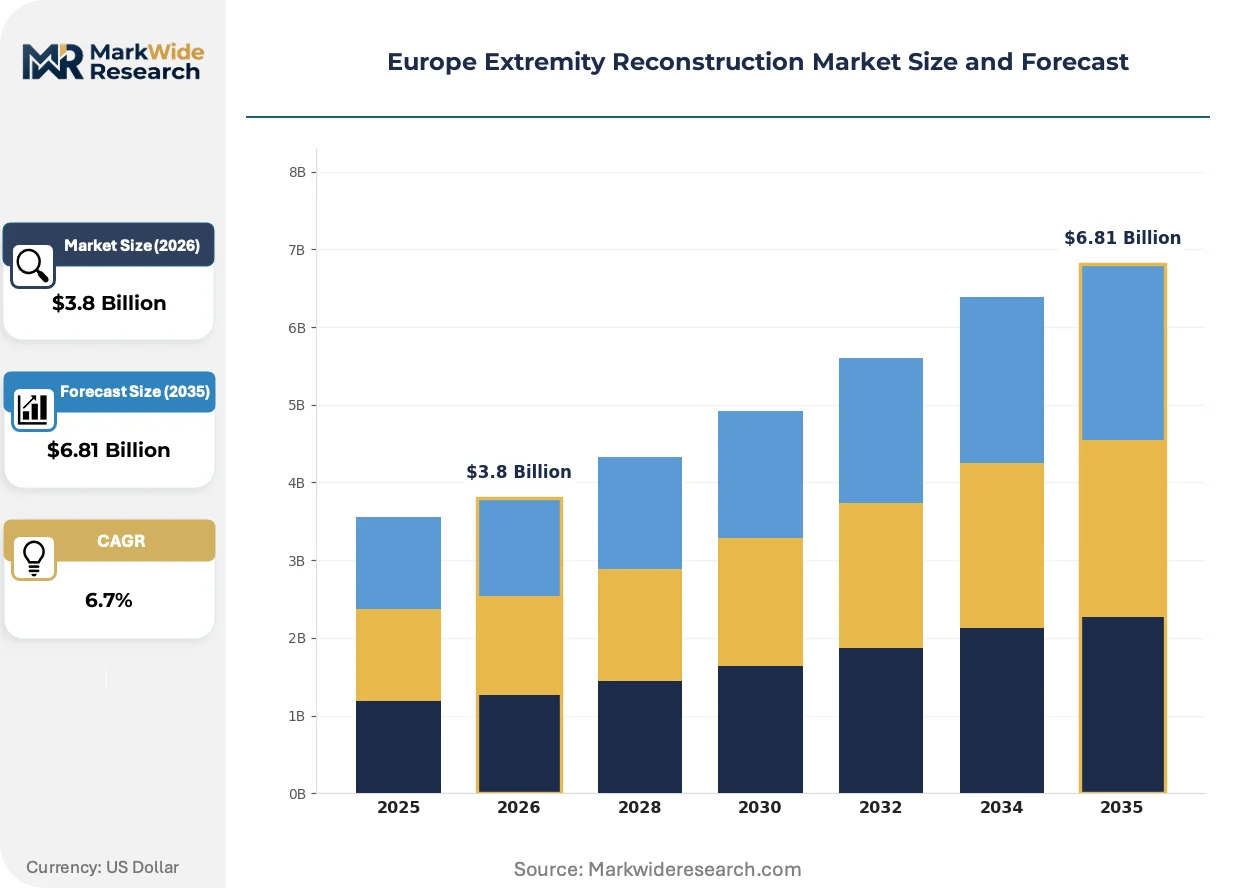
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Plates, Rods, Screws, Fixators Material: Titanium, Stainless Steel, Biologics, Polymers End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgery Centers Application: Trauma, Joint Reconstruction, Sports Injuries, Congenital Disorders |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, DePuy Synthes, Smith & Nephew plc, Integra LifeSciences Holdings Corporation, Arthrex, Acumed, Amplitude Surgical, Medtronic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Extremity Reconstruction Market Evolving Landscape
Digital surgical planning tools and resorbable material platforms are restructuring how European orthopedic teams approach extremity reconstruction, compressing traditional hardware lifecycles.
Patient-specific 3D-printed titanium implants is collapsing the gap between off-the-shelf inventory and anatomical precision requirements. German university hospitals are adopting these systems for complex revision cases within eighteen-month procurement cycles. The technology is collapsing conventional inventory models by eliminating size-matching uncertainty and reducing operative time.
EU Green Deal sustainability mandates are pressuring manufacturers to disclose supply chain carbon intensity and eliminate single-use implant packaging. Orthopedic device producers must redesign sterilization protocols and logistics networks to satisfy emerging environmental audit requirements. German and French procurement authorities are now weighting sustainability scores in tender evaluations for extremity fixation contracts.
Direct-to-hospital logistics partnerships are replacing traditional distributor intermediaries across German and French procurement networks. Specialized orthopedic suppliers are building captive delivery infrastructure to secure tender positioning and capture ambulatory surgery center volume. This channel compression is most visible in Bavaria and Rhône-Alpes, where regional hospital alliances consolidate purchasing power.
Europe Extremity Reconstruction Market Segmentation
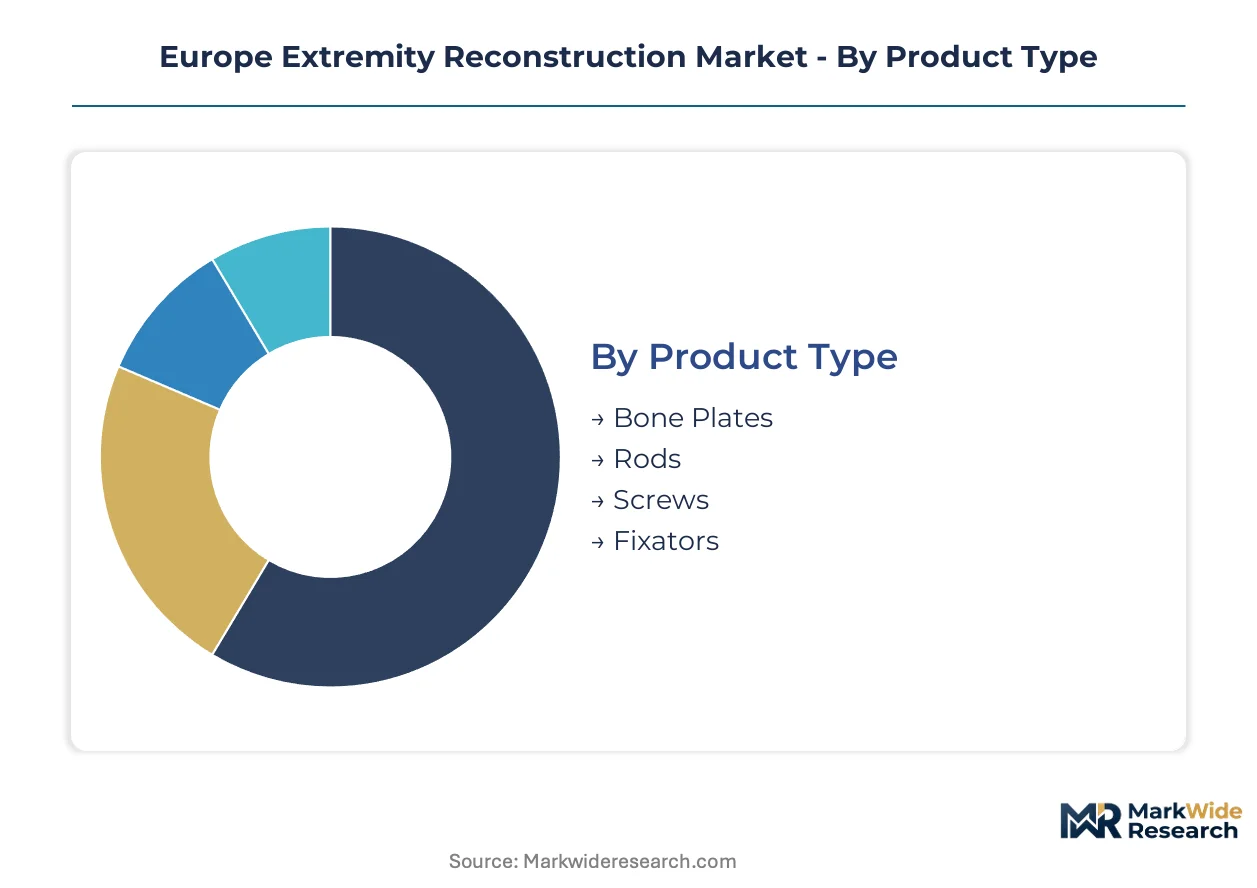
Segmentation in extremity reconstruction reveals divergent procurement rhythms across hardware categories, with metallic implants cycling through tender renewals faster than biologic alternatives. Material composition and end-user channel selection determine margin capture and regulatory exposure for suppliers across European markets.
Product Type:
Inventory velocity varies sharply across fixation hardware, with trauma screws turning over fastest while external fixators linger longest in hospital supply chains due to lower procedural frequency.
- Bone Plates:Anatomically contoured titanium or stainless steel constructs bridging fracture fragments through cortical screw fixation. German trauma centers drive demand for locking compression plates as EMA biocompatibility standards harden material specifications.
- Screws:Cortical, cancellous, and locking screw variants in diameters from 1.5mm to 7.3mm for fragment stabilization. French orthopedic clinics are expanding cannulated screw volumes for minimally invasive ankle fracture repair.
- Rods:Intramedullary nails for long-bone stabilization, typically titanium alloy with proximal/distal interlocking capability. United Kingdom hospitals concentrate demand for tibial and femoral nail systems in level-one trauma centers.
- Fixators:External ring or unilateral frames for complex fracture management and limb lengthening. Italian and Spanish markets show underpenetration of circular frame technology relative to Northern Europe.
Screws dominate installed base through sheer procedural volume. Bone plates are where expansion concentrates as complex trauma and revision cases climb.
Material:
Cost tiers separate clearly across material classes, with titanium commanding premium positioning while polymers and biologics compete on differentiated clinical outcomes rather than price parity.
- Titanium:Alpha-beta alloys delivering superior strength-to-weight ratios and osseointegration properties. Netherlands ambulatory surgery centers are standardizing titanium fixation for outpatient extremity procedures.
- Biologics:Demineralized bone matrix, synthetic grafts, and cellular bone matrices for void filling and fusion enhancement. United Kingdom orthopedic clinics are expanding biologic adjunct use in complex ankle arthrodesis cases.
- Stainless Steel:316L and 22Cr-13Ni-5Mn formulations for cost-sensitive trauma applications with adequate corrosion resistance. German procurement tenders still specify stainless alternatives for high-volume, budget-constrained hospitals.
- Polymers:Resorbable poly-L-lactic acid and polyglycolic acid constructs for pediatric applications and temporary fixation. Scandinavian markets show expanding adoption of resorbable interference screws in ligament reconstruction.
Titanium dominates installed base through premium hardware penetration. Biologics are where expansion concentrates as surgeons seek alternatives to autograft harvesting.
End User:
Channel economics fragment sharply across care settings, with ambulatory surgery centers capturing margin through compressed procedure cycles while rehabilitation centers drive recurring consumable demand.
- Hospitals:Tertiary and secondary acute care facilities performing complex trauma and revision extremity reconstruction. France and the United Kingdom concentrate hospital-based procedural volume in regional trauma networks.
- Ambulatory Surgery Centers:Outpatient facilities in the Netherlands and Scandinavia performing closed reductions and simple fracture fixations. These centers are reshaping procurement through direct manufacturer contracting.
- Orthopedic Clinics:Specialized private practices performing diagnostic arthroscopy and minor extremity procedures. German orthopedic clinics are expanding procedure volumes as regional hospital alliances fragment purchasing.
- Rehabilitation Centers:Post-acute facilities managing hardware removal and functional recovery protocols. Italian rehabilitation networks are integrating with orthopedic clinics for bundled care pathways.
Hospitals dominate installed base through trauma case concentration. Ambulatory surgery centers are where expansion concentrates as healthcare systems redirect low-acuity volume.
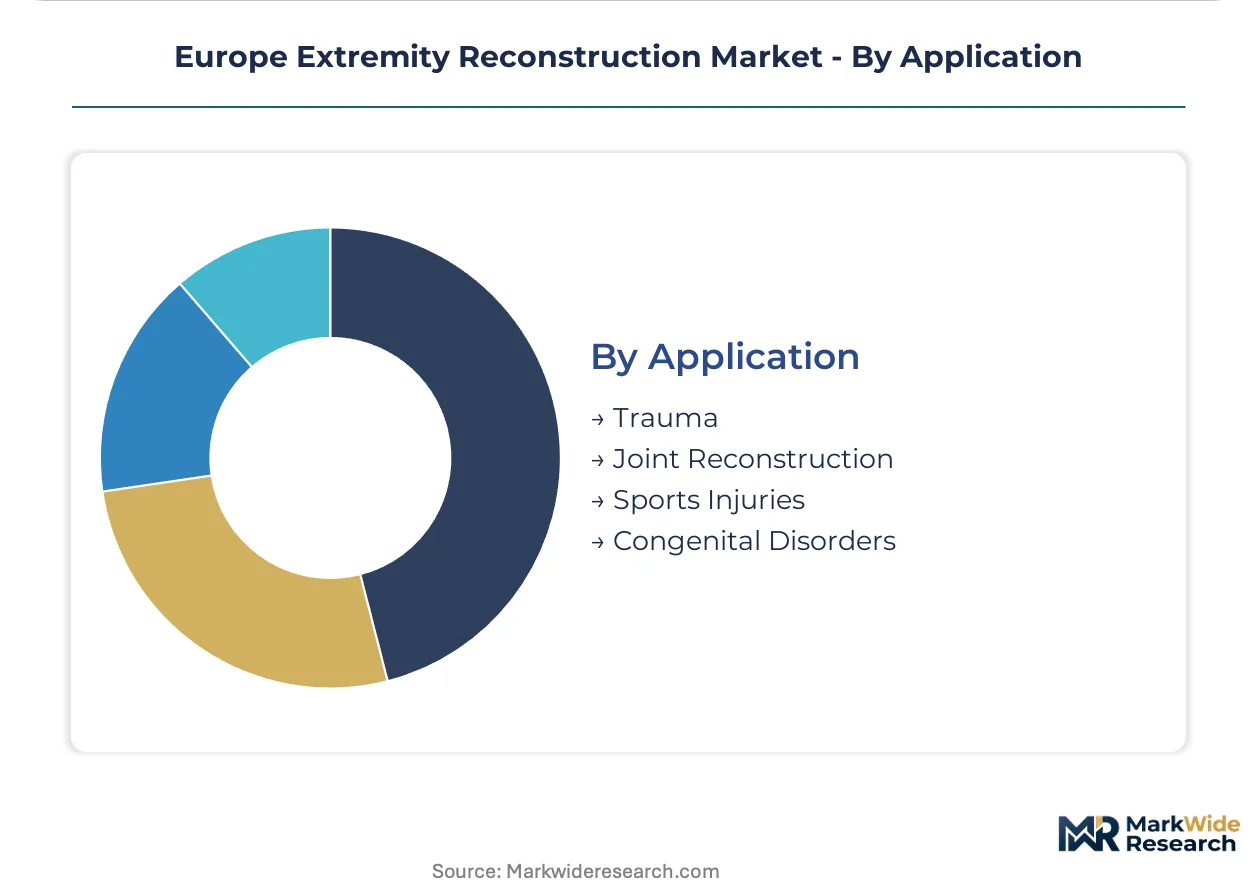
Application:
Procedure maturity separates trauma applications, now commoditized in many European markets, from emerging demand in sports injury reconstruction where technique evolution sustains premium pricing.
- Trauma:Acute fracture management through open reduction and internal fixation. German and French trauma networks concentrate demand for polytrauma extremity stabilization hardware.
- Joint Reconstruction:Ankle arthrodesis, shoulder hemiarthroplasty, and total wrist replacement procedures. United Kingdom hospitals are expanding ankle replacement volumes as implant longevity improves.
- Sports Injuries:Ligament reconstruction, osteochondral repair, and instability correction in athletic populations. Netherlands and Scandinavian markets show expanding ACL and ankle ligament procedure volumes.
- Congenital Disorders:Limb length discrepancy correction and deformity reconstruction in pediatric and adult populations. Italian and Spanish markets present underpenetrated opportunities for specialized pediatric fixation systems.
Trauma dominates installed base through sheer procedural frequency. Joint reconstruction is where expansion concentrates as aging demographics and implant durability improvements align.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network positions Germany as the distribution backbone for extremity implants moving into Central and Eastern European markets. EMA notified body concentration in Frankfurt and Amsterdam accelerates CE marking throughput for manufacturers targeting the region.
Germany
Bavarian university hospitals in Munich and Erlangen are expanding patient-specific 3D-printed titanium implant programs for complex revision surgeries. The EU Medical Device Regulation implementation timeline compresses product launch cycles, forcing accelerated clinical evidence generation. The Rhône-Alpes freight corridor integration allows same-day implant delivery to orthopedic clinics across Baden-Württemberg.
France
Aging demographics in the Île-de-France region are driving ankle and shoulder reconstruction volumes in Parisian tertiary hospitals. ANSM post-market surveillance requirements tighten adverse event reporting obligations for implantable extremity devices. The Lyon-Grenoble medical technology cluster concentrates demand for biologic graft adjuncts in sports injury reconstruction.
United Kingdom
NHS England regional trauma networks are consolidating extremity procedure purchasing across level-one centers in London, Birmingham, and Manchester. The Medicines and Healthcare products Regulatory Agency transition from EU CE marking to UKCA certification creates dual regulatory pathways for manufacturers. Scottish orthopedic centers in Glasgow and Edinburgh are expanding ambulatory surgery capacity for simple fracture fixations.
Netherlands
Healthcare system reforms are redirecting low-acuity extremity procedures to outpatient facilities in the Randstad conurbation. The Dutch Healthcare Authority's bundled payment pilots for ankle arthrodesis reshape procurement economics for implant suppliers. Eindhoven's medical device manufacturing ecosystem supports rapid-prototype production for patient-matched fixation hardware.
Italy
Underpenetrated markets in Lombardy and Emilia-Romagna present expansion opportunities for specialized pediatric fixation systems in congenital deformity correction. The Italian Medicines Agency's health technology assessment processes calibrate reimbursement for next-generation implants versus standard systems. Milan's orthopedic research hospitals are adopting digital surgical planning tools for complex trauma cases.
Europe Extremity Reconstruction Market Competitive Landscape
On the supply side, the industry is consolidating around diversified orthopedic conglomerates with captive logistics infrastructure and specialized mid-cap innovators with focused extremity portfolios. Three strategic archetypes dominate: integrated multinationals with direct-to-hospital distribution networks, biologics-integrated wound care specialists, and patient-specific implant pure-plays leveraging additive manufacturing. Competitive moves concentrate on M&A to acquire 3D-printing capabilities and strategic partnerships with ambulatory surgery center chains to secure volume commitments.
Within the integrated multinational tier, Stryker Corporation and Zimmer Biomet Holdings exemplify supply-side consolidation through captive European logistics networks. Smith & Nephew plc occupies a distinct position bridging advanced wound care with extremity hardware placement, representing the biologics-integrated archetype. These three companies anchor the competitive structure, with Stryker and Zimmer Biomet competing through scale-driven tender positioning while Smith & Nephew differentiates via procedure bundling economics in German orthopedic clinics.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings |
| DePuy Synthes |
| Smith & Nephew plc |
| Integra LifeSciences Holdings Corporation |
| Arthrex |
| Acumed |
| Amplitude Surgical |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Titanium alloy supply concentration in Eastern European smelting operations exposes manufacturers to simultaneous input cost volatility and procurement tier compression, forcing premium-tier pricing spreads to widen while economy-tier margins erode under MDR compliance cost absorption.
Pricing Analysis
Volume-discount tiering structures separate hospital procurement consortiums from ambulatory surgery center direct contracts across German and French markets. Pricing stratifies across premium, standard, and economy tiers based on EMA biocompatibility certification grade and sterilization protocol complexity. Cost compression in the economy tier is intensifying because notified body capacity constraints delay CE marking for budget-tier manufacturers. Ambulatory surgery centers in the Netherlands exhibit the highest price sensitivity due to bundled payment pressure, while Bavarian university hospitals tolerate premium positioning for patient-specific 3D-printed implants.
Supply Chain Analysis
Tariff exposure between Eastern European raw material suppliers and Western European finishing operations dominates supply chain risk calculus for titanium alloy sourcing. Manufacturing concentration centers on Germany, France, and Switzerland for precision machining, while primary titanium sponge production rests on Ukrainian and Russian feedstock channels now subject to trade restriction uncertainty. Distribution runs through direct-to-hospital logistics partnerships replacing traditional distributor networks across Rhône-Alpes and Baden-Württemberg regional hospital alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through MDR clinical evidence requirements creates insurmountable switching costs for hospital procurement committees locked into validated supplier relationships.
For Market Incumbents: Pre-empt biologic graft substitution threats by acquiring synthetic bone void filler capabilities or securing exclusive distribution partnerships with resorbable polymer innovators. Deepen backward integration into titanium alloy sourcing through long-term offtake agreements with Eastern European smelters to isolate margin exposure from commodity volatility. Channel control through captive logistics infrastructure in Bavaria and Rhône-Alpes remains the priority defensive lever. For New Entrants and Emerging Players: Italian and Spanish pediatric fixation markets present underpenetrated white-space opportunities where specialized 3D-printed implant programs can bypass entrenched tender relationships. Target congenital deformity correction applications in Lombardy rehabilitation networks where bundled care pathway integration offers a direct go-to-market angle. Partner with Eindhoven rapid-prototype manufacturers to compress product development cycles for patient-matched hardware. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating the value of notified body relationships and clinical evidence libraries over pure technology assets. Five-to-ten year viability favors targets with established CE marking portfolios and ambulatory surgery center volume commitments. The signal to watch is Italian Medicines Agency reimbursement calibration for patient-specific implants versus standard systems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Notified body engagement accelerates product launch timelines under MDR compression. |
| Hospital System Partnership | Direct contracting with German regional alliances secures tender positioning. |
| Backward Integration | Captive titanium alloy sourcing isolates margin exposure from Eastern European volatility. |
| Software Companion Development | Digital surgical planning tools differentiate patient-specific implant offerings. |
| Reimbursement Strategy | Health technology assessment alignment in Italy and Spain unlocks premium pricing. |
Research Methodology
A spread of perspectives from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions through structured primary interviews validated against secondary sources including EMA device registration databases, EU tender documentation, and hospital procurement records. Bottom-up volume estimates from procedure frequency data triangulated against top-down manufacturer revenue allocations across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon, modeling segmentation dimensions across product type, material composition, end-user channel, and application category. CAGRs derived from historical procedure growth trajectories adjusted for MDR implementation lag effects and ambulatory surgery center expansion rates. Industry-specific inputs incorporated notified body capacity constraints and EU Green Deal sustainability mandate compliance costs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by patient-specific implant pure-plays or biologics-integrated wound care specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Podiatry Services Market
Orthopedics
Elbow Stiffness Market
Orthopedics
Skeletal Deformation Correction Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Tendon Repair Market
Orthopedics
Osgood-Schlatter Market
Orthopedics
Orthopedics Market
Orthopedics
Plantar Fasciitis Market
Orthopedics
Osteopenia Treatment Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Rickets Market
Orthopedics
Canine Orthopedics Market