
 Osteopenia Treatment Market | 2026-2036
Osteopenia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Osteopenia Treatment Market Analytics
The geriatric endocrinology specialist workforce is collapsing across multiple OECD health systems, tightening patient access to bone density diagnostics and specialty referrals. Novartis AG leverages its entrenched bisphosphonate manufacturing infrastructure to sustain supply continuity amid this bottleneck. Eli Lilly and Company anchors its competitive stance through differentiated anabolic therapy pipelines targeting high-fracture-risk cohorts.
Osteopenia treatment encompasses pharmacological and nutritional interventions that elevate bone mineral density above osteoporosis thresholds, with bisphosphonates functioning as nitrogen-containing pyrophosphate analogs that inhibit osteoclast-mediated bone resorption. Oral bisphosphonates dominate volume consumption across hospital and clinic channels, while injectable delivery modes capture premium positioning in long-term care facilities where adherence compliance governs outcomes. The geriatrics therapy area commands the largest patient pool, though endocrinology-directed protocols concentrate margin capture through specialist gatekeeping.
FDA oversight of bone turnover biomarker endpoints shapes Phase III trial design for novel anabolic agents, while EMA's MDR framework governs implantable diagnostic devices used in companion screening. Japan's PMDA accelerates Sakigake-designated pathways for osteoporosis-adjacent therapies, compressing development timelines for osteopenia indications. Stakeholders must monitor how reimbursement authorities in Germany, the United States, and Japan calibrate bone density scan coverage against pharmacoeconomic thresholds for preventive intervention.
Market Dynamics
The osteopenia treatment market pivots on a fundamental supply-demand asymmetry: geriatric endocrinology specialist availability is contracting across OECD health systems while postmenopausal patient volumes expand, forcing care delivery toward hospital-based protocols and injectable formulations that reduce specialist touchpoints.
Growth Catalysts
- PMDA Sakigake Pathways:Japan's accelerated approval track compresses development timelines for osteoporosis-adjacent therapies, drawing pipeline investment toward osteopenia indications.
- Bisphosphonate Manufacturing Scale:Entrenched nitrogen-containing pyrophosphate analog production infrastructure sustains supply continuity amid workforce bottlenecks in bone density diagnostics.
- Hospital Channel Concentration:Postmenopausal women in tertiary care settings drive volume adoption of long-acting injectable formulations where adherence compliance governs outcomes.
Market Restraints
- Specialist Workforce Collapse:The geriatric endocrinology talent pipeline is narrowing across Germany, the United States, and Japan, restricting patient access to bone mineral density testing.
- Reimbursement Calibration Lag:German, US, and Japanese reimbursement authorities apply divergent pharmacoeconomic thresholds for preventive bone density scan coverage, fragmenting market access.
- Oral Formulation Adherence Failure:Daily oral bisphosphonate regimens suffer from high discontinuation rates in outpatient settings, compressing real-world effectiveness.
Strategic Opportunities
- Long-Term Care Facility Penetration:Injectable delivery modes capture premium positioning in US nursing facilities where medication administration compliance determines formulary placement.
- Anabolic Agent Pipelines:Novel therapies targeting high-fracture-risk cohorts differentiate above commoditized bisphosphonate baselines through bone turnover biomarker endpoints.
- Companion Diagnostic Integration:Implantable screening devices governed by EMA's MDR framework create bundled protocol opportunities in European hospital systems.
Industry Challenges
- Phase III Endpoint Standardization:FDA oversight of bone turnover biomarker validation creates protocol complexity and timeline uncertainty for novel anabolic submissions.
- Legacy System Interoperability:Bone mineral density imaging infrastructure in US and German hospitals requires costly integration with electronic health record systems for seamless referral workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteopenia Treatment Market |
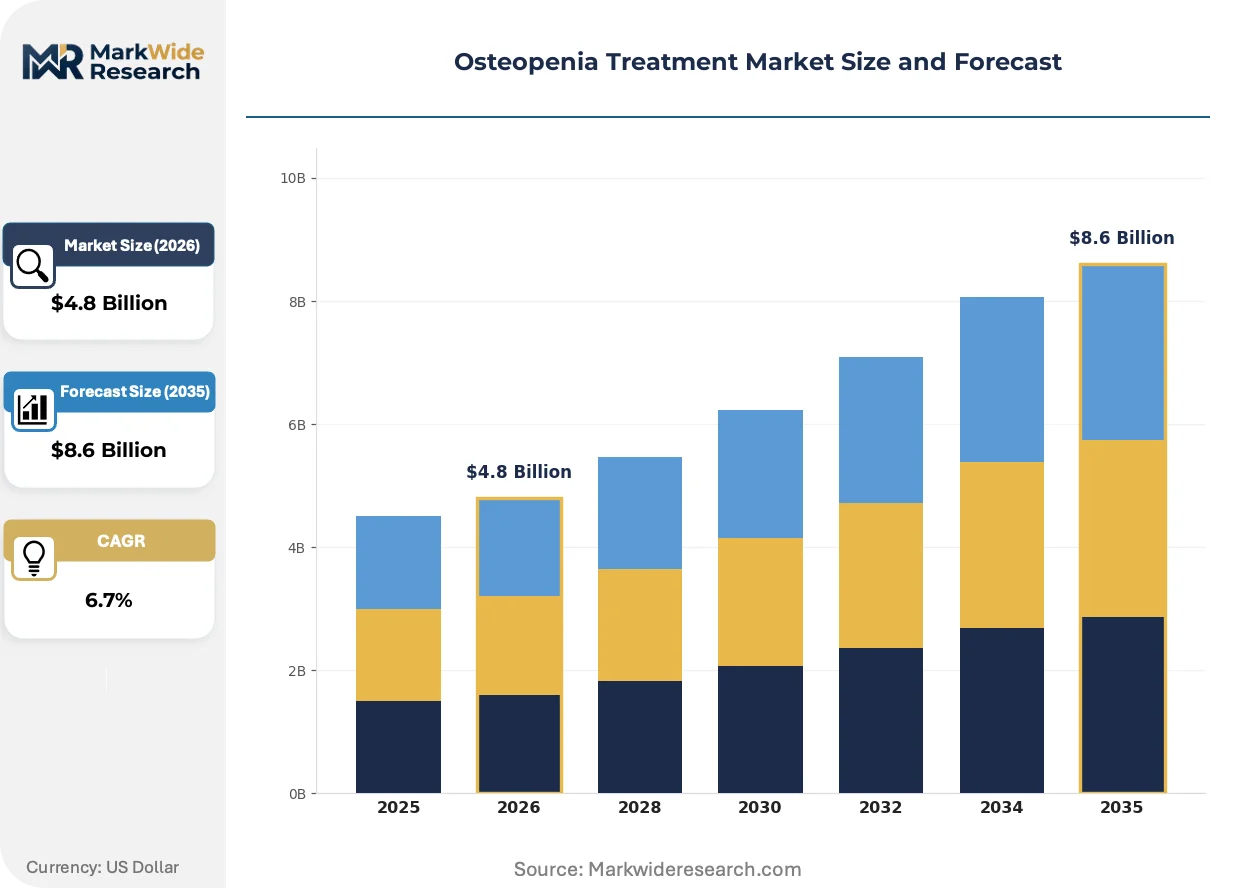
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Hormonal Therapy, Calcium Supplements, Vitamin D Supplements Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Home Care, Hospitals, Clinics, Long-term Care Facilities Therapy Area: Endocrinology, Rheumatology, Orthopedics, Geriatrics |
| Companies Covered | Novartis AG, Teva Pharmaceutical Industries Ltd., Amgen Inc., Radius Health, Inc., GlaxoSmithKline plc, Eli Lilly and Company, Pfizer Inc., UCB S.A., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteopenia Treatment Market Evolving Landscape
Biomarker-guided therapy selection is fragmenting traditional bone density threshold protocols, while regulatory pressure on real-world evidence and channel migration toward institutional settings reshape competitive positioning across the value chain.
Digital bone health monitoring is fragmenting conventional diagnostic pathways. Wearable impact sensors and remote patient monitoring platforms now supplement DEXA scanning for fracture risk stratification. US Medicare Advantage plans are piloting these technologies in postmenopausal cohorts. The technology is fragmenting specialist gatekeeping by enabling primary care physicians to initiate treatment without endocrinology referral.
EMA's MDR framework for implantable diagnostic devices is tightening clinical evidence requirements for bone density screening tools. Manufacturers must now submit post-market surveillance data on diagnostic accuracy in diverse patient populations. German notified bodies are applying these standards most stringently, delaying CE marking for several ultrasound-based screening systems and compressing competitive entry timelines.
Integrated care contracts are reshaping procurement in US health systems. Hospital systems now bundle bone density testing, pharmacotherapy, and fracture liaison services under single episode-based payments. This displaces fee-for-service pharmacy reimbursement. The model is most advanced in Medicare ACOs covering postmenopausal populations in the Northeast and Midwest.
Osteopenia Treatment Market Segmentation
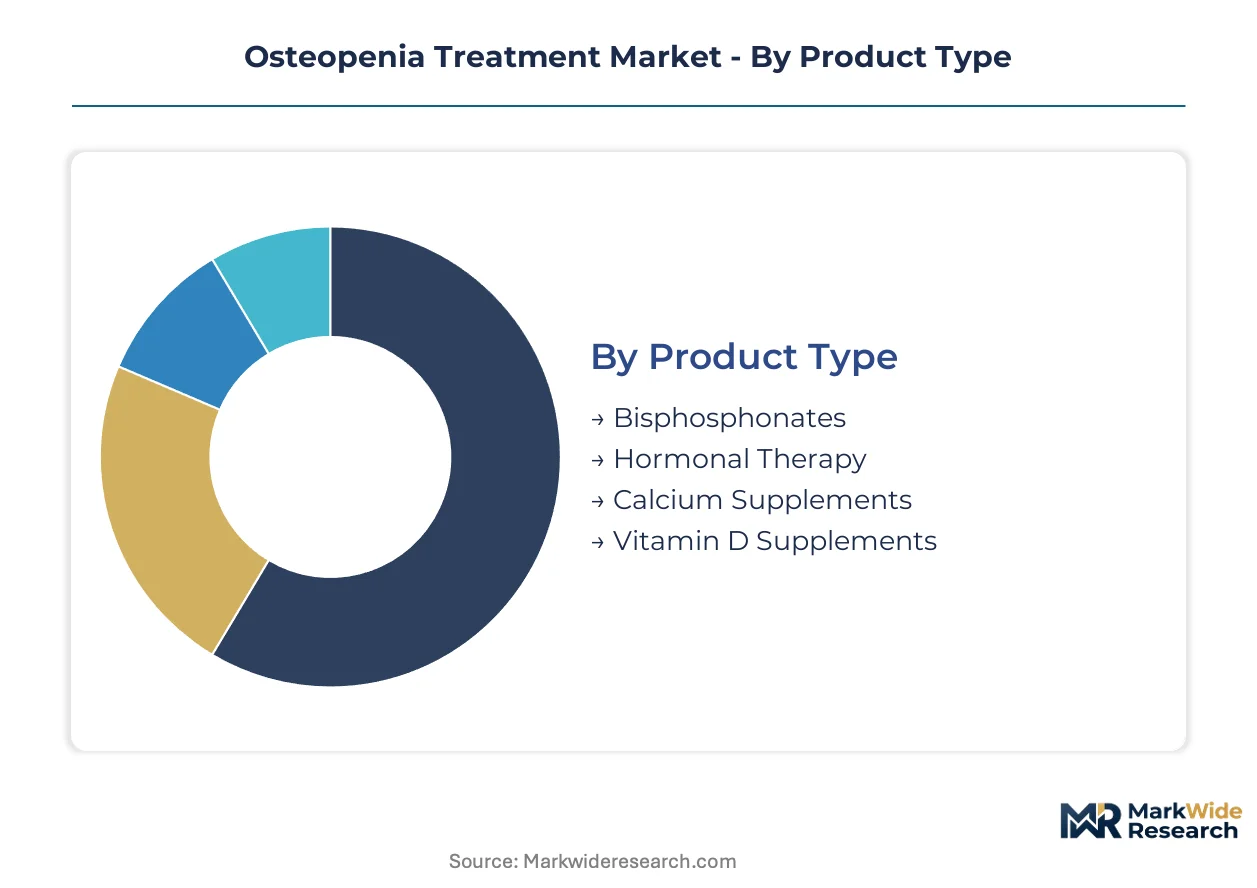
Channel economics and patient adherence patterns fragment the osteopenia treatment landscape across four structural dimensions. Each segmentation axis reveals distinct margin profiles and access barriers that shape competitive positioning.
Product Type:
Hospital formularies favor nitrogen-containing pyrophosphonate analogs for their established reimbursement codes, while retail pharmacy channels concentrate nutritional supplement volumes.
- Bisphosphonates:Nitrogen-containing pyrophosphate analogs inhibit osteoclast-mediated bone resorption through farnesyl pyrophosphate synthase inhibition. Hospital procurement in the United States and Germany concentrates here due to bundled episode-based payment structures. Supply continuity depends on entrenched manufacturing infrastructure amid geriatric endocrinology workforce contraction.
- Hormonal Therapy:Selective estrogen receptor modulators and related agents target postmenopausal women with elevated fracture risk profiles. Demand clusters in tertiary care settings where specialist gatekeeping persists despite workforce bottlenecks. PMDA Sakigake pathways in Japan accelerate pipeline investment for this segment.
- Calcium Supplements:Elemental calcium carbonate and citrate formulations dominate retail pharmacy and direct-to-consumer channels with minimal prescription requirements.
- Vitamin D Supplements:Cholecalciferol and ergocalciferol variants flow through primary care protocols as adjunctive therapy, capturing volume in outpatient settings where adherence compliance governs outcomes.
By volume, Bisphosphonates leads. By growth pace, Hormonal Therapy is ahead.
Delivery Mode:
Adherence failure rates in outpatient settings drive cost tier differentiation, with premium injectable formats commanding institutional placement where administration compliance determines formulary access.
- Oral:Daily and weekly bisphosphonate tablets suffer discontinuation rates exceeding 50% in year-one outpatient use. Retail pharmacy distribution dominates, though real-world effectiveness compression limits margin expansion.
- Injectable:Zoledronic acid and denosumab formulations capture premium positioning in US nursing facilities and hospital infusion centers. Long-acting profiles reduce specialist touchpoints, aligning with workforce contraction constraints.
- Transdermal:Patch-based delivery remains experimental for bone-active agents, with limited commercial penetration outside research protocols.
- Intranasal:Calcitonin-salmon sprays retain niche placement in European markets where patient preference for non-injectable alternatives persists.
Injectable formats claim the steepest expansion trajectory as institutional channels consolidate.
End User:
Patient acuity and reimbursement calibration fragment demand across care settings, with Medicare Advantage pilot programs reshaping channel economics.
- Hospitals:Tertiary care settings concentrate high-fracture-risk cohorts requiring integrated bone density testing and pharmacotherapy protocols. Episode-based payment bundles in US Medicare ACOs displace fee-for-service pharmacy reimbursement.
- Long-term Care Facilities:US nursing facilities prioritize injectable formulations where medication administration compliance governs formulary placement. Staff-mediated dosing overcomes adherence barriers that plague outpatient oral regimens.
- Clinics:Endocrinology and rheumatology outpatient sites face access restrictions from specialist workforce collapse across OECD systems.
- Home Care:Oral bisphosphonates and nutritional supplements flow through mail-order pharmacy and retail channels, though discontinuation rates compress real-world outcomes.
Hospital channels dominate value capture, while long-term care facilities expand most quickly.
Therapy Area:
Specialist gatekeeping intensity determines margin concentration, with geriatrics commanding patient volume and endocrinology directing premium protocol design.
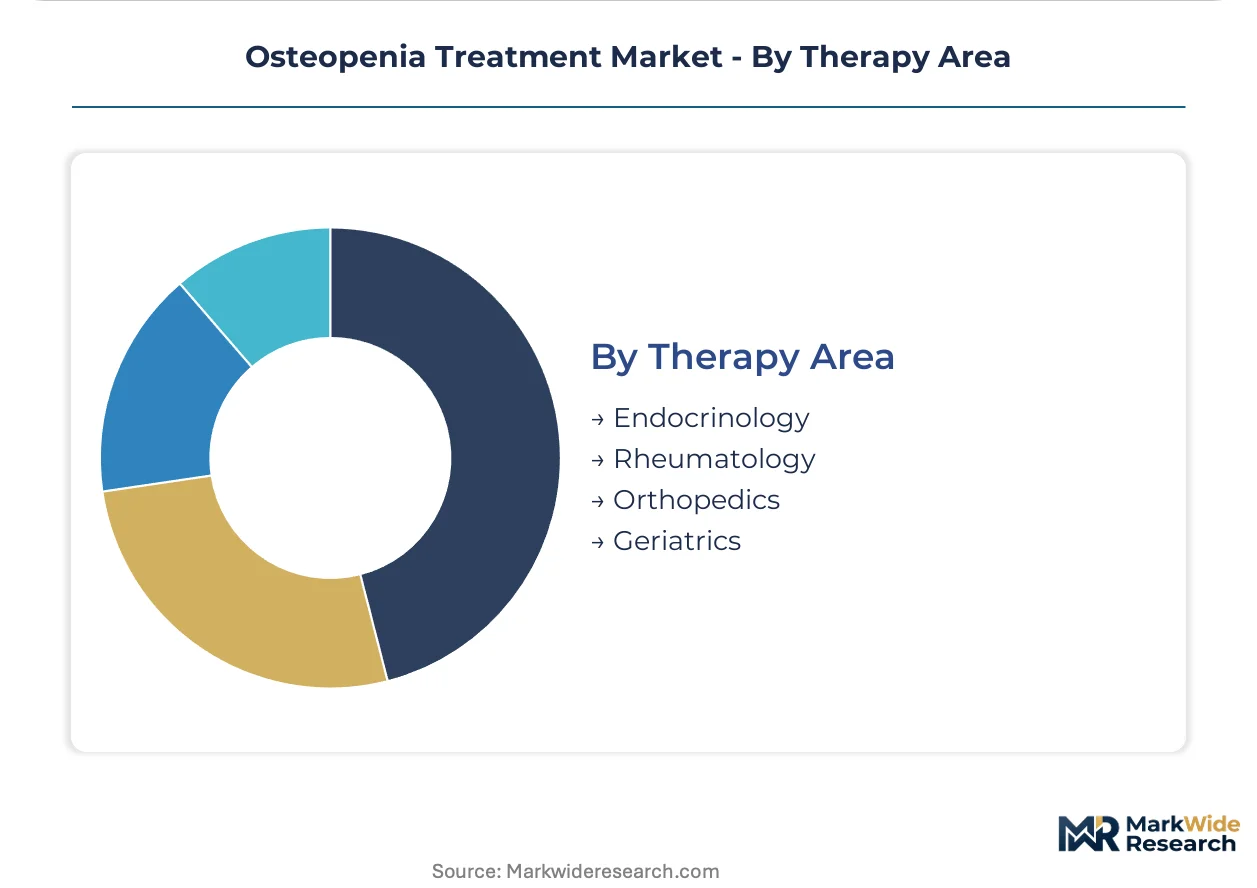
- Geriatrics:The largest patient pool by demographic weight, concentrated in hospital and long-term care settings where age-related bone loss protocols standardize. Workforce bottlenecks in geriatric endocrinology restrict access to diagnostic referral pathways.
- Endocrinology:Specialist-directed protocols govern bone mineral density threshold decisions and anabolic agent selection. FDA oversight of bone turnover biomarker endpoints shapes Phase III trial design for novel therapies targeting this channel.
- Rheumatology:Glucocorticoid-induced bone loss creates secondary demand in autoimmune patient cohorts, with overlapping therapeutic protocols.
- Orthopedics:Fracture liaison services and post-surgical bone health management represent emerging protocol integration points in European hospital systems.
Geriatrics leads by patient volume. Endocrinology directs the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in US hospital systems where bundled episode-based payments command premium formulary placement, while German outpatient clinics face margin compression from divergent pharmacoeconomic thresholds for preventive bone density scan coverage.
United States
Medicare Advantage pilot programs in postmenopausal cohorts drive demand for wearable impact sensors and remote patient monitoring platforms. FDA oversight of bone turnover biomarker endpoints shapes Phase III trial design for novel anabolic agents. Northeast and Midwest Medicare ACOs bundle bone density testing with fracture liaison services under single episode-based payments.
Germany
German notified bodies apply EMA's MDR framework most stringently for implantable diagnostic devices, delaying CE marking for ultrasound-based screening systems. Reimbursement authorities calibrate bone density scan coverage against pharmacoeconomic thresholds that fragment market access for preventive intervention. Bavarian hospital systems concentrate procurement of nitrogen-containing pyrophosphate analogs under bundled payment structures.
Japan
PMDA Sakigake-designated pathways compress development timelines for osteoporosis-adjacent therapies, drawing pipeline investment toward osteopenia indications. METI coordinates national bone health screening programs for postmenopausal women in Kanto and Kansai regions. Tokyo-based tertiary care centers standardize integrated bone density testing and pharmacotherapy protocols for high-fracture-risk cohorts.
United Kingdom
NHS England fracture liaison services reshape procurement by bundling bone density testing with pharmacotherapy under single episode-based payments. MHRA post-Brexit regulatory divergence creates timeline uncertainty for novel anabolic submissions using bone turnover biomarker endpoints. London and Southeast hospital systems concentrate specialist endocrinology protocols despite workforce contraction constraints.
Switzerland
Swissmedic oversight of companion diagnostic integration creates bundled protocol opportunities in Zurich and Geneva hospital systems. Cantonal reimbursement variation produces pricing tier differentiation between premium injectable formulations and oral bisphosphonate baselines. Basel-area pharmaceutical clusters anchor manufacturing infrastructure for long-acting bone-active agents.
Osteopenia Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the osteopenia treatment market. Consolidated manufacturing infrastructure for nitrogen-containing pyrophosphate analogs sits with entrenched pharmaceutical conglomerates, while differentiated anabolic therapy development clusters with specialized biotechnology firms. Two strategic archetypes dominate: scale-driven bisphosphonate producers leveraging supply continuity amid workforce bottlenecks, and innovation-focused anabolic specialists targeting high-fracture-risk cohorts through biomarker-guided protocols. Competitive moves concentrate on strategic partnerships for companion diagnostic integration and geographic expansion into PMDA-accelerated Japanese pathways.
Within the scale-driven archetype, Novartis AG and Eli Lilly and Company exemplify divergent positioning strategies. Novartis anchors supply continuity through entrenched bisphosphonate manufacturing infrastructure that sustains hospital formulary placement amid geriatric endocrinology workforce contraction. Eli Lilly occupies a position within the anabolic therapy tier, targeting high-fracture-risk cohorts through differentiated pipelines governed by FDA bone turnover biomarker endpoints. Pfizer Inc. sits between these archetypes, representing hybrid positioning across both commoditized oral formulations and emerging injectable delivery modes.
| Leading Market Players |
|---|
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Amgen Inc. |
| Radius Health, Inc. |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Pfizer Inc. |
| UCB S.A. |
| Merck & Co., Inc. |
| Others |
Value Network & Pricing Analysis
EMA's MDR framework gates both CE marking qualification and tiered reimbursement access for implantable bone density diagnostics, compressing margin structures for manufacturers unable to absorb post-market surveillance costs while rewarding integrated hospital system vendors with bundled protocol pricing power.
Pricing Analysis
US hospital systems command 40-60% premiums over German outpatient clinics for equivalent bisphosphonate formulations. Three-tier pricing structure across premium injectable, standard oral, and economy generic segments reflects FDA certification tiers and volume contracting scale. Cost compression in oral bisphosphonate tiers is intensifying because of high discontinuation rates and real-world effectiveness disputes. Long-term care facilities demonstrate lowest price sensitivity due to bundled episode-based payment structures, while retail pharmacy channels face acute sensitivity from Medicare Part D formulary competition.
Supply Chain Analysis
Inventory cycles for nitrogen-containing pyrophosphate analogs extend 90-120 days due to multi-step synthesis requirements and API validation protocols. Manufacturing concentrates in Switzerland, Ireland, and Puerto Rico where FDA-inspected facilities anchor global supply. Raw material dependencies include phosphorus pentachloride, aminomethylenephosphonic acid derivatives, and specialized excipient blends. Single-source vulnerability runs through Swiss fine-chemical intermediates subject to EMA export certification delays. Distribution runs through hospital GPO contracts in the United States, regional pharmacy wholesalers in Germany, and METI-coordinated procurement channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The osteopenia treatment market is entering a cyclical recovery phase as postmenopausal demographic expansion intersects with hospital channel consolidation, creating sustained demand pull for long-acting formulations that reduce specialist dependency.
For Market Incumbents: Compound manufacturing scale advantages by locking in multi-year GPO contracts with US hospital systems before workforce bottlenecks force further channel migration. Anchor supply continuity through backward integration into phosphorus-based intermediate production, insulating against EMA export certification delays that threaten competitor inventories. For New Entrants and Emerging Players: Lead with digital bone health monitoring platforms that fragment specialist gatekeeping, targeting Medicare Advantage pilot programs in postmenopausal cohorts as the most penetrable entry vector. Bundle wearable impact sensors with remote patient monitoring subscriptions to bypass saturated bisphosphonate commoditization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across anabolic therapy development as PMDA Sakigake pathways compress clinical trial timelines and reduce capital lock-up periods. Target biotechnology firms with validated bone turnover biomarker endpoints and Japanese regulatory filings already submitted. Watch FDA guidance on real-world evidence acceptance as the inflection signal for anabolic agent valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | EMA MDR compliance for implantable screening devices creates bundled protocol lock-in with German hospital systems. |
| PMDA Sakigake Pathway Entry | Accelerated Japanese approval compresses development timelines for osteoporosis-adjacent anabolic pipelines. |
| Long-Term Care Facility Penetration | Injectable formulation placement in US nursing facilities overcomes oral adherence failures that plague retail channels. |
| Biomarker-Guided Protocol Development | FDA-validated bone turnover endpoints differentiate premium anabolic positioning above commoditized bisphosphonate baselines. |
| Digital Remote Monitoring Launch | Medicare Advantage pilot programs for wearable impact sensors fragment traditional endocrinology referral gatekeeping. |
Research Methodology
Operator-level perspectives from geriatric endocrinologists, hospital formulary directors, GPO contract managers, and PMDA regulatory consultants anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA public assessment reports, ClinicalTrials.gov bone turnover biomarker studies, and CMS Medicare Advantage plan bid data. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs across delivery modes, therapy areas, and regional regulatory clusters.
Sensitivity analysis tested forecast robustness against specialist workforce contraction rates, reimbursement threshold shifts, and PMDA pathway timeline compression. Segmentation dimensions modeled include product type, delivery mode, end-user channel, therapy area specialization, and regional regulatory framework across the projection horizon. CAGRs derived from logistic diffusion curves for anabolic agent adoption and linear extrapolation for mature bisphosphonate volumes, incorporating hospital channel concentration indices and long-term care facility penetration rates as industry-specific inputs.
Forecasts assume regulatory continuity in FDA biomarker validation protocols and EMA MDR enforcement; material policy shifts would require re-modeling. Workforce availability trajectories, reimbursement calibration decisions by German G-BA and US CMS, and PMDA Sakigake designation criteria constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Rickets Market
Orthopedics
Septic Arthritis Market
Orthopedics
Orthopedic Pillow Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Athletic Knee Treatment Market
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Tendon Repair Market
Orthopedics
Osteoarthritis Treatment Market
Orthopedics
Kyphosis Market
Orthopedics
Podiatry Services Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Costochondritis Market
Orthopedics
Spinal Stenosis Market
Orthopedics
Osteoporosis Treatment Market