
 Septic Arthritis Market | 2026-2036
Septic Arthritis Market Size, Share, and Industry Trends Forecast 2026-2036
Septic Arthritis Market Outlook
Orthopedic clinic demand is shifting toward integrated surgical-medical management models for septic arthritis cases. Johnson & Johnson leverages its broad surgical portfolio to anchor joint reconstruction workflows alongside infection control protocols. AbbVie sustains competitive positioning through immunology R&D pipelines that address refractory inflammatory complications. Pfizer dominates hospital antibiotic formularies with established anti-staphylococcal agents used in standard joint infection regimens.
Septic arthritis constitutes a pyogenic bacterial infection of the synovial joint space, typically requiring pathogen identification through arthrocentesis followed by targeted antimicrobial therapy and drainage. The condition demands rapid intervention to prevent irreversible cartilage destruction and secondary osteoarthritis. Antibiotics command the largest product type share as first-line therapy, while surgical instruments capture premium margins in complex prosthetic joint infections requiring debridement. Imaging techniques lead technology adoption through MRI and ultrasound-guided aspiration protocols that reduce diagnostic delay. Diagnostic kits represent the fastest-growing technology segment as point-of-care pathogen detection shortens time-to-treatment decisions.
FDA antibiotic stewardship programs and EMA pharmacovigilance frameworks jointly constrain empirical broad-spectrum prescribing, compelling culture-directed therapy adoption. Joint Commission infection control standards mandate specific perioperative protocols that shape hospital procurement for septic arthritis surgical sets. Stakeholders must monitor resistance pattern surveillance data and diagnostic technology validation to align portfolio investments with evolving clinical pathway requirements.
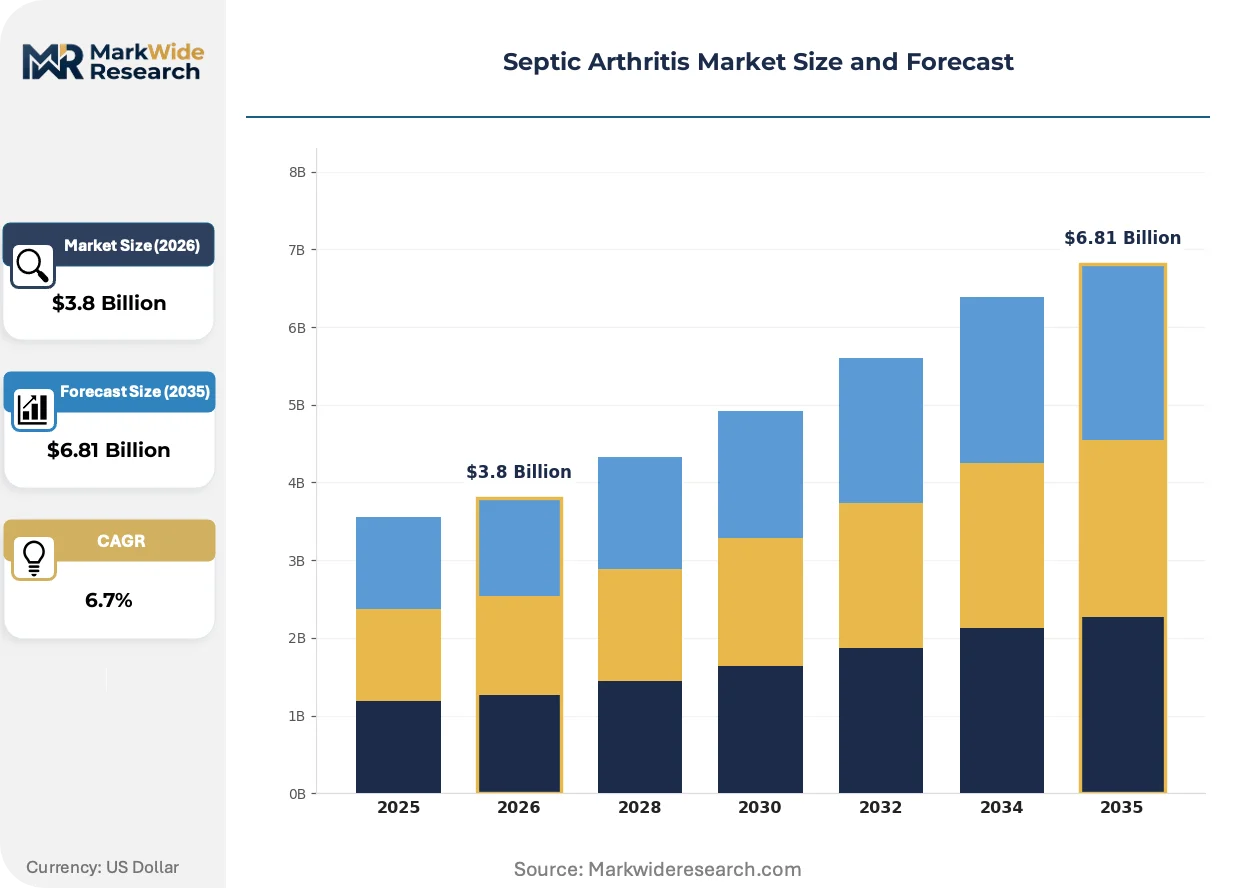
Market Dynamics
FDA antibiotic stewardship mandates are compressing empirical prescribing windows, forcing hospitals toward culture-directed therapy and accelerating point-of-care diagnostic adoption across orthopedic workflows.
Growth Catalysts
- Antimicrobial Stewardship Protocols:FDA's evolving guidelines for hospital antibiotic use are standardizing arthrocentesis-before-therapy protocols, expanding demand for rapid pathogen identification systems in orthopedic departments.
- Prosthetic Joint Volume:Rising hip and knee arthroplasty rates in tertiary care centers are generating elevated prosthetic joint infection caseloads requiring specialized surgical-medical management.
- Molecular Diagnostics:PCR-based synovial fluid testing is shortening time-to-pathogen identification from days to hours, enabling earlier targeted therapy initiation.
Market Restraints
- Antibiotic Pipeline Contraction:Sparse novel anti-staphylococcal development is narrowing therapeutic options against methicillin-resistant organisms in joint infections.
- Diagnostic Reagent Supply:Concentrated manufacturing of specialized culture media and PCR reagents creates vulnerability to single-source disruptions.
- Reimbursement Compression:CMS bundled payment models for joint replacement episodes are constraining separate coding for infection management procedures.
Strategic Opportunities
- Outpatient Parenteral Therapy:Shifting stable post-operative joint infection patients to infusion centers reduces hospital length-of-stay and opens ambulatory service revenue streams.
- AI-Assisted Imaging:Machine learning algorithms applied to MRI sequences are enabling earlier detection of occult joint infections before gross structural damage.
- Pharmacokinetic Modeling:Patient-specific antibiotic dosing software is optimizing intra-articular drug concentration targeting in complex cases.
Industry Challenges
- Microbiology Specialist Shortage:Declining clinical microbiology training programs are lengthening turnaround times for synovial fluid culture interpretation in community hospitals.
- Interoperability Friction:Disconnected EHR systems between orthopedic surgery, infectious disease, and laboratory departments impede coordinated infection management protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Septic Arthritis Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Corticosteroids, Surgical Instruments End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Home Healthcare Treatment Approach: Medication, Surgery, Physiotherapy, Joint Aspiration Technology: Imaging Techniques, Diagnostic Kits, Biopsy Methods, Laboratory Testing |
| Companies Covered | Johnson & Johnson, AbbVie, Pfizer, Merck & Co., Bristol-Myers Squibb, Amgen, Novartis, Roche, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Septic Arthritis Market Strategic Shifts
Diagnostic velocity is emerging as the decisive competitive variable, with technologies compressing the critical window between presentation and pathogen-directed therapy reshaping procurement priorities across hospital systems.
Next-generation sequencing of synovial fluid is overtaking conventional culture methods in complex prosthetic joint infections. Academic medical centers are adopting metagenomic platforms within 18-month procurement cycles. This technology is enabling polymicrobial detection and antimicrobial resistance profiling without prior pathogen suspicion, compressing the diagnostic phase from 72 hours to under 24 hours.
EMA's Medical Device Regulation is tightening clinical evidence requirements for orthopedic surgical instruments used in infected joint debridement. Manufacturers must now submit prospective outcome data for instrument sets labeled for septic arthritis applications. European orthopedic departments are extending procurement timelines by 8-14 months to accommodate notified body review of updated technical documentation.
Hospital value analysis committees are consolidating antibiotic formulary decisions at system level rather than individual facility level. Regional health networks are replacing local pharmacy and therapeutics committees with centralized infectious disease stewardship teams. This concentration is most visible in United States multi-hospital systems exceeding 10 facilities, where standardized joint infection protocols override individual surgeon preferences.
Septic Arthritis Market Segmentation
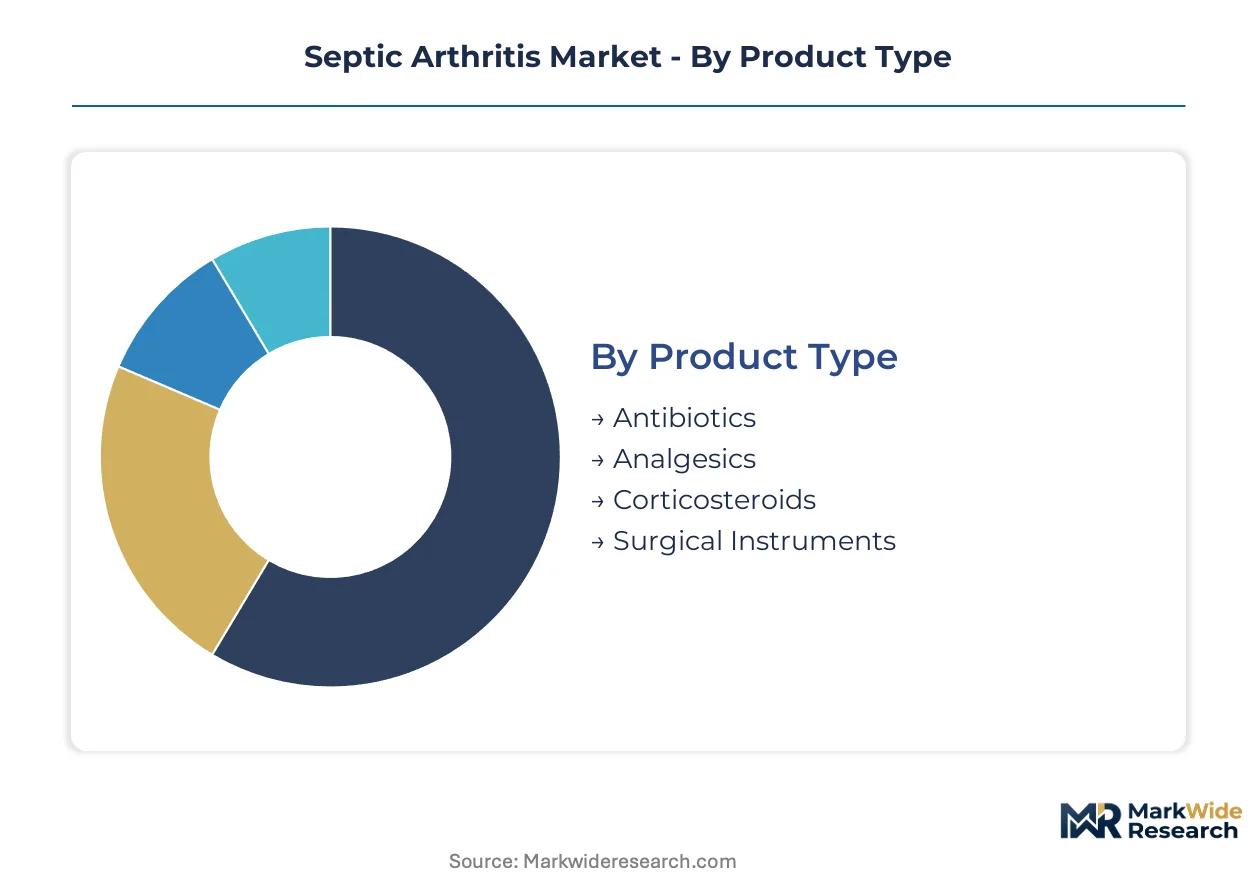
Septic arthritis treatment pathways diverge sharply across clinical settings, with procurement patterns tracking infection severity, surgical complexity, and diagnostic velocity requirements. Each segment category reflects distinct stakeholder priorities—hospital formulary committees, orthopedic surgeons, and laboratory directors—that reshape competitive positioning.
Product Type:
Volume leadership concentrates in established systemic therapies, while premium margins attach to precision surgical hardware and targeted delivery systems.
- Antibiotics:Intravenous vancomycin, ceftriaxone, and anti-staphylococcal penicillins constitute first-line empiric therapy before culture results. Hospital formularies in the United States standardize these agents through centralized infectious disease stewardship committees.
- Surgical Instruments:Arthroscopic shavers, suction-irrigation systems, and modular debridement sets command premium pricing in prosthetic joint infection cases requiring multiple operative stages. Tertiary care centers in Germany and the United States drive specialized instrument procurement.
- Analgesics:NSAIDs and opioid-sparing multimodal protocols manage perioperative pain without altering infection trajectory.
- Corticosteroids:Intra-articular and systemic formulations address refractory inflammatory flares in selected post-infectious arthritis presentations.
Mature deployment sits with Antibiotics across all treatment settings. Newer deployment is concentrated in Surgical Instruments as revision arthroplasty volumes climb.
End User:
Care site determines reimbursement architecture and technology sophistication, with acute settings retaining high-complexity cases and ambulatory channels absorbing stable post-operative management.
- Hospitals:Tertiary academic medical centers manage prosthetic joint infections requiring multidisciplinary coordination between orthopedic surgery, infectious disease, and microbiology laboratories. CMS bundled payment models in the United States shape episode-based procurement decisions.
- Orthopedic Clinics:Ambulatory surgical centers and specialty clinics perform diagnostic arthrocentesis and initiate empiric therapy before hospital transfer. Outpatient parenteral antibiotic programs in France and the United Kingdom expand clinic service scope.
- Rehabilitation Centers:Post-operative mobility restoration and joint function recovery programs follow surgical intervention completion.
- Home Healthcare:Infusion nursing services deliver prolonged IV antibiotic courses for stable patients meeting early discharge criteria.
Complex case concentration anchors in Hospitals. Volume expansion is accelerating fastest in Orthopedic Clinics as ambulatory surgical migration proceeds.
Treatment Approach:
Clinical pathway selection hinges on infection chronicity, prosthetic presence, and host immune status—with surgical threshold decisions increasingly protocolized.
- Medication:Targeted antimicrobial therapy directed by synovial fluid culture and susceptibility testing remains foundational for native joint infections without abscess formation.
- Surgery:Arthrotomy, arthroscopic lavage, and prosthetic exchange procedures address mechanical joint sepsis and biofilm-embedded pathogens.
- Physiotherapy:Post-infectious range-of-motion protocols prevent adhesions and preserve functional outcomes after microbial eradication.
- Joint Aspiration:Diagnostic and therapeutic arthrocentesis provides immediate pressure relief and material for microbiological analysis.
Standard-of-care maturity centers on Medication protocols. Surgical intervention is gaining protocol share fastest as prosthetic joint infection incidence rises.
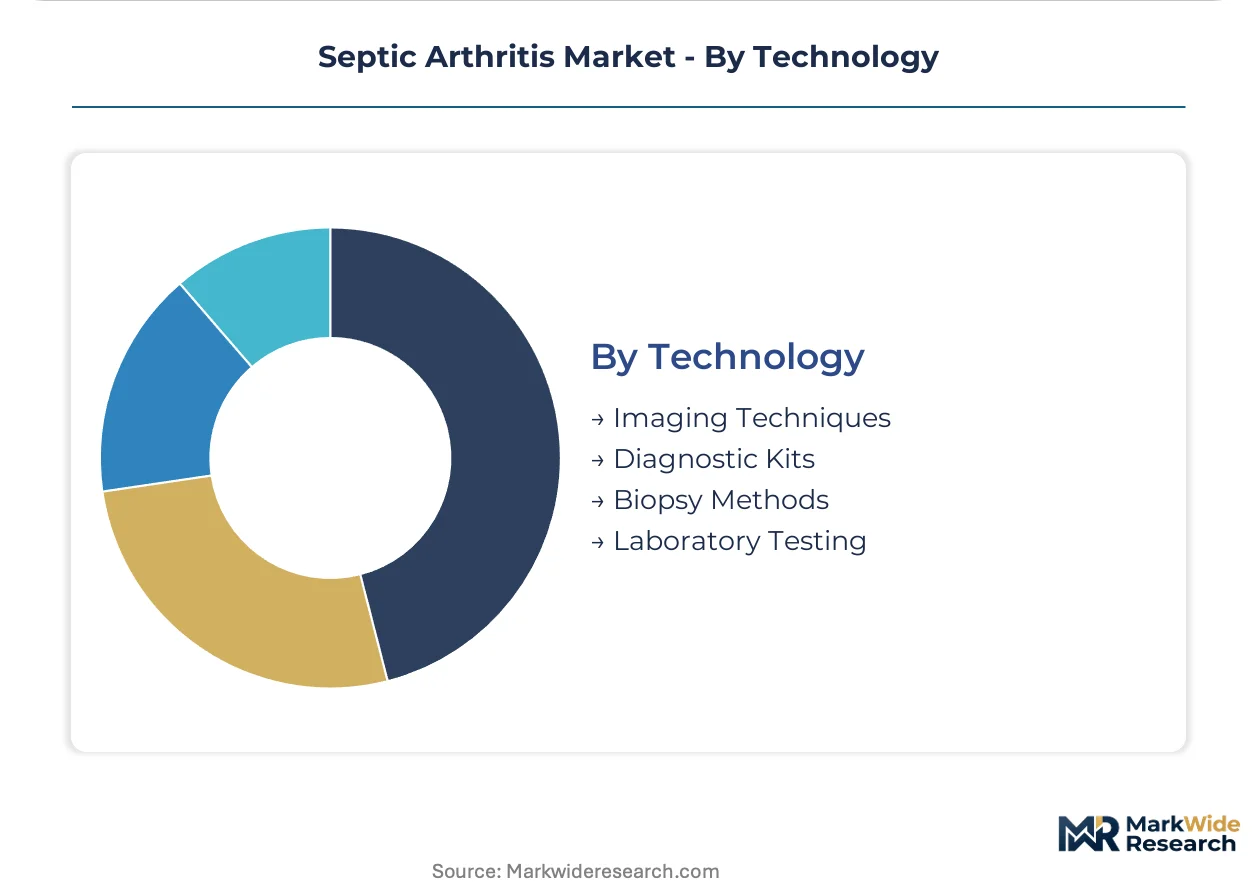
Technology:
Diagnostic velocity now determines competitive positioning, with time-to-pathogen identification compressing from days to hours across leading institutions.
- Diagnostic Kits:PCR-based synovial fluid panels and rapid antigen detection systems enable point-of-care pathogen identification without centralized laboratory processing. Academic medical centers in the United States and Switzerland deploy these platforms within 18-month procurement cycles.
- Imaging Techniques:MRI with gadolinium enhancement and ultrasound-guided aspiration protocols reduce diagnostic delay and guide intervention timing. EMA Medical Device Regulation compliance requirements extend European procurement timelines.
- Biopsy Methods:Synovial tissue sampling via arthroscopy or needle biopsy supports histopathological confirmation in culture-negative presentations.
- Laboratory Testing:Conventional aerobic and anaerobic culture, antimicrobial susceptibility testing, and extended incubation protocols for fastidious organisms retain central reference laboratory roles.
Established infrastructure resides in Laboratory Testing. Diagnostic Kits represent the fastest-growing trajectory as stewardship mandates accelerate targeted therapy initiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Septic arthritis treatment production concentrates in pharmaceutical manufacturing clusters across Germany, Switzerland, and the United States, while consumption patterns track arthroplasty volumes and hospital infrastructure density. The United States absorbs the largest share of advanced diagnostic kits and surgical instruments, reflecting its tertiary care concentration and bundled payment incentives for rapid infection resolution.
United States
Tertiary care centers in Boston, New York, and Houston manage the highest prosthetic joint infection caseloads, driving concentrated demand for molecular diagnostic platforms. FDA antibiotic stewardship mandates require arthrocentesis-before-therapy protocols, accelerating point-of-care PCR adoption. The Mayo Clinic in Rochester anchors multi-center trials for next-generation synovial fluid sequencing technologies.
Germany
Academic medical centers in Berlin and Munich perform the highest European volumes of two-stage revision arthroplasty for infected joints. EMA Medical Device Regulation compliance extends procurement timelines for orthopedic surgical instruments by 8-14 months. The Ruhr Valley industrial corridor hosts specialized manufacturers of arthroscopic debridement sets serving hospital systems across Central Europe.
Switzerland
Swissmedic oversight of diagnostic kit validation creates a regulatory gateway for European market entry, with Basel and Zurich academic hospitals adopting metagenomic platforms within compressed procurement cycles. The country's precision manufacturing base supplies specialized culture media for synovial fluid analysis. Roche's diagnostic division in Basel anchors regional supply chains for PCR-based pathogen identification systems.
United Kingdom
NHS England's outpatient parenteral antibiotic therapy programs expand clinic-based joint infection management beyond traditional hospital settings. NICE guidelines standardize perioperative protocols across orthopedic departments, shaping formulary decisions for anti-staphylococcal agents. The Oxford-Cambridge-London golden triangle concentrates academic research on AI-assisted imaging for early joint infection detection.
Japan
PMDA fast-track pathways for novel diagnostics accelerate adoption of rapid synovial fluid testing in Tokyo and Osaka metropolitan hospitals. METI industrial policy supports domestic manufacturing of orthopedic surgical instruments to reduce import dependency. The Kansai region's medical device cluster specializes in miniaturized arthroscopic equipment for revision joint procedures.
Septic Arthritis Market Competitive Environment
Top-tier vendors anchor hospital antibiotic formularies and surgical instrument portfolios, while mid-tier specialists concentrate on diagnostic platforms and regional distribution networks. The market structure reflects consolidation around integrated surgical-medical solution providers alongside fragmentation in point-of-care diagnostics. Three archetypes dominate: diversified pharmaceutical conglomerates with orthopedic portfolios, pure-play diagnostic technology developers, and specialized surgical instrument manufacturers. Competitive moves center on strategic partnerships between antibiotic developers and diagnostic platform companies, plus vertical integration into outpatient infusion services.
Within the diversified pharmaceutical tier, Johnson & Johnson, Pfizer, and AbbVie occupy positions that span infection control protocols through immunology and anti-infective portfolios. Johnson & Johnson represents the integrated surgical-medical archetype through its broad orthopedic and pharmaceutical assets. Pfizer exemplifies hospital formulary dominance with established anti-staphylococcal agents. AbbVie anchors immunology-focused positioning that addresses refractory inflammatory complications in post-infectious arthritis presentations.
| Leading Market Players |
|---|
| Johnson & Johnson |
| AbbVie |
| Pfizer |
| Merck & Co. |
| Bristol-Myers Squibb |
| Amgen |
| Novartis |
| Roche |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Specialized PCR reagent manufacturing costs in Germany and Switzerland cascade through three-tier pricing structures across premium, standard, and economy diagnostic kit tiers, with FDA-validated platforms commanding hospital formulary premiums over CE-marked alternatives.
Pricing Analysis
Margin tightening in point-of-care diagnostic platforms reflects concentrated manufacturing of thermal-stable polymerases and fluorescent probes. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from research-use-only reagents and unvalidated import alternatives. Cost-down pressure on arthroscopic instrument sets accelerates because EMA Medical Device Regulation compliance extends notified body review timelines. Academic medical centers show lowest price sensitivity for rapid pathogen identification systems, while community hospitals prioritize economy-tier alternatives.
Supply Chain Analysis
CE marking and FDA 510(k) clearance gates concentrate arthroscopic instrument sourcing in Germany, Switzerland, and the United States. Supply draws from precision-machined stainless steel forgings, single-use suction-irrigation disposables, and specialized culture media substrates. Single-source vulnerability sits with Swiss manufacturers of synovial fluid PCR reagents. Distribution runs through orthopedic distributor networks and hospital value analysis committees rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR-based synovial fluid diagnostics are displacing conventional culture methods, compressing diagnostic windows from 72 hours to under 24 hours and reshaping procurement priorities across hospital systems.
For Market Incumbents: Deepen backward integration into rapid diagnostic reagent manufacturing to secure supply continuity against Swiss and German single-source dependencies. Fortify hospital formulary positioning through FDA-cleared multiplex panel development before EMA MDR compliance extends European competitor procurement cycles. Anchor joint reconstruction workflows with integrated infection control protocols that bundle surgical instruments with diagnostic platforms. For New Entrants and Emerging Players: AI-assisted MRI interpretation algorithms offer technology-first wedge into early occult joint infection detection before gross structural damage. Target ambulatory surgical centers in the United States and United Kingdom outpatient parenteral antibiotic programs where hospital stewardship mandates create procurement urgency. Pursue hospital-at-home infusion partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA fast-track designation for novel synovial fluid metagenomic platforms is the leading indicator that diagnostic velocity will determine competitive positioning within the analysis window. Long-term viability hinges on capturing hospital system-level formulary consolidation rather than individual facility procurement. Acquire point-of-care molecular diagnostics specialists with validated orthopedic pathogen panels. Monitor EMA notified body backlog clearance as the signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| PCR Platform FDA Submission | Accelerates hospital formulary entry ahead of stewardship mandate deadlines. |
| Hospital System Partnership | Locks in multi-facility procurement through centralized infectious disease committees. |
| Reimbursement Strategy | Secures separate coding for infection management outside CMS bundled payments. |
| CE Marking Pathway | Opens European access despite EMA MDR extended review timelines. |
| Software Companion Development | Enables AI-assisted imaging integration with existing MRI workflows. |
Study Parameters
FDA 510(k) filings, EMA medical device registration databases, and hospital procurement contract records formed the secondary backbone for market sizing. Primary interviews with orthopedic surgeons, infectious disease specialists, hospital formulary directors, and clinical microbiology laboratory directors validated demand assumptions. Bottom-up and top-down triangulation cross-checked surgical procedure volumes against antibiotic consumption patterns.
Bottom-up modeling anchored revenue estimates to individual product categories across the projection horizon. Segmentation dimensions included product type, treatment approach, end-user facility type, and diagnostic technology tier. CAGRs were derived from procedure volume growth rates and pricing trajectory assumptions. Forecast inputs incorporated arthroplasty revision incidence data and molecular diagnostic adoption curves.
Several conditions sit outside the modeled scope, including novel antibiotic pipeline approvals and point-of-care resistance profiling breakthroughs. Forecasts reflect documented assumptions about regulatory clearance timelines and reimbursement stability. A model refresh is warranted upon material change in FDA antibiotic stewardship enforcement intensity or EMA notified body capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedics
Hips and Knees Reconstructive Market
Orthopedics
Knee Hyaluronic Acid Injections Market
Orthopedics
Bilateral Osteoarthritis Treatment Market
Orthopedics
Orthopedic Soft Tissue Repair Market
Orthopedics
Tendon Repair Market
Orthopedics
Global Foot Drop Treatment Market
Orthopedics
Cruciate Ligament Repair Procedures Market
Orthopedics
Osteonecrosis Treatment Market
Orthopedics
Hallux Rigidus Market
Orthopedics
Osteoporosis Treatment Market
Orthopedics
Kyphosis Market
Orthopedics
Costochondritis Market
Orthopedics
Global Osteoarthritis Therapeutics Market
Orthopedics
Rickets Market
Orthopedics
Rotator Cuff Arthropathy Repair Market
Orthopedics
Osteopenia Treatment Market