
 Crop Bactericides Market | 2026-2036
Crop Bactericides Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Bactericides Market Intelligence
Modular tank-mix bundling of bactericides with fungicides and biostimulants is rebalancing procurement decisions for large-scale growers. Syngenta Crop Protection AG leverages its formulation science to sustain bundled product loyalty across Latin American citrus belts. BASF SE anchors its position through backward integration into active ingredient synthesis, while Nufarm Limited competes via channel control in Australian broadacre distribution.
Crop bactericides comprise antimicrobial agents formulated to suppress or eradicate bacterial phytopathogens, typically containing copper compounds, antibiotics such as streptomycin, or live biological antagonists applied at 0.5–2.0 kg active ingredient per hectare depending on pathogen pressure and crop stage. Their primary commercial purpose is to prevent yield loss from bacterial diseases including fire blight, bacterial spot, and citrus canker in high-value agricultural systems. Biologicals now command the fastest expansion trajectory as residue-conscious export markets tighten maximum residue limits, while copper-based formulations occupy the mature volume core due to decades of proven efficacy against Xanthomonas and Pseudomonas species. Liquid formulations lead value pools because of precision application compatibility with drone and drip-irrigation systems.
The EPA governs bactericide registration under FIFRA, requiring chronic toxicity and environmental fate data that extends development timelines, while the EU's Farm to Fork Strategy and MDR-aligned biocidal product regulations are tightening copper-based product authorizations and accelerating biological alternative pathways. India's Central Insecticides Board under the Ministry of Agriculture mandates local efficacy trials and label expansions that shape market access timelines for multinational registrants. Stakeholders must monitor evolving residue tolerance harmonization between CODEX, EPA, and EU systems to anticipate which active ingredients will retain multi-jurisdictional commercial viability.
Market Dynamics
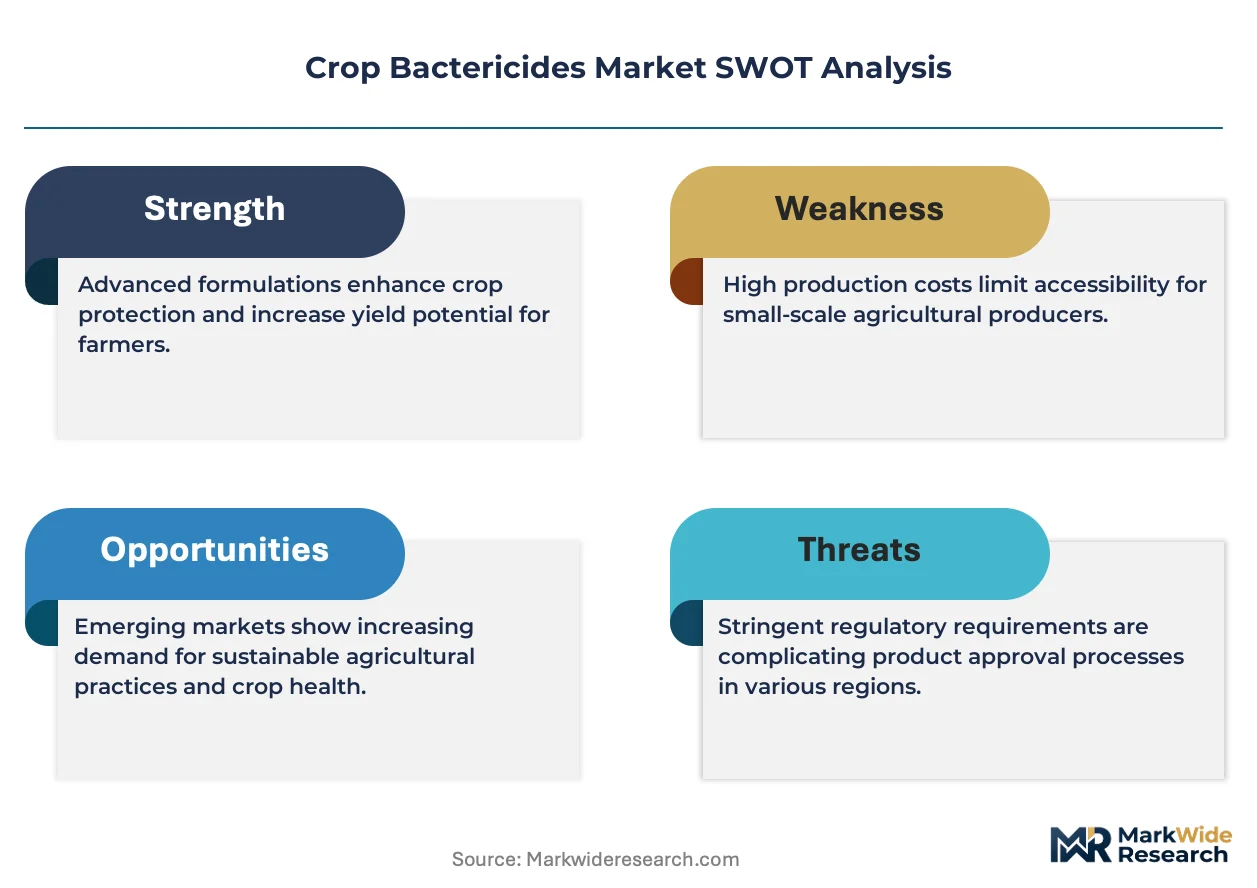
The EU Green Deal's Farm to Fork Strategy pesticide reduction mandates are compressing copper-based bactericide authorization timelines while accelerating biological alternative development pathways across export-oriented agricultural systems.
Growth Catalysts
- Biological Registration Fast-Tracks:The EU's Farm to Fork Strategy pesticide reduction targets are compressing approval timelines for live antagonist formulations, redirecting R&D investment from synthetic chemistry toward microbial biocontrol platforms.
- Protected Cultivation Expansion:Specialty vegetable growers operating greenhouse and hydroponic systems are driving precision application demand for liquid bactericide formulations compatible with drip-irrigation infrastructure.
- Export Market Residue Standards:CODEX-aligned maximum residue limit tightening in European and North American import markets is forcing contract farming clusters in India to adopt residue-free biological bactericide protocols.
Market Restraints
- Copper Authorization Contraction:EFSA-driven cumulative exposure assessments under EU biocidal product regulations are narrowing approved copper compound uses, threatening the mature volume core of existing product portfolios.
- Active Ingredient Supply Concentration:Backward-integrated synthesis capacity for streptomycin and kasugamycin concentrates among Chinese manufacturers creates input vulnerability for formulators lacking captive supply.
- Biological Efficacy Variability:Live antagonist formulations suffer from temperature-sensitive shelf stability and inconsistent field performance against Xanthomonas species, limiting grower confidence in high-pressure disease seasons.
Strategic Opportunities
- Drone Application Compatibility:Ultra-low volume liquid bactericide formulations are absorbing precision agriculture investment from Brazilian citrus cooperatives seeking to reduce labor costs in canker management programs.
- Biostimulant Bundling:Modular tank-mix combinations with micronutrient biostimulants are creating value-capture opportunities for distributors serving large-scale Brazilian and Australian broadacre operations.
- Smallholder Contract Farming:India's Central Insecticides Board local efficacy trial requirements favor registrants establishing domestic formulation partnerships to accelerate label expansions for export-oriented food processor supply chains.
Industry Challenges
- Chronic Toxicology Data Generation:EPA FIFRA-mandated environmental fate studies require multi-year field trials, extending development timelines and freezing pipeline prioritization decisions for multinational registrants.
- Residue Tolerance Harmonization Friction:Divergent CODEX, EPA, and EU maximum residue limit schedules force formulators to maintain multiple product variants, complicating inventory management and label compliance across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Bactericides Market |
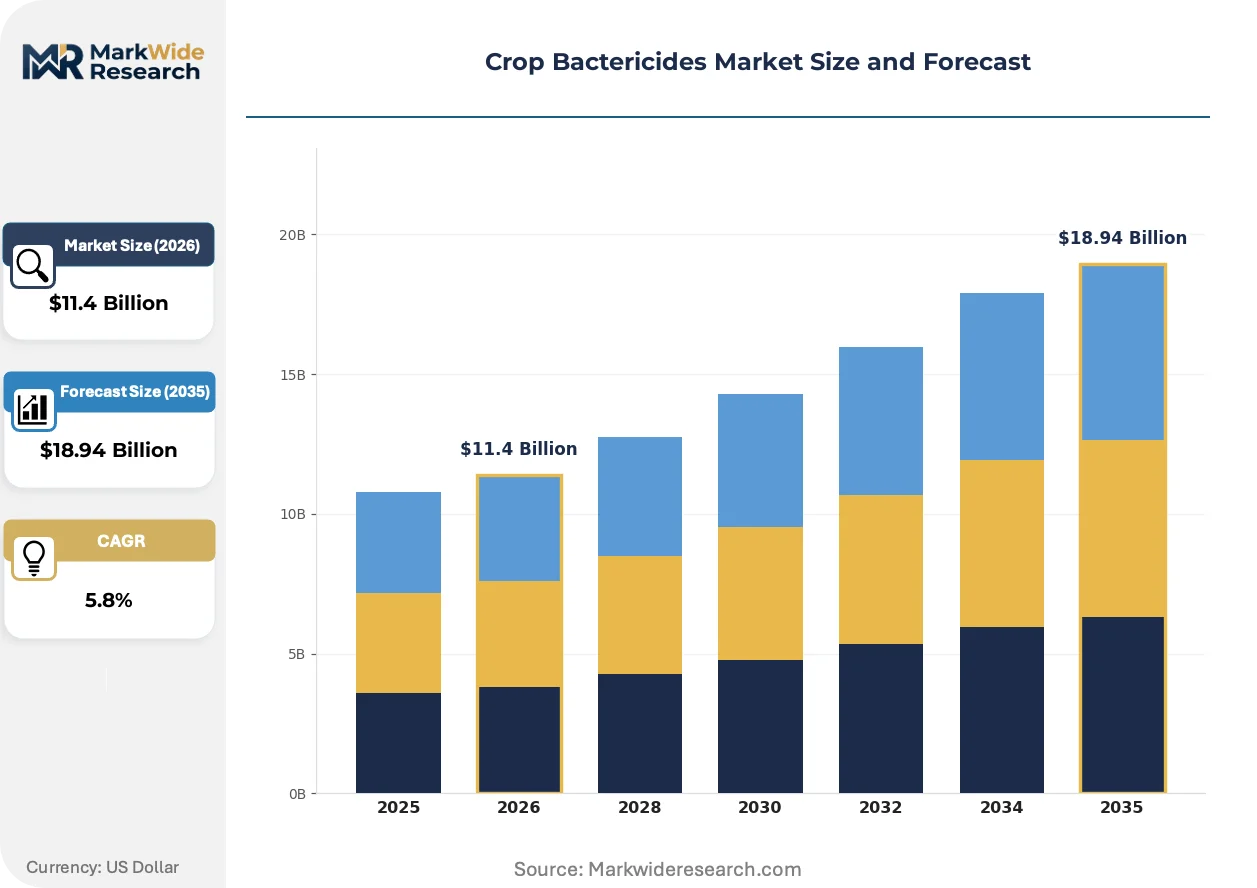
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologicals, Antibiotics, Copper-Based, Synthetic Application: Fruits, Vegetables, Grains, Ornamentals Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Direct Sales, Retail, Online, Agricultural Cooperatives |
| Companies Covered | Sumitomo Chemical Company Ltd., Nufarm Limited, BASF SE, PI Industries, Adama Agricultural Solutions Ltd., Syngenta Crop Protection AG, FMC Corporation, American Vanguard Corporation, Bayer Crop Science AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Bactericides Market Strategic Shifts & Innovations
Formulation science advances and precision application hardware are converging to displace broadcast spraying methods, while biological antagonist platforms are capturing R&D investment previously directed toward synthetic chemistry optimization.
RNA interference bactericides targeting pathogen-specific gene expression are absorbing venture funding from agricultural biotechnology investors, though field-scale delivery systems remain unproven. Greenhouse tomato and pepper producers in the Netherlands and Spain are piloting foliar spray programs integrating these nucleic acid platforms with existing copper rotations. The technology is absorbing regulatory scrutiny from EFSA regarding off-target effects on soil microbiomes, compressing near-term commercialization timelines despite promising greenhouse trial data.
The EU's Farm to Fork Strategy 50% pesticide reduction target by 2030 is forcing member states to accelerate biological product authorization through zonal mutual recognition procedures. National competent authorities in France and Germany are prioritizing microbial biocontrol dossiers over synthetic chemistry renewals, shifting registrant submission strategies toward live antagonist data packages. Citrus and pome fruit growers in Italy and Greece are responding by expanding integrated pest management consultant contracts to navigate the transitioning product landscape.
Buyers in Australian broadacre distribution channels are consolidating procurement decisions through distributor-managed tank-mix bundling programs that combine bactericides, fungicides, and biostimulants into season-long input packages. This channel control model displaces direct manufacturer relationships for wheat and canola growers in New South Wales and Western Australia. The shift concentrates price negotiation leverage with Nufarm Limited and similar distributors possessing regional agronomic advisory capabilities, compressing margin capture for standalone bactericide formulators lacking bundled portfolio depth.
Crop Bactericides Market Segmentation
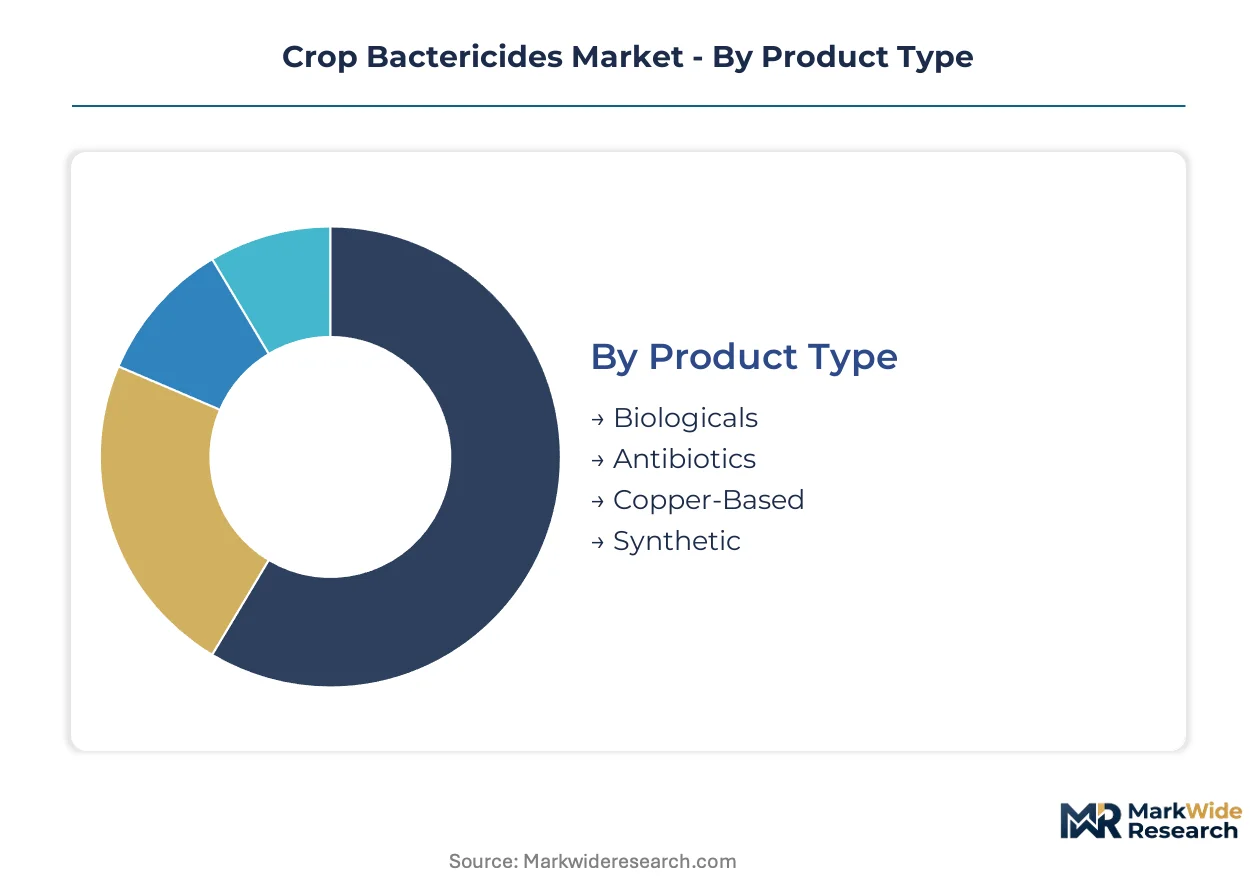
Crop bactericide purchasing decisions fragment across product chemistry, crop value, and application infrastructure. Each segmentation axis reveals distinct margin structures and customer loyalty patterns that shape competitive positioning.
Product Type:
Biologicals command premium positioning while copper-based formulations anchor volume throughput in mature agricultural systems.
- Biologicals:Live microbial antagonist formulations containing Bacillus subtilis or Pseudomonas fluorescens suppress pathogens through competitive exclusion. Dutch greenhouse tomato producers are expanding procurement of these residue-free platforms to meet EFSA-aligned export standards.
- Copper-Based:Fixed copper compounds including copper hydroxide and copper oxychloride deliver broad-spectrum Xanthomonas and Pseudomonas suppression at lower cost per hectare. Italian citrus growers in Calabria and Sicily continue rotating these despite EU authorization compression.
- Antibiotics:Streptomycin and kasugamycin formulations provide targeted fire blight control in high-value pome fruit systems.
- Synthetic:Laboratory-synthesized bactericidal actives occupy niche positions where biological efficacy proves inconsistent.
Today's leader: Copper-Based. Tomorrow's challenger: Biologicals.
Application:
Per-hectare input spending correlates directly with crop value density and export market access requirements.
- Fruits:Citrus canker and fire blight management in Brazilian São Paulo state and Spanish Valencia region drives precision application investment. Drone-compatible liquid formulations are absorbing capital from citrus cooperatives seeking labor cost reduction.
- Vegetables:Bacterial spot control in protected tomato and pepper cultivation commands the steepest price premiums. Netherlands and Spanish Almería greenhouse clusters are expanding integrated pest management consultant contracts to navigate biological transition pathways.
- Grains:Wheat and canola bacterial diseases in Australian New South Wales broadacre systems favor bundled procurement through distributor-managed programs.
- Ornamentals:Nursery stock bacterial blight management occupies a specialized channel with lower volume throughput.
Vegetables capture the highest margin per liter applied. Grains move the largest absolute tonnage.
Formulation:
Application hardware compatibility now determines formulation R&D priority more than active ingredient efficacy alone.
- Liquid:Suspension concentrates and soluble liquids enable ultra-low volume drone spraying and drip-irrigation chemigation. Brazilian citrus cooperatives are piloting aerial application programs that displace ground crew labor.
- Emulsifiable Concentrate:Oil-based carriers improve foliar adhesion in high-rainfall tropical zones. Indian smallholder contract farming clusters supplying export processors favor these for monsoon-season bacterial spot management.
- Granular:Soil-incorporated delivery systems target root-zone pathogens in potato and vegetable systems.
- Powder:Wettable powders retain cost advantage in manual backpack spraying operations across developing agricultural economies.
Liquid formulations absorb the precision agriculture investment wave. Powder retains share where labor substitution remains uneconomical.
Distribution Channel:
Channel control concentration is rebalancing price negotiation leverage away from manufacturers toward agronomic advisory-integrated distributors.
- Agricultural Cooperatives:Brazilian citrus and Australian wheat cooperatives consolidate procurement through season-long input bundling that combines bactericides, fungicides, and biostimulants. This channel control model compresses margin capture for standalone formulators.
- Direct Sales:Large-scale protected cultivation operators in Netherlands and Spain negotiate directly with registrants for customized tank-mix protocols. Direct relationships enable residue management traceability required by EFSA-aligned supermarket chains.
- Retail:Independent farm supply stores serve fragmented smallholder bases in Indian Punjab and Haryana contract farming clusters.
- Online:E-commerce platforms are emerging for specialty biological products in developed market hobby farming segments.
Cooperative bundling dominates volume. Direct sales capture premium customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper-based bactericide formulations first achieved industrial scale in European citrus groves during the early twentieth century, establishing formulation science foundations that now diffuse across export-oriented agricultural systems worldwide. Contemporary demand concentrates in five national markets where regulatory pressure and crop value density intersect.
United States
Fire blight management in Washington State pome fruit orchards and Florida citrus canker programs drive precision application investment. The EPA governs bactericide registration under FIFRA, mandating chronic toxicity studies that extend development timelines for new active ingredients. California's Central Valley vegetable producers are expanding drone-compatible liquid formulation procurement to meet labor cost reduction targets.
Brazil
São Paulo state citrus cooperatives represent the largest single-country demand pool for copper-based bactericides targeting Xanthomonas citri subsp. citri. ANVISA aligns residue tolerance frameworks with CODEX standards to preserve European export market access. Precision agriculture adoption in Minas Gerais coffee regions is accelerating ultra-low volume aerial application programs.
India
Smallholder contract farming clusters in Punjab and Haryana supplying export-oriented food processors are adopting residue-free biological protocols. The Central Insecticides Board under the Ministry of Agriculture mandates local efficacy trials that shape market access timelines for multinational registrants. Maharashtra's protected tomato cultivation belt is expanding integrated pest management consultant contracts to navigate biological transition pathways.
Netherlands
Greenhouse tomato and pepper producers in Westland and Almería clusters command the steepest per-hectare bactericide price premiums globally. EFSA-aligned maximum residue limit enforcement is compressing copper-based product authorization timelines while accelerating biological alternative registrations. Dutch formulation science expertise anchors European microbial biocontrol platform development.
Australia
Wheat and canola broadacre operations in New South Wales favor bundled procurement through distributor-managed tank-mix programs combining bactericides with fungicides and biostimulants. The APVMA regulates agricultural chemical registration with efficacy data requirements that parallel EPA frameworks. Western Australian grain cooperatives are consolidating season-long input purchasing decisions through channel-controlled advisory networks.
Crop Bactericides Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and bundled service integration. The market structures around three tiers: backward-integrated active ingredient synthesizers, formulation specialists with channel control, and regional distributors managing agronomic advisory relationships. Two dominant competitive moves are reshaping positioning: portfolio bundling that combines bactericides with adjacent crop protection categories, and precision application compatibility investments targeting drone and drip-irrigation infrastructure.
Within the backward-integrated synthesis tier, BASF SE and Syngenta Crop Protection AG exemplify captive supply strategies that insulate margin structures from input cost volatility. Nufarm Limited occupies a distinct position among channel-control specialists, leveraging regional agronomic advisory capabilities to consolidate procurement decisions in Australian and Latin American distribution networks. These three entities represent divergent archetypes—European-anchored integrated science platforms versus Asia-Pacific-originating channel specialists—each capturing value through different points in the value chain.
| Leading Market Players |
|---|
| Sumitomo Chemical Company Ltd. |
| Nufarm Limited |
| BASF SE |
| PI Industries |
| Adama Agricultural Solutions Ltd. |
| Syngenta Crop Protection AG |
| FMC Corporation |
| American Vanguard Corporation |
| Bayer Crop Science AG |
| Others |
Cost & Logistics Intelligence
Copper compound feedstock costs originating from Chilean and Peruvian mining operations cascade through formulation tiers, concentrating margin pressure on generic copper hydroxide producers while biological manufacturers capture premium positioning through fermentation-derived active ingredient sourcing.
Pricing Analysis
Three-tier pricing structure across premium biologicals, standard copper-based formulations, and economy wettable powders dominates procurement decisions. Price differentiation hinges on residue certification grade for EU export compliance and bundled agronomic advisory services. Pricing pressure stems from EFSA-driven copper authorization compression forcing portfolio restructuring toward higher-cost microbial alternatives. Smallholder contract farming clusters in India exhibit highest price sensitivity, while Dutch greenhouse operators absorb steepest per-hectare premiums for residue-free protocols.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers controlling streptomycin and kasugamycin active ingredient synthesis. Geographic supply concentration centers on China for antibiotic fermentation capacity, India for copper compound processing, and Brazil for regional formulation packaging. Raw material dependencies include copper ore concentrates, agricultural fermentation substrates, and petroleum-derived formulation carriers. Supply chain risk manifests through regulatory restriction exposure as EU biocidal product regulations narrow copper compound approvals. Distribution runs through agricultural cooperative bundling programs in Latin America and Australia, displacing direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU regulatory compression accelerating biological adoption and Indian smallholder contract farming demand for residue-free export protocols, exploiting the cost differential between synthetic chemistry R&D timelines and microbial biocontrol registration fast-tracks.
For Market Incumbents: Deploy backward integration into active ingredient synthesis to insulate margin structures from Chinese supply concentration. BASF SE exemplifies this lever through captive streptomycin production capacity. Channel control investments in Australian broadacre distribution networks defend against cooperative bundling displacement. Biological platform diversification addresses EFSA-driven copper authorization contraction threatening mature volume cores. For New Entrants and Emerging Players: India's Central Insecticides Board local efficacy trial requirements create procurement consolidation opportunities among export-oriented food processor supply chains. Drone-compatible liquid formulation development for Brazilian citrus cooperatives offers penetrable white-space targeting labor cost reduction priorities. Partnership-based label expansion strategies accelerate market access without captive synthesis infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where biological registration fast-tracks concentrate R&D investment among formulation specialists lacking distribution scale. Long-term viability favors acquirers targeting channel-control specialists with regional agronomic advisory capabilities over standalone active ingredient manufacturers. Signal to watch: EFSA zonal mutual recognition procedure acceleration rates indicating biological platform competitive window duration.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Registration Fast-Track Exploitation | EU Farm to Fork Strategy pesticide reduction targets compress microbial biocontrol approval timelines versus synthetic chemistry. |
| Precision Application Compatibility Investment | Drone and drip-irrigation formulation development absorbs capital from Brazilian citrus cooperatives seeking labor substitution. |
| Channel Control Consolidation | Agricultural cooperative bundling programs in Australia and Latin America concentrate price negotiation leverage with distributors. |
| Backward Integration into Active Synthesis | Captive streptomycin and copper compound production insulates formulators from Chinese supply concentration vulnerability. |
| Smallholder Contract Farming Partnership | India's domestic formulation partnerships accelerate label expansions for export-oriented food processor supply chains. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with crop protection R&D directors, regulatory affairs specialists at multinational registrants, agricultural cooperative procurement managers, and integrated pest management consultants informed demand-side assessments. Secondary sources include EPA FIFRA registration databases, EFSA biocidal product regulation filings, ANVISA residue tolerance frameworks, and Central Insecticides Board approval records. Bottom-up acreage and application rate modeling triangulated against top-down manufacturer revenue segmentation.
Rate-of-change decomposition across the analysis window isolates volume and value drivers through product chemistry transitions, formulation technology shifts, and channel structure evolution. Segmentation dimensions modeled include biological versus synthetic chemistry, liquid versus dry formulation, protected cultivation versus open-field application, and cooperative versus direct procurement channels. CAGRs derived from regression analysis of historical approval timelines, adoption curve patterns in comparable biological transitions, and regulatory acceleration scenarios. Industry-specific inputs incorporate EFSA zonal mutual recognition procedure throughput rates and drone application hardware penetration curves.
Underlying measurement precision varies by segment; copper-based mature product volumes carry tighter precision than biological adoption forecasts subject to efficacy variability and shelf stability uncertainties. Forecasts reflect assumptions regarding regulatory timeline compression, residue tolerance harmonization progress, and precision agriculture capital deployment patterns. Biological efficacy consistency, copper authorization contraction severity, and smallholder contract farming consolidation velocity constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
US Pest Control Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
South America Acaricides Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Soil Fumigant Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
North America Insecticide Market
Crop Protection
Nematicides Market