
 Urban Rooftop Farm-Safe Pest Management Chemistry Market | 2026-2036
Urban Rooftop Farm-Safe Pest Management Chemistry Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Rooftop Farm-Safe Pest Management Chemistry Market Insights
The EU Green Deal's pesticide reduction targets is hardening compliance requirements for biocidal formulations used in peri-urban food production. BASF leverages its microbial screening platforms to develop Bacillus-based insecticides tailored for enclosed rooftop environments. Koppert anchors European supply through its bumblebee pollination and biological control networks, while BioWorks competes with peroxyacetic acid sanitizers engineered for hydroponic reservoir maintenance.
Urban Rooftop Farm-Safe Pest Management Chemistry comprises synthetic and biological active ingredients formulated to eliminate arthropod, fungal, and rodent pests without leaving residues that exceed human toxicity thresholds in food harvested within meters of application sites; these chemistries typically carry OMRI or equivalent organic certification and degrade within 72 hours under UV exposure. Liquid concentrates dominate current procurement volumes due to compatibility with drone and backpack sprayer systems deployed on elevated growing surfaces, while insecticides represent the fastest-expanding product class as thrips, aphids, and whiteflies proliferate in warm, humid greenhouse environments above city centers. Edible flowers and small fruits command premium formulation prices because cosmetic damage tolerance approaches zero for restaurant and retail buyers.
The EPA regulates these chemistries under FIFRA with supplemental state-level 24(c) registrations for urban agricultural uses, while the EU's MDR and REACH frameworks constrain active ingredient approval timelines and residue monitoring protocols. Singapore's national parks authority and the UAE's MOHAP enforce municipal food safety standards that exceed baseline agricultural thresholds for rooftop-sourced produce. Stakeholders must monitor how municipal zoning boards reconcile pesticide buffer distances with building density codes as cultivation expands onto mixed-use structures.
Market Dynamics
The EPA's Food Quality Protection Act amendments and the EU's Farm to Fork Strategy pesticide reduction targets are compressing permissible exposure thresholds for chemistries applied within meters of human habitation, forcing reformulation cycles that favor rapid-degradation biocides.
Growth Catalysts
- EU Green Deal pesticide reduction targets:The 50% pesticide reduction mandate by 2030 is accelerating procurement of microbial insecticides and botanical extracts in Dutch and Belgian controlled-environment agriculture clusters.
- Singapore's 30-by-30 food security target:The city-state's mandate to produce 30% of nutritional needs locally by 2030 is expanding rooftop cultivation acreage and associated biocide demand.
- Drone-mounted precision spraying systems:Automated aerial application technology is enabling targeted biocide delivery on elevated growing surfaces, reducing labor costs and drift risk for commercial rooftop operators.
Market Restraints
- Active ingredient supply concentration:Fermentation-derived Bacillus thuringiensis strains and pyrethrin botanical extracts concentrate sourcing in Chinese and Indian contract manufacturers, creating input vulnerability.
- REACH registration timelines:The EU's 18-36 month active substance evaluation period delays market entry for novel biocidal formulations, compressing commercialization windows.
- UV degradation rate variability:Formulation stability under inconsistent urban UV exposure creates efficacy uncertainty that limits grower confidence in residue-free claims.
Strategic Opportunities
- UAE municipal food safety premium standards:MOHAP's residue thresholds below Codex Alimentarius baselines create a high-margin niche for certified-zero-residue formulations in Dubai and Abu Dhabi rooftop farms.
- Peroxyacetic acid-quaternary ammonium hybrid sanitizers:Converging fungicidal and reservoir disinfection chemistries into single-application products reduces labor inputs for hydroponic operators.
- Direct-to-grower digital distribution platforms:Bypassing traditional agrochemical distributors through specialized e-commerce channels serving urban agriculture clusters captures margin and accelerates technical support delivery.
Industry Challenges
- OMRI certification timeline compression:The 12-18 month organic materials review process delays product launches for rooftop growers requiring immediate residue-free verification for restaurant contracts.
- Cross-contamination protocols in mixed-use buildings:Reconciling pesticide buffer distances with residential occupancy in vertical farming structures requires case-by-case municipal zoning negotiations that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Rooftop Farm-Safe Pest Management Chemistry Market |
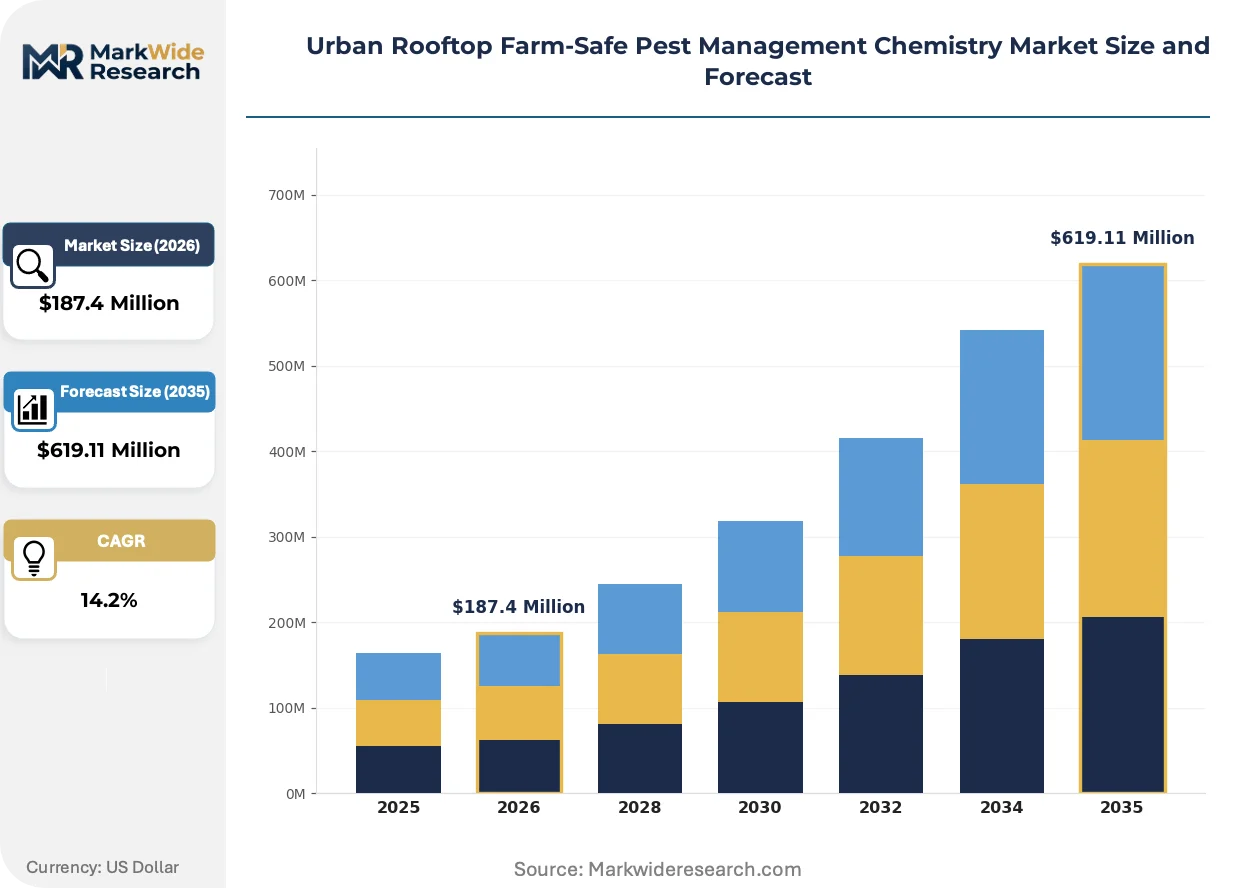
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Herbicides, Fungicides, Rodenticides, Miticides Application: Leafy Vegetables, Fruiting Crops, Herbs & Spices, Small Fruits, Edible Flowers Formulation: Liquid Concentrates, Wettable Powders, Granules, Emulsifiable Concentrates, Dusts End User: Rooftop Growers, Community Gardens, Urban Farmers, Research Institutions, Greenhouse Operators |
| Companies Covered | Koppert, Biobest, Andermatt Group, Certis Biologicals, BioWorks, BioSafe Systems, BASF, Bayer, Syngenta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Rooftop Farm-Safe Pest Management Chemistry Market Trends and Innovations
Formulation chemistry is pivoting toward bio-based actives with documented 48-72 hour degradation curves, while application hardware miniaturizes for constrained rooftop access. Regulatory frameworks are hardening residue monitoring protocols in parallel with urban cultivation expansion.
Electrostatic sprayer systems are electrifying application efficiency in enclosed rooftop greenhouses. Commercial operators in Singapore and the Netherlands are deploying handheld and drone-mounted units that reduce biocide volume by 40-60% through charged-droplet adhesion. The technology is electrifying competitive positioning by enabling precision application at wind speeds that disable conventional hydraulic systems.
REACH's 2023 amendments to biocidal product regulation are extending data requirements for endocrine disruption potential. Formulators must now submit additional mammalian toxicity studies that add 12-18 months to registration timelines. Small and mid-sized biocide developers are responding by withdrawing from the EU market or consolidating through partnership with larger registrants possessing existing dossiers.
Restaurant procurement departments are imposing zero-detectable-residue specifications that exceed regulatory minimums. Direct sourcing contracts with named rooftop farms are displacing wholesale distributor relationships in metropolitan food service channels. This specification escalation is most visible in New York, London, and Tokyo where Michelin-tier establishments market hyperlocal provenance as a competitive differentiator.
Urban Rooftop Farm-Safe Pest Management Chemistry Market Segmentation
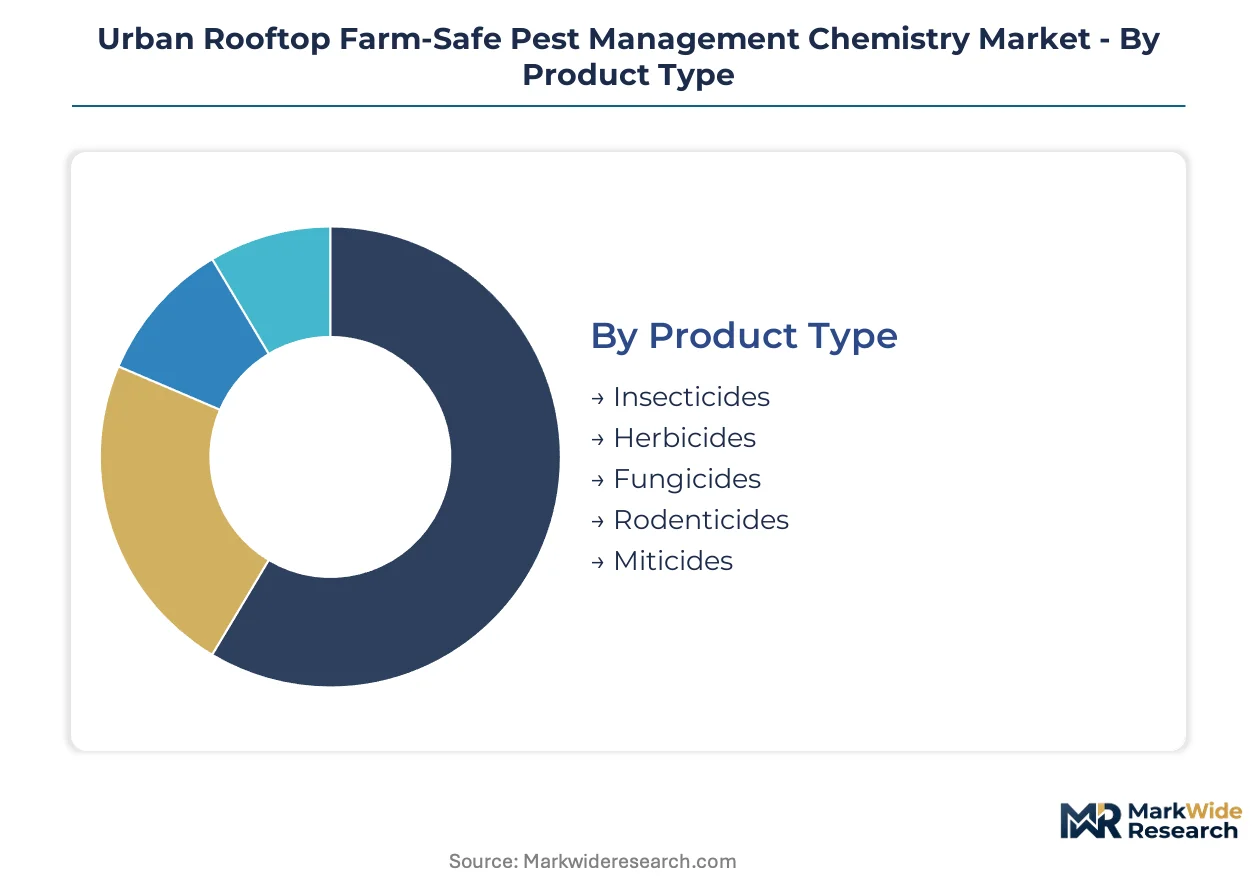
Segmentation reveals how formulation chemistry, crop sensitivity, and operator scale fragment procurement patterns across elevated growing environments. Each axis carries distinct regulatory exposure and margin profiles that reshape supplier prioritization.
Product Type:
Active ingredient selection pivots on degradation kinetics and residue thresholds imposed by proximity to human habitation.
- Insecticides:Pyrethrin and Bacillus thuringiensis formulations dominate thrips and aphid control in Singapore's controlled-environment clusters. Restaurant procurement contracts in New York and London mandate 48-hour degradation verification, compressing supplier certification timelines.
- Fungicides:Peroxyacetic acid and copper-based actives target powdery mildew in humid greenhouse environments above Dubai and Abu Dhabi. MOHAP's residue thresholds below Codex baselines force reformulation for UAE municipal compliance.
- Herbicides:Botanical extracts and acetic acid solutions manage weed pressure in substrate-based systems where mechanical cultivation is impractical.
- Rodenticides:Anticoagulant-free formulations with bittering agents protect stored seeds and infrastructure in mixed-use buildings with residential occupancy below.
- Miticides:Sulfur and horticultural oil emulsions address spider mite outbreaks in hydroponic strawberry and tomato operations.
Insecticides lead on scale; fungicides lead on momentum.
Application:
Crop cosmetic standards and harvest frequency reshape biocide specification intensity across produce categories.
- Edible Flowers:Zero-detectable-residue mandates from Michelin-tier establishments in Tokyo and London command premium formulation prices. Cosmetic damage tolerance approaches absolute zero, requiring electrostatic application systems that reduce drift risk.
- Small Fruits:Raspberry and blueberry cultivation in Dutch glasshouses drives demand for rapid-degradation miticides that clear residue windows before harvest. ECHA's REACH amendments extend data requirements for endocrine disruption screening.
- Leafy Vegetables:Short harvest cycles in Singapore's 30-by-30 program favor microbial insecticides with documented 72-hour UV degradation curves.
- Fruiting Crops:Tomato and pepper operations prioritize systemic resistance inducers compatible with integrated pest management protocols.
- Herbs & Spices:Aromatic oil preservation constraints limit synthetic pyrethroid use in basil and mint cultivation for direct restaurant supply.
Edible flowers capture the steepest premium tier; small fruits show the fastest volume expansion.
Formulation:
Physical state determines compatibility with automated application infrastructure and hydroponic system maintenance protocols.
- Liquid Concentrates:Dominant procurement volume due to drone and backpack sprayer compatibility on elevated growing surfaces with constrained access. Singapore's national parks authority specifies concentrate dilution ratios for municipal rooftop permits.
- Wettable Powders:Bacillus-based biologicals achieve extended shelf stability through desiccation, suplicating research institution procurement in the Netherlands where formulation storage precedes seasonal application windows.
- Granules:Soil-drench applications in substrate-based systems where liquid runoff risks hydroponic reservoir contamination.
- Emulsifiable Concentrates:Botanical oil blends for mite control requiring uniform foliar coverage in enclosed greenhouse environments.
- Dusts:Limited deployment in rooftop contexts due to wind drift concerns and respiratory exposure risks in dense urban corridors.
Liquid concentrates anchor current procurement; wettable powders are gaining share fastest in biological active segments.
End User:
Operator scale and commercial pressure reshape technical support requirements and certification urgency.
- Rooftop Growers:Commercial operators in Dubai and Abu Dhabi purchase certified-zero-residue formulations at premium prices to satisfy MOHAP municipal standards. Direct-to-grower digital platforms are displacing traditional agrochemical distributors.
- Greenhouse Operators:Dutch and Belgian controlled-environment clusters procure microbial screening services alongside biocide formulations, integrating supplier technical support into pest management protocols.
- Urban Farmers:Mixed-use building cultivators negotiate case-by-case buffer distances with municipal zoning boards, extending project timelines and compressing effective application windows.
- Community Gardens:Volunteer-managed sites prioritize cost-minimization over residue verification, creating price sensitivity at the specification threshold.
- Research Institutions:Field trial requirements for novel biocidal actives drive small-batch procurement with extended documentation obligations under EPA FIFRA and EU REACH frameworks.
Rooftop growers command the highest specification intensity; greenhouse operators provide the most stable recurring demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands pioneered modern controlled-environment agriculture in the 1960s, establishing glasshouse engineering standards that now propagate across dense metropolitan corridors worldwide. Dutch technical expertise in biological pest control continues to shape procurement specifications for residue-free chemistries in elevated growing environments.
Netherlands
Westland and Aalsmeer greenhouse clusters drive microbial insecticide procurement for thrips and whitefly management in tomato and ornamental production. The EU Green Deal's Farm to Fork pesticide reduction targets accelerate biological active ingredient adoption. Wageningen University research partnerships anchor formulation development for rapid-degradation biocides.
Singapore
The 30-by-30 food security mandate expands rooftop cultivation acreage across Housing & Development Board estates and commercial developments. Singapore's national parks authority enforces municipal biocide permit standards exceeding baseline agricultural thresholds. Sustenir Agriculture and ComCrop operations in Lim Chu Kang and Woodlands anchor demand for UV-degradable microbial formulations.
United Arab Emirates
MOHAP's residue thresholds below Codex Alimentarius baselines create premium pricing tiers for certified-zero-residue formulations. Dubai and Abu Dhabi rooftop farms supplying hotel restaurants and luxury retail command specification intensity unmatched in conventional agriculture. Emirates Bio-Fertilizer Factory and Badia Farms operations concentrate procurement in Jebel Ali and Al Ain industrial zones.
United States
New York and Chicago municipal zoning boards negotiate pesticide buffer distances with mixed-use building developers, extending project timelines for rooftop cultivators. The EPA's Food Quality Protection Act amendments tighten permissible exposure thresholds for chemistries applied within meters of residential occupancy. Brooklyn Grange and Gotham Greens operations in Queens and Chicago's Pullman District drive insecticide demand for aphid and spider mite control.
Germany
Bavarian and North Rhine-Westphalia controlled-environment clusters procure integrated biological control systems combining biocide formulations with pollinator management. ECHA's REACH amendments extend data requirements for endocrine disruption screening, delaying novel active substance approvals. Munich and Cologne metropolitan greenhouse operators favor Bacillus-based formulations with documented 48-hour degradation curves.
Urban Rooftop Farm-Safe Pest Management Chemistry Market Competitive Landscape
Capital-heavy fermentation producers compete with asset-light formulation specialists across the biocide value chain, creating a tiered supplier structure. Market concentration remains moderate, with biological active ingredient developers occupying distinct niches from synthetic chemistry incumbents. Three archetypes dominate: multinational agrochemical conglomerates with microbial screening platforms, specialized biological control firms with pollination service integration, and regional sanitization chemistry providers. Competitive positioning hinges on registration dossier depth and direct-to-grower technical support capabilities rather than manufacturing scale alone.
Among European biological control specialists, Koppert and Biobest exemplify the pollination-integrated service model, while BASF represents the multinational platform approach with microbial screening infrastructure. Andermatt Group and Certis Biologicals occupy mid-tier positions emphasizing organic certification breadth. BioWorks and BioSafe Systems anchor North American sanitization chemistry supply for hydroponic reservoir maintenance.
| Leading Market Players |
|---|
| Koppert |
| Biobest |
| Andermatt Group |
| Certis Biologicals |
| BioWorks |
| BioSafe Systems |
| BASF |
| Bayer |
| Syngenta |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between OMRI-listed biologicals and conventional synthetics fragments procurement economics across Dutch glasshouse clusters and Singapore HDB estates. Premium formulations commanding three-to-four-fold markups over commodity chemistries trace directly to fermentation batch consistency and REACH dossier depth, while contract manufacturers in India and China anchor cost-competitive supply for unregistered botanical extracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the biocide market by residue certification intensity and degradation documentation. MOHAP-certified zero-residue formulations in Dubai command the highest tier, while standard microbial insecticides serve Dutch greenhouse operators, and economy-grade acetic acid solutions supply community gardens. Price differentiation hinges on organic certification status and UV-degradation verification protocols. Pricing pressure stems from REACH registration cost inflation compressing margins for mid-tier developers. Community garden operators exhibit highest price sensitivity; luxury hotel procurement departments show least.
Supply Chain Analysis
Reverse-logistics infrastructure for expired biological formulations remains underdeveloped across urban agriculture corridors, creating disposal cost uncertainty for rooftop operators. Fermentation-derived Bacillus thuringiensis concentrates supply from China, India, and the Netherlands, while pyrethrin botanical extracts source primarily from Kenya and Tasmania. Raw material dependencies include molasses feedstock, specialized fermentation vessels, and cold-chain distribution assets. Supply chain risk centers on single-source vulnerability for heat-tolerant Bt strain banks. Distribution runs through direct-to-grower digital platforms displacing traditional agrochemical distributors in Singapore and UAE municipal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in formulation services bundling degradation verification with biocide supply, as regulatory documentation costs shift from grower to supplier. Premium-tier displacement of commodity synthetics accelerates where municipal food safety standards exceed baseline agricultural thresholds.
For Market Incumbents: Extend technical service capabilities into degradation curve documentation and municipal permit navigation to defend against asset-light digital distributors. Consolidate fermentation capacity in the Netherlands and Singapore to secure supply proximity for controlled-environment clusters. OMRI certification backlog pressure threatens mid-tier biological developers with 12-18 month launch delays. For New Entrants and Emerging Players: EU Green Deal pesticide reduction targets in the Netherlands and Belgium open a window for rapid-degradation microbial formulations with documented 48-hour UV clearance. White-space targets include peroxyacetic acid-quaternary ammonium hybrid sanitizers for hydroponic reservoir maintenance and drone-compatible concentrate packaging for Singapore rooftop operators. Direct-to-grower subscription models bypass distributor margin capture. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration timelines exceed 24 months and dossier costs exhaust standalone developer balance sheets. Long-term viability favors platform players combining microbial screening infrastructure with existing EU regulatory approvals. Acquisition target archetype: regional sanitization chemistry providers with municipal food safety relationships in UAE and Singapore. Signal to watch: withdrawal of small-scale developers from EU biocidal product regulation submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive Bt strain production secures supply continuity for Koppert and BASF against Indian contract manufacturer concentration. |
| Direct-to-Grower Digital Platform Launch | Bypasses traditional agrochemical distributors in Singapore and Dubai to capture 15-20 point margin expansion. |
| REACH Dossier Partnership Consolidation | Small developers merge registration efforts with BASF or Bayer to survive 18-36 month active substance evaluation periods. |
| Drone-Compatible Concentrate Formulation | Electrostatic application systems in Dutch glasshouses reduce biocide volume by 40-60 percent through charged-droplet adhesion. |
| Municipal Food Safety Certification Program | MOHAP and Singapore National Parks Authority standards create defendable premium tiers for certified-zero-residue suppliers. |
Research Methodology
Multiple input streams — biocide formulation technical directors, municipal food safety regulators, controlled-environment agriculture procurement leads, and drone application system engineers — were reconciled against customs trade data, EPA FIFRA registration databases, ECHA biocidal product regulation filings, and Singapore National Parks Authority permit records. Primary interviews with rooftop farm operators in Dubai, Singapore, and New York supplied application frequency and specification intensity parameters. Bottom-up volume estimates from individual cultivation sites aggregated against top-down market sizing from supplier shipment disclosures.
Historical degradation curve documentation and panel-based procurement intention surveys were cross-referenced to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include active ingredient class, crop cosmetic sensitivity tier, formulation physical state, and operator scale archetype. CAGRs derived from logistic adoption curves fitted to controlled-environment agriculture expansion trajectories in target metropolitan corridors. Industry-specific forecast inputs incorporated REACH amendment implementation timelines and Singapore 30-by-30 acreage targets.
Revisions become necessary when municipal zoning boards alter pesticide buffer distance requirements or when UV degradation rate variability under urban canyon conditions invalidates residue clearance assumptions. Forecasts reflect documented degradation kinetics and regulatory approval timelines subject to ECHA workload fluctuations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Canada Nematicides Market
Crop Protection
Pest Control Services Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
North America Nematicides Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Tebufenozide Market
Crop Protection
Metamifop Market