
 Pest Resistant Crops Market | 2026-2036
Pest Resistant Crops Market Size, Share, and Industry Trends Forecast 2026-2036
Pest Resistant Crops Market Analytics
RNA interference is realigning input economics as seed treatments partially displace broad-spectrum chemical pesticides. Bayer AG leverages its TraitForge platform to stack multiple resistance genes in single germplasm lines. Syngenta AG anchors its position through integrated seed-and-crop-protection bundles that lock in multi-year grower contracts. Corteva Agriscience differentiates via CRISPR-edited native traits that bypass certain regulatory pathways in key jurisdictions.
Pest resistant crops comprise germplasm engineered or selected to express toxic proteins, RNAi molecules, or physical barriers that deter, kill, or suppress target herbivores, pathogens, or nematodes; Bt endotoxins from Bacillus thuringiensis remain the most deployed protein class, typically expressed at parts-per-thousand concentrations in plant tissues, with refuge requirements mandating non-resistant acreage to delay resistance evolution. Genetically modified varieties dominate planted hectares and capture the bulk of trait licensing revenue, while traditional breeding segments expand fastest in markets with restrictive biotechnology regulations where marker-assisted selection accelerates introgression of quantitative resistance loci. Organic and synthetic categories occupy niche positions, with organic limited by certification constraints on genetic modification and synthetic approaches still scaling from laboratory validation to field performance.
USDA-APHIS oversees interstate movement and environmental release of regulated articles under the Plant Protection Act, while EPA mandates insect resistance management plans for all registered plant-incorporated protectants; in parallel, FDA evaluates food safety of novel proteins through its voluntary consultation process. The EU Green Deal and F-Gas Regulation indirectly shape demand by constraining fumigant and pesticide alternatives, pushing growers toward resistant germplasm. Stakeholders must monitor evolving coexistence thresholds between biotech and conventional seed systems as export-dependent markets tighten adventitious presence limits.
Market Dynamics
CRISPR-based gene editing is compressing development timelines from over a decade to under five years, while EPA-mandated refuge requirements force continuous seed portfolio refresh cycles that reshape R&D resource allocation across the sector.
Growth Catalysts
- RNAi seed treatments:Farmers in Brazil's Cerrado region are adopting RNA interference molecules that silence essential pest genes, reducing chemical pesticide passes from four to two per season.
- EU F-Gas Regulation:Restrictions on soil fumigants are pushing Spanish and Italian vegetable growers toward nematode-resistant tomato and pepper varieties.
- Fall armyworm pressure:Sub-Saharan maize producers face yield losses exceeding fifty percent in untreated fields, accelerating demand for Bt-stacked hybrids.
Market Restraints
- Regulatory asynchrony:Brazil's ANVISA approves traits faster than EU EFSA processes, creating trade friction for soybean exporters.
- Refuge mandate costs:EPA requirements for non-resistant acreage reduce effective planted area and complicate farm management.
- Resistance evolution velocity:Target pests develop counter-adaptations within eight to twelve generations, compressing trait efficacy windows.
Strategic Opportunities
- India's regulatory opening:CDSCO streamlined biosafety protocols in 2023, creating first-mover advantage for cotton and brinjal trait developers.
- CRISPR-native trait stacking:Combining multiple resistance mechanisms without transgenic markers bypasses certain EPA and EFSA review pathways.
- Direct-to-grower digital platforms:Seed companies are building proprietary e-commerce channels that displace traditional distributor networks in Argentina.
Industry Challenges
- Gene editing talent scarcity:Plant molecular biologists with CRISPR expertise command premium salaries that strain mid-tier breeding program budgets.
- Adventitious presence thresholds:Japan's Ministry of Agriculture maintains strict low-level presence limits that complicate bulk commodity shipments from multi-trait production zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pest Resistant Crops Market |
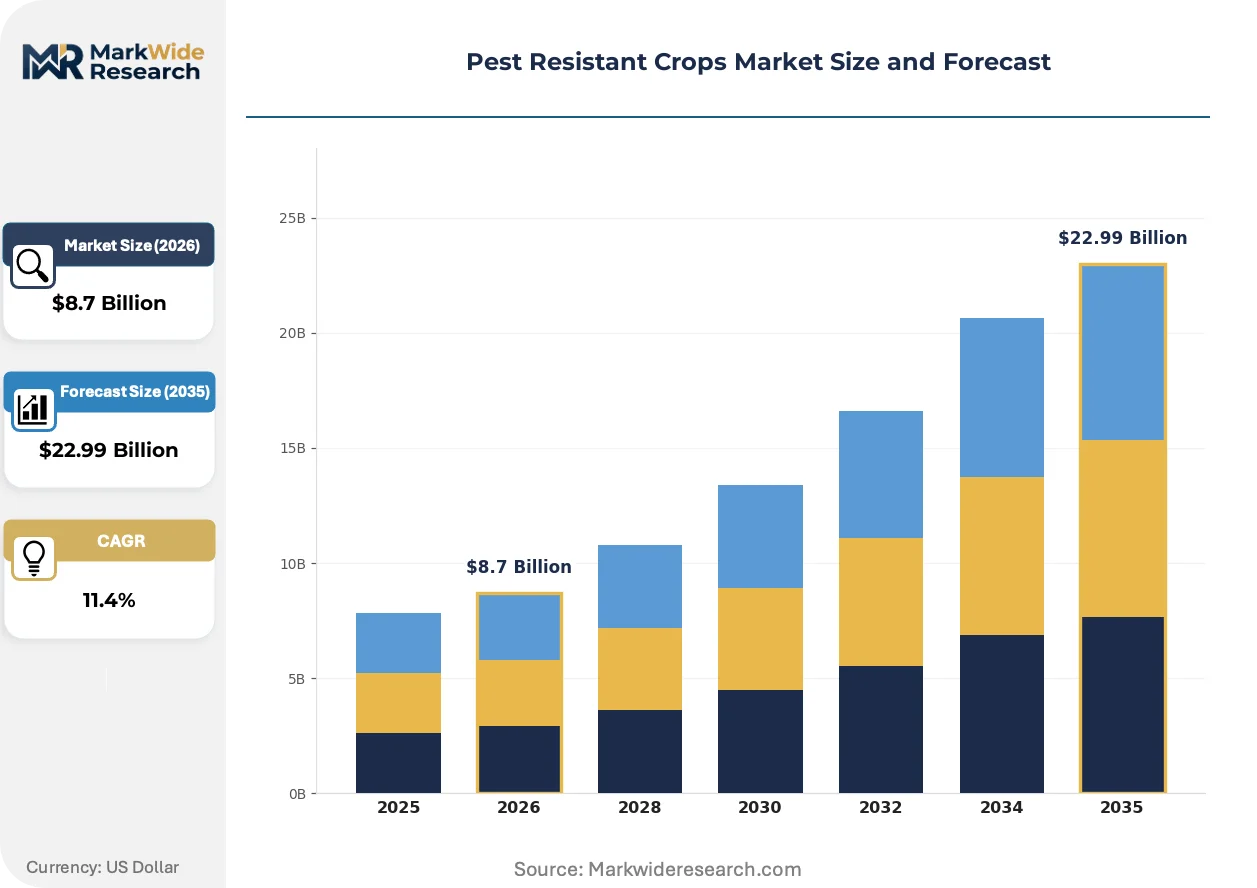
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetically Modified, Traditional Breeding, Organic, Synthetic Usage Type: Commercial Farming, Home Gardening, Research, Seed Production Crop Category: Cereals, Vegetables, Fruits, Pulses Distribution Channel: Direct Sales, Retail, Online Stores, Distributors |
| Companies Covered | Bayer AG, Syngenta AG, Corteva Agriscience, BASF SE, Limagrain, KWS SAAT SE, Sakata Seed Corporation, Rijk Zwaan, Advanta Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pest Resistant Crops Market Evolving Landscape
Gene editing platforms are rewriting competitive economics by collapsing the cost curve for trait development, while regulatory frameworks struggle to categorize novel techniques that blur traditional biotechnology boundaries.
CRISPR-Cas9 multiplex editing is consolidating control over complex resistance pathways. Breeders now target three to five pest susceptibility genes simultaneously in single transformation events. Large-scale corn and soybean operations in Iowa and Illinois are field-testing these stacked-native varieties ahead of broader commercial release. The technology is consolidating R&D spending toward platform capabilities rather than single-trait licensing deals.
EU Green Deal implementation is tightening pesticide reduction targets through 2030. Member states must cut chemical plant protection product use by fifty percent, forcing growers toward genetic solutions. Vegetable seed producers in the Netherlands are accelerating marker-assisted selection programs to meet this demand compression timeline.
Outcome-based contracting is reshaping how Brazilian growers purchase seed-and-crop-protection bundles. Multi-year performance guarantees now tie payment to actual pest suppression metrics rather than input delivery. Large-scale Mato Grosso operations are piloting these arrangements with integrated suppliers, shifting risk allocation from farmer to technology provider.
Pest Resistant Crops Market Segmentation
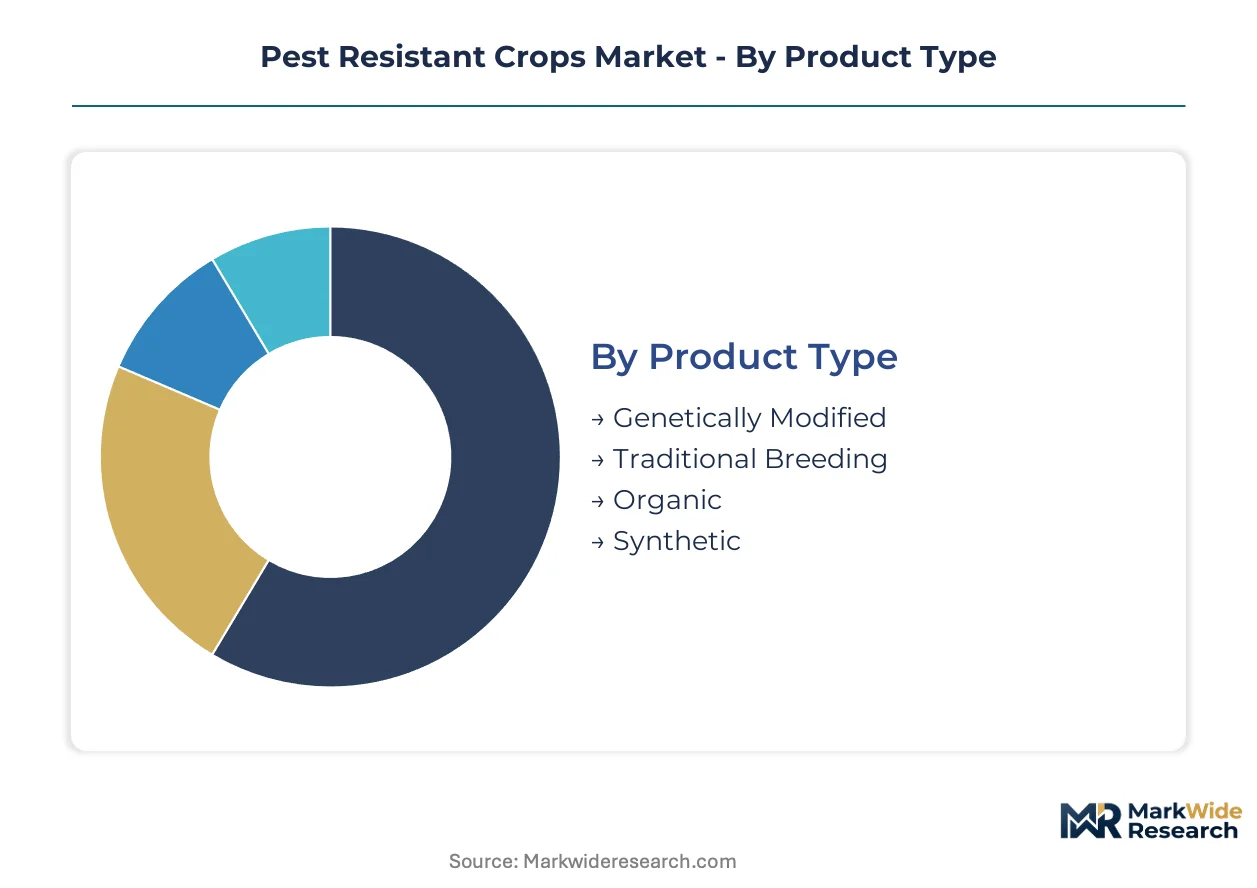
Pest resistant crops segment along four critical dimensions that determine pricing power, regulatory pathway, and customer acquisition cost. Product type dictates development timeline and approval burden. Usage type shapes volume concentration and service intensity requirements.
Product Type:
Supply concentration clusters around platforms with regulatory clarity and established trait licensing infrastructure.
- Genetically Modified:Transgenic varieties expressing Bt endotoxins or other foreign proteins dominate planted hectares and capture the majority of trait licensing revenue. Demand concentrates in Brazil's Mato Grosso and Goiás states where fall armyworm pressure on corn and soybean operations makes premium seed economics compelling despite refuge mandates.
- Traditional Breeding:Marker-assisted selection accelerates introgression of quantitative resistance loci without transgenic markers. European vegetable growers facing EU Green Deal pesticide reduction targets drive fastest expansion here as these varieties bypass EFSA's lengthy GMO assessments.
- Organic:Certification constraints on genetic modification limit this segment to naturally occurring resistance traits identified through participatory breeding programs.
- Synthetic:Laboratory-validated approaches including engineered microbiome associations remain pre-commercial with field performance data still accumulating.
Genetically modified varieties absorb the bulk of installed capacity; traditional breeding is expanding most quickly.
Usage Type:
Customer scale determines service model economics and contract structure complexity.
- Commercial Farming:Large-scale operations in Iowa, Illinois, and Brazil's Cerrado purchase through multi-year bundled contracts with performance guarantees. These customers drive R&D prioritization through volume commitments and data sharing agreements.
- Seed Production:Specialized growers maintain genetic purity and trait integrity for downstream licensing, requiring intensive field monitoring and isolation protocols.
- Research:University and institutional breeding programs access pre-commercial germplasm through material transfer agreements with limited field trial scope.
- Home Gardening:Consumer seed packets represent minimal revenue per unit but build brand recognition and trait familiarity among future commercial decision-makers.
Commercial farming commands the dominant share of revenue; seed production carries the highest margin per hectare.
Crop Category:
Biology of pest interaction and value per hectare shape investment allocation across crop types.
- Cereals:Corn and wheat resistance programs target lepidopteran pests and Fusarium pathogens with the largest absolute R&D budgets in the sector. Iowa and Illinois field stations generate the bulk of performance data.
- Vegetables:Tomato and pepper nematode resistance commands premium pricing in Spain and Italy where fumigant restrictions under EU F-Gas Regulation have eliminated chemical alternatives.
- Pulses:Soybean cyst nematode resistant varieties anchor Brazilian seed portfolios with stacked trait packages.
- Fruits:Perennial crop resistance programs face extended development timelines due to juvenility periods and clonal propagation requirements.
Cereals capture the greatest absolute investment; vegetables show the steepest expansion trajectory.
Distribution Channel:
Channel choice reflects customer scale, geographic density, and service requirements.
- Distributors:Independent seed dealers with agronomic expertise dominate in fragmented farming regions of Argentina and the US Corn Belt, offering credit terms and localized advice.
- Direct Sales:Large-scale Mato Grosso operations and Iowa cooperatives purchase directly from breeders, bypassing margin layers and securing volume discounts.
- Retail:Farm supply stores serve mid-scale operators with immediate availability and established relationships.
- Online Stores:Proprietary e-commerce platforms are displacing traditional networks in Argentina where integrated suppliers seek direct customer data capture.
Distributors maintain the widest geographic footprint; direct sales channels are gaining share fastest among large operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial farming operations in Brazil, the United States, and India generate the majority of trait licensing demand, with regulatory divergence between jurisdictions creating distinct competitive dynamics for germplasm developers.
United States
Iowa and Illinois corn operations drive North American adoption of Bt-stacked hybrids targeting lepidopteran pests. EPA mandates insect resistance management plans with refuge requirements for all registered plant-incorporated protectants. Field stations across the Corn Belt generate performance data that shapes R&D prioritization for stacked-native varieties.
Brazil
Soybean and corn farmers in Mato Grosso and Goiás face mounting pressure from fall armyworm and soybean cyst nematode infestations. ANVISA approves traits faster than European counterparts, creating first-mover advantage for developers. Large-scale Cerrado operations pilot outcome-based contracting with integrated seed-and-crop-protection bundles.
India
Cotton and brinjal growers in Maharashtra and Gujarat accelerate adoption following CDSCO's 2023 biosafety protocol streamlining. The national agricultural regulator reduced approval timelines for genetically modified varieties. Participatory breeding programs in western states identify naturally occurring resistance traits for organic certification compliance.
Germany
Vegetable seed producers in Bavaria and Lower Saxony accelerate marker-assisted selection programs to meet EU Green Deal pesticide reduction targets. EFSA's lengthy GMO assessments push demand toward traditionally bred resistant varieties. Research clusters around Munich and Hanover develop CRISPR-edited native traits that bypass certain review pathways.
Spain
Tomato and pepper growers in Almería and Murcia shift toward nematode-resistant varieties as EU F-Gas Regulation eliminates soil fumigant alternatives. The country's national agricultural regulator enforces coexistence thresholds between biotech and conventional seed systems. Greenhouse operations in southeastern provinces command premium pricing for resistant germplasm.
Pest Resistant Crops Market Competitive Landscape
Trait stacking and CRISPR-based gene editing dominate the current landscape as seed developers compress development timelines and differentiate through regulatory pathway optimization. The market consolidates around integrated platforms with established licensing infrastructure and multi-year grower contracts. Three archetypes prevail: diversified agrochemical conglomerates with seed-and-crop-protection bundles, specialized breeding houses with regional germplasm expertise, and gene editing platform companies with reduced regulatory burden strategies. M&A activity and technology licensing agreements represent the primary competitive moves as mid-tier programs seek access to CRISPR capabilities.
Within the diversified agrochemical tier, Bayer AG and Syngenta AG exemplify integrated platform operators with global trait licensing infrastructure. Corteva Agriscience occupies a distinct position through CRISPR-edited native trait development. Among specialized European breeders, KWS SAAT SE and Rijk Zwaan represent regionally anchored germplasm houses with established vegetable and cereal portfolios. Japanese seed specialists including Sakata Seed Corporation exemplify quality-focused operators with concentrated research in protected cropping systems.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| BASF SE |
| Limagrain |
| KWS SAAT SE |
| Sakata Seed Corporation |
| Rijk Zwaan |
| Advanta Seeds |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty seed distributors in Argentina and the US Corn Belt now control critical inventory nodes, compressing working capital cycles while enforcing stricter payment terms that reshape breeder-to-grower economics.
Pricing Analysis
Volume concentration among Mato Grosso cooperatives and Iowa farming operations drives margin compression at the standard tier, while premium CRISPR-edited native varieties command pricing power through regulatory pathway advantages. Three-tier pricing structure across premium trait-stacked, standard single-trait, and economy conventional seed separates performance-guaranteed bundles from commodity offerings. Pricing pressure stems from Brazilian farmers negotiating outcome-based contracts that shift pest suppression risk to technology providers. Mid-scale operators in Argentina show highest price sensitivity; large-scale Cerrado purchasers prioritize performance metrics over unit cost.
Supply Chain Analysis
Brazil's ANVISA domestic-content mandates for trait approval trials are reshaping sourcing, forcing germplasm developers to maintain local breeding stations and field testing infrastructure. Supply concentrates in the United States, Brazil, and Germany, with proprietary trait platforms drawing from CRISPR reagent suppliers, marker-assisted selection labs, and certified seed multiplication fields. Single-source vulnerability runs through concentrated gene editing enzyme production. Distribution runs through integrated seed-and-crop-protection bundles in Brazil, while independent distributors with credit capacity dominate the US Corn Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene editing talent scarcity and CRISPR platform consolidation create supply-constrained conditions that prop pricing for developers with established regulatory pathways.
For Market Incumbents: Lock in multi-year grower contracts through outcome-based performance guarantees before CDSCO streamlining accelerates Indian competition. Acquire CRISPR-native breeding capabilities to bypass EPA refuge mandate costs threatening margin structures in corn and soybean segments. Channel control through proprietary e-commerce platforms in Argentina displaces distributor margin capture. For New Entrants and Emerging Players: Direct-to-grower digital platforms in Argentina's fragmented farming regions offer lowest customer acquisition cost versus established distributor networks. Target vegetable seed production in Spain and Italy where EU F-Gas Regulation eliminates chemical alternatives and EFSA GMO assessments push demand toward traditionally bred varieties. Pursue marker-assisted selection partnerships with Netherlands-based research clusters to access EU Green Deal-driven demand without transgenic regulatory burden. For Investors and Strategic Acquirers: CDSCO's 2023 biosafety protocol streamlining is the leading indicator that Indian cotton and brinjal trait markets are approaching inflection toward scalable licensing revenue. Target acquisition profiles center on mid-tier breeding programs with established regional germplasm libraries and pending CRISPR platform licensing agreements. Watch for EPA insect resistance management plan modifications as signal of refuge mandate relaxation that would reshape R&D allocation economics.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Native Trait Stacking | Combines multiple resistance mechanisms without transgenic markers, bypassing certain EPA and EFSA review pathways. |
| Outcome-Based Contracting | Ties Brazilian grower payments to actual pest suppression metrics, shifting risk allocation from farmer to technology provider. |
| Direct-to-Grower Digital Platforms | Proprietary e-commerce channels in Argentina displace traditional distributor networks and capture customer data. |
| Marker-Assisted Selection Acceleration | Netherlands vegetable seed producers deploy this to meet EU Green Deal pesticide reduction targets without GMO assessments. |
| Multi-Year Bundled Contracts | Lock in Iowa and Illinois corn operations with performance guarantees and data sharing agreements. |
Research Methodology
Independent corroboration across seed company trait development executives, Brazilian agronomic consultants, EPA regulatory affairs specialists, and Iowa cooperative procurement managers underwrites the qualitative findings. Secondary validation draws from USDA-APHIS permit databases, ANVISA approval registries, EFSA scientific opinions, and CDSCO biosafety committee minutes. Bottom-up acreage adoption estimates triangulate against top-down trait licensing revenue reported in SEC filings across the analysis window.
Comparable-period anchoring to historical Bt trait adoption curves in Brazil and the United States shapes the projection horizon's baseline assumptions. Segmentation modeling incorporates product type, crop category, usage scale, and distribution channel dimensions. CAGRs derive from acreage expansion rates weighted by trait fee structures and refuge mandate adjustments. Forecast inputs include fall armyworm pressure indices in Sub-Saharan Africa and soybean cyst nematode infestation severity in Brazil's Cerrado.
The model holds under stable regulatory pathway differentiation between gene editing and transgenic categories; deviation in EPA or EFSA reclassification of CRISPR-native traits would shift competitive positioning and pricing power. Forecasts reflect assumptions regarding ANVISA approval velocity and EU Green Deal implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Indonesia Fungicide Market
Crop Protection
Avicides Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Europe Herbicide Market
Crop Protection
United States Nematicides Market
Crop Protection
Europe Nematicide Market