
 Global Organophosphate Pesticide Market | 2026-2036
Global Organophosphate Pesticide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organophosphate Pesticide Market Foresight
Aftermarket service revenue from resistance-management advisory programs is reshaping margin distribution across the organophosphate value chain. FMC Corporation leverages its global field-scout network to sustain grower loyalty through integrated pest management bundling. Sumitomo Chemical anchors its position in Asia-Pacific through captive production of malathion intermediates. Syngenta Group competes on digital agronomy platforms that layer prescription mapping over traditional chemical sales.
Organophosphate pesticides are synthetic esters of phosphoric acid that inhibit acetylcholinesterase enzyme activity in target arthropods, with molecular weights typically ranging from 300 to 400 g/mol and field application rates of 0.5 to 2.0 kg active ingredient per hectare depending on crop-pest complex. Their primary commercial purpose remains broad-spectrum control of chewing and sucking insects in high-value and commodity agriculture where rotational chemistry is required. Chlorpyrifos and malathion formulations dominate the product-type segment, though diazinon retains structural importance in residential and livestock applications where mammalian toxicity profiles favor shorter residual compounds. Emulsifiable concentrates lead the formulation category by volume, yet soluble powders are gaining share in precision-application equipment markets where tank-mix compatibility and drift reduction command price premiums.
The EPA's revised human health risk assessment for chlorpyrifos and the EU's REACH authorization restrictions are constraining active ingredient availability while accelerating registration of reduced-risk organophosphate analogs. India's CDSCO and Central Insecticides Board maintain parallel registration pathways that influence export-oriented manufacturers' product development priorities. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chemistries will retain multi-country label access versus face phased withdrawal.
Market Dynamics
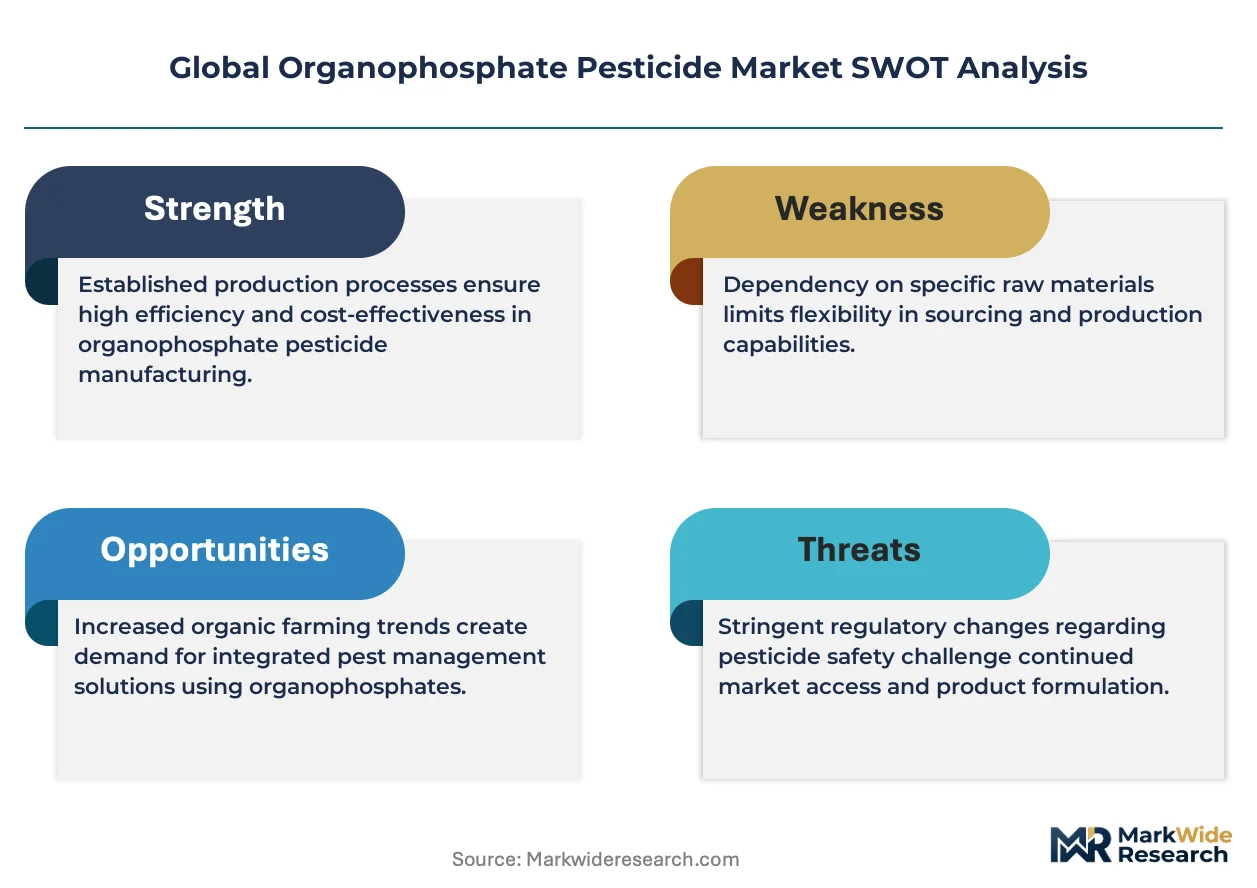
Regulatory divergence between jurisdictions is fragmenting active ingredient availability and forcing manufacturers to maintain parallel formulation portfolios for different export markets.
Growth Catalysts
- Seed treatment expansion:Row-crop growers in Brazil and Argentina are adopting systemic organophosphate coatings to protect germinating soybeans and corn from soil-borne wireworms and root maggots.
- India's PLI scheme:The Production Linked Incentive program for agrochemical manufacturing is attracting technical-grade active ingredient production to Gujarat and Maharashtra industrial corridors.
- REACH authorization pathways:ECHA's transitional arrangements for existing active substances are enabling continued malathion and diazinon use in professional pest control while chlorpyrifos phases out.
Market Restraints
- Feedstock volatility:Phosphorus trichloride and methanol price swings from Chinese petrochemical complexes compress formulation margins during procurement cycles.
- Regulatory friction:EPA's revised chlorpyrifos tolerances and state-level prohibitions in California and New York are eliminating label uses faster than replacement chemistries gain registration.
- Biological substitution:Bacillus thuringiensis and entomopathogenic nematode products are capturing share in high-value horticulture where residue limits favor non-synthetic approaches.
Strategic Opportunities
- Vietnam horticultural exports:Dragon fruit and mango shipments to EU and Japanese markets require approved residue profiles that organophosphate-based integrated pest management programs can satisfy.
- Drone application compatibility:Ultra-low volume formulations soluble in 2-5 liter water carriers are opening precision agriculture channels in Australian broadacre wheat and canola operations.
- Resistance management bundling:Aftermarket advisory services pairing organophosphate rotations with pheromone monitoring systems create recurring revenue streams beyond chemical sales.
Industry Challenges
- Toxicology specialist scarcity:Registration dossier preparation for new organophosphate analogs requires mammalian and ecotoxicology expertise concentrated in Basel, Research Triangle Park, and Hyderabad contract research organizations.
- Manufacturing asset reconfiguration:Chlorpyrifos-specific synthesis trains require 18-24 month conversion timelines and capital outlays to produce alternative phosphorothioate chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organophosphate Pesticide Market |
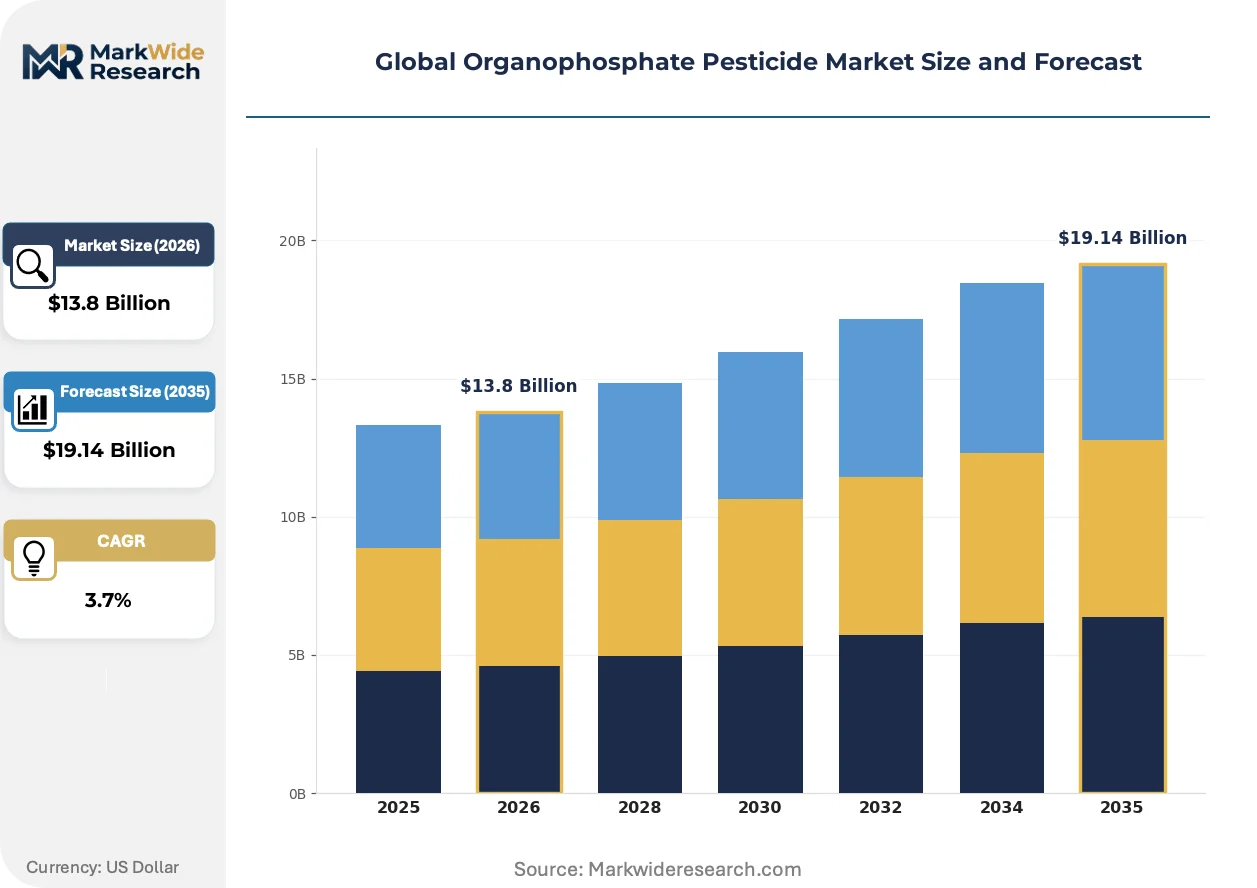
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $19.14 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorpyrifos, Malathion, Diazinon, Phosmet Application: Agricultural Crops, Residential, Industrial, Livestock Formulation: Granules, Liquids, Emulsifiable Concentrates, Soluble Powders Distribution Channel: Online Retail, Agricultural Distributors, Retail Stores, Direct Sales |
| Companies Covered | FMC Corporation, Sumitomo Chemical Co., Ltd., Syngenta Group, Corteva Agriscience, Adama Agricultural Solutions, Bayer AG, UPL Limited, Nufarm Limited, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organophosphate Pesticide Market Shifts & Advancements
Formulation chemistry and application technology are converging to extend organophosphate utility in markets where regulatory pressure is narrowing the approved product pipeline.
Microencapsulation technology using polyurea and gelatin-gum arabic wall systems is extending field persistence of malathion and acephate through controlled release mechanisms. Vegetable seed companies in the Netherlands and Spain are specifying encapsulated formulations for coated seed applications where dust-off reduction protects pollinator populations. This delivery innovation is rendering obsolete traditional emulsifiable concentrate tank-mixes in high-value protected cropping systems.
EPA's revised human health risk assessment for chlorpyrifos and associated tolerances revocation is eliminating food uses while accelerating registration of reduced-risk organophosphate analogs with shorter environmental half-lives. Formulators are pivoting toward diazinon and malathion for residential and livestock applications where exposure pathways differ. The regulatory compression is most acute in California's Central Valley, where permanent crop growers face immediate loss of key materials without equivalent replacement chemistries.
Aftermarket resistance-management advisory programs are unbundling from chemical sales and commanding separate subscription fees based on scouting intensity and prescription mapping granularity. Large row-crop operations in the US Corn Belt and Brazilian Cerrado are contracting integrated pest management services that bundle pheromone trapping, weather-based disease models, and rotational chemistry recommendations. This service-layer expansion is most visible in Iowa and Mato Grosso soybean systems where herbicide-resistant weed pressure has trained growers to value proactive resistance prevention.
Global Organophosphate Pesticide Market Segmentation
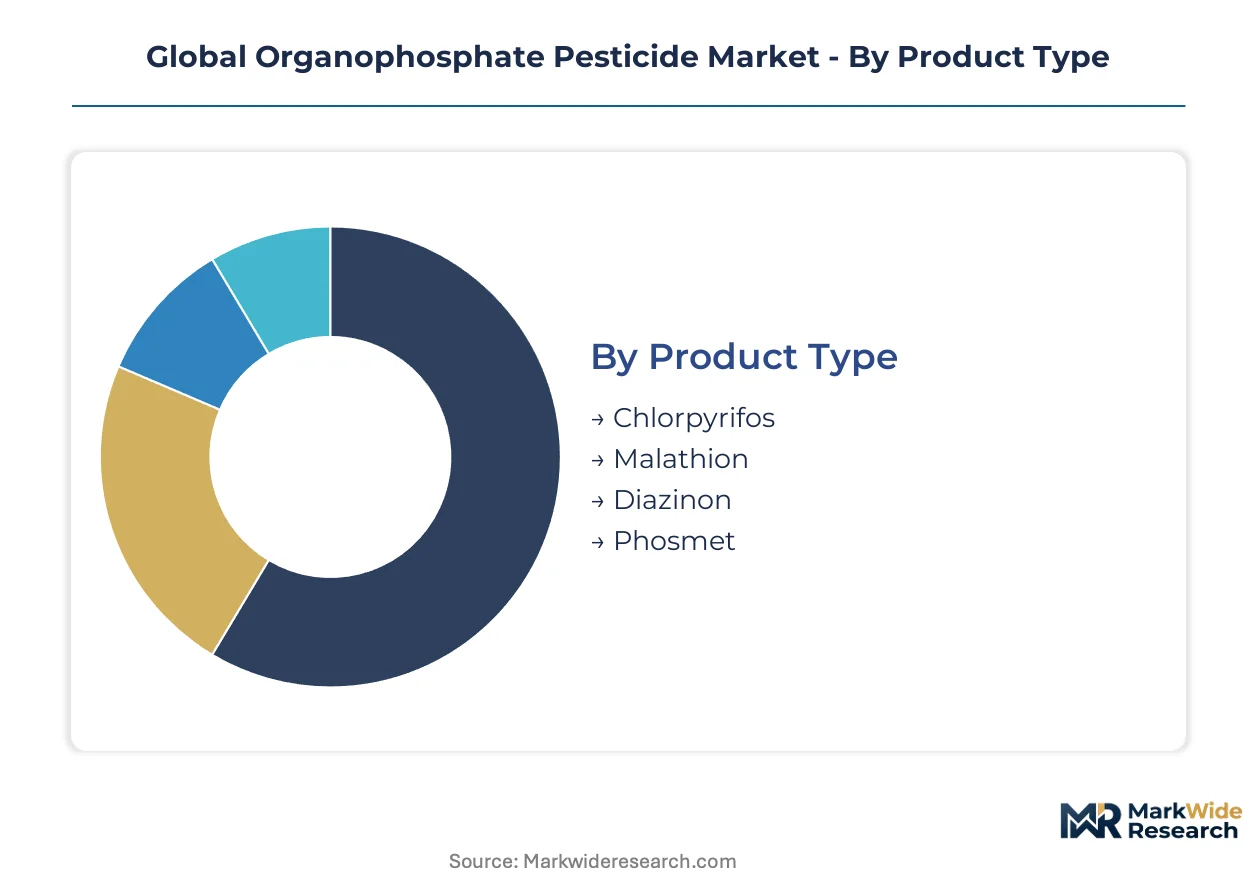
Segmentation in organophosphate pesticides reveals how regulatory pressure and application technology are reshaping product portfolios. Manufacturers must align formulation chemistry with jurisdiction-specific label approvals and precision agriculture equipment compatibility.
Product Type:
Active ingredient selection tracks regulatory tolerance windows and residue limit requirements across import-dependent agricultural economies.
- Chlorpyrifos:This phosphorothioate ester delivers broad-spectrum control of soil-dwelling and foliar pests through cholinesterase inhibition. EPA tolerance revocations and EU REACH restrictions are eliminating food crop applications while preserving limited industrial and greenhouse uses in jurisdictions with transitional arrangements.
- Malathion:A phosphorodithioate compound with favorable mammalian toxicity profiles enables continued registration in professional pest control and residential vector management. India's CDSCO maintains active import approvals for malathion technical grade, supporting domestic formulation for horticultural export zones in Maharashtra and Gujarat.
- Diazinon:Retains structural importance in livestock dip applications and perimeter pest control where shorter environmental persistence reduces groundwater monitoring burdens.
- Phosmet:Specialized use in tree fruit and nut crops continues in markets with established maximum residue limits for pome fruit exports.
Established volume favors chlorpyrifos in legacy industrial applications; emerging adoption favors malathion as regulatory substitution accelerates.
Application:
End-use concentration varies sharply by regulatory jurisdiction and crop value intensity.
- Agricultural Crops:Row-crop seed treatment and foliar spray applications dominate volume, with Brazil and Argentina soybean systems driving systemic coating demand for wireworm protection.
- Residential:Perimeter barrier treatments and lawn care formulations concentrate in US and Australian suburban markets where homeowner application equipment penetration is highest.
- Industrial:Structural pest control in food processing facilities and warehouse fumigation requires specialized formulations with vapor pressure specifications.
- Livestock:Dip and pour-on applications for ectoparasite control in cattle and sheep operations persist where macrocyclic lactone resistance has developed.
Volume concentrates in agricultural crops; margin expansion concentrates in residential subscription services bundling monitoring with chemical application.
Formulation:
Physical delivery form determines equipment compatibility and operator exposure pathways.
- Emulsifiable Concentrates:Oil-in-water systems blending active ingredient with petroleum distillates and surfactants remain the default for broadacre ground application. Tank-mix flexibility with herbicides and fungicides sustains demand in Brazilian Cerrado operations where single-pass input application is economically critical.
- Soluble Powders:Dry flowable formulations dissolve rapidly in 2-5 liter water carriers, enabling ultra-low volume drone application in Australian wheat and canola precision agriculture programs where drift reduction commands price premiums.
- Granules:Clay-based carriers impregnated with active ingredient provide soil-incorporated protection against subsurface pests in corn and potato systems.
- Liquids:Ready-to-use formulations eliminate on-farm mixing requirements for residential and small-scale horticultural operators.
Emulsifiable concentrates anchor current volume; soluble powders are climbing the fastest on precision application equipment penetration.
Distribution Channel:
Channel structure reflects customer scale and technical service requirements.
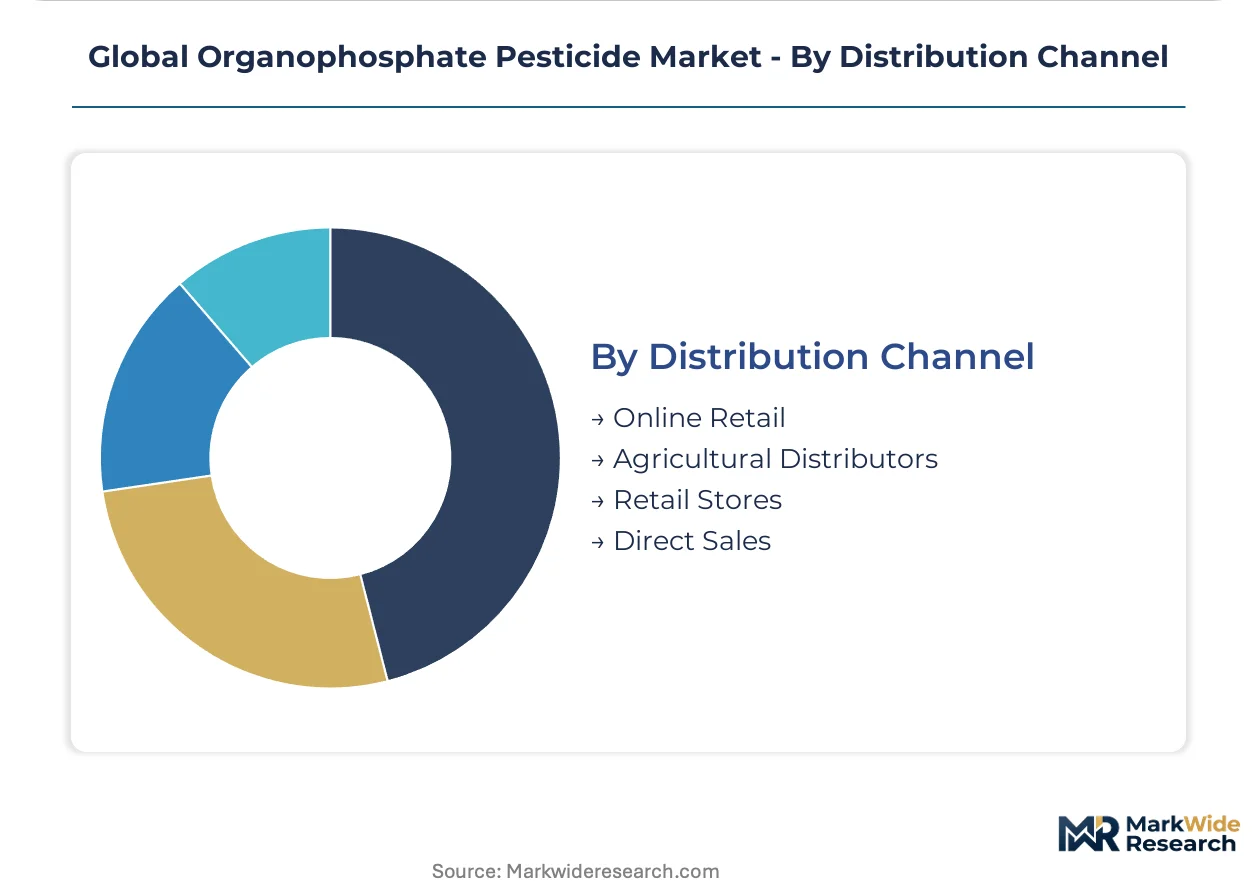
- Agricultural Distributors:Independent and cooperative supply networks dominate row-crop input procurement in US Corn Belt and Brazilian Mato Grosso, bundling credit, agronomic advice, and logistics.
- Direct Sales:Large integrated pest management contractors and plantation operators source technical grade active ingredient directly from manufacturers for on-site formulation.
- Online Retail:E-commerce penetration accelerates in residential segments where homeowners research label requirements before purchase.
- Retail Stores:Garden center and farm supply outlets serve hobby farmers and small-acreage horticulturalists with ready-to-use package sizes.
Agricultural distributors capture the volume foundation; direct sales capture the steepest expansion trajectory on integrated service contract growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical-grade production clusters in China and India supply the majority of global organophosphate active ingredients, while formulation and distribution networks concentrate in agricultural economies with high insecticide application intensity. Regulatory divergence between jurisdictions is fragmenting product availability and forcing manufacturers to maintain parallel portfolios.
United States
EPA tolerance revocations for chlorpyrifos are eliminating food crop applications while accelerating registration of reduced-risk analogs. State-level prohibitions in California and New York outpace federal timelines, creating compliance complexity for multi-state operators. The Research Triangle Park corridor in North Carolina hosts toxicology contract research organizations that prepare registration dossiers for mammalian and ecotoxicology studies.
Brazil
Soybean seed treatment demand drives systemic organophosphate coating adoption for wireworm and root maggot protection in the Cerrado region. ANVISA maintains parallel registration pathways that influence export-oriented manufacturers' product development priorities. Mato Grosso and Goiás states concentrate row-crop input procurement through agricultural distributor networks bundling credit and agronomic advice.
India
The PLI scheme for agrochemical manufacturing attracts technical-grade active ingredient production to Gujarat and Maharashtra industrial corridors. CDSCO and Central Insecticides Board registrations influence export-oriented manufacturers' priorities for horticultural export zones. Maharashtra and Gujarat formulation facilities supply domestic demand and re-export to Southeast Asian and African markets.
Germany
ECHA REACH authorization restrictions on chlorpyrifos force reformulation toward less persistent organophosphate analogs. The F-Gas Regulation and transitional arrangements for existing active substances enable continued malathion use in professional pest control. BASF SE and Bayer AG headquarters in Ludwigshafen and Leverkusen anchor European regulatory strategy and portfolio management.
Australia
Ultra-low volume drone application compatibility opens precision agriculture channels in broadacre wheat and canola operations. The APVMA maintains residue limit harmonization with Codex and major export markets to facilitate grain shipments. Western Australia and New South Wales concentrate soluble powder formulation demand for 2-5 liter water carrier applications.
Global Organophosphate Pesticide Market Competitive Landscape
Integrated agrochemical conglomerates and specialized generic manufacturers split the market through differentiated regulatory capabilities and distribution reach. The structure tilts toward consolidation at the active ingredient level while fragmenting across regional formulation and distribution tiers. Two archetypes dominate: multinational innovators with captive toxicology and registration infrastructure, and Asia-Pacific technical-grade producers supplying merchant market active ingredients. Competitive moves concentrate on backward integration into phosphorus trichloride intermediates and resistance-management service bundling.
Within the multinational innovator tier, FMC Corporation, Syngenta Group, and Sumitomo Chemical Co., Ltd. exemplify archetypes built on global field-scout networks and integrated pest management service layering. These entities occupy positions where aftermarket advisory revenue reshapes margin distribution beyond commodity chemical sales, anchoring grower loyalty through prescription mapping and pheromone monitoring systems rather than price competition alone.
| Leading Market Players |
|---|
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| Syngenta Group |
| Corteva Agriscience |
| Adama Agricultural Solutions |
| Bayer AG |
| UPL Limited |
| Nufarm Limited |
| BASF SE |
| Others |
Supply & Pricing Matrix
Chinese phosphorus trichloride production clusters in Jiangsu and Shandong provinces anchor global organophosphate intermediate supply, concentrating margin capture with state-backed petrochemical conglomerates while forcing downstream formulators into long-term offtake contracts to secure feedstock allocation.
Pricing Analysis
Aftermarket resistance-management advisory services now drive lifetime value beyond chemical unit sales, with subscription fees for scouting and prescription mapping commanding recurring revenue streams. Three-tier pricing structure across premium encapsulated formulations, standard emulsifiable concentrates, and economy-grade technical concentrates reflects certification tier and drift-reduction performance. Cost compression in generic technical-grade malathion is intensifying because Indian PLI-supported capacity additions are flooding merchant markets. Smallholder horticultural operators in Southeast Asia exhibit highest price sensitivity, while integrated pest management contractors in the US Corn Belt prioritize service bundling over per-unit chemical cost.
Supply Chain Analysis
Supplier-financing facilities extended by Indian and Chinese technical-grade producers are locking in formulation partners through 90-120 day payment terms against traditional 30-day cycles. Manufacturing gravity centers on China, India, and Germany, with intermediate synthesis feeding merchant markets across Asia-Pacific and Latin America. Phosphorus trichloride, methanol, and specialized phosphorothioate catalysts constitute critical input dependencies. Single-source vulnerability concentrates in Jiangsu province environmental compliance shutdowns. Distribution runs through agricultural distributor networks in Brazil and the US Midwest, supplemented by direct technical-grade sales to plantation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital agronomy platforms are transforming organophosphate value capture from transactional chemical sales to subscription-based ecosystem lock-in, with prescription mapping interoperability creating winner-take-most dynamics among integrated pest management providers.
For Market Incumbents: Harden registration dossier capabilities through captive toxicology infrastructure in Hyderabad and Research Triangle Park contract research organizations to accelerate reduced-risk analog approvals ahead of chlorpyrifos phase-outs. Deepen backward integration into phosphorus trichloride intermediates through joint ventures with Chinese state petrochemical entities to secure feedstock allocation against environmental compliance volatility. For New Entrants and Emerging Players: Vietnam dragon fruit and mango export zones represent the most penetrable entry point, where EU and Japanese residue limit compliance creates demand for approved organophosphate-based integrated pest management programs. Australian broadacre wheat and canola drone application channels offer second-mover advantage through ultra-low volume soluble powder formulations. Partner with precision agriculture equipment OEMs for tank-mix compatibility certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian technical-grade manufacturers holding CDSCO registrations and Gujarat corridor production assets. Five-to-ten year viability hinges on regulatory substitution pace rather than chemistry obsolescence. Watch for EPA registration acceleration of reduced-risk phosphorothioate analogs as inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Trichloride | Captive intermediate supply from Chinese petrochemical complexes secures margin against feedstock volatility. |
| Microencapsulation Formulation Launch | Polyurea wall systems extend malathion persistence for Dutch and Spanish vegetable seed coating specifications. |
| Drone Application Compatibility Certification | APVMA registration for 2-5 liter water carrier solubility opens Australian wheat and canola precision channels. |
| Resistance Management Service Subscription | Pheromone monitoring bundling with rotational chemistry recommendations creates recurring revenue in Iowa soybean systems. |
| Joint Venture with Indian PLI Beneficiaries | Gujarat and Maharashtra technical-grade production partnerships leverage CDSCO registration pathways for Southeast Asian re-export. |
Research Methodology
Cross-validation between EPA registration databases and ECHA REACH authorization records anchors the qualitative findings on regulatory divergence patterns. Primary interviews with agrochemical plant managers in Gujarat and Maharashtra, procurement leads at Brazilian agricultural distributors, technical R&D directors at European formulators, and resistance management service contractors in the US Corn Belt were combined with secondary validation. Secondary sources include customs and trade data from CDSCO and DGFT filings, SEC 10-K disclosures from listed agrochemical conglomerates, ANVISA registration databases, and APVMA residue limit harmonization records. Bottom-up technical-grade production estimates and top-down formulation demand triangulation were applied across the analysis window.
Calibration against historical registration timelines and active ingredient phase-out patterns shaped the analytical framework. Segmentation dimensions modeled include product type, application end-use, formulation physical form, and regional regulatory cluster. CAGRs were derived from production capacity buildout schedules and substitution elasticity estimates. Forecast inputs incorporate PLI scheme disbursement trajectories and drone application equipment penetration curves.
Practitioners should monitor EPA tolerance revocation acceleration and ECHA sunset clause activations for early signals of chemistry availability compression. Forecasts reflect assumptions on regulatory substitution pace and intermediate supply continuity. Macroeconomic commodity price volatility, unilateral regulatory prohibition, or biological control breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Tebufenozide Market
Crop Protection
Metamifop Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Global Acaricides Market
Crop Protection
South America Molluscicides Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Azoxystrobin Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Organic Pesticides Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Global Aquatic Herbicides Market