
 South America Acaricides Market | 2026-2036
South America Acaricides Market Size, Share, and Industry Trends Forecast 2026-2036
South America Acaricides Market Insights
Formulation-grade suspended concentrates is reorganizing procurement patterns among South American growers. Bayer AG leverages its Brazilian manufacturing footprint to sustain supply continuity across soybean belt distribution channels. Syngenta anchors its regional position through dedicated acaricide R&D facilities in São Paulo state. UPL competes on price-accessible emulsifiable concentrate portfolios tailored to mid-scale Argentine fruit operations.
Acaricides are pesticidal compounds specifically formulated to kill or suppress mites and ticks, typically incorporating active ingredients such as abamectin, bifenazate, or etoxazole at specified concentrations measured in grams per liter. These agents function through contact, systemic, or translaminar action to protect crop yields, livestock health, and structural integrity in commercial settings. Pyrethroid-based formulations currently dominate volume sales across the region due to established efficacy against two-spotted spider mite populations, while biological acaricides represent the fastest-expanding category as Brazilian exporters face EU residue limits. Liquid formulations command premium positioning through convenience and calibration precision, though granular variants retain cost-sensitive share among smallholder coffee producers in Colombia and Peru.
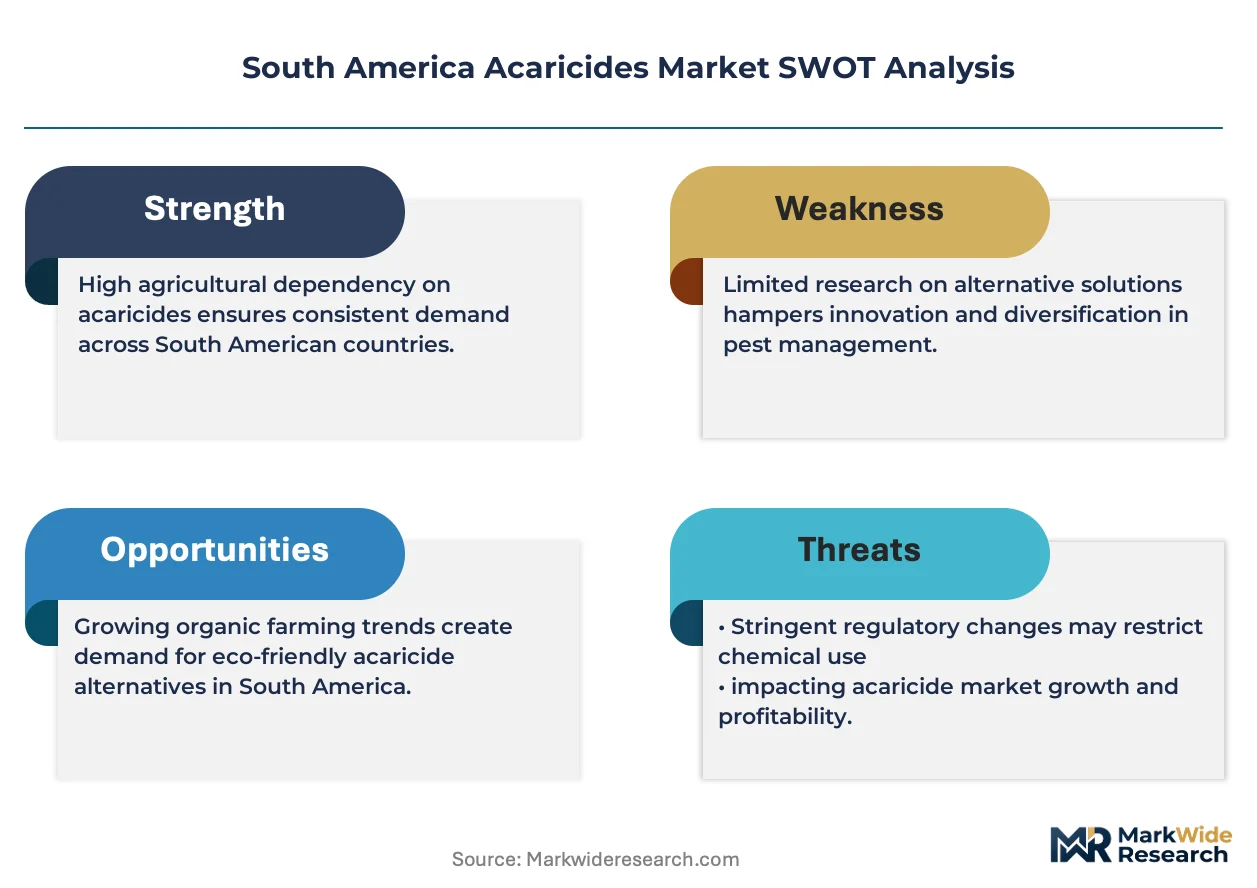
ANVISA maintains stringent toxicity classification protocols that delay novel acaricide registrations by 24-36 months, while Brazil's Ministry of Agriculture enforces maximum residue limits aligned with European EFSA standards to preserve export market access. Argentina's SENASA operates parallel evaluation tracks that create divergent compliance burdens for multinational suppliers. Stakeholders must monitor pending regulatory harmonization proposals between Mercosur member states that could consolidate or fragment product approval pathways.
Market Dynamics
ANVISA's extended registration timelines for novel chemistries are compressing product development cycles and forcing suppliers to prioritize reformulation of existing active ingredients over new molecule introduction.
Growth Catalysts
- Soybean belt expansion:Mato Grosso's intensified double-cropping practices generate sustained acaricide demand through extended growing seasons and elevated mite pressure cycles.
- EU MRL alignment:Brazil's Ministry of Agriculture enforcement of EFSA-equivalent residue standards drives biological acaricide adoption among export-oriented citrus operations.
- Translaminar formulation advances:Suspended concentrate technologies improve application efficiency and reduce field labor requirements for large-scale mechanized farms.
Market Restraints
- Petrochemical input volatility:Pyrethroid precursor costs fluctuate with international crude derivatives, squeezing margin stability for emulsifiable concentrate producers.
- Registration concentration risk:ANVISA's São Paulo-based evaluation backlog creates single-point delays affecting all novel chemistry submissions regardless of sponsor geography.
- Biological efficacy limitations:Beauveria bassiana and Metarhizium anisopliae formulations demonstrate slower knockdown speeds versus synthetic alternatives, limiting adoption in acute infestation scenarios.
Strategic Opportunities
- Peruvian coffee highlands:Smallholder cooperative aggregation creates consolidated procurement channels currently underserved by granular formulation suppliers.
- Precision application convergence:Drone-mounted spraying systems paired with GIS-mapped prescription maps enable variable-rate acaricide deployment.
- Mercosur harmonization protocols:Pending regulatory alignment proposals could streamline multi-country product approvals and reduce redundant toxicology testing burdens.
Industry Challenges
- Field entomology expertise scarcity:Mite identification and resistance monitoring capabilities lag expansion of treated acreage in frontier agricultural zones.
- Legacy equipment incompatibility:Suspended concentrate formulations require nozzle calibration and tank-cleaning protocols that conflict with existing farmer practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Acaricides Market |
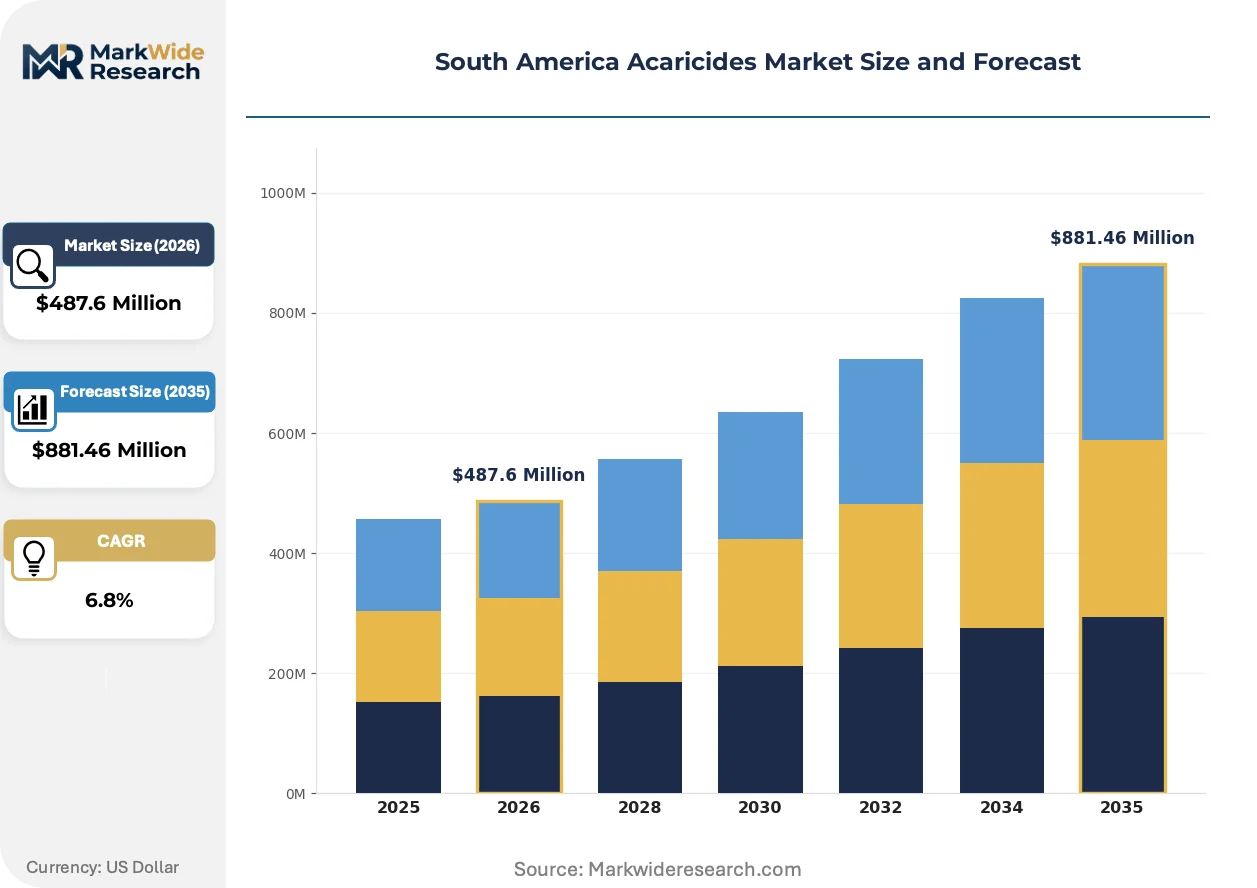
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organophosphates, Carbamates, Pyrethroids, Biological Acaricides Application: Agricultural Use, Residential Use, Commercial Use, Industrial Use Delivery Mode: Liquid Formulation, Granular Formulation, Suspended Concentrate, Emulsifiable Concentrate End User: Farmers, Pest Control Companies, Gardeners, Agrochemical Distributors |
| Companies Covered | Corteva Agriscience, Syngenta, Bayer AG, UPL, Nufarm, BASF SE, FMC Corporation, ADAMA Ltd, Sumitomo Chemical, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Acaricides Market Trends and Innovations
Formulation chemistry and application methodology are converging to reduce per-hectare active ingredient loads while maintaining efficacy thresholds against resistant mite populations.
Microencapsulated abamectin formulations are decomposing traditional emulsifiable concentrate market share by enabling controlled release and reduced phytotoxicity risk. São Paulo citrus cooperatives have adopted these technologies at scale since 2022. The shift is compressing demand for conventional solvent-based carriers and forcing reformulation of legacy product lines.
ANVISA's revised toxicity reclassification framework is accelerating withdrawal timelines for WHO Class I compounds from Brazilian agricultural use. This regulatory compression affects organophosphate-based acaricides most severely. Suppliers are redirecting R&D investment toward reduced-risk chemistry categories to maintain product portfolio viability.
Cooperative procurement consolidation is restructuring distributor relationships across Argentina's Mendoza fruit belt. Pooled purchasing agreements are displacing individual farm supply contracts and compressing intermediary margins. This behavioral shift is most pronounced in mid-scale apple and pear operations seeking volume-based price leverage.
South America Acaricides Market Segmentation
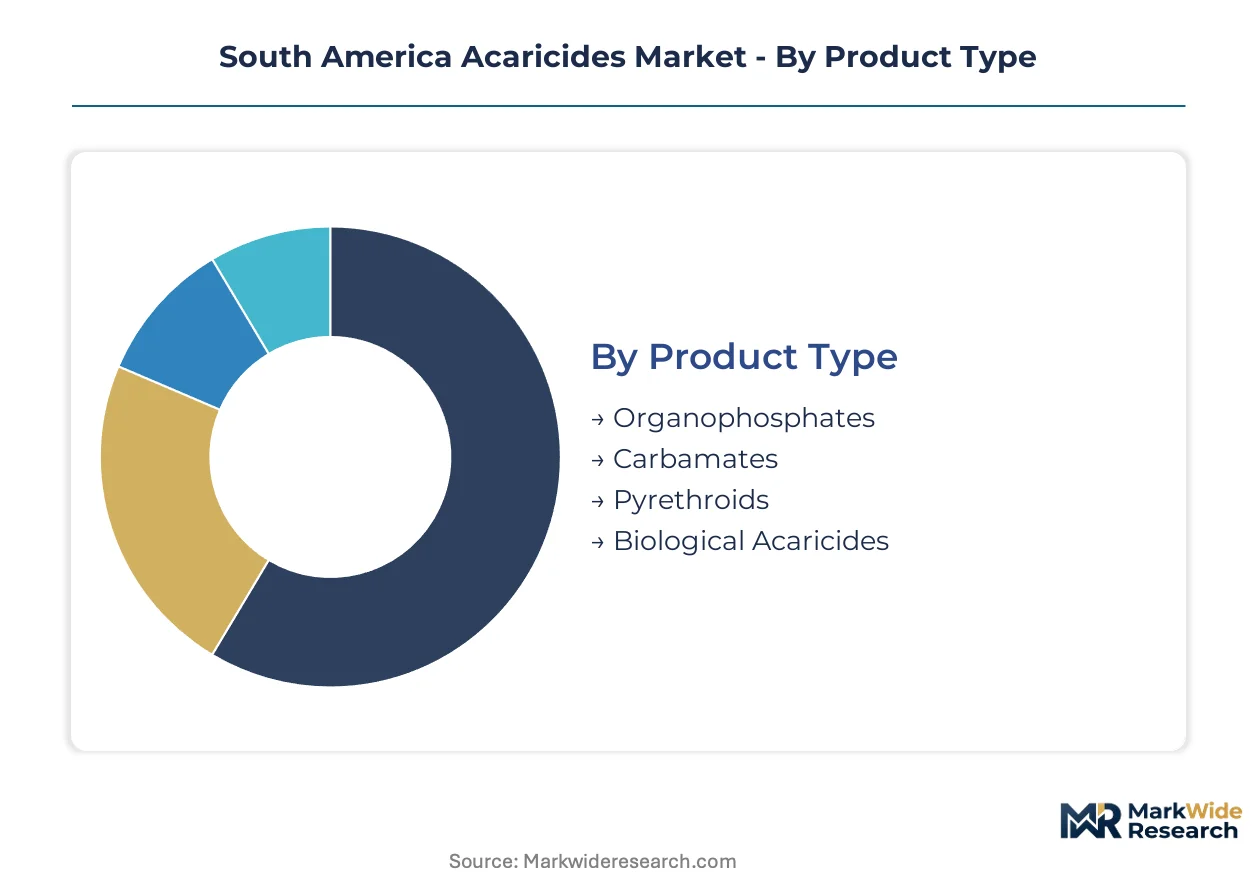
Acaricide procurement patterns in South America diver sharply across formulation chemistry and end-use economics. Mite pressure intensity, export compliance requirements, and application scale together determine which segment combinations capture margin concentration in Brazilian soybean belts versus Argentine fruit valleys.
Product Type:
Pyrethroids command the widest gross margins through established volume throughput and manufacturing scale efficiencies.
- Pyrethroids:Synthetic esters derived from chrysanthemum acid derivatives deliver rapid knockdown against Tetranychus urticae populations. São Paulo citrus exporters specify these formulations for pre-shipment residue management under EU MRL protocols.
- Biological Acaricides:Microbial agents incorporating Beauveria bassiana or Metarhizium anisopliae conidia target mite populations through infection rather than neurotoxicity. Brazilian organic soybean cooperatives in Mato Grosso are scaling procurement as EU-bound shipments face synthetic residue thresholds.
- Organophosphates:Cholinesterase inhibitors face ANVISA reclassification pressure under revised toxicity frameworks.
- Carbamates:Carbaryl and methomyl formulations retain niche positioning in Peruvian smallholder coffee operations.
Pyrethroids hold installed capacity. Biological acaricides are rotating up the share rankings.
Application:
Volume concentration tracks agricultural hectarage expansion, while value capture concentrates in export-facing crop protection.
- Agricultural Use:Field-scale deployment across soybean, citrus, coffee, and grape operations accounts for the dominant throughput. Double-cropping intensification in Brazil's Cerrado biome extends treatment windows and compounds annual acaricide consumption per hectare.
- Commercial Use:Greenhouse and nursery operations in Argentina's Mendoza province demand precision-formulated products with short pre-harvest intervals.
- Residential Use:Urban pest control applications in São Paulo and Buenos Aires metropolitan zones favor ready-to-use formulations.
- Industrial Use:Food processing facility perimeter treatments and storage protection represent a thin volume layer.
Agricultural use anchors volume throughput. Commercial use is climbing the fastest on value-per-liter metrics.
Delivery Mode:
Labor cost differentials between mechanized Brazilian farms and manual-dependent Andean operations fragment formulation preferences.
- Suspended Concentrate:Microencapsulated active ingredient suspensions enable extended residual control and reduced phytotoxicity risk. São Paulo citrus cooperatives have standardized on these formulations since 2022, displacing conventional emulsifiable concentrates.
- Emulsifiable Concentrate:Solvent-based carriers retain cost-sensitive penetration among Argentine mid-scale pome fruit growers.
- Liquid Formulation:Ready-to-apply solutions command calibration precision premiums in drone-mounted spraying systems.
- Granular Formulation:Slow-release matrices suit smallholder coffee producers in Colombia and Peru with limited equipment access.
Suspended concentrate holds installed capacity. Liquid formulation is rotating up the share rankings.
End User:
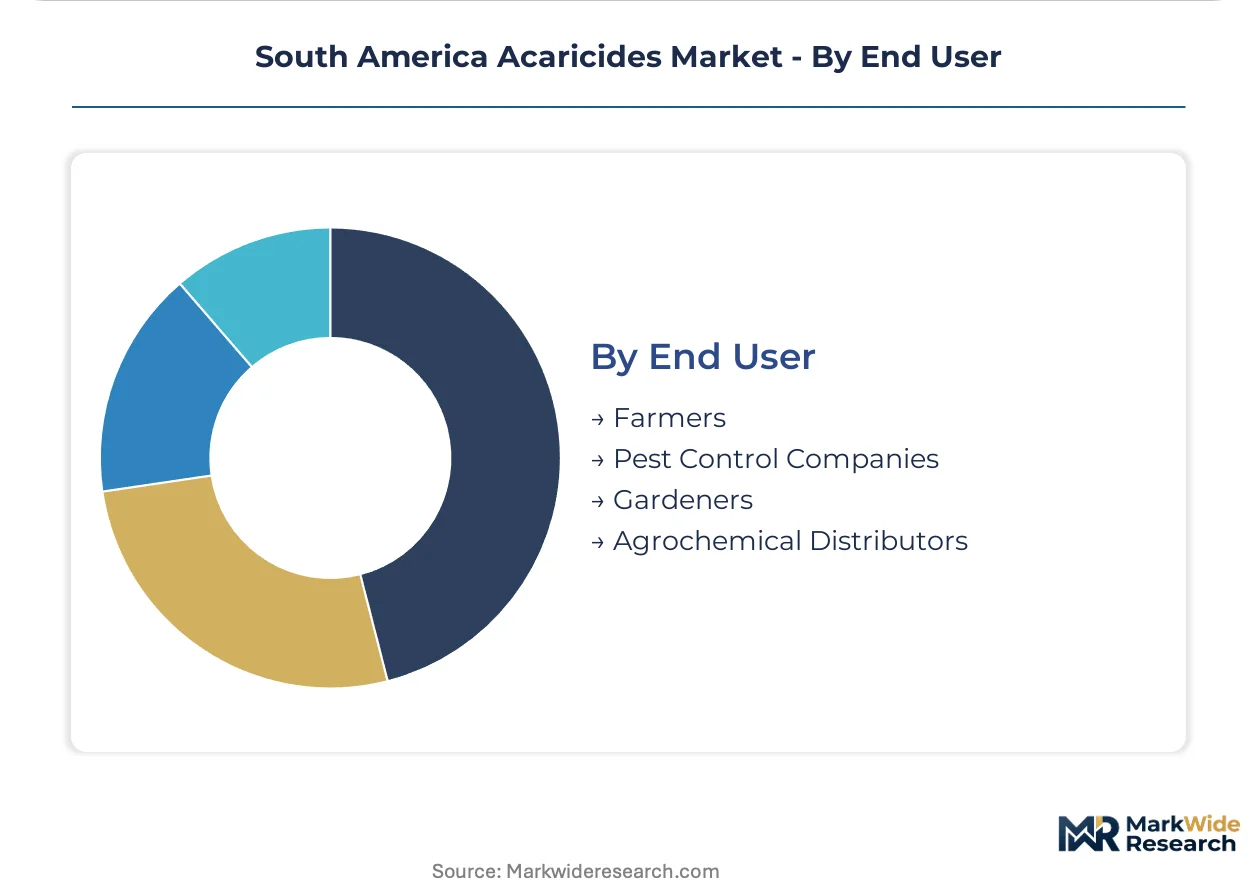
Procurement consolidation through cooperative structures is compressing distributor margins and shifting volume toward direct manufacturer relationships.
- Farmers:Large-scale operators in Mato Grosso and São Paulo states negotiate direct supply contracts with formulation manufacturers, bypassing traditional agrochemical distributors.
- Agrochemical Distributors:Regional supply houses in Argentina's interior provinces retain relevance through credit extension and technical advisory services.
- Pest Control Companies:Licensed applicators serving commercial greenhouse and food processing accounts require specialized training certification under ANVISA protocols.
- Gardeners:Hobbyist and small-scale urban cultivators represent a fragmented, price-sensitive endpoint.
Farmers hold installed capacity. Agrochemical distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation manufacturing clusters concentrate in southeastern Brazil, with São Paulo state anchoring regional supply chains. Argentine distributors maintain cross-border procurement relationships through Mercosur trade corridors. Andean smallholder markets remain fragmented, creating procurement consolidation opportunities.
Brazil
Mato Grosso's double-cropped soybean acreage generates sustained acaricide consumption through extended treatment windows. ANVISA's São Paulo-based evaluation backlog delays novel chemistry registrations by 24-36 months, compressing product development cycles. São Paulo citrus cooperatives have standardized on microencapsulated suspended concentrates since 2022.
Argentina
Mendoza province's apple and pear export operations drive precision-formulated demand with short pre-harvest interval requirements. SENASA operates parallel evaluation tracks that create divergent compliance burdens for multinational suppliers. Pooled purchasing agreements across mid-scale operations are displacing individual farm supply contracts.
Colombia
Smallholder coffee producers in the Andean highlands favor granular formulations due to limited equipment access. The national agricultural institute enforces residue monitoring protocols aligned with European export standards. Antioquia and Caldas departments concentrate procurement through cooperative aggregation channels.
Peru
Highland coffee cooperatives represent underserved consolidated procurement channels for granular formulation suppliers. The Ministry of Agriculture's organic certification programs accelerate biological acaricide adoption among EU-bound exporters. Cajamarca and Amazonas regions exhibit acute field entomology expertise scarcity.
Chile
Central Valley grape and berry operations demand precision application technologies for export-facing residue management. The national agricultural service maintains strict maximum residue limits mirroring EFSA standards. Metropolitan Santiago distributors serve as technical advisory hubs for adjacent fruit-growing regions.
South America Acaricides Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South America acaricides market. Integrated agrochemical conglomerates with Brazilian manufacturing footprints sustain supply continuity through soybean belt distribution channels, while regional specialists compete on price-accessible portfolios. Three archetypes dominate: R&D-intensive multinationals with dedicated São Paulo facilities, scale-driven generic manufacturers serving mid-scale Argentine operations, and biological specialists targeting EU-compliant export segments. Competitive dynamics center on reformulation speed to navigate ANVISA toxicity reclassifications and cooperative procurement consolidation to bypass traditional distributor margins.
Within the integrated multinational tier, Bayer AG and Syngenta anchor regional positioning through established Brazilian manufacturing infrastructure and dedicated acaricide research facilities. UPL occupies a distinct cost-accessibility position serving Argentine fruit operations through emulsifiable concentrate portfolios. These three exemplify how geographic manufacturing presence and formulation specialization determine competitive viability under extended regulatory timelines.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Syngenta |
| Bayer AG |
| UPL |
| Nufarm |
| BASF SE |
| FMC Corporation |
| ADAMA Ltd |
| Sumitomo Chemical |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between São Paulo citrus cooperatives and suspended concentrate manufacturers lock in supply continuity while anchoring price visibility against petrochemical input volatility. These contracts compress spot market exposure for Brazilian soybean belt distributors who face margin instability from pyrethroid precursor cost fluctuations.
Pricing Analysis
ANVISA's toxicity reclassification framework dictates the pricing tier structure across South American acaricide procurement. Three-tier pricing separates microencapsulated suspended concentrates from standard emulsifiable concentrates from granular formulations, with premium tiers capturing calibration precision and residue compliance value. Cost compression in emulsifiable concentrate tiers is intensifying because Argentine mid-scale fruit growers aggregate purchasing through cooperative structures. Smallholder coffee producers in Peru and Colombia exhibit the highest price sensitivity, while São Paulo citrus exporters prioritize residue certification over unit cost.
Supply Chain Analysis
Port of Santos congestion underwrites delivery risk for active ingredient shipments entering Brazilian formulation plants. Manufacturing concentration centers on southeastern Brazil, with São Paulo state anchoring regional production capacity, while Argentine distributors draw from cross-border Mercosur corridors and Andean markets feed from Peruvian and Colombian import channels. Single-source vulnerability runs through pyrethroid precursor supply tethered to international crude derivative markets. Distribution runs through cooperative aggregation channels that displace traditional agrochemical distributor margins across Argentina's interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field entomology expertise scarcity constrains resistance monitoring and precision application adoption across frontier agricultural zones in the South America acaricides market. Suppliers who close this capability gap capture pricing power through technical advisory bundling.
For Market Incumbents: Shield portfolio viability by accelerating reformulation of legacy organophosphate lines ahead of ANVISA withdrawal timelines. Prioritize backward integration into microencapsulation technology to secure suspended concentrate supply continuity against São Paulo evaluation backlogs. Channel control through direct farmer contracts in Mato Grosso defends margin position against cooperative procurement consolidation. For New Entrants and Emerging Players: Anchor in Peruvian highland coffee cooperatives currently underserved by granular formulation suppliers with limited equipment access. The most penetrable segment sits among EU-bound organic exporters in Cajamarca seeking Beauveria bassiana alternatives to synthetic residue thresholds. A technical advisory-led go-to-market angle builds trust where field entomology expertise scarcity persists. For Investors and Strategic Acquirers: Biological formulation specialists with established ANVISA registration pathways and EU MRL compliance documentation represent the highest-conviction acquisition target archetype. Long-term viability hinges on exposure to export-oriented crop protection rather than domestic-only commodity agriculture. Watch biological efficacy improvement rates against synthetic knockdown benchmarks as the inflection indicator for share rotation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microencapsulation | São Paulo citrus cooperatives standardized on suspended concentrates since 2022. |
| ANVISA Registration Pathway Investment | Novel chemistry submissions face 24-36 month evaluation delays from São Paulo backlog. |
| Cooperative Procurement Partnership | Pooled purchasing agreements across Mendoza displace individual farm supply contracts. |
| Biological Efficacy R&D Expansion | EU-bound Brazilian soybean exporters face synthetic residue threshold pressure. |
| Precision Application Technology Licensing | Drone-mounted spraying systems enable variable-rate deployment across Mato Grosso. |
Research Methodology
Operator-level perspectives from agronomic advisors at São Paulo citrus cooperatives, procurement managers at Mato Grosso soybean operations, ANVISA regulatory affairs specialists, and Argentine SENASA compliance officers anchored the qualitative base. These primary inputs combined with secondary validation from customs trade records, ANVISA registration databases, Brazilian Ministry of Agriculture residue monitoring reports, and SEC filings from listed agrochemical manufacturers. Bottom-up volume estimates from formulation-grade consumption patterns triangulated against top-down value projections from manufacturer revenue disclosures.
Sensitivity analysis around petrochemical input cost trajectories and ANVISA evaluation timeline scenarios shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product chemistry class, application crop type, formulation delivery mode, and end-user procurement structure. CAGRs derived from historical volume trajectories adjusted for double-cropping intensification and export compliance adoption curves. Forecast inputs incorporated biological acaricide efficacy improvement rates and cooperative procurement consolidation velocity.
Decision-makers should treat outputs as directional under base assumptions of sustained EU MRL alignment and ANVISA toxicity reclassification continuity; material deviation in regulatory harmonization timelines or petrochemical cost regimes would warrant model refresh. Practitioners should keep alternative scenarios live as Mercosur regulatory alignment proposals and biological formulation efficacy benchmarks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Soil Fumigant Market
Crop Protection
Pest Control Products Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
North America Nematicides Market
Crop Protection
Europe Nematicide Market
Crop Protection
United States Nematicides Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
North America Molluscicides Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Global Termite Control Market
Crop Protection
Pest Control Market