
 Humic and Fulvic Acid Based Biostimulants Market | 2026-2036
Humic and Fulvic Acid Based Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Humic and Fulvic Acid Based Biostimulants Market Insights
Horticultural plants is restructuring demand composition across the biostimulant value chain, pulling formulation investment toward high-margin greenhouse and orchard segments. Valagro S.p.A. anchors Mediterranean supply through specialized extraction expertise, while Koppert B.V. competes on biological integration with beneficial microorganism platforms. Haifa Group extends its position by leveraging compound fertilizer synergies that bundle humic acid with precision nutrition systems.
Humic and fulvic acid based biostimulants comprise complex organic macromolecules derived from lignitic coal, peat, or composted biomass, with humic acids averaging molecular weights of 2,000–300,000 Da and fulvic acids below 2,000 Da, functioning primarily as chelating agents and root-zone biostimulants that enhance nutrient uptake efficiency in agricultural systems. Fulvic acid formulations command premium positioning due to superior foliar penetration and lower application rates, while potassium humate dominates volume in soil amendment applications across broad-acre cereal production. Seed treatment represents the fastest-growing application vector as coating technologies integrate humic substances with microbial inoculants for early-stage root establishment.
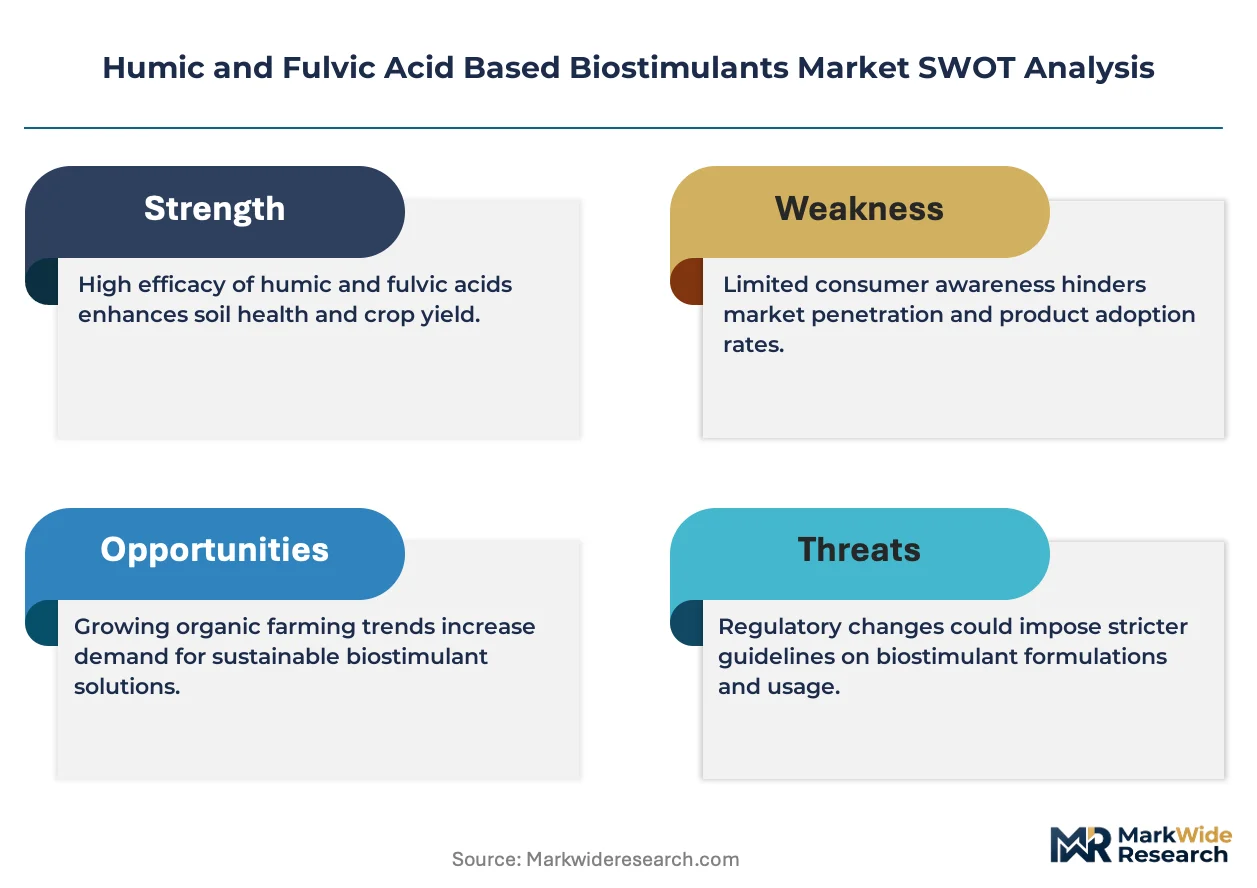
The EU Fertilizing Products Regulation and REACH compliance frameworks constrain market entry for non-European manufacturers, while the USDA National Organic Program governs input certification pathways in North American organic farm segments. Brazil's MAPA fertilizer registration requirements and India's FCO standards under the Ministry of Agriculture create parallel compliance architectures that shape regional competitive dynamics. Stakeholders must monitor evolving carbon intensity thresholds in EU Green Deal implementation, as lifecycle accounting for peat-extracted versus leonardite-derived humic sources will likely redirect procurement criteria and supplier qualification protocols.
Market Dynamics
Specialty crop producers in California and Florida are expanding biostimulant programs for high-value horticultural plants, pulling formulation investment toward high-margin greenhouse and orchard segments and compressing legacy commodity fertilizer protocols.
Growth Catalysts
- EU Fertilizing Products Regulation:The regulation is reshaping product registration pathways across member states, creating harmonized market access for compliant humic acid formulations and accelerating cross-border trade.
- Brazil's Cerrado soybean belt:Soil amendment protocols in this concentrated production zone now integrate humic substances at scale, generating sustained volume demand for potassium humate applications.
- Seed treatment coating technologies:Integration of humic substances with microbial inoculants for early-stage root establishment represents the fastest-growing application vector as precision agriculture expands.
Market Restraints
- Peat extraction lifecycle accounting:Evolving carbon intensity thresholds under EU Green Deal implementation will likely redirect procurement criteria and supplier qualification protocols, disadvantaging peat-derived sources.
- REACH compliance frameworks:These constrain market entry for non-European manufacturers, creating structural friction for Asian and North American suppliers seeking European market access.
- Fulvic acid production cost structure:Premium positioning due to superior foliar penetration requires specialized extraction expertise, limiting supplier base concentration.
Strategic Opportunities
- India's FCO standards under the Ministry of Agriculture:Parallel compliance architectures create white space for early entrants to establish registration precedence before market saturation.
- Compound fertilizer synergies:Bundling humic acid with precision nutrition systems enables technology convergence opportunities for integrated input providers.
- Biological integration platforms:Beneficial microorganism pairing with humic substrates opens new formulation categories beyond standalone soil amendments.
Industry Challenges
- Extraction expertise scarcity:Specialized knowledge in lignitic coal and leonardite processing concentrates among Mediterranean suppliers, creating talent bottlenecks for new market entrants.
- USDA National Organic Program certification timelines:Input certification pathways for North American organic farm segments involve protracted verification cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Humic and Fulvic Acid Based Biostimulants Market |
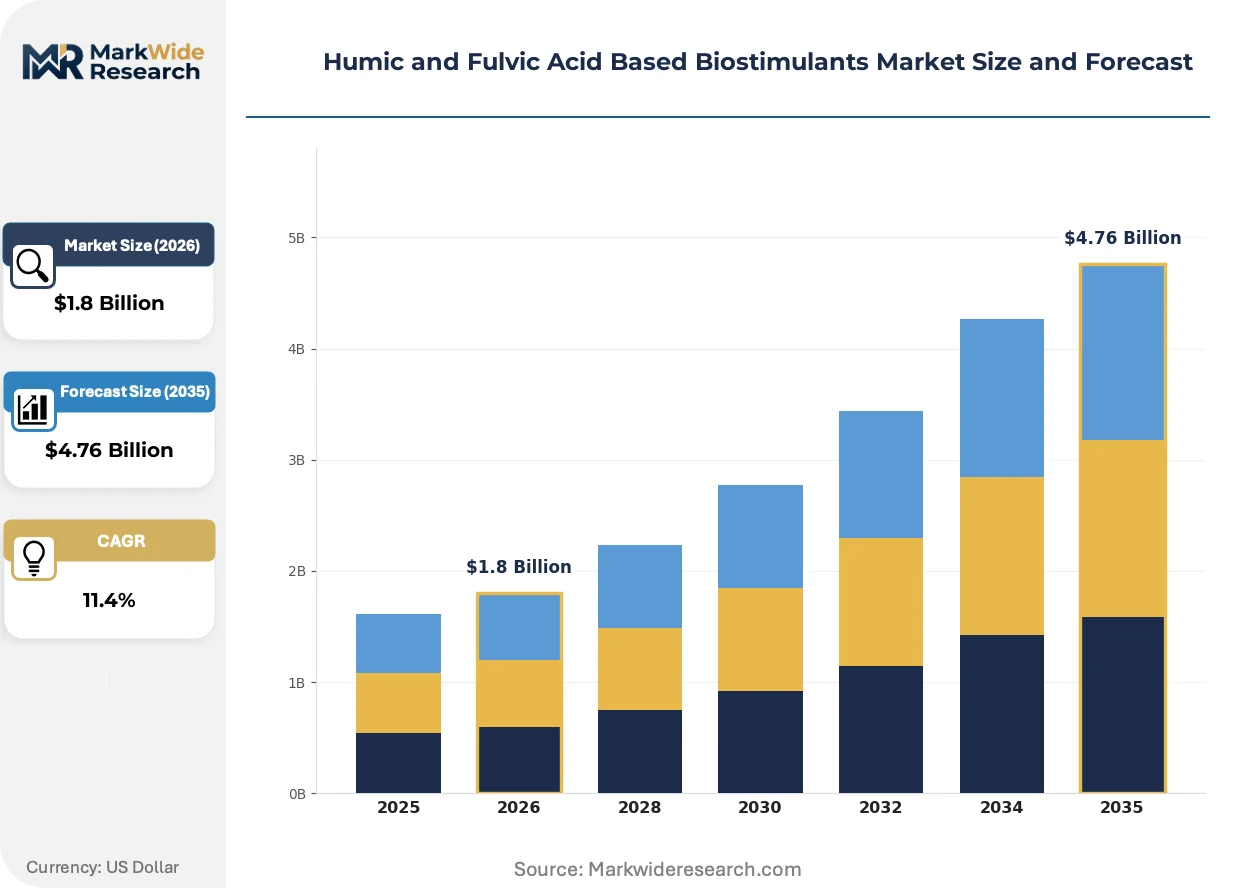
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acid, Fulvic Acid, Humic-Fulvic Blends, Potassium Humate, Sodium Fulvate Application: Seed Treatment, Foliar Spray, Soil Amendment, Hydroponics, Greenhouse Cultivation Crop Type: Cereal Grains, Horticultural Plants, Oilseeds, Pulses & Legumes, Fiber Crops End User: Agri Input Manufacturers, Crop Producers, Horticulturists, Organic Farm Operators, Plant Nurseries |
| Companies Covered | BASF SE, Bayer AG, UPL Limited, Syngenta AG, FMC Corporation, Valagro S.p.A., Koppert B.V., Biolchim S.p.A., Haifa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Humic and Fulvic Acid Based Biostimulants Market Trends and Innovations
Formulation science is advancing rapidly as manufacturers seek differentiation through molecular weight precision and application-specific delivery systems.
Microbial-humic co-formulation technology is unifying previously separate input categories into single-application products. Greenhouse operators in the Netherlands and Spain are adopting these integrated treatments at accelerating pace. This convergence is compressing the traditional supplier landscape by eliminating standalone inoculant and humic acid purchasing decisions.
REACH authorization requirements for novel organic substances are tightening substance safety documentation obligations. Industrial consequence includes elevated compliance costs that disproportionately burden smaller extraction operations. Specialty crop segments in Germany and France are responding by consolidating supplier relationships toward vertically integrated compounders with in-house regulatory capabilities.
Buyer preference is rotating toward certified organic-compatible inputs regardless of farm certification status. Distributors in Brazil and Australia are displacing generic commodity offerings with branded, certificated product lines. This shift is most visible in high-value permanent crop operations where residue sensitivity drives input selection criteria.
Humic and Fulvic Acid Based Biostimulants Market Segmentation
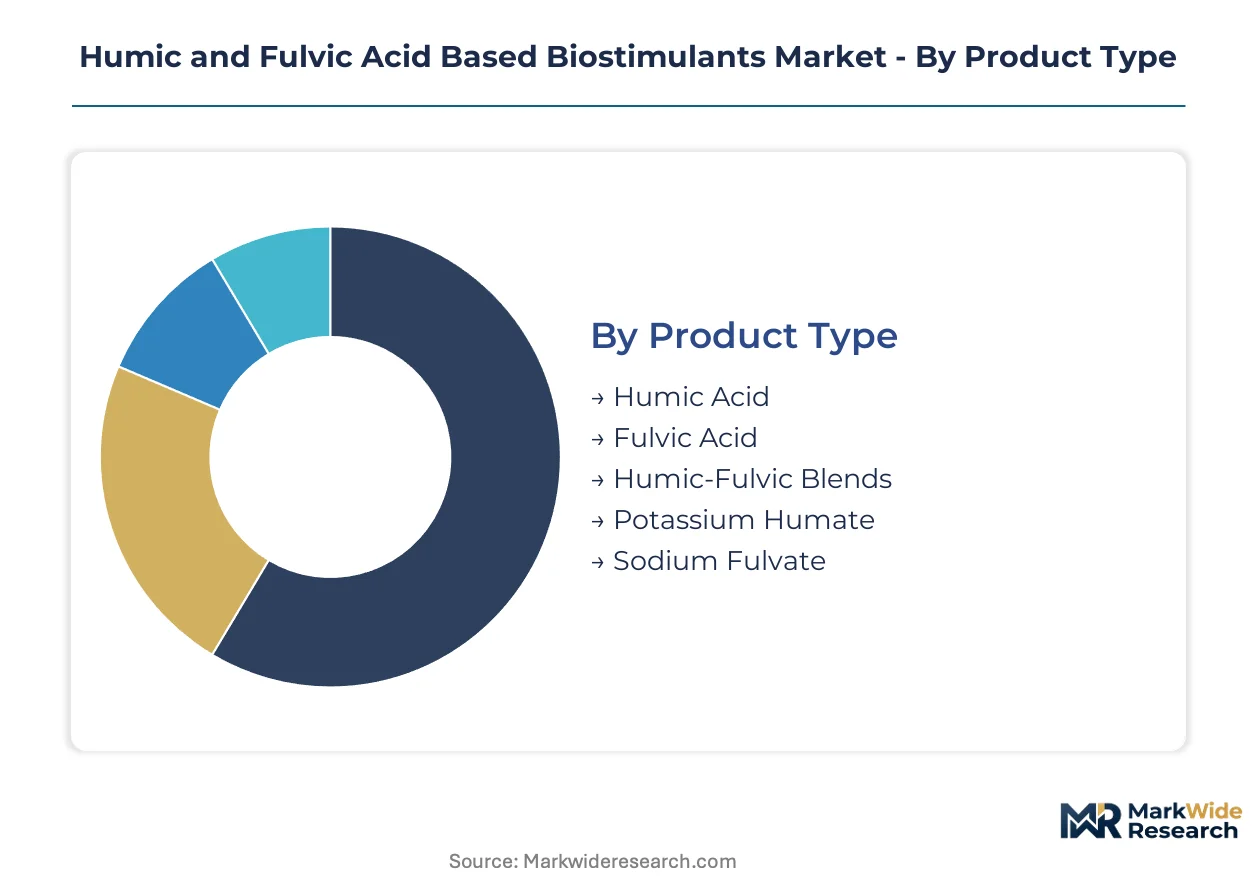
Humic and fulvic acid biostimulants exhibit distinct performance profiles across molecular weight classes and application vectors, with formulation chemistry and delivery method jointly determining uptake efficiency and commercial viability. Segmentation clarity enables procurement alignment between soil amendment protocols and crop-specific nutrient enhancement requirements.
Product Type:
Product substitution patterns reflect evolving grower sophistication, with potassium humate users upgrading toward fulvic acid concentrates for precision foliar programs and blend formulations for integrated soil-rootzone management.
- Humic Acid:High molecular weight fractions (2,000–300,000 Da) function as soil conditioners and root-zone biostimulants that enhance cation exchange capacity in alkaline soils. Demand concentrates in Brazil's Cerrado soybean belt, where potassium humate integration at scale drives sustained volume procurement for broad-acre cereal production.
- Fulvic Acid:Low molecular weight compounds below 2,000 Da demonstrate superior foliar penetration and chelation efficiency, commanding premium positioning due to lower application rates and faster plant assimilation. Specialty crop producers in California and Florida are expanding fulvic-based programs for high-value horticultural plants, pulling formulation investment toward greenhouse and orchard segments.
- Humic-Fulvic Blends:Synergistic combinations target dual-mode delivery through soil amendment and foliar uptake pathways.
- Potassium Humate:Dominates volume in soil amendment applications across commodity grain production systems.
- Sodium Fulvate:Soluble salt formulation optimized for hydroponic and fertigation delivery systems.
Volume placements concentrate in potassium humate; the faster expansion belongs to fulvic acid.
Application:
Application method selection hinges on crop growth stage timing and labor cost structures, with seed treatment commanding attention for early-stage root establishment economics.
- Seed Treatment:Coating technologies integrate humic substances with microbial inoculants for synchronized early-stage root establishment and rhizosphere colonization. Precision agriculture expansion in the Netherlands and Spain accelerates adoption of microbial-humic co-formulation platforms.
- Foliar Spray:Fulvic acid concentrates enable rapid nutrient translocation through leaf cuticle penetration, with greenhouse operators in Mediterranean clusters adopting these treatments at accelerating pace.
- Soil Amendment:Traditional broadcast and banded application of humic acid for long-term soil organic matter enhancement.
- Hydroponics:Recirculating system integration requires low-residue, fully soluble formulations.
- Greenhouse Cultivation:Controlled environment agriculture demands precise dosing and residue-sensitive input certification.
Soil amendment retains the largest installed base; seed treatment demonstrates the steepest expansion trajectory.
Crop Type:
Crop value per hectare dictates biostimulant intensity, with permanent crop operators accepting premium input costs unavailable to commodity grain producers.
- Horticultural Plants:High-value greenhouse and orchard segments generate margin compression tolerance for premium fulvic acid formulations. Specialty crop producers in California and Florida are restructuring demand composition across the biostimulant value chain, pulling formulation investment toward these segments.
- Cereal Grains:Broad-acre wheat and corn production relies on potassium humate for cost-effective soil amendment at scale.
- Oilseeds:Soybean and canola systems integrate humic substances for nitrogen fixation support and stress mitigation.
- Pulses & Legumes:Rhizobium symbiosis enhancement drives microbial-humic co-application protocols.
- Fiber Crops:Cotton and other fiber systems utilize humic acid for water stress management in arid production zones.
Horticultural plants capture the highest margin per hectare; oilseeds generate the fastest volume growth in Brazil's Cerrado belt.
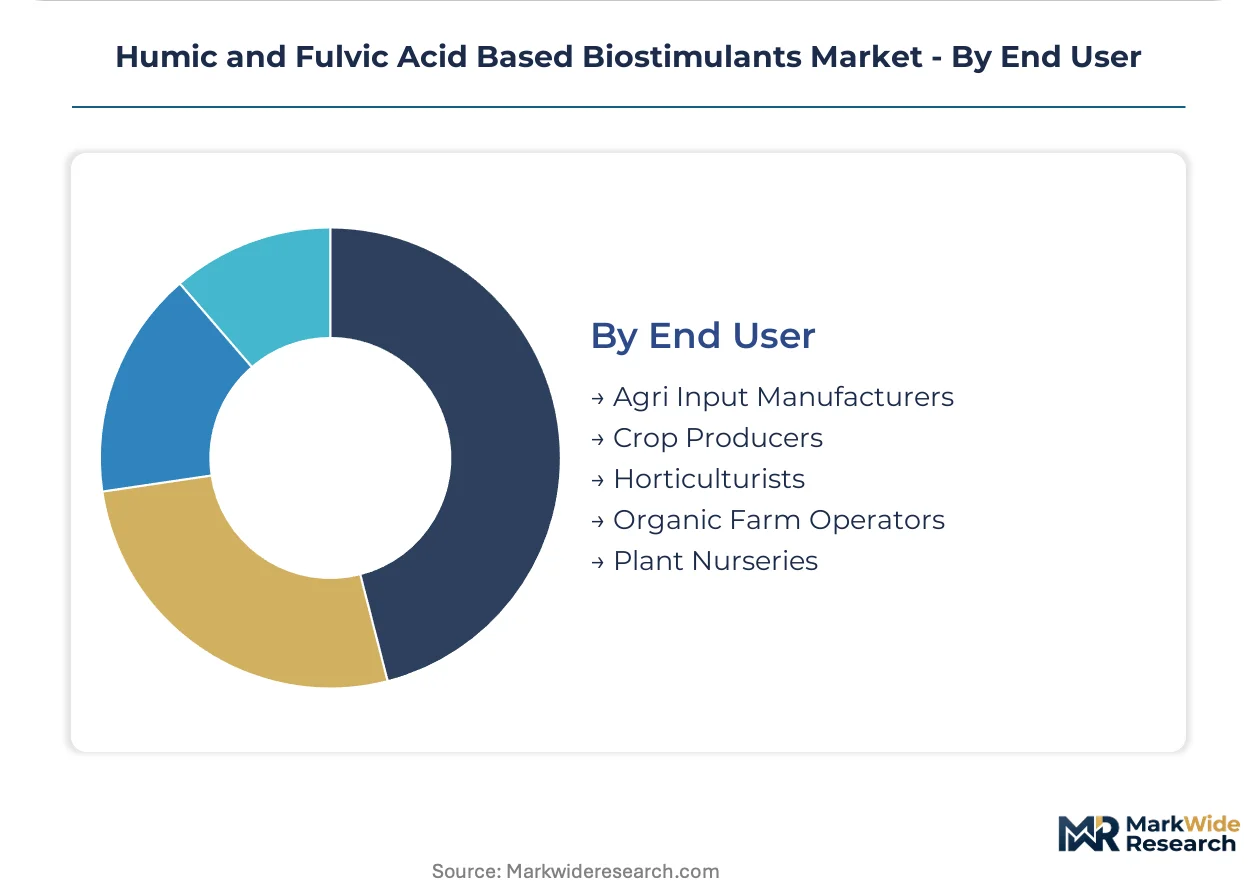
End User:
End user sophistication spans from integrated compounders seeking formulation ingredients to direct farm operators demanding finished, certificated products.
- Agri Input Manufacturers:Compound fertilizer producers bundle humic acid with precision nutrition systems, leveraging formulation synergies for technology convergence. Haifa Group extends its position through this integration pathway.
- Crop Producers:Direct farm procurement concentrates in high-value permanent crop operations where residue sensitivity drives input selection criteria.
- Horticulturists:Specialized greenhouse and nursery operators require certified organic-compatible inputs regardless of farm certification status.
- Organic Farm Operators:USDA National Organic Program certification pathways govern input selection with protracted verification cycles.
- Plant Nurseries:Propagation-stage applications emphasize root establishment and transplant survival rates.
Agri input manufacturers dominate procurement volume; organic farm operators are gaining share fastest amid certification requirement tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's MATOPIBA agricultural frontier operates as a concentrated demand zone where soybean producers integrate humic substances at scale, while regulatory divergence across major producing nations fragments supplier qualification pathways.
Brazil
MAPA fertilizer registration requirements govern potassium humate integration across the Cerrado soybean belt, where soil amendment protocols now embed humic substances as standard practice. ANVISA and the Ministry of Agriculture enforce parallel compliance architectures that shape procurement criteria for domestic and imported formulations. São Paulo-based distributors are consolidating supplier relationships toward vertically integrated compounders with in-house regulatory capabilities.
United States
Specialty crop producers in California's Central Valley and Florida's citrus belt are expanding biostimulant programs for high-value horticultural plants. The USDA National Organic Program governs input certification pathways with protracted verification cycles that delay revenue recognition for new entrants. Fresno and Immokalee clusters pull formulation investment toward greenhouse and orchard segments, compressing legacy commodity fertilizer protocols.
India
FCO standards under the Ministry of Agriculture create white space for early entrants to establish registration precedence before market saturation. The Fertilizer Control Order mandates specific quality parameters for humic acid products sold across state boundaries. Maharashtra and Gujarat agricultural input manufacturers are bundling humic acid with precision nutrition systems for technology convergence.
European Union
The EU Fertilizing Products Regulation is reshaping product registration pathways across member states, creating harmonized market access for compliant formulations. REACH compliance frameworks constrain market entry for non-European manufacturers, accelerating cross-border trade only for qualified suppliers. Netherlands greenhouse operators and Spanish Mediterranean clusters are adopting microbial-humic co-formulation platforms at accelerating pace.
China
Dual carbon goals under MEE oversight are redirecting procurement criteria toward leonardite-derived humic sources with lower lifecycle carbon intensity than peat-extracted alternatives. GB standards for organic fertilizer inputs govern quality specifications for domestic production and export qualification. Shandong Province extraction operations concentrate specialized knowledge in lignitic coal processing, creating talent bottlenecks for new market entrants.
Humic and Fulvic Acid Based Biostimulants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with Mediterranean extraction expertise concentrating among established suppliers while Asian compounders compete on volume throughput. The supplier base organizes around three archetypes: vertically integrated compounders with captive raw material sources, biological platform integrators pairing microorganisms with humic substrates, and regional formulators serving protected domestic markets. M&A activity targets regulatory capability acquisition, while capacity expansion concentrates in leonardite-rich zones with favorable carbon accounting profiles.
Among extraction specialists, Valagro S.p.A. and Biolchim S.p.A. exemplify the Mediterranean knowledge concentration in lignitic coal and leonardite processing. Koppert B.V. occupies a position within the biological integration archetype, representing the convergence of beneficial microorganism platforms with humic substrate delivery. Haifa Group anchors the compound fertilizer synergy segment, where bundling humic acid with precision nutrition systems enables technology convergence for integrated input providers.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| UPL Limited |
| Syngenta AG |
| FMC Corporation |
| Valagro S.p.A. |
| Koppert B.V. |
| Biolchim S.p.A. |
| Haifa Group |
| Others |
Pricing and Supply Chain Analysis
Agri input manufacturers in Brazil and India concentrate procurement volume for humic acid formulations, anchoring contract-based long-term offtake pricing that rewards volume commitment with preferential terms while spot purchasers absorb premium markups for compressed lead times.
Pricing Analysis
Short lead time premiums of 15-25% apply to fulvic acid concentrates demanded by California specialty crop producers facing compressed application windows, while spot inventory of potassium humate trades at discounts to contract benchmarks in Brazil's Cerrado belt. Three-tier pricing structure across premium, standard, and economy levels separates certified organic-compatible fulvic formulations from generic humic acid and unbranded commodity extracts. Pricing pressure stems from REACH compliance cost absorption by non-European suppliers seeking European market access. Organic farm operators exhibit highest price sensitivity due to protracted USDA National Organic Program certification timelines that delay cost recovery, while greenhouse operators in the Netherlands accept premium positioning for residue-sensitive inputs.
Supply Chain Analysis
Domestic-content mandates under India's FCO standards and Brazil's MAPA registration requirements are reshaping sourcing patterns, compelling foreign suppliers to establish local formulation partnerships or absorb extended approval cycles. Extraction operations concentrate in China, Italy, and the United States, with Shandong Province and Mediterranean clusters anchoring lignitic coal processing expertise. Raw material flows draw from leonardite deposits, peat bogs, and composted biomass feedstocks, with carbon intensity accounting increasingly filtering supplier qualification. Single-source vulnerability concentrates in Mediterranean extraction specialists where specialized knowledge bottlenecks limit rapid capacity scaling. Distribution runs through agrochemical distributors and direct compounder relationships, with São Paulo-based and Fresno-based intermediaries consolidating toward vertically integrated suppliers with in-house regulatory capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory capability ownership, with REACH and EU Fertilizing Products Registration compliance costs forcing smaller extraction operations toward acquisition or exit.
For Market Incumbents: Extend formulation patent positions in microbial-humic co-formulation platforms before biological integration platforms commoditize standalone humic offerings. Acquire specialized extraction expertise in leonardite-rich zones with favorable carbon accounting profiles to secure backward integration into captive raw material sources. Channel control through distributor consolidation in Brazil and India protects margin position against generic commodity displacement. For New Entrants and Emerging Players: Begin with India's FCO standards white space before Maharashtra and Gujarat agricultural input manufacturers saturate registration precedence. Target seed treatment coating technologies as the fastest-growing application vector with lower regulatory burden than finished fertilizer registration. Pursue co-development partnerships with established compounders lacking biological integration capabilities rather than standalone brand building. For Investors and Strategic Acquirers: The window for entry favors vertically integrated compounders with captive leonardite sources and in-house EU regulatory capabilities. Mid-cap Mediterranean extraction specialists with specialized knowledge concentration represent prime acquisition targets as compliance cost structures widen competitive moats. Monitor carbon intensity threshold enforcement under EU Green Deal implementation as the inflection signal redirecting procurement criteria and supplier qualification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Capability Acquisition | REACH authorization expertise unlocks European market access for non-compliant Asian suppliers. |
| Backward Integration into Leonardite Sources | Captive raw material supply secures carbon accounting advantages under EU Green Deal procurement criteria. |
| Microbial-Humic Co-Formulation Development | Biological integration platforms unify previously separate input categories into single-application products. |
| Seed Treatment Technology Licensing | Coating expertise enables fastest-growing application vector penetration with lower regulatory barriers. |
| Certified Organic-Compatible Product Line Expansion | USDA National Organic Program certification captures buyer preference rotation regardless of farm certification status. |
Research Methodology
Multi-period observation of MAPA registration timelines, FCO standard enforcement patterns, and EU Fertilizing Products Regulation implementation anchored the trend analysis, supplemented by interviews with extraction plant managers, agrochemical procurement leads at Brazilian distributors, regulatory affairs directors at Mediterranean compounders, and technical R&D directors developing microbial-humic platforms. Secondary validation drew from ANVISA fertilizer filings, Ministry of Agriculture quality parameter disclosures, customs and trade data on lignitic coal imports, and SEC 10-K disclosures from listed agricultural input manufacturers. Bottom-up volume triangulation across potassium humate, fulvic acid, and blend formulations converged with top-down value estimates from agrochemical market audits.
Segment-weighting across molecular weight classes, application vectors, and crop value tiers structured the analytical framework over the projection horizon. Product type stratification by humic acid, fulvic acid, potassium humate, and blend categories combined with application segmentation across seed treatment, foliar spray, soil amendment, and hydroponics delivery. CAGRs derived from regression analysis against planted area expansion, biostimulant intensity per hectare trends, and input substitution elasticities. Industry-specific forecast inputs included carbon intensity accounting adoption curves and microbial co-formulation penetration rates in greenhouse clusters.
Underlying measurement precision varies by segment; seed treatment and fulvic acid concentrate categories carry tighter precision than commodity potassium humate due to more concentrated supplier reporting. Forecasts reflect assumptions around regulatory timeline stability, carbon threshold enforcement consistency, and substitution elasticity persistence in Brazil's Cerrado belt. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Asia Pacific Feed Pelletizing Agents Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
South America Feed Antibiotics Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Amino Acid for Agriculture Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
US Fungicide Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
Asia-Pacific Feed Premix Market