
 Herbicide Safeners Market | 2026-2036
Herbicide Safeners Market Size, Share, and Industry Trends Forecast 2026-2036
Herbicide Safeners Market Analysis
Cereal crop applications is hardening as the dominant end-use vertical for herbicide safeners, displacing earlier vegetable-centric demand patterns. BASF SE leverages its integrated crop protection portfolio to anchor supply relationships across European wheat-growing regions. Corteva Agriscience sustains R&D intensity in novel oxime chemistry, while UPL Limited competes through channel control in emerging agricultural markets.
Herbicide safeners are chemical adjuvants that protect crop plants from phytotoxic injury by inducing detoxification enzymes, typically formulated as co-biocides at 0.5-2% active ingredient load in commercial herbicide products. Their primary commercial purpose centers on expanding the selective weed-control window for post-emergence sulfonylurea and aryloxyphenoxypropionate chemistries. Phenolic compounds occupy the mature volume tier with stable margins, whereas triazoles represent the fastest-growing chemistry class as manufacturers reformulate for temperature-stress resilience. Application demand tilts decisively toward cereal crops, with oilseed crops forming a secondary margin pool where safener premiums prove stickiest.
EPA registration requirements under FIFRA now effectively mandate safener inclusion for new sulfonylurea active ingredients targeting major row crops, while REACH compliance in Europe imposes full toxicological dossiers on safener imports. Bayer AG and Syngenta Group navigate these dual regulatory architectures through dedicated regulatory-affairs units in Basel and Research Triangle Park. Stakeholders must monitor pending EPA endangered-species assessments for herbicide-safener combinations, as these rulings will reshape product-specific market access faster than chemistry innovation cycles.
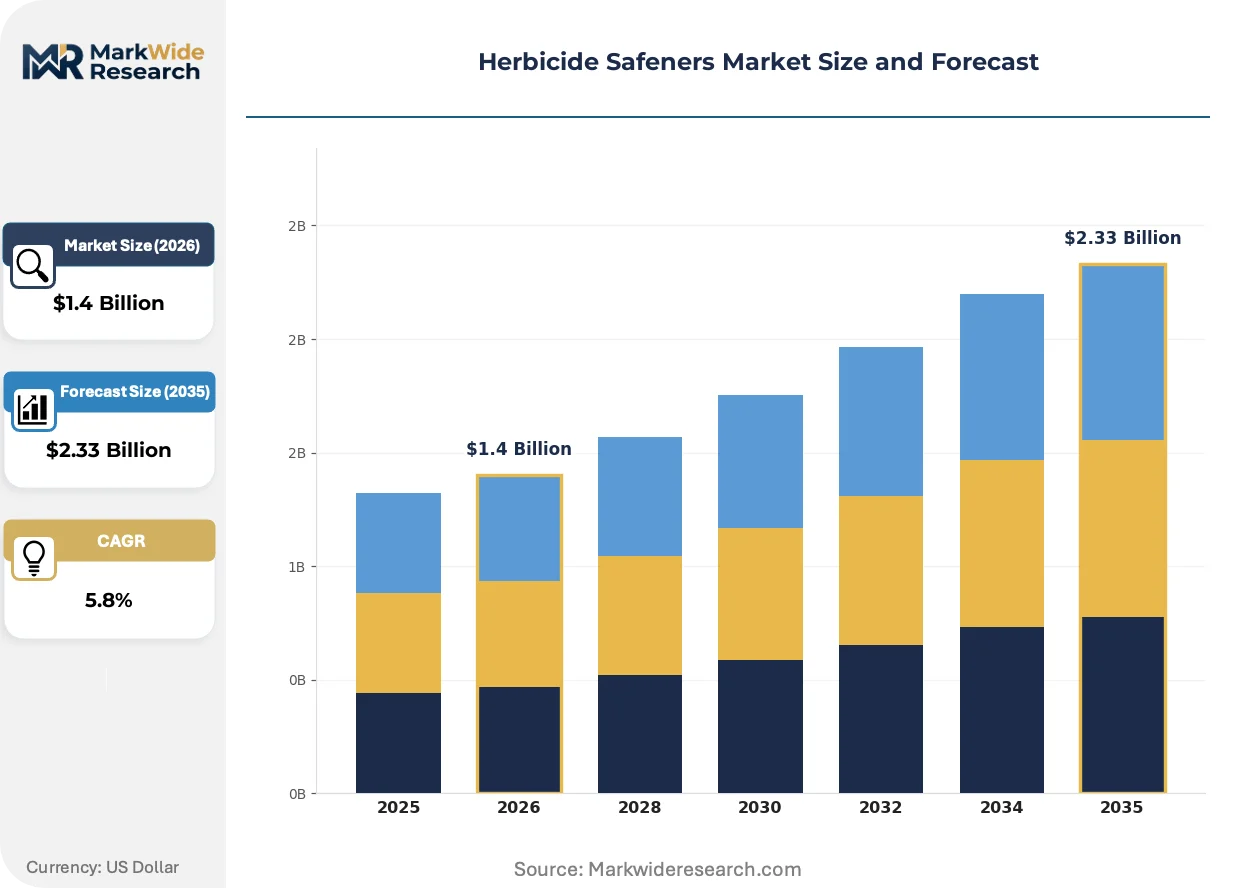
Market Dynamics
EPA registration mandates under FIFRA now require safener co-formulation for new sulfonylurea herbicides targeting major row crops, structurally embedding safeners into herbicide product development cycles rather than treating them as optional adjuvants.
Growth Catalysts
- REACH toxicological dossiers:ECHA compliance requirements in Europe now demand full safener toxicological profiles for import authorization, accelerating reformulation investments by manufacturers seeking European wheat market access.
- Cereal crop concentration:North American grain belts, specifically the US Corn Belt and Canadian prairie provinces, generate sustained volume demand as sulfonylurea herbicide use intensifies in wheat and corn rotations.
- Triazole chemistry transition:Temperature-stress resilience requirements in post-emergence applications are pulling formulation shifts from phenolic safeners toward triazole-based alternatives with broader environmental tolerance windows.
Market Restraints
- Active ingredient cost volatility:Oxime carbamate feedstock prices fluctuate with petrochemical input cycles, compressing margin stability for novel safener chemistries in development pipelines.
- Registration timeline friction:EPA endangered-species assessments for herbicide-safener combinations now extend product launch windows by 18-36 months, freezing capital deployment longer than chemistry innovation cycles.
- Biological herbicide substitution:Microbial bioherbicide platforms from crop protection startups threaten to bypass safener-dependent chemistries entirely in specialty vegetable applications.
Strategic Opportunities
- Indian wheat belt expansion:Punjab and Haryana states present underpenetrated demand as FAO-backed extension programs promote sulfonylurea adoption in high-yield wheat varieties.
- Drone application integration:Precision agriculture service providers are integrating safener-loaded micro-encapsulated formulations into aerial spray protocols, opening channel partnerships beyond traditional agrochemical distribution.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams for reduced-chemistry crop protection create regulatory tailwinds for safener manufacturers demonstrating biodegradability improvements in dossier submissions.
Industry Challenges
- Metabolic pathway modeling expertise:Safener development now requires computational toxicologists capable of predicting cytochrome P450 enzyme induction patterns, a skill set concentrated in Basel and Research Triangle Park corridors.
- Legacy formulation integration:Retrofitting triazole safeners into existing sulfonylurea manufacturing lines demands capital-intensive process revalidation without guaranteed volume commitments from herbicide partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbicide Safeners Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic Compounds, Dinitroanilines, Triazoles, Oximes Application: Cereal Crops, Oilseed Crops, Vegetables, Fruits Formulation: Wettable Granules, Emulsifiable Concentrates, Suspension Concentrates, Liquid Distribution Channel: Online Retail, Agricultural Cooperatives, Specialty Stores, Wholesalers |
| Companies Covered | Corteva Agriscience, UPL Limited, BASF SE, Nufarm Limited, ADAMA Agricultural Solutions Ltd., Syngenta Group, FMC Corporation, Sumitomo Chemical Company, Limited, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbicide Safeners Market Emerging Trajectories
Reformulation activity is accelerating around temperature-resilient chemistries and precision delivery systems, with regulatory compliance costs now driving consolidation in safener development capabilities.
Micro-encapsulation technology is integrating triazole safeners into controlled-release matrices that match herbicide degradation curves in soil environments. Large-scale wheat cooperatives in the Canadian prairie provinces are adopting these formulations to reduce reapplication frequency. This integration is compressing the competitive window for conventional phenolic safeners by extending product residual activity without concentration increases.
REACH authorization amendments under ECHA's 2024 substance evaluation roadmap now classify certain oxime carbamate metabolites as substances of very high concern. European formulators are responding by accelerating dossier submissions for alternative safener candidates ahead of sunset date deadlines. Wheat-growing regions in France and Germany face the most immediate product substitution requirements, with distributors already restructuring inventory commitments.
Channel consolidation among North American agricultural retailers is concentrating procurement decisions into fewer buying desks at regional cooperative headquarters. Independent formulators now compete for slotting agreements with these consolidated entities rather than individual farm relationships. This behavioral shift is most visible in the US Corn Belt, where three regional cooperatives now control over sixty percent of safener volume allocation decisions.
Herbicide Safeners Market Segmentation
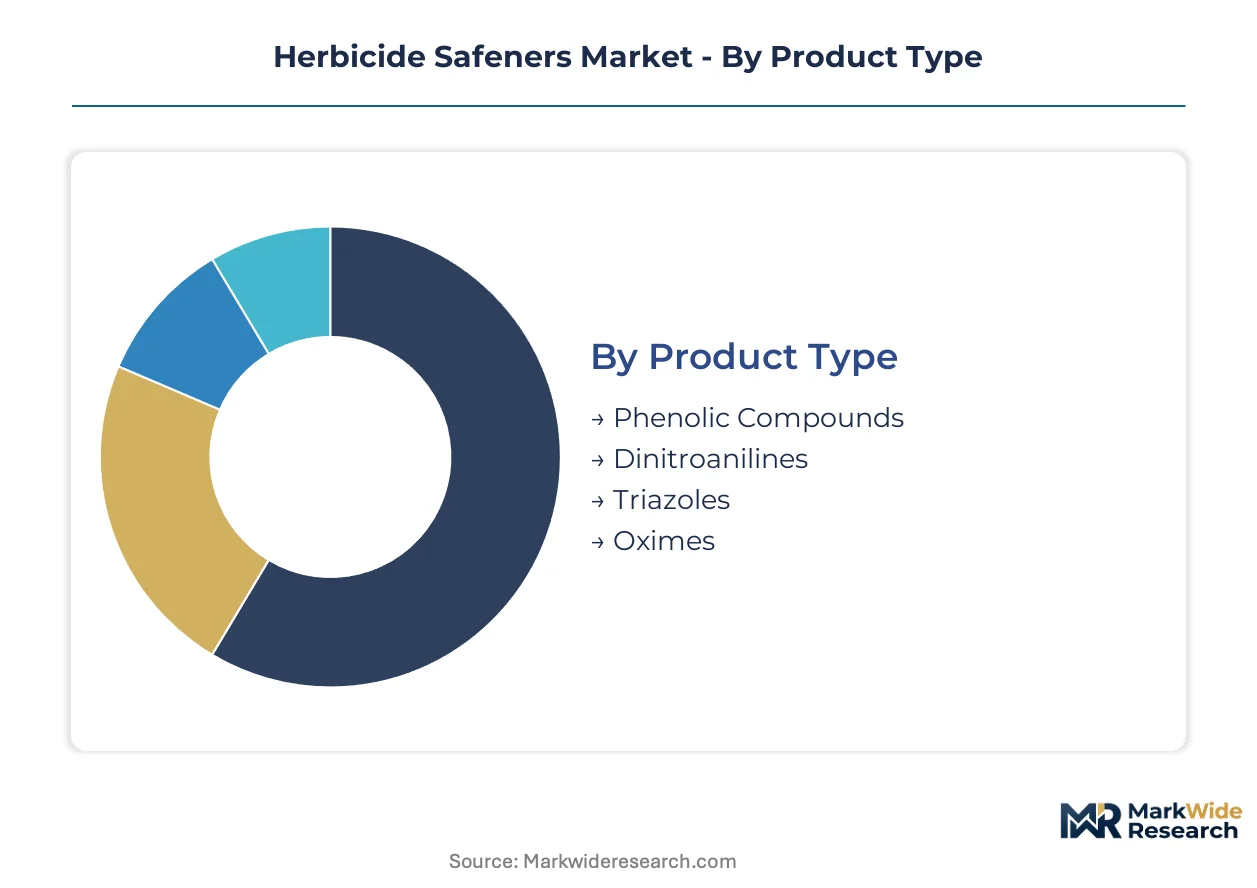
Herbicide safener segmentation reveals chemistry-driven margin stratification and channel consolidation reshaping procurement patterns. Understanding these divides exposes where formulation investments concentrate versus where commoditization pressures mount.
Product Type:
Phenolic compounds anchor volume tiers with stable margins, while triazoles command premium positioning through temperature-resilience advantages.
- Phenolic Compounds:These mature safener chemistries rely on hydroxybenzene derivatives to induce glutathione S-transferase enzymes in cereal crop tissues. Demand concentrates across the US Corn Belt where sulfonylurea herbicide use in corn-soy rotations remains intensive, though margin compression from generic competition constrains R&D reinvestment.
- Triazoles:Five-membered nitrogen heterocycles deliver superior cytochrome P450 enzyme induction under temperature-stress conditions. French and German wheat-growing regions are pulling formulation shifts toward this chemistry class as REACH dossier requirements harden around metabolite toxicity profiles.
- Dinitroanilines:Nitro-substituted aniline structures provide pre-emergence safening for oilseed crop applications in Canadian prairie provinces.
- Oximes:Carbon-nitrogen double-bond functionality enables rapid metabolic detoxification in aryloxyphenoxypropionate herbicide pairings.
Mature deployment sits with phenolic compounds. Newer deployment is concentrated in triazoles.
Application:
Cereal crop concentration defines volume allocation, while oilseed applications retain margin stickiness through specialized formulation requirements.
- Cereal Crops:Wheat, corn, and barley rotations dominate safener consumption as sulfonylurea herbicide intensity increases across North American grain belts. The US Corn Belt and Canadian prairie provinces generate sustained procurement volumes through cooperative buying desks.
- Oilseed Crops:Canola and soybean applications demand higher safener loadings due to inherent metabolic sensitivity, supporting premium pricing in formulations targeting Canadian canola cooperatives.
- Vegetables:Specialty crop applications face substitution pressure from microbial bioherbicide platforms bypassing safener-dependent chemistries entirely.
- Fruits:Orchard and vineyard deployments remain niche, constrained by limited sulfonylurea herbicide registrations in perennial cropping systems.
Volume leadership belongs to cereal crops. Margin protection concentrates in oilseed applications.
Formulation:
Liquid formulations capture efficiency-seeking demand, while suspension concentrates serve precision agriculture integration.
- Liquid:Ready-to-use aqueous solutions simplify tank-mixing logistics for large-scale wheat operations in Punjab and Haryana states, where extension programs promote sulfonylurea adoption.
- Suspension Concentrates:Finely dispersed solid particles in continuous liquid phase enable drone application integration through controlled droplet sizing, opening channel partnerships with aerial spray service providers.
- Wettable Granules:Granular dispersible formulations reduce dust exposure during handling in European wheat cooperative storage facilities.
- Emulsifiable Concentrates:Oil-in-water systems persist in legacy sulfonylurea product lines facing process revalidation costs for triazole safener retrofitting.
Operational simplicity favors liquid formulations. Technical sophistication drives suspension concentrate adoption.
Distribution Channel:
Cooperative consolidation concentrates procurement decisions, while online retail fragments individual farm purchases.
- Agricultural Cooperatives:Regional cooperative headquarters in the US Corn Belt now control over sixty percent of safener volume allocation decisions, compressing independent formulator access to individual farm relationships.
- Online Retail:E-commerce platforms enable price transparency for smaller wheat producers in Indian states, though logistics constraints limit bulk chemical shipment viability.
- Specialty Stores:Independent agronomic retailers retain influence in vegetable-growing regions where application timing requires localized technical support.
- Wholesalers:Distributor networks face margin pressure as channel consolidation upstream reduces slotting fee leverage.
Procurement power centralizes through cooperatives. Direct farm access fragments across online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and Switzerland, while consumption concentrates across North American grain belts and Indian wheat regions. Regulatory divergence between EPA mandates and REACH dossier requirements is fragmenting product registration strategies. Each geography now demands chemistry-specific compliance pathways.
United States
The US Corn Belt generates sustained safener volume through cooperative procurement desks managing sulfonylurea herbicide rotations. EPA registration mandates under FIFRA now embed safeners into new active ingredient approvals, extending development timelines. Research Triangle Park hosts regulatory affairs units navigating endangered-species assessment requirements.
Canada
Canadian prairie provinces drive demand through wheat and canola cooperative buying structures. Health Canada's PMRA maintains alignment with EPA data requirements while imposing additional aquatic toxicity thresholds. Calgary and Winnipeg distribution hubs are consolidating inventory commitments ahead of triazole chemistry transitions.
Germany
Rhineland-Palatinate and Bavaria wheat regions face immediate product substitution pressure from ECHA's 2024 oxime carbamate metabolite classifications. REACH authorization amendments now classify certain safener breakdown products as substances of very high concern. BASF SE leverages Ludwigshafen manufacturing integration to accelerate alternative chemistry dossier submissions.
India
Punjab and Haryana states present underpenetrated demand as FAO-backed extension programs promote sulfonylurea adoption in high-yield wheat varieties. The Central Insecticides Board mandates separate safener toxicological data for import registration, creating documentation bottlenecks. Mumbai-based formulators are establishing direct channel partnerships with state agricultural departments.
France
Paris Basin and Picardy wheat cooperatives are restructuring inventory commitments ahead of REACH sunset dates for legacy phenolic safeners. ANSM and ECHA coordination is accelerating metabolite toxicity evaluations beyond standard authorization timelines. Lyon formulation facilities are retrofitting production lines for triazole-based alternatives.
Herbicide Safeners Market Vendor Landscape
Top-tier vendors anchor integrated crop protection portfolios, while mid-tier specialists compete through regional channel control and chemistry-specific formulation expertise. The competitive terrain stratifies between R&D-intensive conglomerates with captive regulatory affairs capabilities and agile formulators serving cooperative procurement desks. Three archetypes dominate: diversified agrochemical conglomerates, regional formulation specialists, and precision agriculture technology integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with drone application protocols and micro-encapsulation licensing reshaping alliance structures.
Among diversified agrochemical conglomerates, BASF SE, Bayer AG, and Syngenta Group exemplify the integrated portfolio archetype. These entities occupy positions where regulatory affairs scale and manufacturing integration create defensive moats around wheat belt procurement relationships. Their Basel and Research Triangle Park corridors concentrate metabolic pathway modeling expertise that smaller competitors cannot replicate.
| Leading Market Players |
|---|
| Corteva Agriscience |
| UPL Limited |
| BASF SE |
| Nufarm Limited |
| ADAMA Agricultural Solutions Ltd. |
| Syngenta Group |
| FMC Corporation |
| Sumitomo Chemical Company, Limited |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Oxime carbamate feedstock costs transmit downstream through triazole safener formulations into premium pricing tiers for temperature-resilient wheat applications, while phenolic compound margins compress under generic competition across US Corn Belt cooperative procurement desks.
Pricing Analysis
Margin tightening in phenolic safener tiers reflects generic manufacturer entry and cooperative volume aggregation power across North American grain belts. Three-tier pricing structure across premium triazole, standard phenolic, and economy dinitroaniline levels separates temperature-stress performance grades. Cost-down pressure on novel oxime chemistries accelerates because petrochemical input volatility destabilizes R&D pipeline economics. Large-scale cereal cooperatives exhibit lowest price sensitivity due to bundled herbicide-safener contract structures, while independent vegetable growers face highest sensitivity as microbial bioherbicide alternatives erode willingness-to-pay.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Basel, and Research Triangle Park anchor hub-and-spoke patterns for formulated safener shipments to wheat cooperative storage facilities. Manufacturing concentrates in Germany, Switzerland, and the United States, with active ingredient synthesis tethered to Rhineland-Palatinate and Bavaria chemical complexes. Raw material dependencies span aniline derivatives, nitrogen heterocycle precursors, and petrochemical carbamate intermediates. Single-source vulnerability sits with metabolic pathway modeling expertise concentrated in Basel and Research Triangle Park corridors. Distribution runs through agricultural cooperative headquarters rather than traditional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA registration mandates under FIFRA function as a cost-of-compliance barrier that entrenches incumbents with captive regulatory affairs scale while raising capital requirements beyond emerging player reach.
For Market Incumbents: Extend regulatory dossier capabilities into REACH authorization amendments ahead of ECHA sunset dates for oxime carbamate metabolites, and deepen backward integration into triazole precursor manufacturing to secure margin position against feedstock volatility. Microbial bioherbicide substitution threats in vegetable applications demand defensive patent landscaping around detoxification enzyme induction mechanisms. For New Entrants and Emerging Players: E-commerce platform partnerships with state agricultural departments offer route-to-market access in Indian wheat belt regions where FAO extension programs drive sulfonylurea adoption. Precision agriculture service providers represent the most penetrable channel archetype, with drone application integration creating white-space positioning beyond cooperative procurement concentration. Target formulation licensing agreements with aerial spray operators rather than direct cooperative slotting competition. For Investors and Strategic Acquirers: ECHA substance evaluation roadmap acceleration is the leading indicator that metabolite toxicity dossier capabilities will command acquisition premiums in the medium-term viability window. Acquisition target archetypes include regional formulators with established Central Insecticides Board registration experience and computational toxicology boutiques in cytochrome P450 enzyme modeling. Monitor EPA endangered-species assessment rulings as the inflection signal reshaping product-specific market access faster than chemistry innovation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Triazole Precursors | Ludwigshafen manufacturing complexes secure feedstock position against oxime carbamate volatility. |
| REACH Authorization Dossier Expansion | Basel regulatory units accelerate alternative chemistry submissions ahead of ECHA sunset deadlines. |
| Drone Application Protocol Licensing | Precision agriculture service providers in Canadian prairie provinces open channel partnerships beyond cooperatives. |
| Micro-Encapsulation Technology Partnership | Controlled-release matrices match herbicide degradation curves for wheat cooperative reapplication reduction. |
| Indian State Agricultural Department Alliances | Mumbai formulators establish direct channel access in Punjab and Haryana extension program territories. |
Methodological Framework
Independent corroboration across plant manager interviews at Rhineland-Palatinate formulation facilities, procurement leads at North American wheat cooperatives, and regulatory affairs directors in Research Triangle Park underwrites the qualitative findings. Secondary validation drew from EPA FIFRA registration databases, ECHA authorization submissions, customs trade data for safener active ingredient flows, and SEC filings of diversified agrochemical conglomerates. Bottom-up volume estimates from cooperative procurement desk aggregation combined with top-down chemistry-class segmentation triangulation anchored market sizing.
Comparable-period anchoring against historical sulfonylurea herbicide adoption curves established baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include chemistry class, crop application, formulation type, and regional regulatory cluster. CAGRs derived from weighted average of segment-specific growth trajectories incorporating triazole chemistry transition rates, REACH compliance investment intensity, and cooperative procurement consolidation patterns. Forecast inputs encompassed temperature-stress resilience requirements and drone application adoption curves.
Inputs from regulatory filing databases and cooperative procurement managers were available through the study window; gaps in real-time inventory commitment data from consolidated buying desks introduce uncertainty bands around near-term volume allocation forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Crop Bactericides Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Europe Fungicide Market
Crop Protection
Tebuconazole Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
South America Acaricides Market
Crop Protection
Pest Control Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Fogger Market
Crop Protection
Isoxaflutole Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Specialty Pesticides Market