
 Sweet Potato Fly Market | 2026-2036
Sweet Potato Fly Market Size, Share, and Industry Trends Forecast 2026-2036
Sweet Potato Fly Market Analytics
Buyer concentration among processed food manufacturers is pivoting toward vertically integrated sweet potato suppliers with captive pest management programs. McCain Foods Limited leverages its frozen vegetable supply chain to mandate IPM compliance across contract farms. Lamb Weston Holdings, Inc. anchors its procurement in the Pacific Northwest with weevil-free certification requirements. Nestlé differentiates through biological control partnerships that eliminate chemical residue risks in baby food ingredient streams.
Sweet potato fly denotes the larval and adult stages of Cylas formicarius and related pests that tunnel into tuber flesh, causing internal damage that renders crops unmarketable for fresh or processed use. Pheromone trapping density and degree-day modeling for emergence prediction represent core technical parameters guiding treatment timing. The pest control method segment shows biological and integrated approaches gaining share as chemical registrations face pressure, while the application area dimension reveals greenhouse operations commanding premium pricing due to zero-tolerance quarantine protocols. The lifecycle stage category concentrates monitoring investment on larvae detection, since internal feeding causes irreversible quality loss before external symptoms appear.
The EPA regulates agricultural chemical residues under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU Green Deal's Farm to Fork strategy targets 50% pesticide reduction, directly constraining chemical control options. California's Department of Pesticide Regulation imposes additional restrictions on soil fumigants in the Imperial Valley, accelerating grower migration to biological alternatives. Stakeholders must monitor pheromone disruption technology maturation and biocontrol agent registration pipelines to secure supply positions ahead of regulatory phase-outs.
Market Dynamics
Regulatory phase-out of soil fumigants across California's Central Valley and the Netherlands' greenhouse clusters is compressing treatment windows and forcing rapid biological control adoption. Degree-day modeling and pheromone disruption systems now determine competitive positioning among pest management providers.
Growth Catalysts
- EU Green Deal pesticide reduction targets:The 50% pesticide reduction mandate under Farm to Fork is eliminating chemical alternatives in Dutch and Spanish export-oriented greenhouse operations.
- Pheromone mating disruption maturation:Synthetic sex pheromone formulations now achieve 90%+ trap suppression efficacy, enabling precise larval emergence prediction in California's Imperial Valley.
- Phytosanitary certification premiums:Japanese and South Korean import protocols for Cylas formicarius-free tubers create price premiums for certified supply chains.
Market Restraints
- Biocontrol agent registration timelines:EPA and EFSA evaluation periods for entomopathogenic nematodes extend 18-36 months, delaying commercial deployment.
- Input cost volatility:Laboratory-reared parasitoid wasp production depends on sterile insect diet substrates vulnerable to agricultural commodity price swings.
- Technical limitation in detection:Internal larval feeding produces no external symptoms until irreversible tuber damage occurs, complicating early intervention economics.
Strategic Opportunities
- Underpenetrated Australian fresh export segment:Queensland and New South Wales sweet potato growers lack integrated pheromone monitoring infrastructure despite expanding Asian market access.
- Technology convergence:IoT-enabled trap networks combined with machine learning image recognition enable real-time population density mapping and automated treatment alerts.
- Regulatory tailwind from California DPR:The Department of Pesticide Regulation's soil fumigant buffer zone restrictions accelerate grower subsidies for biological transition programs.
Industry Challenges
- Entomological modeling expertise scarcity:Degree-day calculation and phenological forecasting require specialized agricultural extension knowledge concentrated in land-grant university programs.
- Greenhouse infrastructure retrofit costs:Existing Dutch Venlo-style structures require ventilation modifications to accommodate mass-released parasitoid dispersal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweet Potato Fly Market |
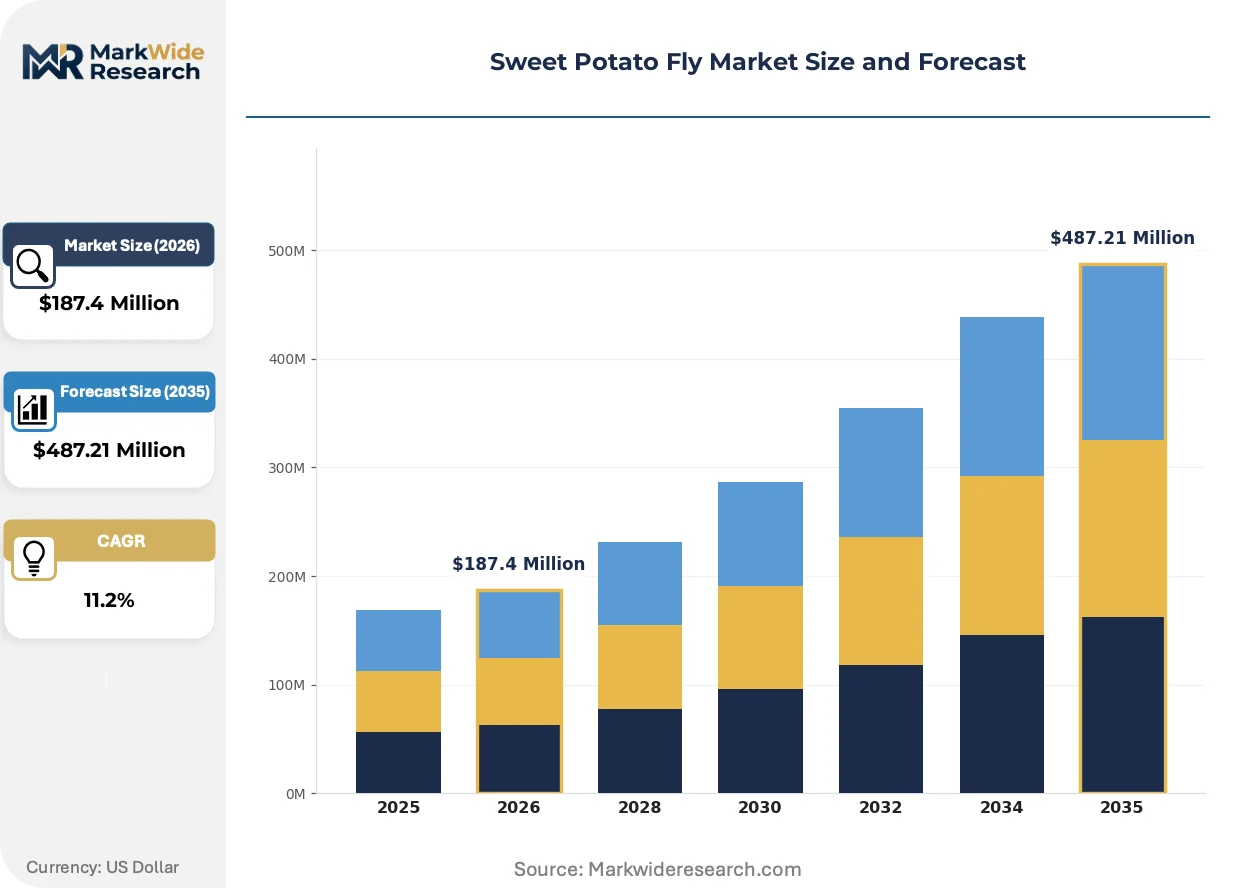
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pest Control Method: Chemical, Biological, Cultural, Integrated Application Area: Agricultural Fields, Greenhouses, Organic Farms, Home Gardens Fly Species: Sweet Potato Weevil, Aphid, Leaf Miner, Others Lifecycle Stage: Larvae, Adult, Egg, Pupa |
| Companies Covered | McCain Foods Limited, Nestlé, Dole Food Company Inc., Lamb Weston Holdings, Inc., AV Thomas Produce, Jackson Farming Company, Ham Farms, Conagra Brands, Inc., PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweet Potato Fly Market Evolving Landscape
Precision entomology tools are compressing the gap between pest detection and biological intervention, eliminating the latency that previously favored calendar-based chemical spraying. Three concurrent developments are restructuring competitive dynamics.
RNA interference-based biopesticides targeting Cylas formicarius-specific gene sequences are rewriting treatment economics for organic-certified operations. California's Central Valley cooperatives are piloting foliar-applied dsRNA formulations ahead of EPA registration decisions. The technology is compressing the efficacy gap between biological and chemical mortality rates.
REACH authorization requirements for soil-applied insecticides are eliminating chlorpyrifos alternatives across EU member state greenhouse clusters. Dutch growers face 2027 deadlines for complete phase-out of authorized chemical stocks. Biological control service contracts now structure pricing around guaranteed weevil-free certification rather than treatment frequency.
Buyer consolidation among frozen vegetable processors is fragmenting supplier relationships into tiered certification categories. McCain Foods and Lamb Weston now mandate third-party IPM audit compliance as a contract precondition, displacing spot-market tuber purchases. This restructuring is most visible in the Pacific Northwest, where processor-owned cold storage facilities enforce 48-hour post-harvest quarantine protocols.
Sweet Potato Fly Market Segmentation
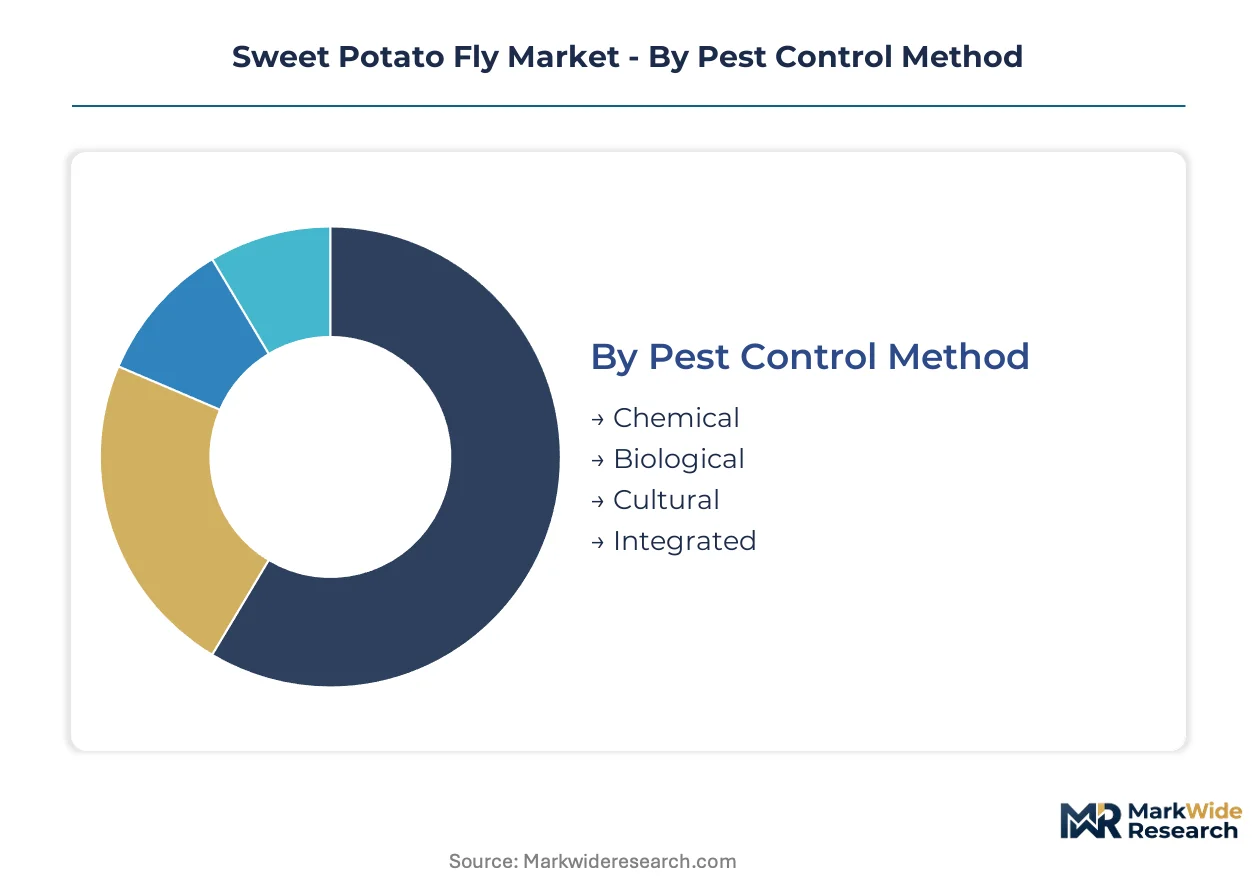
Sweet potato fly management demands precise alignment between pest biology, cultivation environment, and regulatory constraints. Segmentation reveals where technology investments concentrate and which control modalities command premium positioning across divergent grower economics.
Pest Control Method:
Standardized chemical protocols dominate commodity production, while biological and integrated approaches customize service delivery for export-certified and organic supply chains.
- Chemical:Synthetic pyrethroids and organophosphates deliver immediate mortality for calendar-based spray programs. Demand concentrates in conventional agricultural fields across India's Maharashtra and Karnataka states, where cost-per-hectare thresholds override residue concerns for domestic-market tubers.
- Biological:Entomopathogenic nematodes and mass-reared parasitoid wasps target larval stages with species-specific precision. California's Imperial Valley cooperatives and the Netherlands' Westland greenhouse cluster anchor procurement, driven by Japanese and South Korean phytosanitary certification requirements that reject chemical residues entirely.
- Cultural:Crop rotation intervals, harvest timing adjustments, and post-harvest curing protocols disrupt weevil population cycles without input costs.
- Integrated:Pheromone monitoring networks combined with threshold-triggered biological release optimize intervention timing and minimize ecological impact.
Leading the category by volume: Chemical. Expanding most quickly: Biological.
Application Area:
Facility infrastructure determines monitoring precision and treatment delivery mechanisms across the cost-to-value spectrum.
- Agricultural Fields:Open-field operations deploy perimeter pheromone traps and degree-day modeling across thousands of hectares. Queensland and New South Wales in Australia lack integrated monitoring infrastructure despite expanding Asian export access, creating supply gaps for certified tuber streams.
- Greenhouses:Controlled-environment agriculture enables zero-tolerance quarantine protocols through physical exclusion and climate-manipulated pest suppression. Dutch Venlo-style structures command premium pricing for biological service contracts structured around guaranteed weevil-free certification.
- Organic Farms:Certified operations face absolute prohibitions on synthetic inputs, mandating pheromone disruption and biocontrol exclusivity.
- Home Gardens:Small-scale cultivation relies on visual inspection and basic trapping without systematic population monitoring.
Dominant by revenue concentration: Greenhouses. Steepest expansion trajectory: Agricultural Fields in underpenetrated export zones.
Fly Species:
Species-specific biology dictates tunneling patterns, host range, and consequently the technical sophistication required for effective suppression.
- Sweet Potato Weevil:Cylas formicarius larvae tunnel into tuber flesh, causing internal damage invisible until harvest. California's Central Valley and the Netherlands' greenhouse clusters concentrate monitoring investment here, since this species triggers the strictest import prohibitions.
- Aphid:Vector for sweet potato feathery mottle virus, causing yield reduction through secondary infection rather than direct tuber damage.
- Leaf Miner:Liriomyza species larvae create serpentine mines in foliage, reducing photosynthetic capacity and marketable leaf quality for specialty greens.
- Others:Secondary pests including whiteflies and thrips require identification-specific protocols that complicate integrated management planning.
Commanding greatest R&D investment: Sweet Potato Weevil. Fastest protocol diversification: Aphid as virus vector management converges with seed certification systems.
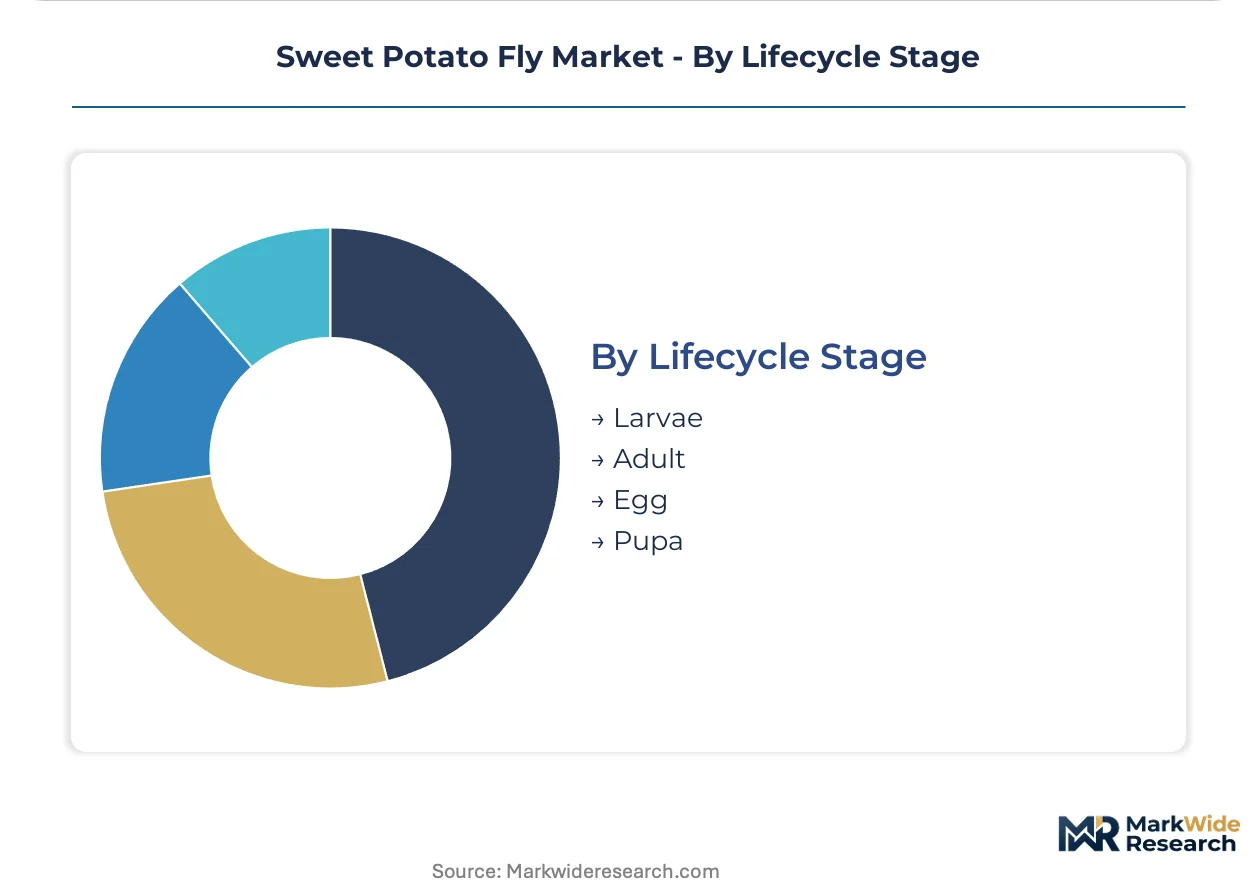
Lifecycle Stage:
Detection feasibility and intervention windows vary dramatically across developmental phases, concentrating technology investment where early action prevents irreversible loss.
- Larvae:Internal feeding stage produces no external symptoms until tuber quality is already compromised. Pheromone trapping density and degree-day modeling for emergence prediction represent the core technical parameters guiding treatment timing investments.
- Adult:Mobile stage enables pheromone-based mating disruption and mass trapping with synthetic sex pheromone formulations achieving suppression efficacy above ninety percent.
- Egg:Cryptic placement in stem bases and leaf axils resists direct detection, shifting control focus to oviposition deterrents.
- Pupa:Soil-dwelling stage susceptible to entomopathogenic nematode applications and soil temperature manipulation.
Greatest monitoring expenditure: Larvae. Emerging fastest: Adult-stage pheromone disruption as registration pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processed food manufacturers in the United States and the Netherlands drive procurement standards for integrated pest management solutions, with regulatory pressure from FDA and EFSA residue limits tightening compliance requirements across export-oriented supply chains.
United States
California's Central Valley and Imperial Valley anchor domestic biological control adoption, where the Department of Pesticide Regulation imposes soil fumigant buffer zone restrictions that accelerate grower subsidies for transition programs. McCain Foods mandates IPM compliance across contract farms in the Pacific Northwest, while Lamb Weston enforces weevil-free certification requirements through processor-owned cold storage facilities.
Netherlands
Westland greenhouse clusters command premium pricing for biological service contracts structured around guaranteed weevil-free certification, driven by EU Green Deal Farm to Fork pesticide reduction targets. REACH authorization requirements eliminate chlorpyrifos alternatives with 2027 deadlines for complete phase-out, restructuring supplier relationships into tiered certification categories for export-oriented growers.
Australia
Queensland and New South Wales sweet potato growers lack integrated pheromone monitoring infrastructure despite expanding Asian market access, creating supply gaps for certified tuber streams. The country's national agricultural regulator maintains strict phytosanitary protocols for Cylas formicarius-free exports to Japan and South Korea, where import premiums reward certified supply chains.
Japan
Import protocols for Cylas formicarius-free tubers create price premiums that propagate backward through Asian supply chains, concentrating demand for pheromone-based certification systems. METI coordinates with prefectural agricultural extensions to standardize degree-day modeling approaches across Kyushu and Kanto growing regions, where domestic production competes with certified imports.
India
Maharashtra and Karnataka states maintain conventional chemical spray programs for domestic-market tubers, where cost-per-hectare thresholds override residue concerns. The country's food safety regulator monitors agricultural chemical residues under standards that diverge from export-oriented phytosanitary requirements, segmenting procurement between commodity and certified supply chains.
Sweet Potato Fly Market Competitive Landscape
North American processors anchor one tier; European greenhouse specialists hold certification-driven positioning. The market structures around three archetypes: frozen vegetable processors with captive IPM mandates, biological control service providers with guaranteed outcome contracts, and integrated suppliers with in-house pest management programs. M&A activity concentrates on pheromone technology licensing, while strategic partnerships link biocontrol agent developers with greenhouse operators facing regulatory deadlines.
Within the processor-driven tier, McCain Foods Limited and Lamb Weston Holdings, Inc. represent vertically integrated procurement models that mandate third-party audit compliance as contract preconditions. Nestlé occupies a distinct position through biological control partnerships that eliminate chemical residue risks in ingredient streams. These three companies exemplify how buyer concentration is fragmenting supplier relationships into tiered certification categories that displace spot-market purchases.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Nestlé |
| Dole Food Company Inc. |
| Lamb Weston Holdings, Inc. |
| AV Thomas Produce |
| Jackson Farming Company |
| Ham Farms |
| Conagra Brands, Inc. |
| PepsiCo |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between phytosanitary-compliant and commodity tuber streams manifests in both contract pricing premiums and supply chain segregation. Japanese and South Korean import protocols force biological control investments upstream, while domestic-market growers in India absorb chemical input volatility without price recovery mechanisms.
Pricing Analysis
Volume-vs-margin split separates frozen vegetable processors purchasing on weevil-free certification from spot-market commodity growers. Three-tier pricing structure across certified-export, processor-contract, and domestic-commodity levels reflects phytosanitary compliance costs and residue testing investments. Pricing pressure stems from entomopathogenic nematode production scale limitations and laboratory-reared parasitoid substrate cost volatility. Processor buyers exhibit lowest price sensitivity due to captive supply chain requirements, while Indian domestic growers face acute margin compression from chemical input inflation.
Supply Chain Analysis
Freight cost differentials between live biocontrol agent shipments and stable chemical formulations concentrate supplier selection in California and the Netherlands. Production draws from mass-rearing facilities in California's Central Valley, the Netherlands' Westland cluster, and emerging capacity in Queensland. Raw material dependencies include sterile insect diet substrates, synthetic pheromone precursors, and climate-controlled greenhouse infrastructure. Single-source vulnerability pervades pheromone synthesis capabilities concentrated among specialty chemical manufacturers. Distribution runs through processor-owned cold storage networks enforcing quarantine protocols before contract settlement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pheromone disruption technology is displacing calendar-based chemical spraying as the dominant pest suppression modality, compressing treatment economics and restructuring supplier relationships across export-oriented growing regions.
For Market Incumbents: Lock in pheromone technology licensing positions ahead of EPA and EFSA registration deadlines for RNA interference formulations. Deepen backward integration into mass-rearing facilities to secure parasitoid wasp supply against diet substrate price volatility. Processor contract renewals now mandate third-party IPM audit compliance as a non-negotiable precondition. For New Entrants and Emerging Players: Begin with underpenetrated Australian pheromone monitoring infrastructure in Queensland and New South Wales, where expanding Asian export access lacks technical service coverage. IoT-enabled trap networks with machine learning image recognition offer differentiated entry against incumbent manual scouting services. Partner with California Department of Pesticide Regulation subsidy programs to accelerate biological transition adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in biological control service providers with guaranteed weevil-free certification contracts rather than input suppliers. Long-term viability hinges on pheromone formulation IP and entomological modeling expertise concentration in land-grant university programs. Monitor EPA registration pipeline announcements for entomopathogenic nematode approvals as inflection indicators for scalable deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Pheromone Technology Licensing | Secures IP positioning ahead of regulatory phase-outs in California and Dutch greenhouse clusters. |
| Mass-Rearing Facility Expansion | Captures economies of scale in parasitoid wasp production for Japanese phytosanitary certification demand. |
| IoT Trap Network Deployment | Enables real-time population mapping for Queensland growers lacking integrated monitoring infrastructure. |
| Processor Contract Restructuring | Aligns pricing with guaranteed weevil-free outcomes rather than treatment frequency in Pacific Northwest supply chains. |
| RNA Interference Pipeline Investment | Positions for organic-certified market entry as EPA evaluates dsRNA formulation registrations. |
Research Methodology
Independent corroboration across agricultural extension specialists, frozen vegetable procurement directors, and biological control service providers underwrites the qualitative findings in this study. Primary interviews with entomological researchers at land-grant universities, greenhouse operations managers in Dutch Westland clusters, and California Department of Pesticide Regulation officials supplied forward-looking regulatory intelligence. Secondary validation drew from EPA registration databases, EFSA scientific opinions, Japanese MAFF phytosanitary bulletins, and customs trade data for certified tuber exports. Bottom-up grower survey data and top-down processor procurement volume estimates were reconciled through iterative triangulation.
Comparable-period anchoring to historical biological control adoption curves in California's Imperial Valley established baseline penetration rates across the projection horizon. The analytical framework modeled pest control method, application area, and lifecycle stage dimensions alongside regulatory cluster segmentation by jurisdiction. CAGRs were derived from degree-day modeling adoption trajectories and pheromone disruption efficacy maturation curves. Forecast inputs incorporated EU Green Deal pesticide reduction compliance deadlines and Japanese import protocol enforcement intensity.
Underlying measurement precision varies by segment; greenhouse biological control contracts carry tighter precision than open-field commodity estimates due to standardized reporting requirements. Forecasts reflect assumptions about regulatory timeline adherence and biocontrol agent registration approval pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Europe Soil Treatment Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Global Algaecides Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Iprodione Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
IPM Pheromones Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
South America Nematicides Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Pest Management Services Market
Crop Protection
Europe Acaricides Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Global Acaricides Market
Crop Protection
Organic Pesticides Market