
 France Compound Feed Market | 2026-2036
France Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
France Compound Feed Market Foresight
Soybean meal is consolidating its position as the dominant protein source in French compound feed, displacing regional rapeseed meal in cost-sensitive poultry and swine rations. Cargill Inc. leverages its crush capacity in Saint-Nazaire to anchor supply security for Atlantic coast integrators. TERRENA sustains cooperative ownership structures that dominate western France's channel control. Nutreco N.V. specializes in premix and additive formulations, competing on mineral density and enzyme bioavailability.
Compound feed denotes industrially manufactured, nutritionally complete rations formulated from cereals, oilseeds, forages, minerals, vitamins, and enzymes, processed through grinding, mixing, pelleting, or liquid application to meet species-specific metabolizable energy and amino acid requirements for livestock growth, reproduction, or lactation. Poultry feed leads volume due to France's integrated broiler and layer sectors, while aquafeed represents the fastest-expanding margin pool as Mediterranean and Atlantic finfish farming scales. Mash retains cost advantage for ruminant operations, though pellets command premium positioning in automated pig and poultry systems where feed conversion efficiency determines profitability.
ANSES evaluates novel feed additives and contaminants under France's national food safety mandate, while DGAL enforces EU-wide feed hygiene regulation through port and mill inspections. The EU Green Deal's Farm to Fork strategy tightens protein autonomy targets, pressuring formulators to substitute imported soy with cultivated legumes and processed animal proteins. Stakeholders must monitor protein crop subsidy allocations and biosecurity protocol shifts to align formulation investments with regulatory trajectory.
Market Dynamics
France's compound feed sector faces structural pressure from the EU Green Deal's protein autonomy targets, which mandate substitution of imported soy with domestic legumes and processed animal proteins. This regulatory trajectory forces formulators to reconfigure supply chains and nutritional matrices simultaneously.
Growth Catalysts
- ANSES feed additive approvals:Accelerated novel enzyme and probiotic authorizations enable precision nutrition for dairy cattle, lifting milk yield efficiency benchmarks.
- Brittany livestock density:Concentrated poultry and swine operations around Saint-Nazaire and Lorient sustain captive demand for compound feed volumes.
- Cooperative channel control:TERRENA and regional cooperatives lock in farmer loyalty through integrated grain procurement and technical advisory services.
Market Restraints
- Soybean meal import dependency:Over 70% of protein feedstock arrives via Atlantic ports, exposing margins to currency volatility and Black Sea supply disruptions.
- DGAL inspection intensity:EU-wide feed hygiene enforcement through port and mill audits raises compliance overhead for smaller compounders.
- Rapeseed meal displacement:Cost-competitive soy formulations crowd out regional oilseed proteins, eroding crop rotation incentives for French farmers.
Strategic Opportunities
- Faba bean cultivation expansion:Ile-de-France and Centre-Val de Loire regions offer untapped acreage for protein crop substitution under CAP eco-scheme subsidies.
- Aquafeed margin pool:Mediterranean seabass and Atlantic salmon farming operations seek specialized marine protein formulations.
- Digital feed formulation platforms:Real-time metabolizable energy optimization tools penetrate mid-sized integrator operations.
Industry Challenges
- Precision livestock nutrition expertise:Shortage of veterinarians trained in amino acid balancing and enzyme dosing limits technical service capacity.
- Pelleting line retrofit costs:Automated poultry and pig systems demand particle uniformity specifications that legacy mash equipment cannot achieve.
- Traceability system integration:Blockchain-enabled ingredient tracking requires IT infrastructure upgrades across cooperative networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Compound Feed Market |
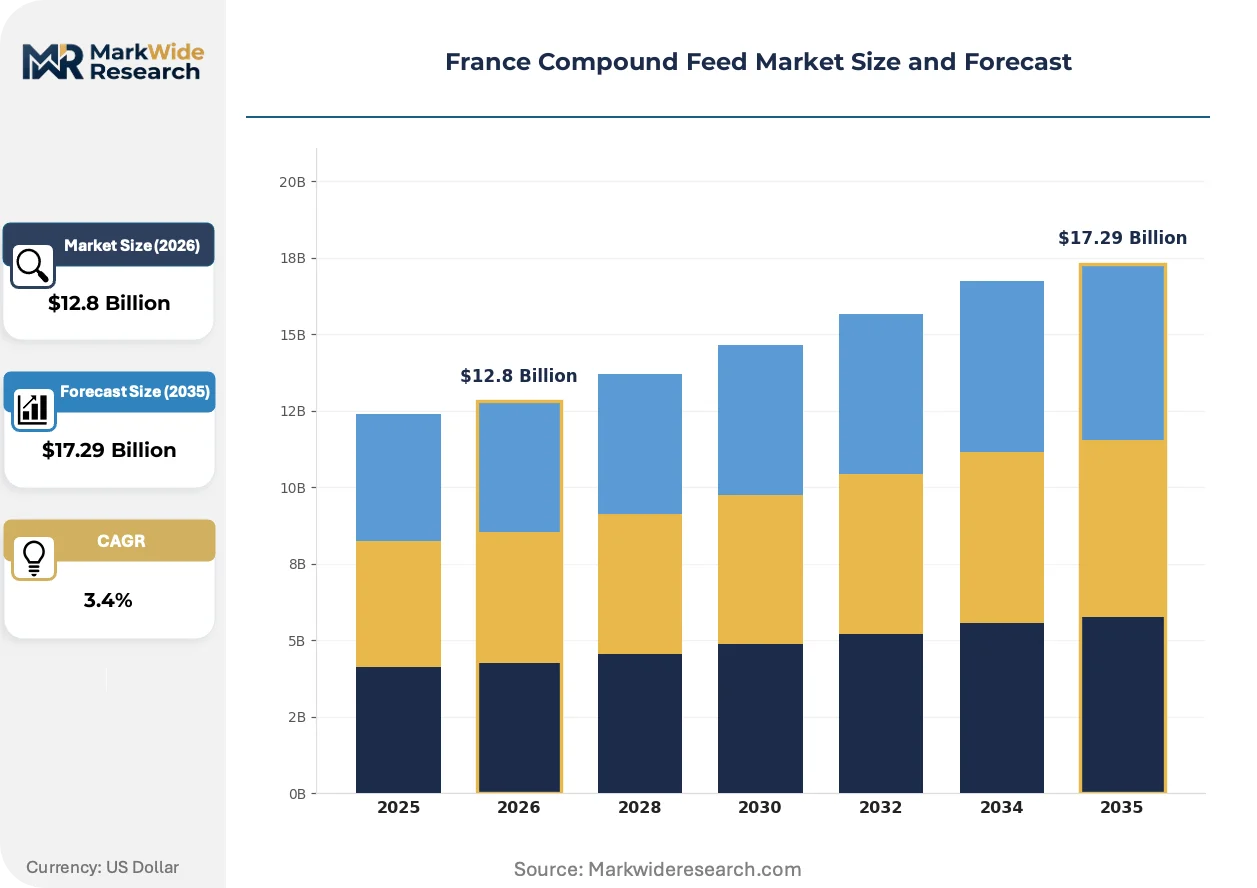
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.29 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Animal Type: Poultry, Swine, Cattle, Aquatic Species, Sheep, Equine Product Form: Pellets, Mash, Crumbles, Granules, Liquids Feed Ingredient: Cereals, Oilseeds, Forages, Minerals, Vitamins, Enzymes Distribution Channel: Direct Sales, Retail Feed Stores, Online Sales, Cooperatives, Dealers |
| Companies Covered | Cargill Inc., Alltech Inc., TERRENA, ForFarmers, Avril Group, Archer Daniels Midland, Nutreco N.V., Neovia Group, ABN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Compound Feed Market Shifts & Advancements
Formulation science is pivoting toward metabolizable energy precision and alternative protein matrices, driven by regulatory protein autonomy mandates and integrator demands for feed conversion efficiency gains.
Exogenous enzyme cocktails targeting non-starch polysaccharides in wheat-barley rations are absorbing formulation share from traditional mineral-dense premixes. Poultry integrators in western France adopt these blends at accelerating rates as phytase and xylanase combinations unlock energy from local cereals. This absorption is compressing premix margins while elevating enzyme suppliers to strategic partnership status.
The EU Green Deal's Farm to Fork strategy tightens protein crop subsidy allocations and processed animal protein re-authorization timelines. French compounders must reformulate rations ahead of 2030 protein autonomy targets, accelerating R&D spending on insect meal and single-cell protein pathways. Dairy cattle operations face the steepest adjustment curves given their reliance on imported soy hulls.
Integrators in Brittany are consolidating procurement decisions through cooperative technical committees, displacing individual farm-level purchasing. This concentration shifts bargaining power toward volume buyers and compresses compounder margins on standard rations. The pattern is most visible in broiler operations where feed represents 65-70% of production costs.
France Compound Feed Market Segmentation
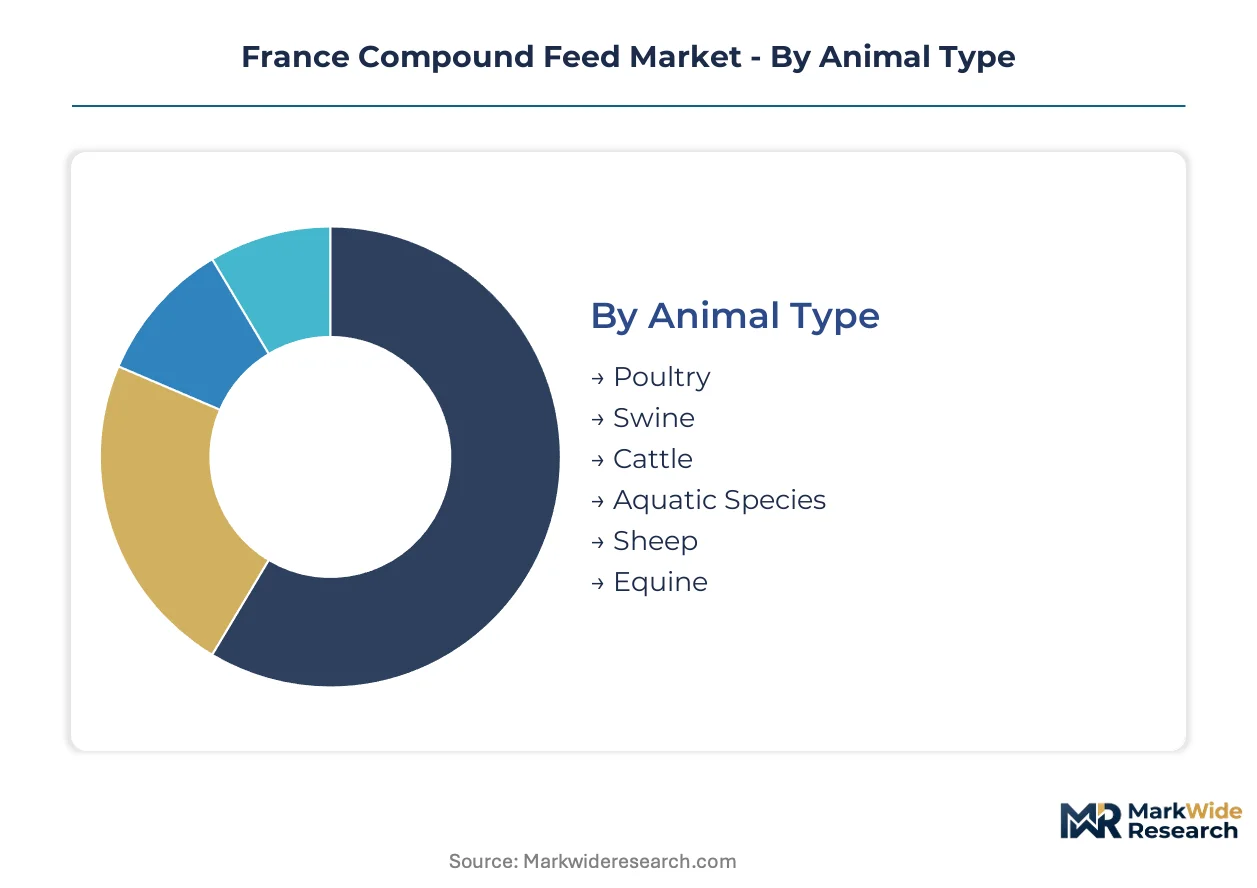
Segmentation in French compound feed reveals how formulation specifications, distribution economics, and species-specific metabolizable energy requirements create distinct competitive arenas. Each axis carries different margin structures and regulatory exposure.
Animal Type:
Species-specific digestive physiology and production intensity drive formulation complexity and pricing power.
- Poultry:Broiler and layer operations in Brittany and Pays de la Loire dominate volume consumption. Automated feeding systems in integrated operations demand precise amino acid profiles and uniform pellet durability for feed conversion efficiency.
- Swine:Post-weaning and finishing phases require phase-feeding protocols with varying lysine-to-energy ratios. Cooperative technical committees in western France centralize procurement decisions, compressing compounder margins on standard grower-finisher rations.
- Cattle:Dairy operations concentrate in Normandy and Brittany, where rumen-protected fats and bypass proteins command premium positioning for milk yield optimization.
- Aquatic Species:Mediterranean seabass and Atlantic salmon farming operations seek specialized marine protein formulations with precise fatty acid profiles.
- Sheep:Seasonal pasture supplementation in Massif Central and Pyrenees regions sustains regional compounder presence through localized mineral blocks.
- Equine:Performance and breeding stables in Ile-de-France drive demand for low-starch, high-fiber rations with controlled non-structural carbohydrate levels.
Mature deployment sits with poultry and swine. Newer deployment is concentrated in aquatic species.
Product Form:
Processing technology investments separate cost-competitive commodity supply from precision nutrition services.
- Pellets:Thermomechanical processing achieves 95% durability indices required by automated pig and poultry systems. Steam conditioning and die specifications determine metabolizable energy retention and feed conversion ratios.
- Mash:Unprocessed grinding retains cost advantage for ruminant operations with self-feeding infrastructure. Brittany dairy cooperatives favor mash for calf starter programs where intake stimulation outweighs labor efficiency.
- Crumbles:Intermediate particle size bridges pellet durability and mash palatability for young poultry.
- Granules:Larger diameter formats suit sheep and goat operations with limited mechanization.
- Liquids:Molasses-based supplements and fat emulsions penetrate high-performance dairy segments.
Capital intensity clusters in pellets. Granules and liquids are gaining share fastest in specialized applications.
Feed Ingredient:
Protein autonomy mandates and ANSES safety evaluations reconfigure sourcing strategies across nutritional categories.
- Cereals:Wheat and barley from Centre-Val de Loire and Picardy provide starch foundations. Local enzyme cocktails targeting non-starch polysaccharides unlock energy from these regional grains.
- Oilseeds:Soybean meal imported through Saint-Nazaire dominates protein supply, displacing regional rapeseed meal in cost-sensitive formulations.
- Forages:Dehydrated alfalfa from Crau and Val de Saône supplies rumen fiber for dairy cattle.
- Minerals:Premix formulations compete on bioavailability coefficients and precision dosing systems.
- Vitamins:Stability in pelleting conditions determines supplier selection for A, D, and E supplementation.
- Enzymes:Phytase and xylanase combinations absorb formulation share from mineral-dense premixes as integrators seek feed conversion gains.
Ingredient sophistication is deepest in enzymes. Oilseeds face the steepest substitution pressure under protein autonomy targets.
Distribution Channel:
Channel structure determines technical service intensity and working capital requirements.
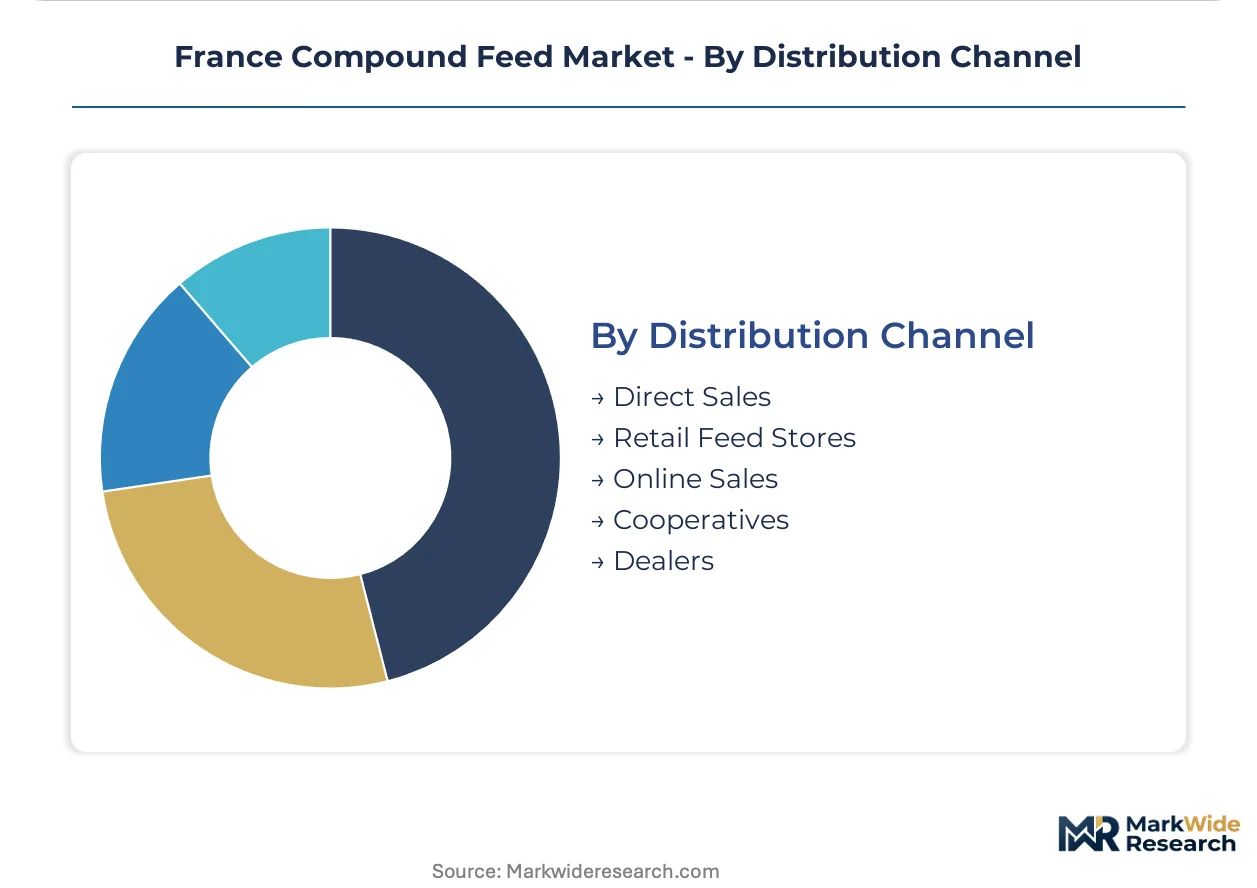
- Direct Sales:Large integrators in Brittany negotiate volume contracts with compounders for customized premix programs and real-time formulation adjustments.
- Cooperatives:TERRENA and regional groups lock in farmer loyalty through integrated grain procurement, credit facilities, and veterinary advisory services.
- Retail Feed Stores:Independent merchants serve hobby farmers and equine operations with bagged specialty products.
- Dealers:Regional distributors extend compounder reach into fragmented cattle and sheep segments.
- Online Sales:Digital platforms penetrate smallholder poultry and hobby equine markets with subscription delivery models.
Cooperative channel control is entrenched in western France. Direct sales are climbing the fastest as integrator consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound feed demand clusters in France's western livestock corridors, where dense poultry, swine, and dairy operations anchor formulation volumes and shape distribution economics across sub-regional markets.
Brittany
Integrated broiler and layer operations around Saint-Nazaire and Lorient sustain the highest feed consumption density in France. DGAL inspection protocols enforce EU feed hygiene standards through port and mill audits along the Atlantic coast. Cargill's crush capacity at Saint-Nazaire secures soybean meal supply for cooperative integrators in the region.
Normandy
Dairy cattle operations concentrate in Calvados and Manche, where rumen-protected fats and bypass proteins command premium positioning for milk yield optimization. ANSES evaluates novel feed additives under national food safety mandates affecting local formulators. Dehydrated alfalfa from Crau supplies fiber requirements for high-production herds across the dairy belt.
Pays de la Loire
Swine finishing operations around Cholet and La Roche-sur-Yon drive phase-feeding demand with varying lysine-to-energy ratios. Cooperative technical committees centralize procurement decisions, compressing compounder margins on standard grower-finisher rations. TERRENA's integrated grain procurement locks in farmer loyalty through credit facilities and veterinary advisory services.
Centre-Val de Loire
Wheat and barley production from Beauce and Sologne provides starch foundations for regional formulations. CAP eco-scheme subsidies incentivize faba bean cultivation for protein crop substitution under EU Green Deal protein autonomy targets. Local enzyme cocktails targeting non-starch polysaccharides unlock energy from these regional grains for poultry and swine rations.
Occitanie
Mediterranean seabass farming operations around Sète and Frontignan seek specialized marine protein formulations with precise fatty acid profiles. Aquafeed represents the fastest-expanding margin pool as finfish farming scales along the Languedoc coast. Premix suppliers compete on mineral density and enzyme bioavailability for high-performance aquatic species.
France Compound Feed Market Competitive Landscape
Cooperative channel consolidation dominates the current landscape as TERRENA and regional groups tighten farmer loyalty through integrated grain procurement and technical advisory services. The vendor base organizes around three strategic archetypes: multinational traders with crush capacity, cooperative-owned compounders with distribution control, and premix specialists competing on formulation precision. Capacity expansion at Atlantic port facilities and backward integration into oilseed processing represent the primary competitive vectors reshaping supply security.
Among multinational operators, Cargill Inc. and Archer Daniels Midland exemplify trader-archetype positioning through crush assets and port access. Nutreco N.V. occupies the premix-specialist tier, competing on mineral density and enzyme bioavailability. TERRENA represents cooperative-channel control, anchoring western France's distribution economics through integrated procurement and farmer financing structures.
| Leading Market Players |
|---|
| Cargill Inc. |
| Alltech Inc. |
| TERRENA |
| ForFarmers |
| Avril Group |
| Archer Daniels Midland |
| Nutreco N.V. |
| Neovia Group |
| ABN |
| Others |
Supply & Pricing Matrix
Premium-mid-economy pricing differentiation across French compound feed separates enzyme-enhanced precision formulations from commodity mash rations, with the divergence widening as cooperative procurement concentrates volume buying power in Brittany and western regions. This tiered structure feeds directly into supply chain configurations, where Atlantic port access for imported soybeans anchors cost-competitive standard rations while domestic enzyme production and regional grain origination sustain premium positioning.
Pricing Analysis
Volume-margin splits favor commodity mash for ruminant operations while precision pellets capture premium returns in automated poultry and swine systems. Price differentiation rests on formulation complexity and ANSES additive certification tiers, with enzyme-enhanced rations commanding substantial uplifts over mineral-dense premix alternatives. Cost compression in standard grower-finisher rations is intensifying because cooperative technical committees centralize procurement decisions across western France. Small cattle operations exhibit highest price sensitivity, whereas integrated broiler systems prioritize feed conversion efficiency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Atlantic port dependency for soybean meal arriving through Saint-Nazaire, exposing formulators to currency volatility and Black Sea supply disruptions. Geographic supply concentration centers on Brazil, Argentina, and Ukraine for protein feedstock, while regional wheat and barley from Centre-Val de Loire provide starch foundations. Raw material dependencies include imported soy hulls, regional cereals, and specialized marine proteins for aquafeed formulations. Distribution runs through cooperative networks anchored by TERRENA, with direct sales to large integrators gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's compound feed sector is consolidating as protein autonomy mandates and cooperative procurement concentration squeeze sub-scale compounders without backward integration or formulation specialization.
For Market Incumbents: Acquire crush capacity and oilseed processing assets to secure supply security against import volatility. Defensive positioning requires deepening enzyme formulation partnerships with poultry integrators while retrofitting pelleting lines for automated system specifications. The threat of rapeseed meal displacement by cost-competitive soy formulations demands captive supply of domestic protein crops through CAP eco-scheme cultivation contracts. For New Entrants and Emerging Players: Mediterranean aquafeed integrators represent the most penetrable buyer archetype, with specialized marine protein formulations underserved by incumbent compounders. White-space targets include digital feed formulation platforms for mid-sized operators and faba bean processing for protein crop substitution. Go-to-market positioning should emphasize real-time metabolizable energy optimization and ANSES-compliant novel additive pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in cooperative acquisition by multinational traders seeking channel control in western France. Long-term viability favors premix specialists with enzyme bioavailability expertise and aquafeed formulators capturing fastest-expanding margin pools. Watch for DGAL inspection intensity increases as inflection indicators for compliance overhead pressure on smaller compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's Saint-Nazaire crush capacity secures soybean meal supply for Atlantic coast integrators. |
| Enzyme Formulation Partnership | Phytase and xylanase combinations absorb share from mineral-dense premixes in poultry operations. |
| CAP Eco-Scheme Cultivation Contract | Faba bean expansion in Centre-Val de Loire addresses EU Green Deal protein autonomy targets. |
| Pelleting Line Retrofit Investment | Steam conditioning upgrades achieve durability indices required by automated pig and poultry systems. |
| Aquafeed Specialization Program | Mediterranean seabass and Atlantic salmon farming operations seek precise fatty acid formulations. |
Research Methodology
Document review covered customs and trade data for feed ingredient flows, ANSES additive approval registers, and CAP subsidy allocation records, complemented by interviews with cooperative procurement directors, compounder formulation scientists, poultry integrator operations managers, and DGAL inspection officers. Secondary validation drew from EU feed hygiene enforcement reports, regional agricultural statistics, and port throughput disclosures. Bottom-up volume modeling triangulated against top-down sector expenditure estimates.
Market size and growth projections across the analysis window employed segmentation by animal type, product form, feed ingredient category, and distribution channel, with CAGRs derived from historical trajectory analysis and regulatory impact assessment. Industry-specific inputs included protein autonomy mandate timelines, enzyme adoption curves in western France integrators, and cooperative consolidation patterns in Brittany and Pays de la Loire.
Revisions become necessary when EU protein crop subsidy allocations shift, DGAL inspection protocols intensify, or Black Sea supply disruptions materialize beyond historical volatility patterns. Forecasts reflect documented assumptions about regulatory trajectory and technology adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Italy Alfalfa Market