
 North America Insecticide Market | 2026-2036
North America Insecticide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insecticide Market Insights
Entomologist staffing at agricultural extension services is collapsing across the US Midwest, stretching grower access to integrated pest management expertise. Bayer AG leverages its digital farming platform to bridge this advisory gap through remote pest monitoring tools. Corteva Agriscience anchors its position with proprietary seed-treatment combinations that reduce foliar spray dependence. FMC Corporation differentiates through a concentrated portfolio of diamide chemistry targeting lepidopteran resistance management.
North America insecticides comprise synthetic and biological formulations designed to disrupt arthropod nervous systems, reproductive cycles, or metabolic pathways through contact, systemic, or translaminar action, with active ingredient concentrations typically ranging from 0.5% to 40% depending on crop protection or public health application. These compounds serve primarily to safeguard yield and quality in row crops, specialty agriculture, turf management, and vector control programs. Liquid formulations dominate commercial channels due to ease of tank-mixing and aerial application compatibility, while granular products sustain steady demand in turf and ornamental segments where soil-dwelling pest pressure is pronounced. Foliar spray remains the largest application method by volume, though seed treatment is displacing early-season sprays in corn and soybeans as growers prioritize upfront protection and reduced field passes.
EPA FIFRA re-registration timelines and state-level pollinator protection plans in California and New York are tightening neonicotinoid access and pushing reformulation toward biopesticide alternatives. Health Canada's PMRA conducts parallel regulatory reviews that influence cross-border product availability and label harmonization. USDA conservation programs incentivize reduced-risk pesticide selection, redirecting procurement patterns among cooperative extension networks. Stakeholders must track state-level 24(c) special local need registrations and emerging resistance monitoring data to anticipate product phase-outs and replacement windows.
Market Dynamics
EPA re-registration timelines under FIFRA are compressing product lifecycles and forcing rapid reformulation toward bio-based active ingredients before patent cliffs hit synthetic chemistry portfolios.
Growth Catalysts
- USDA Conservation Programs:Cost-share incentives for reduced-risk pesticide selection redirect procurement through cooperative extension networks toward biopesticide alternatives.
- Seed-Treatment Chemistry:Upfront protection embedded in corn and soybean seeds displaces early-season foliar sprays while reducing total field passes per growing season.
- California Specialty Crop Expansion:Integrated pest management program adoption among avocado and citrus growers drives demand for selective lepidopteran control agents.
Market Restraints
- Active Ingredient Import Concentration:Pyrethroid and neonicotinoid technical-grade supply concentrates in Chinese and Indian manufacturing clusters, exposing formulators to tariff volatility.
- EPA FIFRA Re-Registration Friction:Extended data call-ins for ecological toxicity studies delay label amendments and restrict use pattern expansions.
- Biological Substitute Performance Gap:Bacillus thuringiensis and entomopathogenic fungal products exhibit shorter field persistence than synthetic alternatives in high-rainfall growing regions.
Strategic Opportunities
- Florida Vector Control Programs:State-funded mosquito abatement districts seek novel adulticide rotations to manage pyrethroid resistance in Aedes aegypti populations.
- Drone Application Infrastructure:Aerial spray service providers invest in ultra-low-volume formulation partnerships to access canopy penetration in soybean and cotton systems.
- Canada PMRA Harmonization:Parallel regulatory review pathways enable simultaneous US-Canada product launches that compress commercialization timelines.
Industry Challenges
- Entomologist Capacity Deficit:Agricultural extension services across the US Midwest operate with fewer than half the field specialist positions staffed two decades ago.
- Resistance Monitoring Data Fragmentation:State-level insecticide resistance surveillance networks lack standardized protocols, complicating product rotation recommendations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insecticide Market |
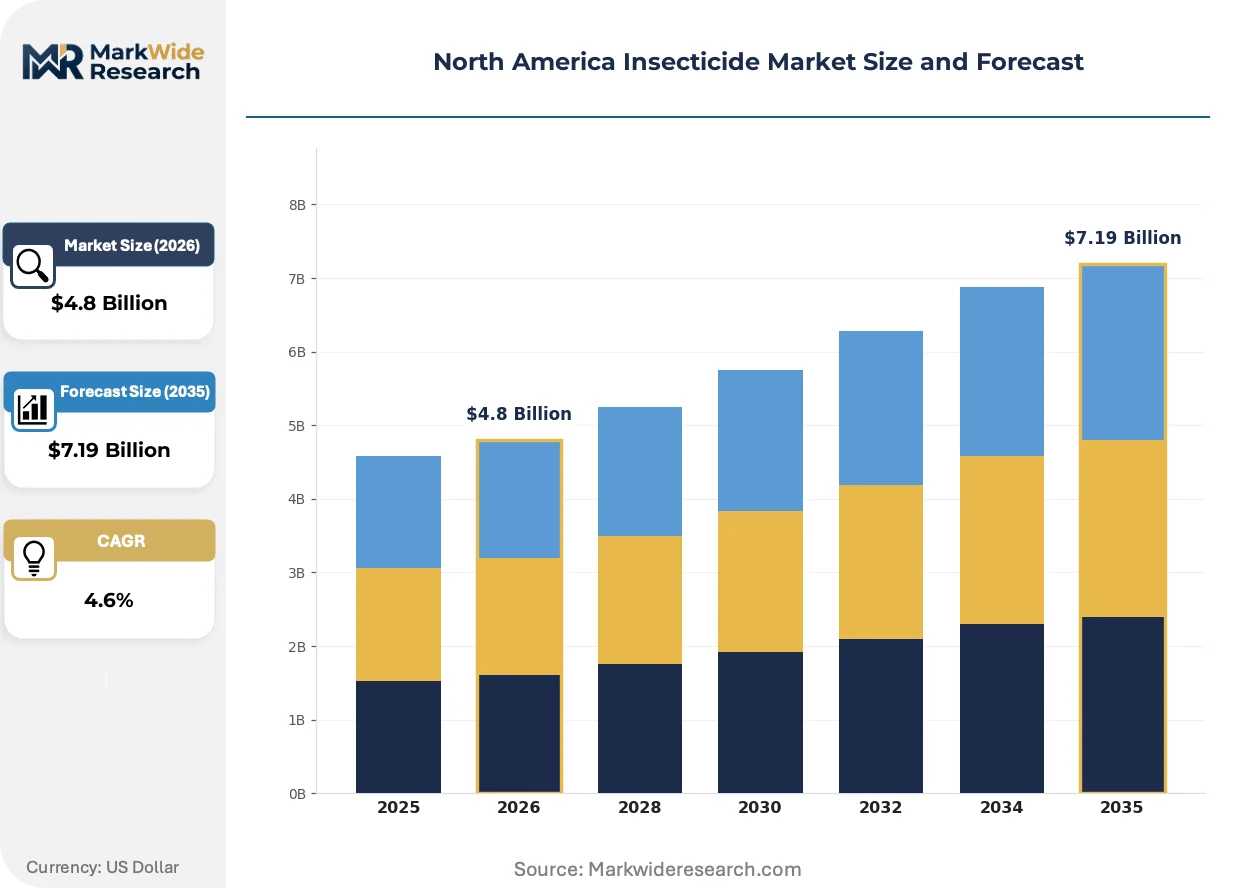
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
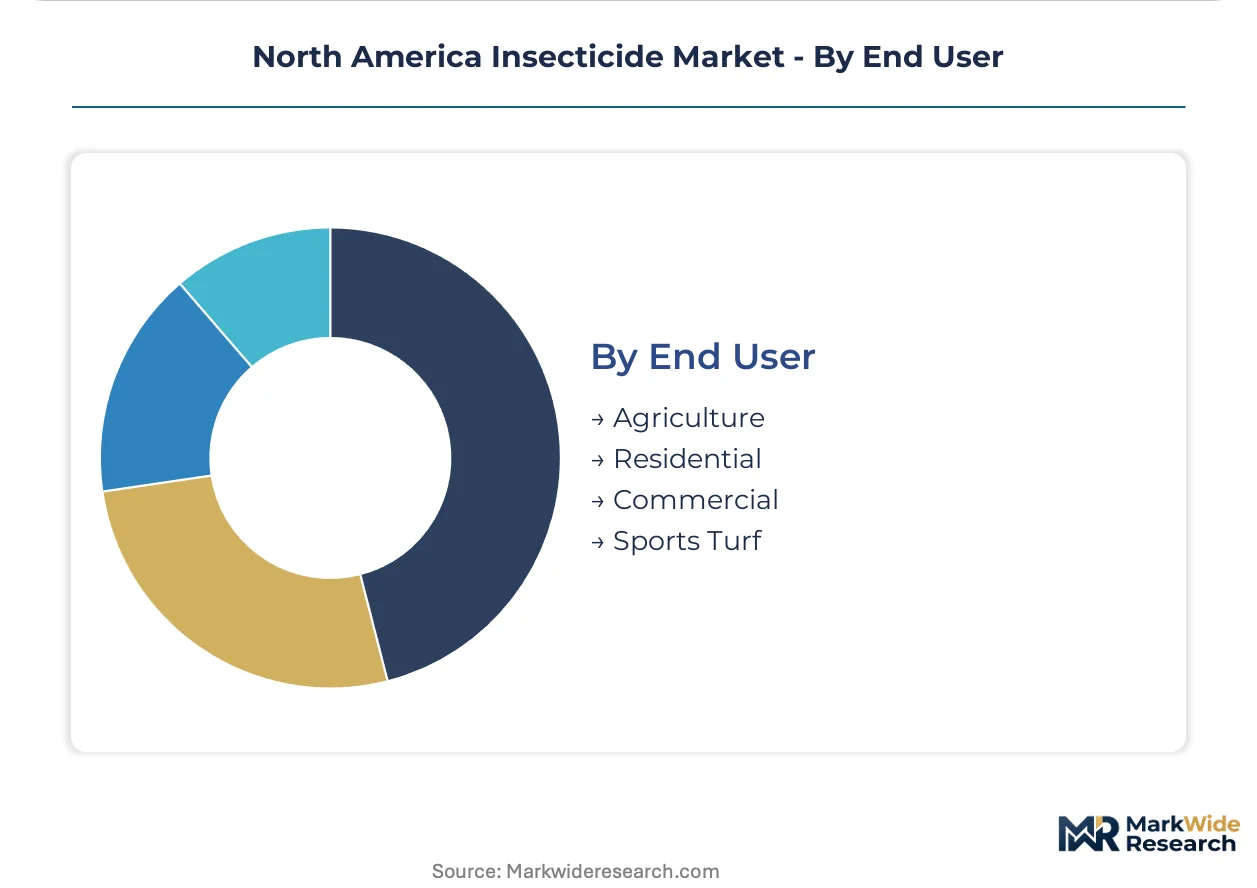
| Segmentation | Product Type: Herbicides, Fungicides, Insecticides, Pesticides Formulation: Liquid, Granular, Concentrate, Ready-to-Use Application Method: Foliar Spray, Soil Treatment, Seed Treatment, Trunk Injection End User: Agriculture, Residential, Commercial, Sports Turf |
| Companies Covered | Bayer AG, Corteva Agriscience, FMC Corporation, Syngenta Group, BASF SE, Nufarm Ltd, UPL Limited, American Vanguard Corporation, ADAMA Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insecticide Market Trends and Innovations
Digital pest monitoring hardware and RNA interference chemistry are converging to reshape how growers time applications and select modes of action against evolving pest populations.
RNA interference-based insecticides targeting specific lepidopteran gene sequences is supplanting broad-spectrum neurotoxic chemistries in specialty vegetable systems. California lettuce and brassica growers pilot these precision biocontrol tools through subscription-based advisory services. The technology compresses resistance development timelines while commanding premium positioning against conventional diamide rotations.
Health Canada's PMRA accelerated review pathways for biopesticide submissions compress regulatory lag versus conventional active ingredient registrations. The streamlined process attracts mid-scale fermentation-based manufacturers seeking North American market entry. Corn Belt distributors now stock Canadian-registered biological products ahead of EPA label approvals.
Outcome-based service contracts bundle scouting, application timing, and efficacy guarantees displace per-gallon product transactions among mid-acreage Midwest soybean operations. Regional agronomy cooperatives absorb inventory risk while capturing margin through performance-linked pricing. Ontario and Manitoba grain producers exhibit similar contracting appetite as crop insurance products integrate pest damage riders.
North America Insecticide Market Segmentation
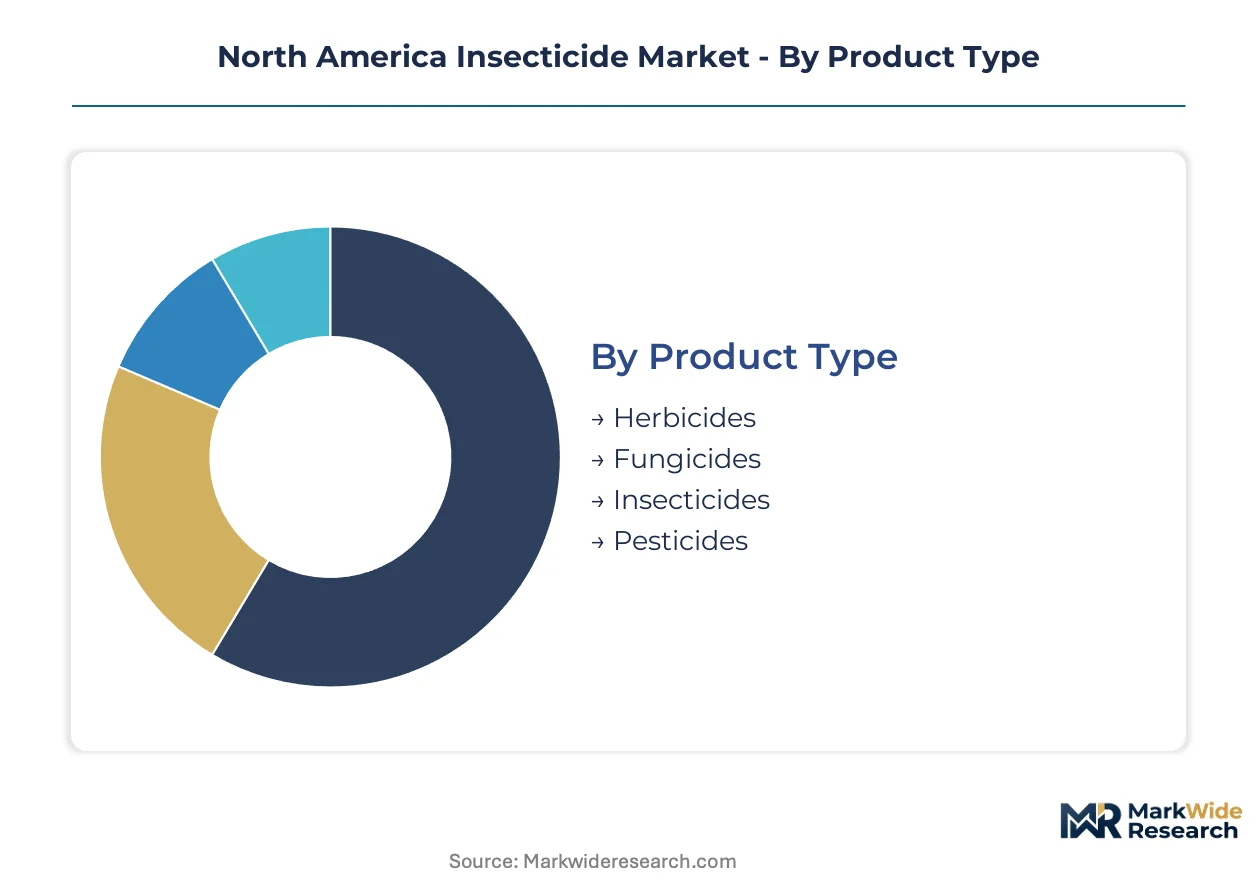
Insecticide segmentation in North America reflects divergent regulatory pathways across EPA FIFRA, Health Canada PMRA, and state-level pollinator protection mandates. Formulation chemistry and application method determine compliance burden, label restrictions, and speed to market across the US Midwest corn belt and California specialty crop zones.
Product Type:
EPA re-registration timelines under FIFRA compress lifecycles for synthetic neurotoxic chemistries while accelerating biopesticide review pathways, creating asymmetric development economics across active ingredient categories.
- Herbicides:Glyphosate, glufosinate, and dicamba formulations dominate row-crop acreage in Iowa, Illinois, and Indiana. Resistance management mandates from EPA and state departments of agriculture drive tank-mix requirements with insecticides and fungicides, bundling procurement decisions.
- Fungicides:Triazole and strobilurin chemistry protects high-value specialty crops in California's Central Valley and Florida's citrus belt. SDHI combinations command premium positioning as resistance to older modes of action accelerates in grape and almond systems.
- Insecticides:Pyrethroid, neonicotinoid, and diamide active ingredients anchor corn and soybean protection in the US Corn Belt. California Department of Pesticide Regulation restrictions on neonicotinoid use in pollinator-sensitive zones push growers toward biological alternatives and pheromone disruptors.
- Pesticides:Broad-spectrum synthetic and biological combinations serve vector control districts across Florida, Texas, and Arizona. EPA ecological toxicity data call-ins delay label expansions for new aquatic use patterns.
Established volume favors herbicides; emerging adoption favors insecticide biological alternatives.
Formulation:
Application infrastructure constraints and drift mitigation requirements shape formulation demand across aerial, ground, and precision equipment fleets.
- Liquid:Emulsifiable concentrates and suspension concentrates enable tank-mix flexibility for corn and soybean foliar programs. Compatibility with aerial application nozzles and drone spray systems sustains demand across the US Plains states.
- Granular:Soil-applied formulations target root-feeding pests in turf management and ornamental segments. Granular demand concentrates in golf course maintenance across Florida, Arizona, and southern California where soil-dwelling white grub pressure is pronounced.
- Concentrate:High-load active ingredient formulations reduce freight costs and packaging waste for commercial applicator operations. Professional pest control services in Texas and Florida metropolitan corridors favor concentrate economics for mosquito and termite programs.
- Ready-to-Use:Pre-diluted products serve residential consumers and small-scale landscapers without mixing equipment. Retail channels in Canadian provinces stock ready-to-use formats ahead of growing season peaks to capture homeowner demand.
Commercial applicators drive concentrate volume; residential channels expand ready-to-use fastest.
Application Method:
Seed treatment infrastructure investments by major seed companies are displacing early-season spray volume while reducing total field passes.
- Foliar Spray:Aerial and ground-based canopy applications remain the dominant delivery mode for mid- and late-season pest pressure in cotton, soybean, and vegetable systems. Drift mitigation requirements from EPA and state regulatory agencies tighten nozzle specifications and buffer zone mandates.
- Soil Treatment:Pre-plant and at-plant incorporated chemistry controls soil-dwelling pests in potato, sugar beet, and vegetable root crops. California's Central Valley and Idaho's Magic Valley exhibit concentrated demand for soil-applied neonicotinoid alternatives.
- Seed Treatment:Proprietary fungicide-insecticide combinations embedded in corn and soybean seeds displace early-season foliar sprays. Bayer, Corteva, and Syngenta seed platforms capture value through bundled trait-chemistry packages.
- Trunk Injection:Arboricultural applications target borers and vascular pests in urban tree management. Municipal forestry departments in Chicago, Toronto, and Vancouver deploy injection systems for emerald ash borer and spotted lanternfly containment.
Seed treatment captures upfront protection economics; trunk injection climbs fastest in urban pest containment.
End User:
USDA conservation program incentives and crop insurance integration reshape procurement authority across producer types.
- Agriculture:Row-crop and specialty crop producers account for the majority of insecticide volume, with corn, soybean, cotton, and high-value vegetable systems driving mode-of-action rotation requirements. Cooperative extension networks in the US Midwest struggle with entomologist staffing deficits, shifting advisory reliance to digital platforms and private agronomy services.
- Residential:Homeowner demand concentrates in lawn and garden pest control, with ready-to-use formulations dominating retail channels. State-level restrictions on neonicotinoid consumer products in New York and Connecticut redirect demand toward pyrethroid and biological alternatives.
- Commercial:Professional pest control operators service structural, ornamental, and industrial accounts across metropolitan corridors. Integrated pest management certification requirements from the National Pest Management Association influence product selection and application protocols.
- Sports Turf:Golf course superintendents and athletic field managers demand selective chemistry for grub and surface-feeding insect control. Resistance monitoring programs led by the Golf Course Superintendents Association of America guide rotation strategies against annual bluegrass weevil and white grub complexes.
Agriculture anchors volume concentration; sports turf exhibits steepest precision-input expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA FIFRA re-registration timelines and Health Canada PMRA parallel reviews anchor regulatory coordination across the continent. USDA conservation incentives and state-level pollinator protection plans reshape procurement geography.
United States
Corn Belt soybean and corn acreage drives pyrethroid and neonicotinoid consumption across Iowa, Illinois, and Indiana. California Department of Pesticide Regulation restricts neonicotinoid use in pollinator-sensitive zones, pushing avocado and citrus growers toward biological alternatives. Specialty crop expansion in Florida's citrus belt concentrates demand for selective lepidopteran control agents.
Canada
PMRA accelerated review pathways for biopesticide submissions compress regulatory lag versus conventional active ingredient registrations. Ontario and Manitoba grain producers adopt outcome-based service contracts bundling scouting and application timing. Corn Belt distributors stock Canadian-registered biological products ahead of EPA label approvals.
Mexico
Export-oriented vegetable production in Sinaloa and Baja California demands residue-compliant insecticide formulations for US market access. Mexican agricultural health authority SENASICA coordinates with EPA on maximum residue limit harmonization. Northern border states concentrate formulator investments serving cross-border specialty crop supply chains.
North America Insecticide Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America insecticide market. Consolidated multinational agrochemical conglomerates with integrated seed platforms dominate proprietary chemistry development and bundled trait-chemistry packages. Mid-scale fermentation-based manufacturers and generic technical-grade suppliers occupy distinct competitive tiers. Portfolio diversification into biopesticide alternatives and strategic partnerships for drone application infrastructure represent dominant competitive moves.
Among multinational conglomerates, Bayer AG and Corteva Agriscience exemplify the integrated seed-treatment archetype through digital farming platforms and proprietary combinations that reduce foliar spray dependence. FMC Corporation occupies a position within the specialized chemistry tier, representing concentrated portfolio strategies targeting resistance management. These three anchors illustrate how competitive positioning stratifies across bundled platform economics versus focused technical specialization.
| Leading Market Players |
|---|
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Syngenta Group |
| BASF SE |
| Nufarm Ltd |
| UPL Limited |
| American Vanguard Corporation |
| ADAMA Agricultural Solutions |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Chinese and Indian technical-grade manufacturing clusters shapes both supply concentration and price floors for North American formulators. Pyrethroid and neonicotinoid active ingredient production runs at high utilization rates, compressing marginal cost curves while tariff exposure on cross-Pacific lanes introduces volatility into landed cost structures.
Pricing Analysis
Trans-Pacific freight spreads between Shanghai and Long Beach versus Mumbai and Houston create divergent landed cost positions for US formulators sourcing from Chinese versus Indian technical-grade suppliers. Three-tier pricing structure across premium, standard, and economy levels separates proprietary seed-treatment bundles from generic foliar formulations and commodity spot purchases. Pricing pressure stems from EPA FIFRA re-registration data call-ins accelerating patent cliff timelines for synthetic neurotoxic chemistries. Mid-acreage Midwest soybean operations exhibit highest price sensitivity through outcome-based service contract adoption, while California specialty crop growers show lowest sensitivity due to residue compliance premiums.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on Asia-North America trade lanes amplify inbound logistics costs for technical-grade active ingredient shipments. Pyrethroid and neonicotinoid manufacturing concentrates in China and India, with fermentation-based biopesticide production expanding in Canada and Mexico. Raw material dependencies include chlorinated intermediates, pyrethrum extract, and Bacillus thuringiensis fermentation feedstocks. Single-source vulnerability from concentrated Chinese technical-grade supply exposes formulators to tariff volatility and export license disruptions. Distribution runs through regional agronomy cooperatives and commercial applicator networks serving the Corn Belt and California Central Valley.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA interference chemistry and EPA biopesticide fast-track pathways are accelerating formulation disruption, compressing development timelines from discovery to commercial launch.
For Market Incumbents: Secure proprietary seed-treatment chemistry positions through trait-chemistry bundling before diamide patent cliffs erode lepidopteran control margins. Deepen backward integration into Bacillus thuringiensis fermentation capacity to offset Chinese technical-grade concentration risk. Anchor digital advisory platforms to compensate for collapsing agricultural extension entomologist staffing across the US Midwest. For New Entrants and Emerging Players: Advisory service gaps in integrated pest management expertise across Iowa, Illinois, and Indiana cooperative extension networks present white-space entry points. Target Florida vector control districts seeking pyrethroid resistance rotation alternatives for Aedes aegypti management. Pursue subscription-based scouting and application timing contracts bundling drone deployment infrastructure with biological product recommendations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-based biopesticide manufacturers with PMRA-registered products awaiting EPA label harmonization. Five-to-ten year viability rests on regulatory tailwinds for reduced-risk chemistry and conservation program procurement redirection. Monitor EPA 24(c) special local need registration velocity as inflection indicator for state-level product substitution windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Bacillus thuringiensis production insulates formulators from Chinese technical-grade tariff exposure. |
| RNA Interference Platform Development | Precision biocontrol targeting lepidopteran gene sequences commands premium positioning against diamide rotations. |
| Drone Application Infrastructure Partnership | Ultra-low-volume formulation access penetrates soybean and cotton canopy for aerial service providers. |
| PMRA-EPA Harmonization Fast-Track | Simultaneous US-Canada product launches compress commercialization timelines for biopesticide entrants. |
| Outcome-Based Service Contract Expansion | Performance-linked pricing absorbs inventory risk while capturing margin through guaranteed efficacy terms. |
Research Methodology
Desk research of EPA FIFRA registration databases, Health Canada PMRA submission records, and USDA conservation program procurement disclosures preceded structured interviews with agricultural extension entomologists, seed company R&D directors, commercial applicator operations managers, and cooperative extension procurement leads. Primary fieldwork across Iowa, Illinois, California, and Florida validated secondary data on resistance monitoring networks and state-level pollinator protection plan implementation. Bottom-up acreage-by-crop modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Variance decomposition across product type, formulation chemistry, application method, and end-user segments structured the analytical framework over the projection horizon. CAGRs derived from segmented growth rate blending weighted by base-year contribution. Industry-specific forecast inputs incorporated EPA re-registration timeline probability distributions and PMRA accelerated review pathway completion rates for biopesticide submissions.
Underlying assumptions cover EPA FIFRA re-registration schedule adherence, PMRA-EPA label harmonization continuity, and tariff regime stability on Asia-North America technical-grade trade lanes, with deviation risk concentrated in extended ecological toxicity data call-ins and state-level 24(c) registration denials. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Global Acaricides Market
Crop Protection
Europe Herbicide Market
Crop Protection
Pest Control Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
India Herbicide Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
North America Acaricides Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Europe Nematicide Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Global Insect Growth Regulators Market