
 Germany Crop Protection Chemicals Market | 2026-2036
Germany Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Crop Protection Chemicals Market Foresight
Biological active ingredient platforms is fragmenting traditional synthetic chemistry dominance in German crop protection. Bayer AG leverages its integrated R&D pipeline across conventional and bio-based molecules to sustain portfolio breadth. BASF SE anchors its position through specialty fungicide chemistry for viticulture and potato systems. Syngenta Group competes via digital farming interfaces bundled with precision application services.
Germany crop protection chemicals comprise formulated substances—synthetic or biological active ingredients combined with adjuvants, carriers, and stabilizers—designed to prevent, eliminate, or control pests, diseases, and weeds in agricultural production. These formulations typically specify active ingredient concentrations, application rates per hectare, and pre-harvest intervals to ensure efficacy while meeting residue limits. Herbicides command the largest product type share, reflecting Germany's extensive cereal and maize cultivation base where weed pressure drives repeat applications. Fungicides represent the fastest-expanding category, propelled by tighter grape and fruit quality standards in southwestern growing regions. Liquid formulations dominate volume due to compatibility with precision spraying equipment, though granules retain share in conservation tillage systems.
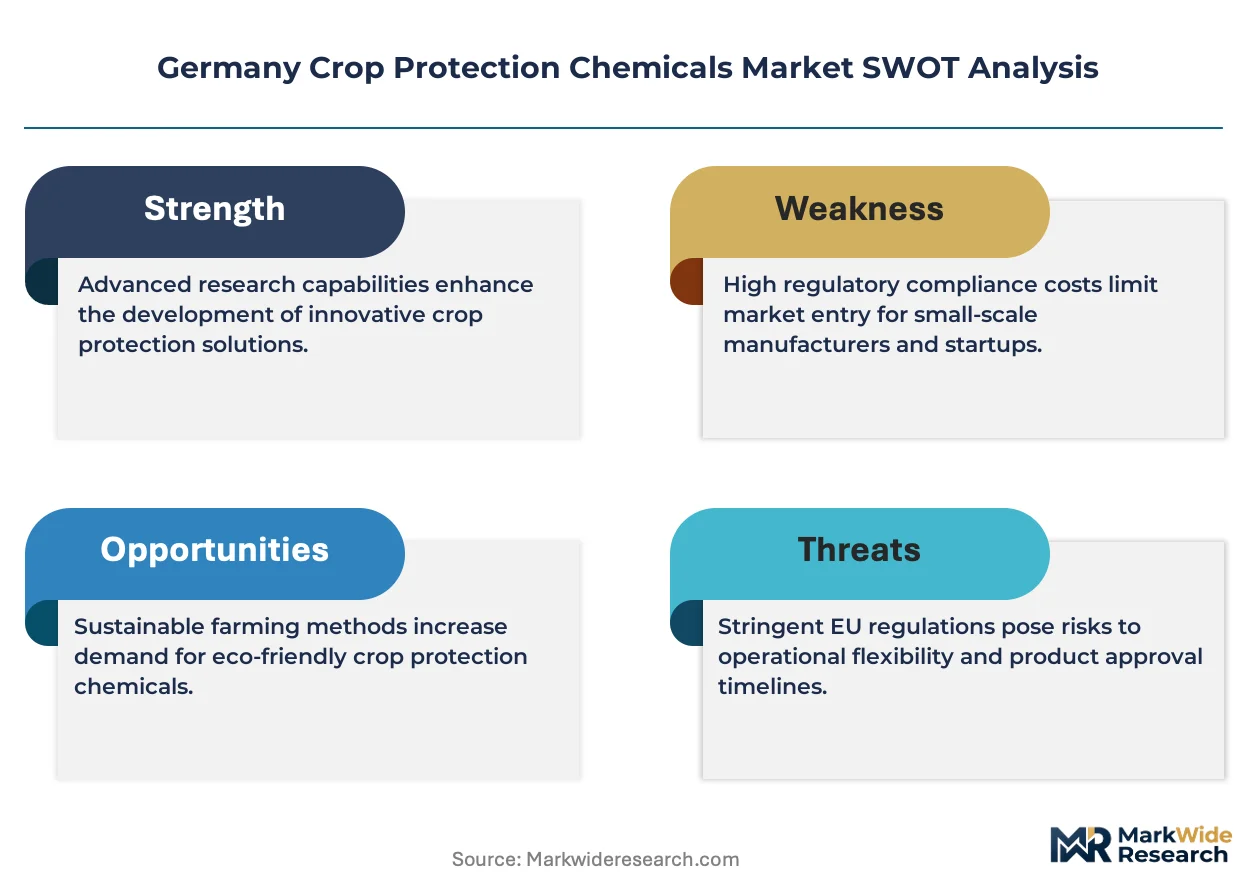
The Federal Office of Consumer Protection and Food Safety enforces maximum residue limits under EU harmonized standards, while the German Federal Agency for Agriculture and Food oversees plant protection product authorization timelines. REACH compliance and the EU Sustainable Use Directive shape active ingredient eligibility, forcing manufacturers to retire legacy chemistries and register replacements. Stakeholders must monitor regulatory divergence between German federal implementation and EU-level Farm to Fork milestones to anticipate product portfolio obsolescence cycles.
Market Dynamics
The EU Farm to Fork Strategy's pesticide reduction mandate is forcing German manufacturers into simultaneous reformulation and biological R&D investments, compressing product development timelines while fragmenting traditional synthetic chemistry portfolios.
Growth Catalysts
- Precision Application Technology:Drone-mounted variable-rate spraying systems are expanding adoption among Baden-Württemberg viticulture cooperatives. These platforms reduce active ingredient volumes per hectare while maintaining efficacy thresholds.
- EU Green Deal Implementation:National funding streams for integrated pest management transition are accelerating grower willingness to trial biological alternatives. Federal cost-sharing programs cover up to fifty percent of certification expenses for sustainable conversion.
- Rhineland-Palatinate Specialty Crop Expansion:High-value asparagus and table grape cultivation is concentrating demand for residue-minimal protection solutions. Export-oriented growers in this region face stricter MRL compliance for Swiss and Nordic retail chains.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers control over seventy percent of technical-grade synthetic molecule supply. German formulators face freight volatility and customs processing delays for critical herbicide intermediates.
- REACH Re-registration Burden:The European Chemicals Agency's data requirements for legacy chemistries impose multi-year compliance timelines. Smaller German distributors lack capital reserves to sustain parallel registration tracks for replacement molecules.
- Biological Efficacy Limitations:Microbial fungicides demonstrate inconsistent performance under Central European humidity fluctuations. Grape growers in Mosel report yield protection gaps during extended wet seasons that synthetic chemistry previously covered.
Strategic Opportunities
- Digital Farming Convergence:Integration of satellite imagery with application equipment is creating subscription-based service models. Bayer and BASF field teams bundle sensing hardware with crop protection prescriptions.
- Conservation Tillage Expansion:Granular herbicide formulations retain relevance in Brandenburg and Mecklenburg-Vorpommern no-till systems. These eastern states lag western biological adoption curves, extending synthetic product lifecycles.
- Carbon Credit Monetization:The EU Carbon Removal Certification Framework enables growers to quantify emission reductions from reduced-input programs. Formulators can co-develop verification protocols that lock in multi-year supply relationships.
Industry Challenges
- Biological Formulation Expertise Gap:German chemical engineering programs emphasize synthetic process optimization. Few graduates possess microbial stabilization and shelf-life extension competencies required for next-generation product development.
- Federal Agency Authorization Backlogs:The German Federal Agency for Agriculture and Food faces staffing constraints that extend novel active ingredient review timelines. Applicants report eighteen-to-twenty-four-month delays beyond EU harmonized baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Crop Protection Chemicals Market |
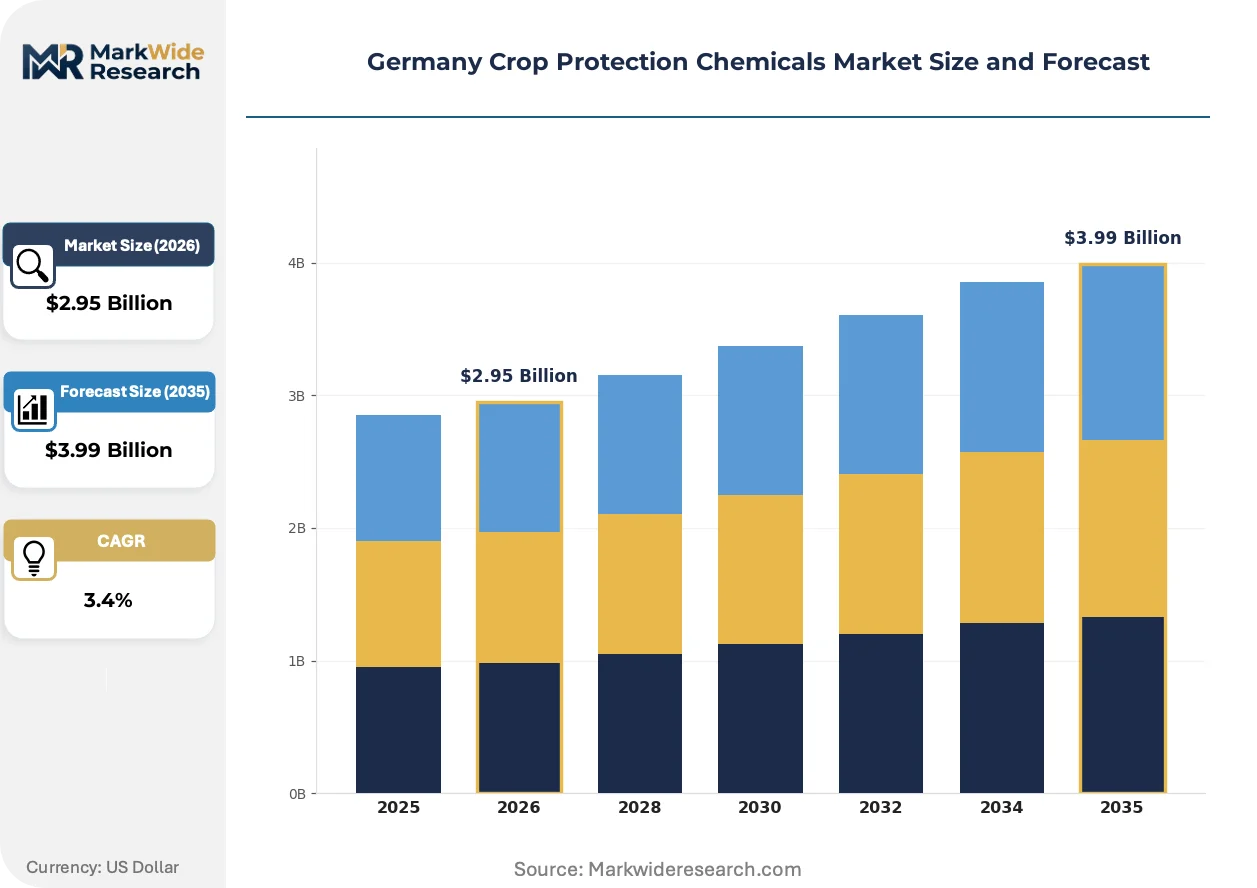
| Market Size in 2026 | $2.95 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides, Bactericides Formulation: Liquid, Granules, Wettable Powder, Emulsifiable Concentrates, Dust Application: Cereal Crops, Vegetable Cultivation, Fruit Orchards, Viticulture, Specialty Crops End User: Large-Scale Farms, Smallholder Farmers, Agricultural Cooperatives, Contract Growers |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, ADAMA Agricultural Solutions Ltd, Corteva Agriscience, FMC Corporation, UPL, Nufarm, Wynca Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Crop Protection Chemicals Market Shifts & Advancements
Sensor-enabled application systems and regulatory-driven biological substitution are restructuring how German growers procure and deploy crop protection. These shifts compress decision cycles while elevating data integration requirements across the value chain.
Variable-rate nozzle control paired with real-time canopy sensing is digitizing spray operations across Bavarian cereal operations. Large-scale farming cooperatives in Lower Saxony deploy these systems on over forty percent of self-propelled sprayers. The technology is digitizing input cost structures by enabling per-square-meter prescription maps that replace flat-rate field applications.
REACH authorization sunset clauses are forcing systematic phase-outs of neonicotinoid and phenoxy herbicide chemistries. German formulators must submit replacement dossiers three years ahead of commercial deadlines to secure uninterrupted supply. Viticulture and orchard segments face the steepest transition curves given their reliance on narrow-spectrum fungicides now under regulatory review.
Direct procurement between grower cooperatives and biological suppliers is shortening traditional distribution tiers. Rhineland-Palatinate vegetable producer associations now contract fermentation firms for customized Bacillus-based solutions. This disintermediation concentrates volume with specialized manufacturers while reducing margin capture by conventional agrochemical distributors in southwestern growing regions.
Germany Crop Protection Chemicals Market Segmentation
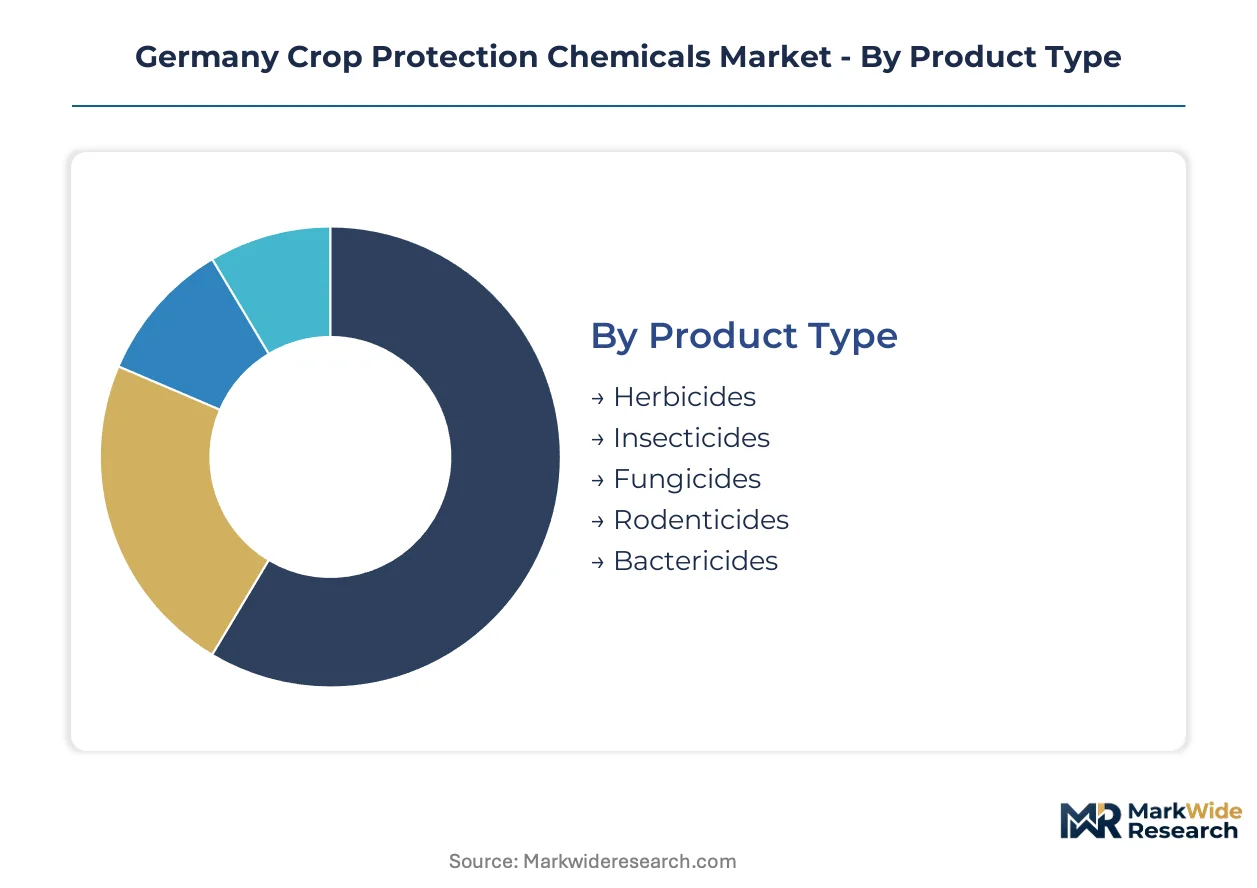
German crop protection demand fragments across crop systems, farm scales, and regulatory exposure zones. Segmentation reveals where biological substitution pressures concentrate versus where synthetic chemistry retains structural advantages.
Product Type:
Mature synthetic chemistries dominate volume while biological alternatives emerge fastest in residue-sensitive segments.
- Herbicides:Formulations containing glyphosate, sulfonylureas, and phenoxy compounds target weed suppression in cereal and maize systems across northern Germany. Demand concentrates in Lower Saxony and Brandenburg cereal belts where broadleaf pressure drives repeat applications; growers face mounting resistance management costs.
- Fungicides:Triazole, strobilurin, and biological-based formulations protect grapevine, potato, and vegetable crops from downy mildew and Botrytis. Southwestern viticulture regions in Baden-Württemberg and Rhineland-Palatinate drive premium demand as ECHA REACH reviews narrow approved chemistries.
- Insecticides:Neonicotinoid alternatives and pyrethroid formulations target aphid and lepidopteran pressure in rapeseed and vegetable systems.
- Rodenticides:Anticoagulant and non-anticoagulant baits protect stored grain and orchard operations.
- Bactericides:Copper-based and biological formulations address fire blight in pome fruit orchards.
Herbicides retain volume leadership; fungicides hold the steepest expansion curve.
Formulation:
Application technology compatibility determines formulation selection across German farm scales.
- Liquid:Suspension concentrates and soluble liquids enable precision nozzle control on GPS-guided sprayers. Bavarian cereal cooperatives deploy these formulations on over forty percent of self-propelled equipment; variable-rate compatibility reduces per-hectare active ingredient volumes.
- Granules:Controlled-release formulations suit conservation tillage systems in Brandenburg and Mecklenburg-Vorpommern no-till operations. Eastern German states lag western biological adoption, extending synthetic product lifecycles where soil incorporation replaces foliar spraying.
- Wettable Powder:Dry flowable formulations requiring tank-mix agitation serve specialty crop segments.
- Emulsifiable Concentrates:Oil-based carriers penetrate waxy cuticles in orchard and vine applications.
- Dust:Limited to seed treatment and greenhouse applications with restricted drift exposure.
Liquid formulations dominate value capture; granules sustain relevance in conservation tillage corridors.
Application:
Residue standard intensity varies sharply across German crop systems.
- Cereal Crops:Wheat, barley, and maize cultivation across northern plains generates repeat herbicide and fungicide demand. Lower Saxony and Schleswig-Holstein field crop zones prioritize cost efficiency over residue minimization; commodity pricing pressure constrains premium product uptake.
- Viticulture:Grape production in Mosel, Rheinhessen, and Baden faces the strictest EU MRL enforcement. Export-oriented cooperatives trial microbial fungicides under Farm to Fork transition funding; wet season efficacy gaps force synthetic backup retention.
- Vegetable Cultivation:Asparagus, onion, and brassica operations in Rhineland-Palatinate and Bavaria drive residue-minimal protection demand.
- Fruit Orchards:Apple and pear systems in Lake Constance region require fire blight and scab management protocols.
- Specialty Crops:Hop cultivation in Hallertau and table grape production concentrate high-value protection spending.
Cereal crops anchor volume demand; viticulture commands premium pricing power.
End User:
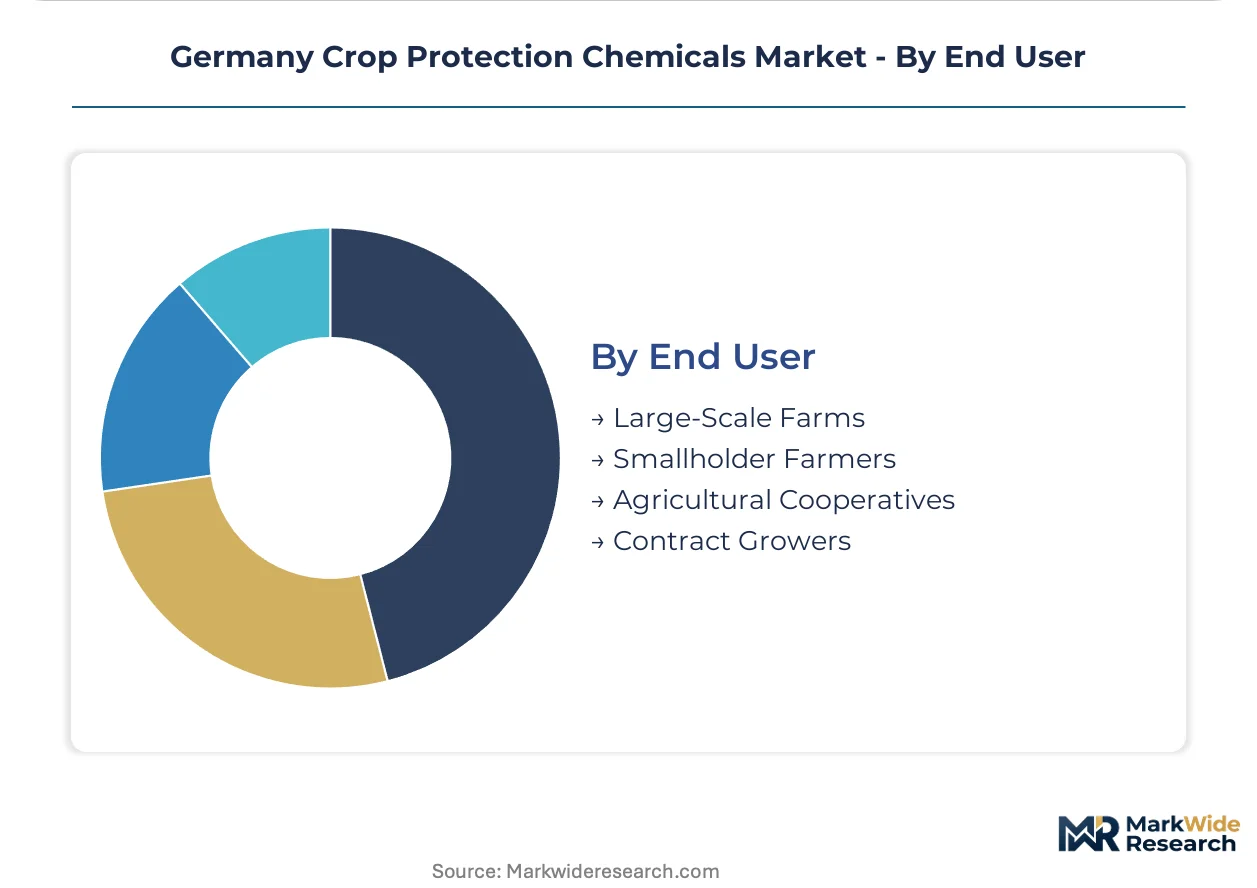
Farm scale determines procurement channel and biological adoption velocity.
- Large-Scale Farms:Operations exceeding 500 hectares in eastern Germany deploy precision application infrastructure and direct manufacturer relationships. Brandenburg arable enterprises negotiate volume contracts with integrated precision service bundles.
- Agricultural Cooperatives:Baden-Württemberg and Bavarian purchasing groups consolidate biological procurement through direct fermentation firm contracts. Southwestern vegetable associations bypass conventional distributors for customized Bacillus-based formulations.
- Smallholder Farmers:Sub-50 hectare operations rely on retail agronomist advice and standard formulation portfolios.
- Contract Growers:Processor-tied operations face buyer-mandated residue protocols in potato and sugar beet systems.
Large-scale farms drive precision technology adoption; cooperatives accelerate biological disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's crop protection chemicals sector operates as a net importer of technical-grade active ingredients, with formulators dependent on Chinese and Indian intermediate supply chains while exporting finished specialty formulations to neighboring EU markets and premium viticulture regions.
Baden-Württemberg
Precision viticulture and high-value vegetable cultivation drive biological fungicide demand in this southwestern state. The German Federal Agency for Agriculture and Food processes plant protection authorizations with eighteen-to-twenty-four-month delays beyond EU baselines. Stuttgart-based cooperatives deploy drone-mounted variable-rate spraying systems across steep-slope vineyards.
Rhineland-Palatinate
Asparagus and table grape export operations concentrate demand for residue-minimal protection solutions. Federal cost-sharing programs cover fifty percent of integrated pest management certification expenses. Mosel valley growers trial microbial alternatives while retaining synthetic backups for wet-season efficacy gaps.
Bavaria
Large-scale cereal cooperatives anchor herbicide volume consumption across the northern plains. REACH compliance requirements force systematic phase-outs of phenoxy chemistries three years ahead of commercial deadlines. Lower Bavaria field crop zones prioritize cost efficiency over residue minimization amid commodity pricing pressure.
Lower Saxony
Extensive wheat and maize belts generate repeat applications of broadleaf weed suppressants. The EU Sustainable Use Directive shapes active ingredient eligibility for northern German arable systems. Cuxhaven and Oldenburg farming enterprises negotiate volume contracts with precision service bundles.
Brandenburg
Conservation tillage expansion sustains granular herbicide relevance in eastern no-till operations. Eastern states lag western biological adoption curves, extending synthetic product lifecycles. Large-scale arable enterprises exceeding 500 hectares deploy direct manufacturer relationships for input procurement.
Germany Crop Protection Chemicals Market Competitive Landscape
On the supply side, the industry is consolidating around integrated R&D pipelines that span conventional and bio-based molecule portfolios. Three strategic archetypes dominate: diversified chemical conglomerates with fermentation capabilities, precision agriculture platform providers bundling hardware with crop protection prescriptions, and specialized biological manufacturers contracting directly with grower cooperatives. Dominant competitive moves include backward integration into microbial strain development and technology licensing agreements for satellite-guided application systems.
Among Germany-based chemical conglomerates, BASF SE and Bayer AG exemplify the integrated R&D archetype, anchoring positions through specialty fungicide chemistry and combined conventional-bio-based pipelines respectively. Syngenta Group occupies a position within the precision agriculture tier, representing the digital farming convergence strategy that bundles sensing hardware with application prescriptions. These three entities collectively illustrate how market participants are restructuring around regulatory-driven biological substitution and sensor-enabled application technologies.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| ADAMA Agricultural Solutions Ltd |
| Corteva Agriscience |
| FMC Corporation |
| UPL |
| Nufarm |
| Wynca Group |
| Others |
Supply & Pricing Matrix
Chinese manufacturers controlling over seventy percent of technical-grade synthetic molecule supply concentrate pricing power with formulators in Rhineland-Palatinate and Baden-Württemberg. Margin pools sit downstream with distributors bundling precision application services and biological certification programs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across German cereal cooperatives. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade under EU Farm to Fork compliance tiers and volume scale commitments. Cost compression in economy-tier herbicides is intensifying because Chinese freight volatility feeds raw material instability. Smallholder farmers in sub-50 hectare operations demonstrate highest price sensitivity; large-scale eastern German enterprises with direct manufacturer relationships exhibit lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Chinese and Indian technical-grade producers supplying phenoxy and neonicotinoid intermediates to German formulators. Raw material dependencies center on glyphosate technicals, strobilurin precursors, and microbial fermentation substrates. Single-source vulnerability runs through Chinese customs processing chokepoints for critical herbicide actives. Distribution runs through regional agronomist networks and cooperative purchasing groups consolidating biological procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German crop protection is approaching a platform-economics inflection where precision application hardware and biological formulation subscriptions merge into interoperable farm management ecosystems. Bayer's FieldView and Syngenta's digital interfaces exemplify this interoperability shift locking growers into multi-year service relationships.
For Market Incumbents: Entrench biological R&D pipelines through backward integration into microbial strain development, countering regulatory phase-outs of neonicotinoid chemistries under ECHA REACH sunset clauses. Expand captive fermentation capacity in southwestern states to secure Bacillus-based formulation supply against disintermediation threats from direct cooperative contracting. For New Entrants and Emerging Players: Mid-scale vegetable producer associations in Rhineland-Palatinate represent the most penetrable entry point for customized biological solutions bypassing conventional distribution tiers. Conservation tillage corridors in Brandenburg and Mecklenburg-Vorpommern extend synthetic product lifecycles where granular formulations retain relevance. Target cooperative technical managers with residue-minimal certification support bundled with application training. For Investors and Strategic Acquirers: Capital is best deployed toward precision agriculture platform providers with satellite-guided prescription capabilities and established hardware-installation relationships across Bavarian cereal belts. Long-term viability over the next decade hinges on digital farming convergence velocity and biological efficacy consistency under Central European humidity stress. Monitor ECHA authorization timelines for novel microbial actives as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Strain Development | BASF and Bayer secure proprietary Bacillus libraries against cooperative disintermediation in southwestern viticulture regions. |
| Precision Application Hardware Bundling | Syngenta locks Bavarian cereal cooperatives into subscription-based sensing services with variable-rate nozzle control. |
| Long-term Supply Agreement with Chinese Technical Producers | German formulators hedge freight volatility and customs delays for critical herbicide intermediates. |
| Joint Venture with Fermentation Specialists | Rhineland-Palatinate vegetable associations secure customized biological formulations bypassing conventional distributors. |
| Green Certification Program under EU Farm to Fork | Export-oriented growers in Mosel valley qualify for Swiss and Nordic retail chain residue protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, and Cefic sector reports. Interviews with plant protection product managers at German formulators, procurement leads at Baden-Württemberg viticulture cooperatives, distribution channel partners, and technical R&D directors at biological fermentation firms ground quantitative estimates. Bottom-up volume triangulation across crop-specific application rates and top-down value reconciliation against federal authorization databases validate segmentation outputs.
Forecast inputs include regulatory authorization timelines under EU Farm to Fork milestones, precision technology adoption curves across eastern versus western German states, and biological substitution elasticity in residue-sensitive segments. Segmentation dimensions span product type, formulation technology, crop system intensity, and farm scale tier. CAGRs derive from trend extrapolation of active ingredient volumes adjusted for REACH phase-out schedules and federal cost-sharing program uptake rates.
Practitioners should monitor ECHA sunset clause accelerations, Chinese export license volatility, and wet-season biological efficacy gaps for early signals of forecast revision. Quarterly review of Federal Agency for Agriculture and Food authorization backlogs and cooperative procurement disintermediation velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Australia Crop Protection Chemicals (Pesticides) Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Pest Control Products Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Global Algaecides Market
Crop Protection
China Fungicide Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Larvicides Market
Crop Protection
Metamifop Market
Crop Protection
Europe Herbicide Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Fruit and Vegetable Crop Protection Market