
 Brazil Crop Protection Chemical Market | 2026-2036
Brazil Crop Protection Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Crop Protection Chemical Market Outlook
The agrochemical retail channel in Brazil's interior is fragmenting as regional cooperatives and digital platforms erode traditional distributor dominance. Bayer AG sustains formidable brand equity through its integrated seed-and-chemistry bundling across the Cerrado. Syngenta Group competes via deep technical service networks embedded with soybean and corn growers. Ourofino Agrociência anchors its position through localized manufacturing and regulatory agility tailored to Brazilian tropical conditions.
Crop protection chemicals encompass synthetic and biological formulations designed to control weeds, insects, fungi, and rodents through active ingredients such as glyphosate, atrazine, and azoxystrobin applied at specified dosage rates per hectare. Their primary purpose is to safeguard yield potential in commercial agriculture by mitigating biotic stressors that reduce productivity. Herbicides command the largest product type position due to the dominance of no-till soybean systems where pre- and post-emergence weed control is essential. Liquid formulations lead the formulation landscape because of ease of tank-mixing and aerial application compatibility across Brazil's expansive farms. Agricultural crops absorb the vast majority of application volume, with horticulture representing a faster-growing but smaller margin pool driven by export-oriented fruit and vegetable operations.
ANVISA governs human health-based pesticide registration and residue tolerance settings, while MAPA oversees agricultural efficacy and environmental fate assessments for product approval. These dual regulatory tracks create compliance complexity that favors companies with dedicated Brazilian regulatory affairs capacity. The Central Bank of Brazil's rural credit policies and the Central Bank's environmental risk guidelines for agricultural lending are beginning to tie financing terms to sustainable input practices. Stakeholders must monitor how evolving federal bioinput legislation and state-level pesticide buffer zone disputes reshape product portfolios and geographic market access.
Market Dynamics
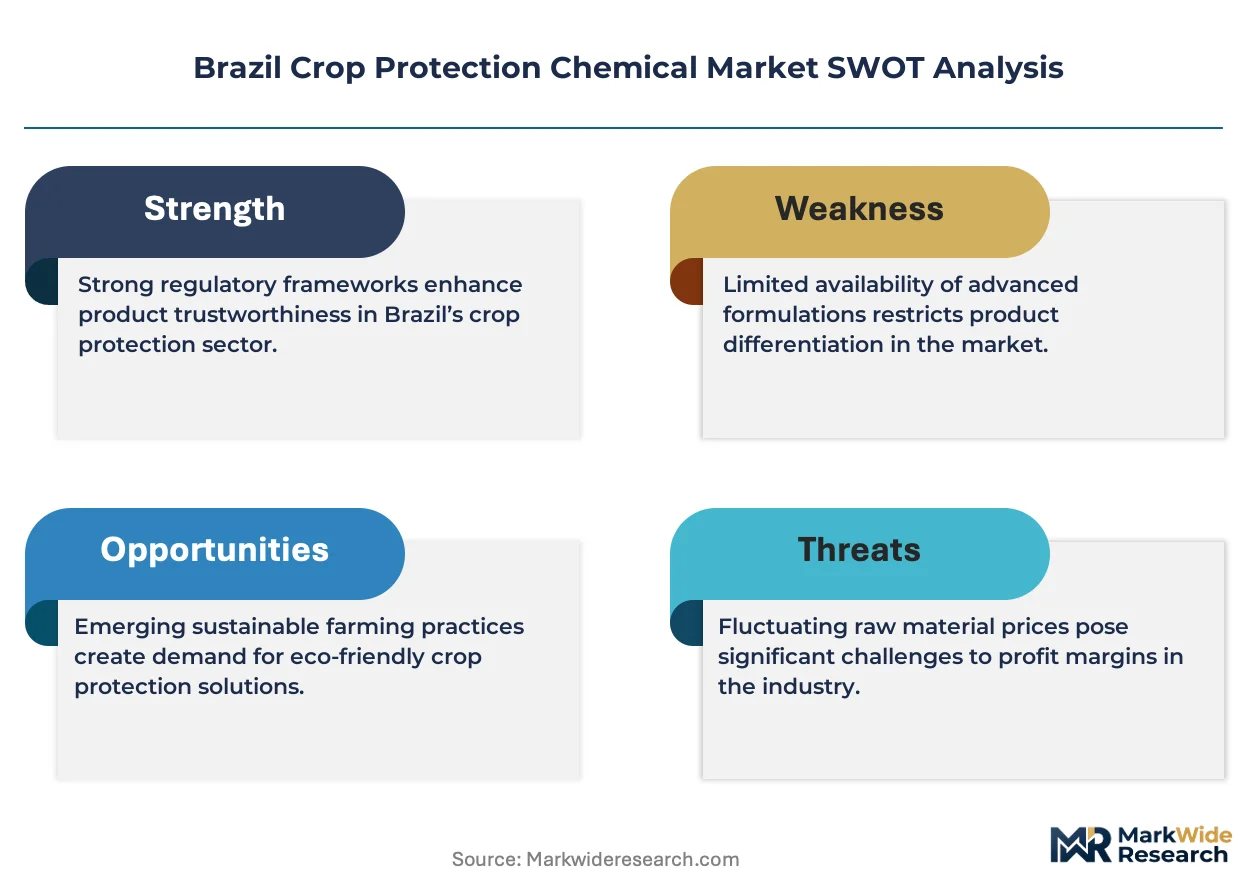
ANVISA's tightening residue limits and MAPA's bioinput certification are forcing rapid formulation pivots toward low-toxicity chemistries and biological alternatives across Brazil's agrochemical value chain.
Growth Catalysts
- Herbicide-resistant weed pressure:Glyphosate-resistant populations in Mato Grosso and Paraná are expanding pre- and post-emergence herbicide rotations, creating sustained demand for novel mode-of-action products.
- MAPA bioinput framework:The certification pathway for biological crop protection inputs is accelerating farmer adoption of microbial and botanical formulations as residue-compliant alternatives.
- Central Bank rural credit policies:Tied financing terms linking credit access to sustainable input practices are redirecting procurement toward lower-toxicity chemistries.
Market Restraints
- Active ingredient import concentration:Brazil relies heavily on Chinese and Indian suppliers for technical-grade glyphosate and atrazine, exposing formulators to currency volatility and geopolitical supply disruptions.
- Dual-track regulatory friction:ANVISA's human health assessments and MAPA's agricultural efficacy reviews operate on non-synchronized timelines, extending product registration cycles and freezing portfolio decisions.
- Biological substitution threat:Accelerating farmer trials of Bacillus-based biofungicides and entomopathogenic nematodes are capturing share in specialty crop segments with premium residue requirements.
Strategic Opportunities
- MATOPIBA frontier expansion:The consolidated agricultural region spanning Maranhão, Tocantins, Piauí, and Bahia offers underpenetrated acreage for intensive agrochemical adoption as soy-corn rotations displace pasture.
- Digital platform distribution:E-procurement channels and farm management software integrations are disintermediating traditional distributor networks and capturing margin from price-transparent transactions.
- Drone application convergence:Precision agriculture hardware paired with ultra-low-volume liquid formulations is enabling variable-rate spraying that reduces chemical load per hectare while preserving efficacy.
Industry Challenges
- Regulatory affairs talent scarcity:The specialized skill set bridging toxicology, agronomy, and Brazilian administrative law commands premium compensation and constrains expansion timelines for mid-size formulators.
- Legacy tank-mix incompatibility:Biological inoculants and synthetic chemistries often exhibit antagonism in co-application, requiring reformulation investment and farmer re-education on compatibility protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Crop Protection Chemical Market |
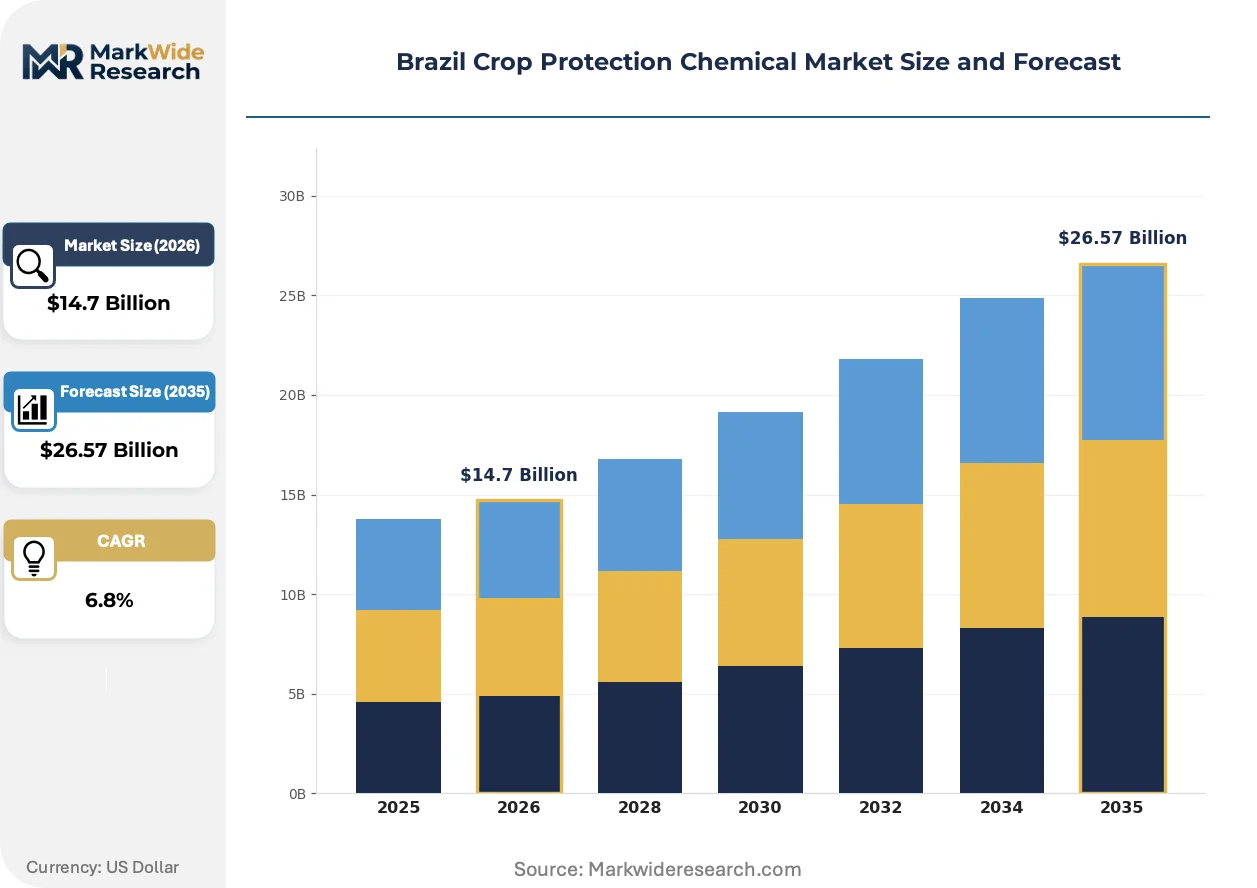
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Rodenticides Application: Agricultural Crops, Horticulture, Turf & Ornamentals, Others Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Retail, E-commerce, Distributors, Direct Sales |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, Syngenta Group, FMC Corporation, UPL Limited, Ourofino Agrociência, ADAMA Agricultural Solutions, Nortox S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Crop Protection Chemical Market Strategic Shifts
Formulation science and application technology are converging to reduce chemical load intensity while preserving yield protection, reshaping product development priorities across the Brazilian agrochemical sector.
RNA interference-based biopesticides targeting specific lepidopteran pests are virtualizing the traditional broad-spectrum insecticide model by enabling precision pest suppression without collateral beneficial insect mortality. Large-scale soybean operators in the Cerrado are piloting these products through integrated pest management contracts. This technology is virtualizing commodity insecticide margins into premium precision-biotech service revenues.
ANVISA's updated pesticide residue limits for soybeans and corn exports are compressing maximum residue levels to align with EU and Chinese import standards, forcing reformulation of established products and accelerating biological adjuvant adoption. Formulators must now demonstrate residue degradation kinetics under tropical field conditions. Export-oriented growers in Mato Grosso are responding by segregating input protocols between domestic and export-destined grain streams.
Cooperative procurement consortia are consolidating demand from mid-size farms into volume-aggregated tenders that bypass traditional distributor markups and extract direct-manufacturer pricing. These buying groups now represent substantial volume in Paraná and Rio Grande do Sul. The disintermediation is most visible among second-generation family farms with sufficient scale to justify dedicated agronomic staff but insufficient volume for individual direct negotiation.
Brazil Crop Protection Chemical Market Segmentation
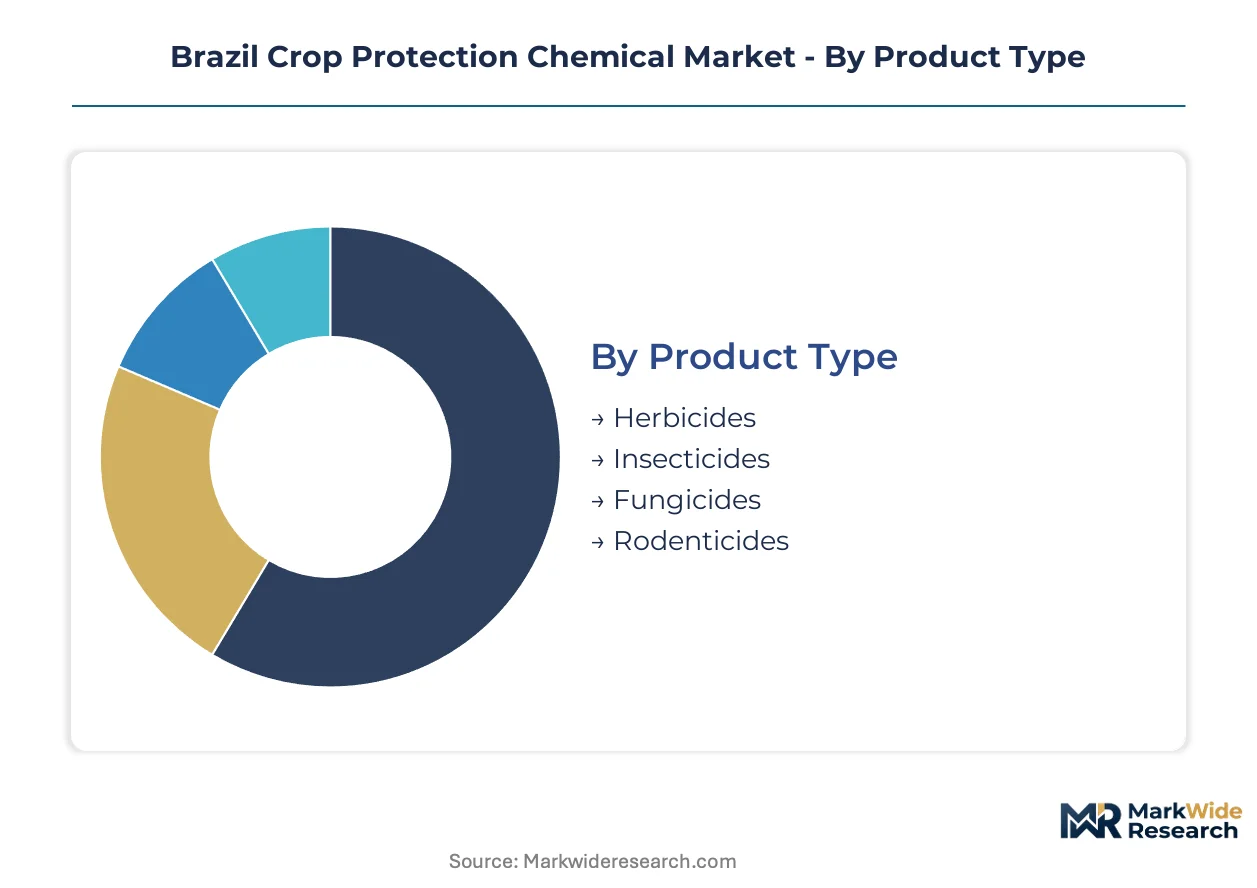
Segmentation reveals how Brazil's crop protection chemical demand stratifies across farming systems, formulation technologies, and procurement channels. Each dimension exposes distinct margin structures and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Cost tier differentiation separates commodity-scale chemistry from specialty biocontrol inputs with residue compliance premiums.
- Herbicides:Glyphosate, atrazine, and 2,4-D formulations dominate volume through pre- and post-emergence weed control in no-till soybean systems. Mato Grosso and Paraná growers drive rotation demand amid spreading resistant weed populations.
- Fungicides:Azoxystrobin, triazoles, and SDHI chemistry protect yield against Asian soybean rust and corn foliar diseases. Cerrado farmers apply prophylactically given humid tropical conditions that accelerate pathogen pressure.
- Insecticides:Neonicotinoid and pyrethroid chemistry targets lepidopteran and sucking pest complexes in cotton and corn.
- Rodenticides:Anticoagulant and acute toxicant formulations protect stored grain and sugarcane ratoon establishment.
Herbicides command the established base. The steepest expansion runs through fungicides.
Application:
Customer type segmentation isolates export-oriented commercial agriculture from domestic-market horticulture with divergent residue tolerance requirements.
- Agricultural Crops:Soybean, corn, cotton, and sugarcane absorb the overwhelming volume through mechanized aerial and ground rig application. MATOPIBA frontier expansion in Maranhão and Tocantins extends addressable acreage as soy-corn rotations displace degraded pasture.
- Horticulture:Fruit and vegetable operations in São Paulo's Vale do Ribeira and Pernambuco's São Francisco Valley deploy biological and low-toxicity synthetics for EU and US export compliance.
- Turf & Ornamentals:Golf courses and urban landscaping in São Paulo and Brasília sustain steady demand for selective herbicides and systemic fungicides.
- Others:Forestry plantations and pasture renovation represent peripheral volume with distinct seasonal patterns.
Agricultural crops anchor volume concentration. Horticulture gains share fastest on export premium capture.
Formulation:
Application technology compatibility determines formulation selection across Brazil's scale-differentiated farm structures.
- Liquid:Suspension concentrates and soluble liquids enable rapid tank-mixing and ultra-low-volume aerial application across Cerrado mega-farms. Compatibility with drone spraying systems accelerates adoption among precision agriculture adopters.
- Emulsifiable Concentrate:Oil-based carriers improve rainfastness and cuticle penetration for systemic fungicide and insecticide delivery in high-rainfall tropical zones.
- Granular:Controlled-release matrices suit soil-applied insecticide and nematicide delivery in root-feeding pest management.
- Powder:Wettable powders persist in smallholder segments and seed treatment applications where water quality constraints favor dry handling.
Liquid formulations dominate operational scale. Emulsifiable concentrates climb fastest on rainfastness premium.
Distribution Channel:
Supply concentration shapes margin capture between manufacturer, intermediary, and farm gate across Brazil's fragmented interior.
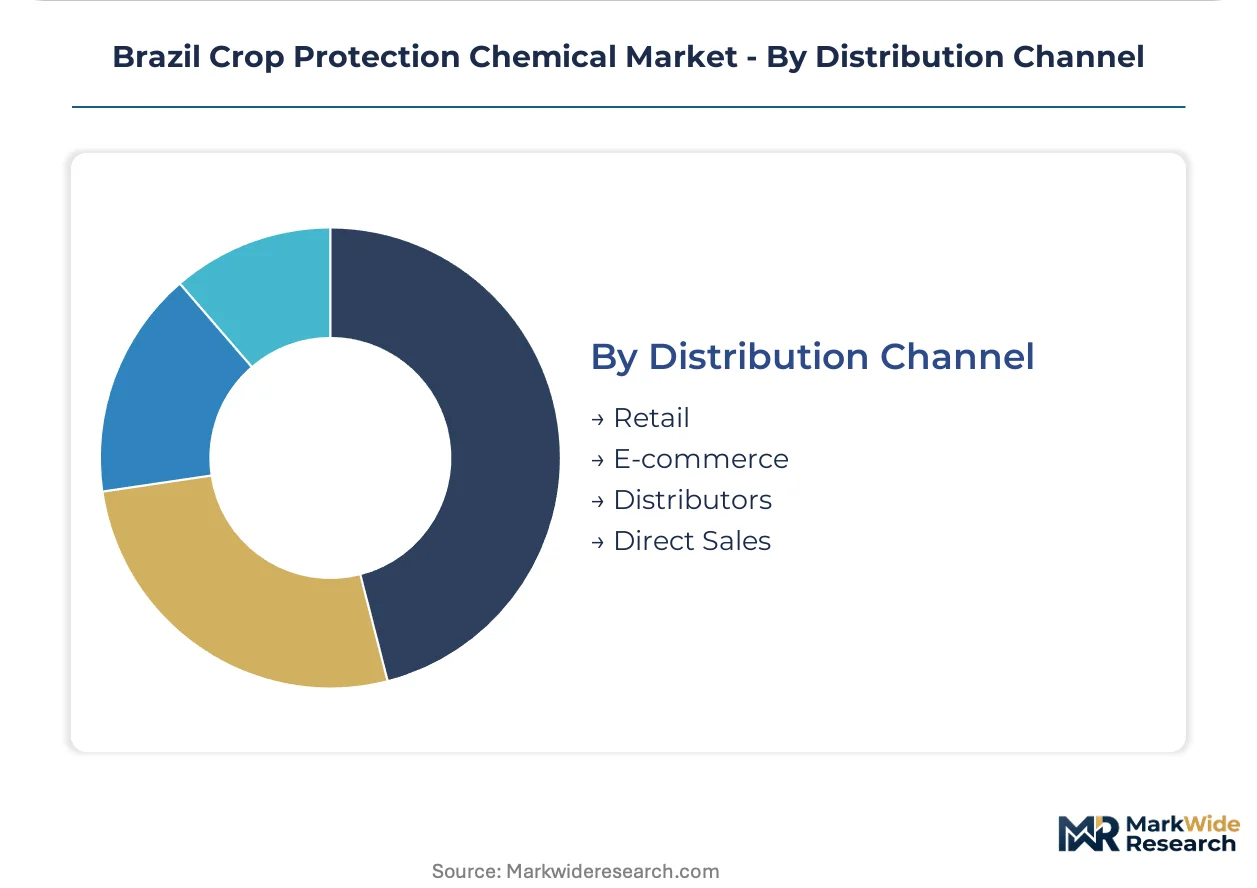
- Distributors:Regional agrochemical wholesalers in Rondonópolis, Cascavel, and Rio Verde maintain inventory depth and credit extension for large-scale cooperatives. Technical service bundling preserves relevance despite price transparency pressure.
- Retail:Rural supply stores and cooperative outlets serve mid-size farms with immediate availability and local agronomic relationships.
- E-commerce:Digital platforms and farm management software integrations disintermediate traditional networks through price-transparent tenders and direct-manufacturer contracting.
- Direct Sales:Formulators contract directly with mega-farm operators and cooperative consortia for volume-aggregated procurement bypassing distributor markups.
Distributors retain the established infrastructure. E-commerce captures the steepest expansion trajectory on disintermediation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ferrovia Norte-Sul rail corridor and the multimodal terminals at Rondonópolis and Lucas do Rio Verde underwrite Mato Grosso's agrochemical distribution dominance, connecting interior farm supply depots to Atlantic export terminals at Santos and Paranaguá.
Mato Grosso
Glyphosate-resistant weed pressure and expanding soy-corn rotations drive intensive herbicide and fungicide demand across the Cerrado belt. ANVISA's residue limit updates for export-bound soybeans force growers to segregate input protocols between domestic and international grain streams. Rondonópolis anchors the state's agrochemical logistics, with distributor warehouses and aerial application services clustering around the rail-terminal complex.
Paraná
No-till soybean systems and second-corn rotations sustain pre- and post-emergence herbicide rotations amid spreading resistant weed populations. MAPA's bioinput certification framework accelerates farmer trials of microbial formulations in the state's cooperative-dominated procurement channels. Cascavel and Maringá concentrate technical service networks and regional distributor headquarters serving the western agricultural corridor.
Rio Grande do Sul
Small-to-mid-scale family farms and cooperative procurement consortia drive demand for price-transparent input sourcing through digital platforms. The Central Bank of Brazil's rural credit policies tie financing terms to sustainable input practices, redirecting procurement toward lower-toxicity chemistries. Passo Fundo and Erechim anchor the state's distributor infrastructure and cooperative buying group concentration.
São Paulo
Export-oriented horticulture in Vale do Ribeira and citrus belts deploys biological and low-toxicity synthetics for EU and US residue compliance. ANVISA's tightened maximum residue levels for fruit exports compress formulation choices toward premium biocontrol alternatives. Piracicaba and Jaboticabal host research stations and technical service hubs bridging university agronomy programs to commercial farming operations.
Bahia
MATOPIBA frontier expansion displaces degraded pasture with soy-corn rotations, opening underpenetrated acreage for intensive agrochemical adoption. State-level pesticide buffer zone disputes around the São Francisco River basin reshape product portfolio access and application timing restrictions. Barreiras and Luís Eduardo Magalhães concentrate input distribution infrastructure serving the western agricultural frontier.
Brazil Crop Protection Chemical Market Competitive Environment
Platform integrators command the system tier through bundled seed-and-chemistry offerings and embedded technical service networks; component specialists sit upstream with localized manufacturing and regulatory agility tailored to Brazilian tropical conditions. The market structure consolidates around multinational research-based innovators with Brazilian formulation capacity, mid-size regional formulators with regulatory specialization, and emerging biological input developers capturing residue-compliant premium segments. Two dominant competitive moves define current positioning: direct-to-farm digital platform expansion disintermediating traditional distributor markups, and precision agriculture hardware partnerships enabling variable-rate application service bundling.
Among research-based innovators with Brazilian manufacturing presence, Bayer AG, Syngenta Group, and BASF SE occupy positions defined by integrated portfolio breadth and technical service infrastructure. Bayer AG exemplifies the platform integrator archetype through seed-and-chemistry bundling across the Cerrado. Syngenta Group represents the technical service-embedded model with agronomic networks anchored in soybean and corn growing regions. BASF SE sits within the diversified chemistry tier with formulation capacity serving both commodity and specialty crop segments. Regional specialists including Ourofino Agrociência anchor competitive positioning through regulatory agility and localized production responsiveness.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| Syngenta Group |
| FMC Corporation |
| UPL Limited |
| Ourofino Agrociência |
| ADAMA Agricultural Solutions |
| Nortox S.A. |
| Others |
Value Chain & Pricing Dynamics
The Ferrovia Norte-Sul rail corridor's freight cost dynamics concentrate supply power among Mato Grosso-based distributors while forcing price differentiation between domestic and export-bound input streams. Regional cooperatives exploit this logistics bottleneck to extract volume discounts that compress margins for mid-size formulators serving fragmented interior markets.
Pricing Analysis
Volume-discount tiering separates mega-farm direct contracts from cooperative procurement consortia and retail channel markups. Three-tier pricing structure across premium residue-compliant, standard synthetic, and economy generic formulations reflects ANVISA certification grade and volume scale. Cost compression in economy herbicides is intensifying because Chinese technical-grade import volatility feeds through to spot pricing. Cooperative buyers exhibit highest price sensitivity; export-oriented MATOPIBA operators accept premium biocontrol pricing for EU market access.
Supply Chain Analysis
Contract-manufacturing concentration rests with Chinese and Indian technical-grade producers supplying glyphosate and atrazine active ingredients to Brazilian formulators. Raw material dependencies center on imported technical-grade herbicides, formulated adjuvants, and biological inoculant substrates. Single-source vulnerability runs through concentrated Chinese glyphosate production exposed to currency fluctuation and geopolitical friction. Distribution runs through regional agrochemical wholesalers in Rondonópolis and Cascavel extending credit to cooperative buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story. ANVISA's dual-track registration process creates switching costs that entrench incumbents with dedicated Brazilian regulatory affairs capacity.
For Market Incumbents: Insulate formulation portfolios by accelerating backward integration into biological active ingredient production, capturing MAPA bioinput certification premiums before generic competitors replicate compliance pathways. Deepen channel control through embedded technical service networks that bind soybean growers to proprietary tank-mix protocols resistant to price-transparent digital platforms.
For New Entrants and Emerging Players: Build out white-space positions in drone-compatible ultra-low-volume formulations and MATOPIBA frontier logistics infrastructure where distributor networks remain underdeveloped. The most penetrable segment sits with mid-size family farms in Rio Grande do Sul cooperative consortia seeking residue-compliant alternatives to multinational bundled offerings. A direct-to-farm digital procurement angle with transparent pricing and agronomic content bypasses traditional distributor markups.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational parents divesting non-core tropical formulation assets lacking scale synergy with home-market portfolios. Long-term viability favors specialists with captive biological manufacturing and ANVISA regulatory expertise over commodity synthetic traders. Watch accelerating farmer adoption rates of Bacillus-based biofungicides as inflection signal for biological substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Manufacturing | Captures MAPA certification premiums and reduces Chinese API dependency for residue-compliant portfolios. |
| Drone Application Formulation Development | Aligns product specifications with precision agriculture hardware adoption across Cerrado mega-farms. |
| Direct-to-Farm Digital Platform Launch | Disintermediates traditional distributor networks and captures margin from cooperative procurement consortia. |
| Regulatory Affairs Capacity Expansion | Accelerates ANVISA registration timelines and defends against mid-size formulators with constrained compliance resources. |
| MATOPIBA Logistics Infrastructure Partnership | Secures first-mover distribution positioning in frontier soy-corn rotation expansion zones. |
Study Parameters
The analysis maps herbicide, fungicide, insecticide, and biological input sub-sectors, each validated through agronomic directors at regional cooperatives, regulatory affairs leads at formulators, procurement officers at distributor networks, and technical service managers embedded with Cerrado growers. Primary interview findings triangulate against ANVISA registration databases, MAPA bioinput certification records, Central Bank rural credit policy documents, and customs import data for technical-grade active ingredients. Bottom-up acreage-by-crop application rate modeling reconciles with top-down value chain revenue aggregation.
Assumptions held ANVISA residue limit evolution and MAPA bioinput framework implementation as fixed regulatory baselines while varying farmer adoption curves for biological alternatives and drone application penetration rates. Segmentation dimensions span product type, formulation technology, distribution channel, and regional production cluster. CAGRs derive from compound growth trajectory analysis across the projection horizon, incorporating soybean rust pressure indices and glyphosate-resistant weed spread rates as crop protection demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese technical-grade producers to forward-integrate into Brazilian formulation would shift outcomes through price compression in commodity herbicides. Quarterly review of ANVISA registration approval velocity, Central Bank rural credit disbursement trends, and MATOPIBA acreage conversion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Dicamba Market
Crop Protection
Global Algaecides Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
Europe Herbicide Market
Crop Protection
Fosthiazate Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
North America Nematicides Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Larvicides Market
Crop Protection
US Insecticide Market
Crop Protection
Fumigation Service Market
Crop Protection
Captan Fungicide Market
Crop Protection
Herbicide Safeners Market
Crop Protection
United Kingdom Crop Protection Chemicals Market