
 Vietnam Fungicide Market | 2026-2036
Vietnam Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Fungicide Market Insights
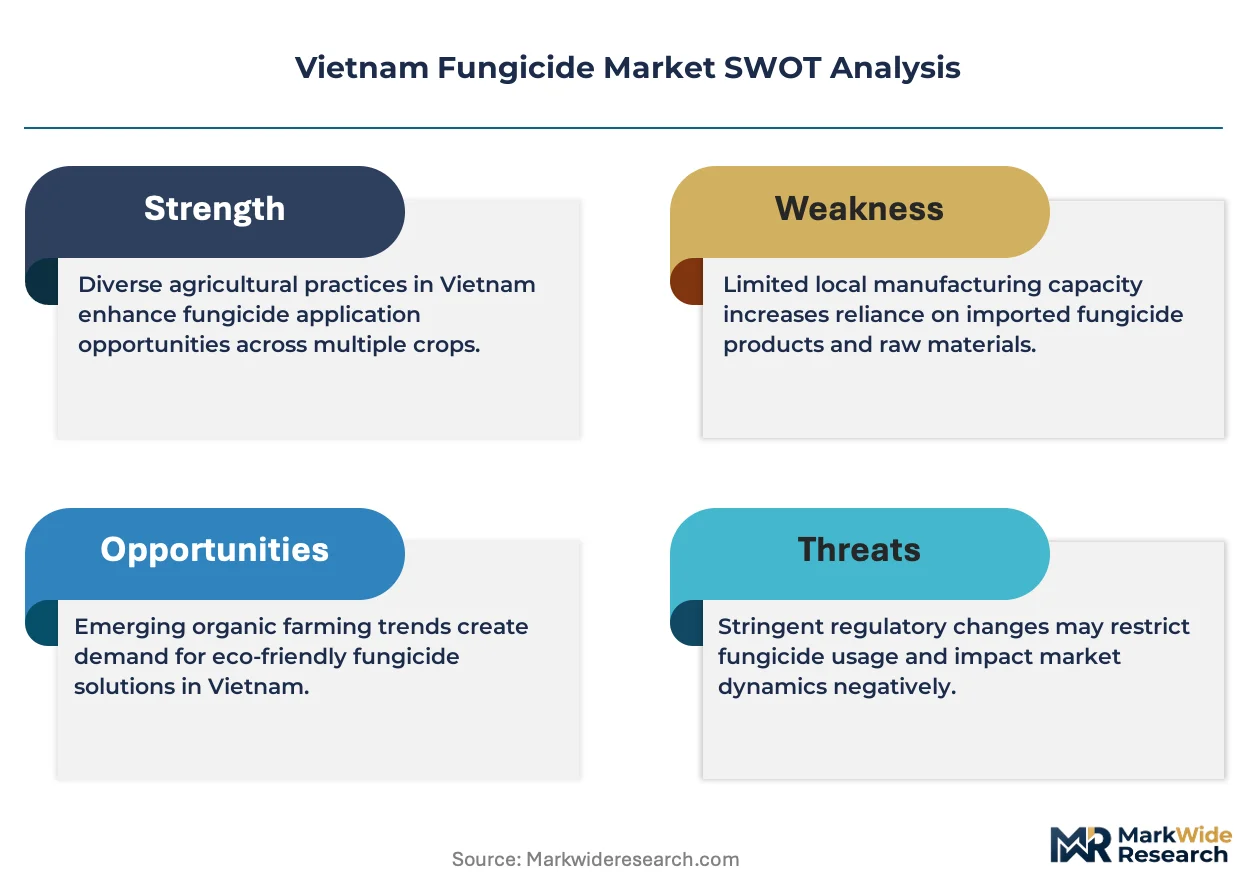
Subscription-based agronomy advisory bundled with fungicide procurement is rebalancing how Vietnamese distributors capture farmer loyalty. Bayer AG anchors its position through backward integration into active ingredient synthesis, ensuring supply continuity for azole and strobilurin chemistries. Syngenta Group extends its reach via dedicated rice crop protection programs across the Mekong Delta, while UPL Limited competes through price-accessible generic formulations tailored to smallholder budgets. ADAMA Agricultural Solutions Ltd. navigates regulatory complexity by pre-registering formulations aligned with Vietnam's revised MRL protocols.
A fungicide is a biocidal compound or biological organism that destroys or inhibits the growth of fungi or fungal spores, typically formulated with active ingredients such as triazoles, strobilurins, or dithiocarbamates at concentrations ranging from 5% to 50% by weight, and applied to protect crops from pathogenic infection and yield loss. Systemic fungicides penetrate plant tissues and redistribute through xylem vessels, making them dominant in rice blast management where curative action is essential after initial infection. Contact formulations retain larger margin pools in vegetable production around Da Lat and Lam Dong provinces, where frequent reapplication cycles create recurring revenue for distributors. Foliar spray remains the primary application method, though soil treatment adoption accelerates in high-value dragon fruit orchards seeking root rot prevention.
Vietnam's Ministry of Agriculture and Rural Development enforces pesticide registration through the Plant Protection Department, while the Vietnam Standards and Quality Institute certifies formulation consistency under national QCVN standards. These frameworks restrict market access for uncertified imports and elevate compliance costs for new entrants. Stakeholders must monitor evolving MRL harmonization pressures from export destination markets, particularly EU and Japanese import thresholds, which will determine which chemistries retain commercial viability in Vietnamese production systems.
Market Dynamics
Circular 24's tightened MRL enforcement is compressing distributor margins while accelerating consolidation toward certified formulation suppliers across Vietnam's rice and vegetable belts.
Growth Catalysts
- Sheath blight pressure in Mekong Delta rice:Climate humidity patterns intensify fungal pathogen cycles, forcing farmers toward recurring fungicide applications.
- Plant Protection Department registration protocols:Pre-registration alignment with revised MRL standards creates first-mover advantage for compliant suppliers.
- Greenhouse intensification near Hanoi:Protected vegetable cultivation in Red River Delta generates year-round demand for systemic and contact formulations.
Market Restraints
- Active ingredient import concentration:Azole and strobilurin chemistries depend on concentrated East Asian synthesis capacity, exposing formulators to supply continuity risk.
- Smallholder budget fragmentation:Price-sensitive rice farmers split purchases across multiple generic suppliers, eroding brand loyalty and distributor margin pools.
- EU-Japan MRL harmonization lag:Divergent import thresholds between Vietnam's trading partners force dual-formulation strategies that inflate compliance overhead.
Strategic Opportunities
- Central Highlands dragon fruit expansion:Soil treatment fungicide adoption in root rot prevention remains underpenetrated among high-value orchard operators.
- Subscription agronomy bundling:Advisory services combined with procurement contracts lock in recurring revenue from Mekong Delta cooperatives.
- Biological fungicide convergence:Integration of microbial antagonists with synthetic chemistries opens premium positioning for export-oriented vegetable producers.
Industry Challenges
- Field agronomist scarcity:Technical advisory capacity fails to match cooperative expansion, stretching distributor support networks.
- Registration timeline compression:Plant Protection Department review queues delay new formulation commercialization by multiple growing seasons.
- Legacy inventory obsolescence:MRL-downgraded chemistries strand distributor stocks, forcing write-downs during regulatory transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Fungicide Market |
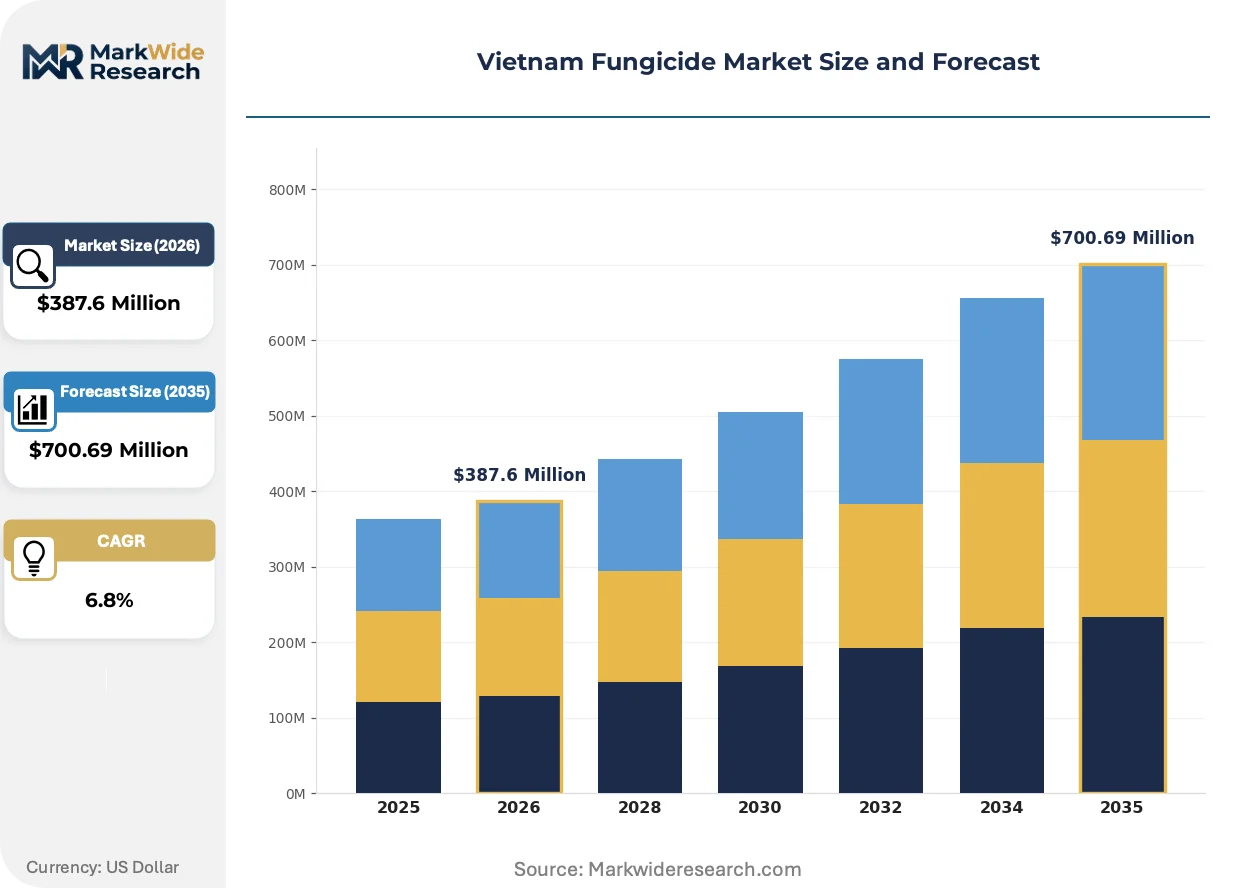
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systemic, Contact, Preventive, Curative Application Method: Foliar Spray, Soil Treatment, Seed Treatment, Granular Crop Type: Fruits, Vegetables, Cereals, Ornamentals Formulation Type: Liquid, Powder, Granule, Emulsifiable Concentrate |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, ADAMA Agricultural Solutions Ltd., UPL Limited, FMC Corporation, Corteva Agriscience, Nufarm Ltd, Wynca Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Fungicide Market Trends and Innovations
Nano-emulsion delivery systems and biological-synthetic hybrid formulations are compressing application intervals while reshaping how Vietnamese distributors bundle technical advice with product supply.
Nano-emulsion fungicide carriers is electrifying penetration efficiency in rice blast management. Mekong Delta cooperatives adopting these formulations reduce spray volumes by half while maintaining curative coverage. This technology is compressing the cost-per-hectare gap between premium systemic brands and generic alternatives.
Vietnam's Plant Protection Department is synchronizing registration requirements with ASEAN MRL harmonization frameworks. Formulators must now submit residue trial data across multiple climatic zones before commercial approval. Rice export-oriented suppliers in An Giang and Dong Thap provinces are pre-positioning documentation to capture accelerated review pathways.
Farmer purchasing through mobile-enabled cooperative aggregators is displacing traditional village-level retailer networks. Digital platforms in Tien Giang and Vinh Long provinces pool orders to unlock volume-tier pricing from distributors. This channel shift concentrates buyer power while compressing distributor field service obligations toward technical rather than transactional support.
Vietnam Fungicide Market Segmentation
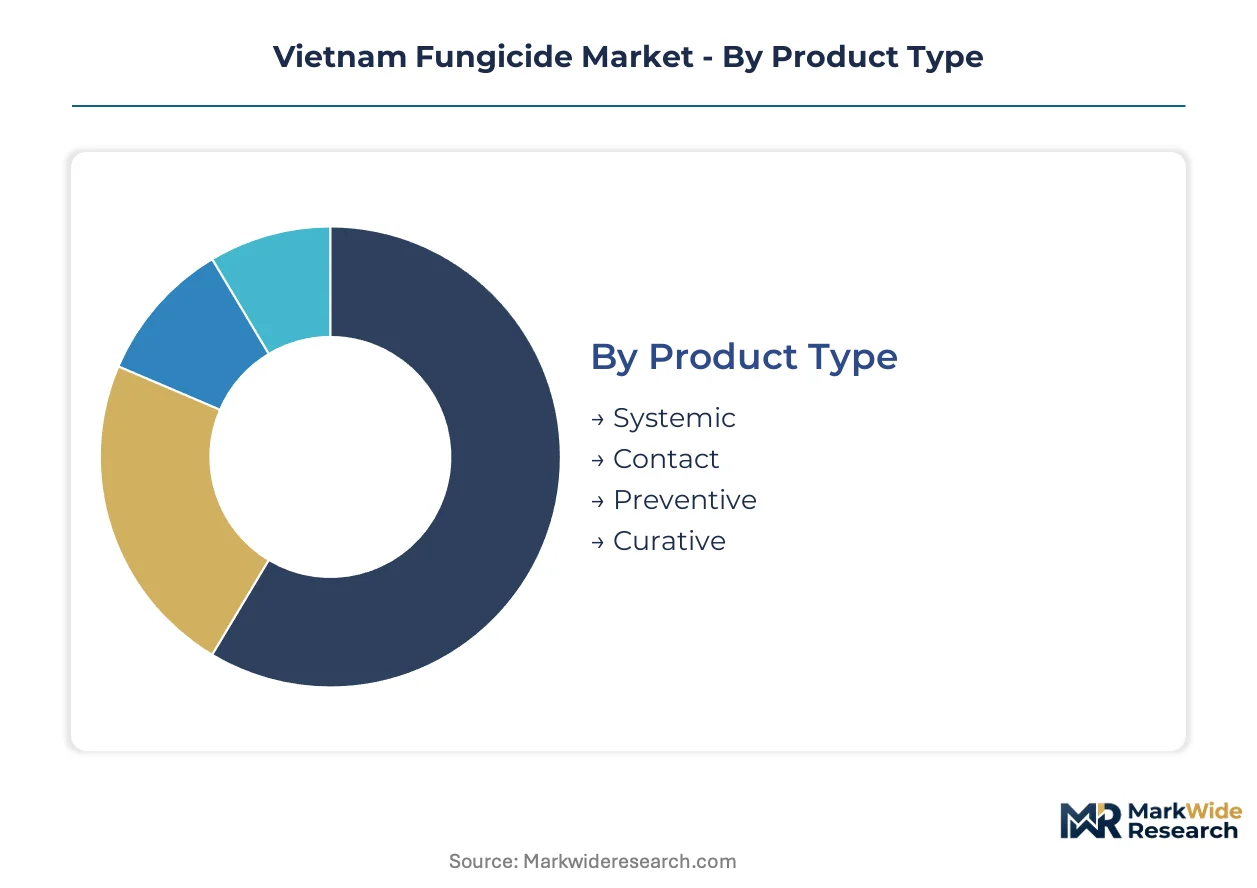
Fungicide procurement patterns in Vietnam diverge sharply across crop protection protocols, with Mekong Delta rice operators prioritizing curative systemics while Red River Delta vegetable growers cycle through contact formulations on compressed schedules. Understanding these segment boundaries clarifies where formulation investments concentrate and which application technologies capture distributor margins.
Product Type:
Upgrade cycles from contact to systemic chemistries accelerate where curative intervention becomes essential after initial infection.
- Systemic:These formulations penetrate plant tissues and redistribute through xylem vessels, making them dominant in rice blast management across An Giang and Dong Thap provinces where post-infection treatment determines yield recovery. Circular 24's tightened MRL protocols favor pre-registered systemic brands with documented residue profiles for EU-bound exports.
- Contact:Surface-acting compounds retain larger margin pools in Da Lat greenhouse operations, where frequent reapplication cycles on high-value vegetables generate recurring revenue for distributors serving Lam Dong province.
- Preventive:Prophylactic applications concentrate in seedbed and nursery stages of dragon fruit propagation in Binh Thuan province.
- Curative:Post-infection treatments see concentrated demand during monsoon-triggered sheath blight outbreaks in Mekong Delta wet-season rice.
Systemic formulations sit at the top of the volume ranking, with curative applications climbing the fastest as climate volatility intensifies disease pressure windows.
Application Method:
Cost tier differentiation separates labor-intensive foliar operations from capital-heavy soil treatment infrastructure in high-value orchard segments.
- Foliar Spray:Aerial and ground-based foliar delivery dominates rice production across Tien Giang and Vinh Long provinces, where cooperative aggregators pool spray contractor services to reduce per-hectare labor costs.
- Soil Treatment:Drench and fumigation protocols gain traction in Central Highlands dragon fruit orchards seeking phytophthora root rot prevention, with soil treatment adoption expanding fastest among export-certified operations.
- Seed Treatment:Pre-planting chemical coatings on rice seeds see concentrated use in certified seed multiplication programs under Plant Protection Department supervision.
- Granular:Slow-release granule applications concentrate in ornamental nursery operations around Hanoi where precision placement justifies material cost premiums.
Foliar spray commands the widest installed base, though soil treatment gains share fastest as orchard operators invest in root-zone protection infrastructure.
Crop Type:
Customer type fragmentation splits procurement between cooperative-aggregated rice volumes and individually negotiated vegetable contracts.
- Fruits:Dragon fruit, mango, and longan operations in Binh Thuan and Son La provinces drive demand for residue-compliant formulations meeting Japanese and EU import thresholds.
- Vegetables:Intensive greenhouse tomato and cucumber production in Red River Delta provinces generates year-round fungicide consumption with compressed reapplication intervals.
- Cereals:Rice dominates absolute volume, with Mekong Delta cooperatives negotiating bulk procurement terms for blast and sheath blight management.
- Ornamentals:Flower farms around Dalat and Hanoi prioritize aesthetic damage prevention with lower tolerance for visible fungal infection.
Cereals generate the largest absolute tonnage, with fruits expanding most quickly as export-oriented orchard acreage increases.
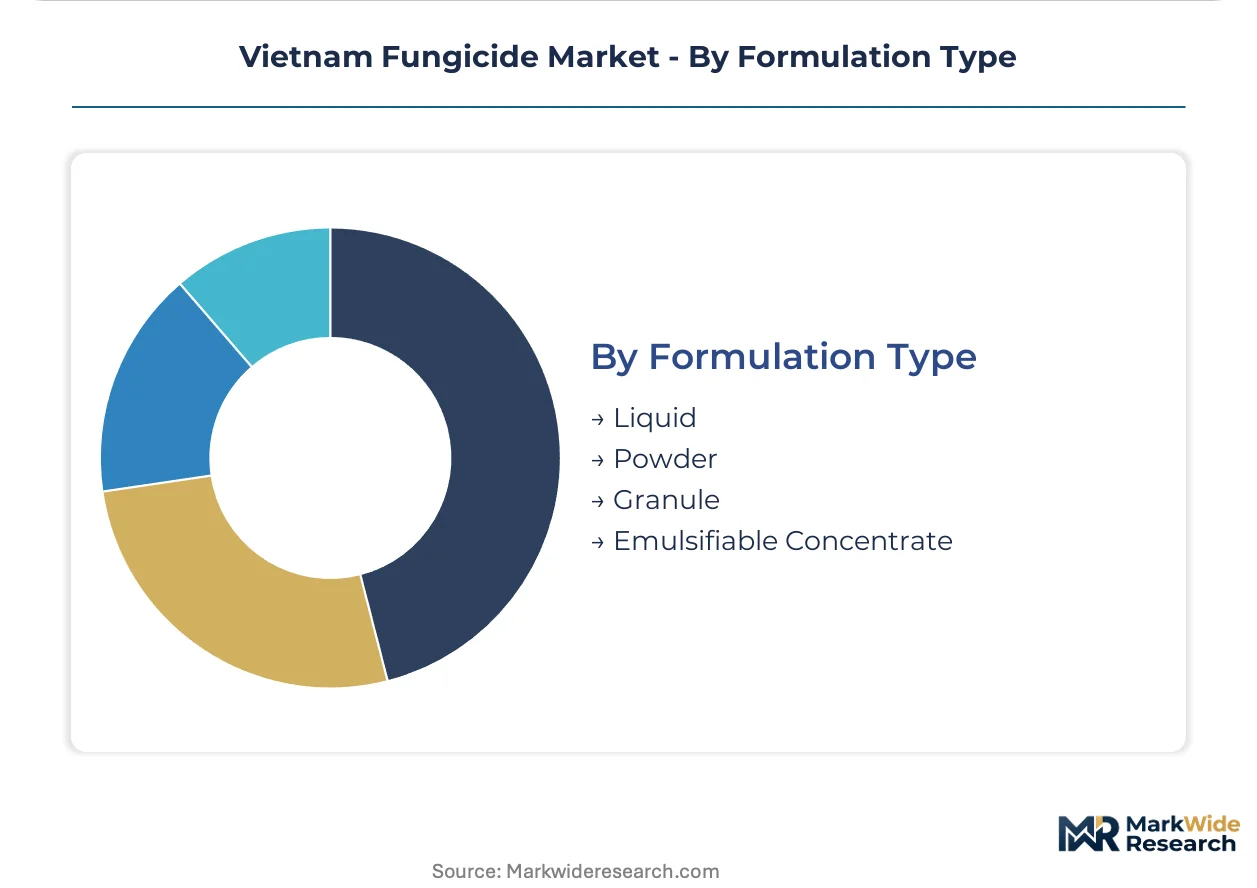
Formulation Type:
Supply concentration in liquid formulation capacity shapes distributor inventory strategies across the country.
- Liquid:Suspension concentrates and soluble liquids dominate rice cooperative procurement for foliar spray compatibility with mechanized application equipment.
- Powder:Wettable powders retain cost-sensitive smallholder segments in remote Mekong Delta districts with limited cold-chain storage requirements.
- Granule:Dry granule formulations serve soil treatment applications in orchard and vegetable bed preparation.
- Emulsifiable Concentrate:EC formulations see concentrated use in vegetable production where oil-based carriers enhance adhesion under humid greenhouse conditions.
Liquid formulations hold the dominant volume position, with emulsifiable concentrates gaining traction fastest in protected cultivation expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands larger absolute fungicide volumes than Vietnam, yet the latter's export-oriented agriculture creates tighter MRL compliance requirements that reshape procurement patterns across Southeast Asian supply chains.
Mekong Delta
Sheath blight and rice blast pressure drives recurring systemic fungicide applications across An Giang and Dong Thap provinces. Vietnam's Plant Protection Department enforces Circular 24 MRL protocols that filter distributor inventories toward certified formulations. Can Tho and Long An districts concentrate cooperative procurement networks that aggregate smallholder demand into volume-tier contracts with multinational suppliers.
Red River Delta
Intensive greenhouse vegetable production near Hanoi generates year-round demand for contact formulations with compressed reapplication cycles. The Vietnam Standards and Quality Institute certifies formulation consistency under QCVN standards that restrict uncertified imports. Bac Ninh and Hung Yen provinces host expanding protected cultivation clusters where distributors bundle technical advisory with recurring fungicide supply.
Central Highlands
Dragon fruit orchard expansion in Binh Thuan and Lam Dong provinces accelerates soil treatment adoption for phytophthora root rot prevention. Vietnam's Ministry of Agriculture and Rural Development coordinates pesticide registration review that delays new formulation commercialization. Da Lat and Bao Loc districts concentrate high-value fruit operations seeking residue-compliant chemistries for EU and Japanese export thresholds.
Southeast Region
Industrial fruit zones in Dong Nai and Ba Ria-Vung Tau provinces drive demand for biological-synthetic hybrid formulations among export-certified growers. ASEAN MRL harmonization frameworks require residue trial data submission across multiple climatic zones before commercial approval. Ho Chi Minh City logistics hubs coordinate distributor networks serving the southern agricultural belt.
Vietnam Fungicide Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with backward-integrated multinationals commanding premium systemic formulations while generic assemblers capture price-sensitive rice cooperative volumes. The vendor base concentrates around three strategic archetypes: research-driven innovators with captive active ingredient synthesis, regional formulators with import-dependent supply chains, and cooperative-aligned distributors bundling advisory services. Capacity expansion in nano-emulsion delivery systems and pre-registration alignment with revised MRL standards represent the dominant competitive moves reshaping positioning.
Among the research-intensive tier, Bayer AG and Syngenta Group exemplify backward-integrated structures that control azole and strobilurin chemistries from synthesis through formulation. ADAMA Agricultural Solutions Ltd. occupies a position navigating regulatory complexity through pre-registration strategies aligned with Vietnam's revised protocols. These three anchors represent distinct approaches to compliance-heavy market access: captive supply security, dedicated crop programs, and regulatory anticipation.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| ADAMA Agricultural Solutions Ltd. |
| UPL Limited |
| FMC Corporation |
| Corteva Agriscience |
| Nufarm Ltd |
| Wynca Group |
| Others |
Pricing and Supply Chain Analysis
Mekong Delta rice cooperatives concentrate procurement volumes into annual contract negotiations, locking in systemic fungicide pricing through volume-tier agreements with multinational formulators. This buyer consolidation creates tiered pricing separation between certified premium brands and generic alternatives, with Circular 24 compliance costs embedded as a non-negotiable surcharge.
Pricing Analysis
Capacity additions in Chinese azole synthesis facilities are reshaping price floors for strobilurin and triazole chemistries imported into Vietnam. Three-tier pricing structure across certified premium, registered standard, and unregistered economy levels reflects differentiation by Plant Protection Department registration status and residue documentation completeness. Pricing pressure stems from smallholder budget fragmentation splitting orders across multiple generic suppliers. Rice cooperatives in An Giang and Dong Thap provinces exhibit highest price sensitivity, while export-certified dragon fruit operators in Binh Thuan province absorb premium tier costs to secure EU-Japan MRL compliance.
Supply Chain Analysis
Dual-sourcing requirements from Vietnamese distributors mandate qualification of at least two active ingredient suppliers for azole and strobilurin chemistries. Geographic supply concentration centers on China, India, and South Korea for technical-grade synthesis, with formulation finishing distributed across domestic Vietnamese plants. Raw material dependencies include ethylene, propylene, and specialized solvent carriers subject to petrochemical price volatility. Single-source vulnerability concentrates in nano-emulsion carrier technology controlled by limited East Asian patent holders. Distribution runs through Ho Chi Minh City logistics hubs coordinating last-mile delivery to provincial cooperative aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's fungicide market functions as a regulatory compounder where Circular 24 MRL enforcement creates accelerating compliance premiums for pre-registered formulations. This regulatory milestone drives demand consolidation toward certified suppliers capable of residue documentation across multiple climatic zones.
For Market Incumbents: Deploy backward integration into active ingredient synthesis to secure supply continuity for azole and strobilurin chemistries against East Asian concentration risk. Deepen cooperative advisory bundling in Tien Giang and Vinh Long provinces to lock in recurring revenue from Mekong Delta rice aggregators. This counters margin compression from generic competitors and digital platform disintermediation threatening traditional village retailer networks.
For New Entrants and Emerging Players: Launch via mobile-enabled cooperative aggregator partnerships to bypass entrenched distributor field service obligations in Mekong Delta provinces. Target soil treatment fungicide penetration in Central Highlands dragon fruit orchards where root rot prevention infrastructure remains underdeveloped. Pursue biological-synthetic hybrid formulations for export-certified vegetable producers seeking premium positioning under ASEAN MRL harmonization frameworks.
For Investors and Strategic Acquirers: Regional formulators with pre-registered Circular 24 portfolios are the most active acquirer targets in this space, commanding valuation premiums for accelerated approval pathways. Long-term viability hinges on residue trial data assets spanning multiple climatic zones and crop types. Watch for inflection in EU-Japan MRL harmonization lag resolution, which would eliminate dual-formulation overhead and consolidate procurement toward single-certification suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-registration Alignment with Circular 24 | Plant Protection Department compliance creates first-mover advantage for certified formulation suppliers. |
| Nano-emulsion Delivery System Investment | Mekong Delta cooperatives reduce spray volumes by half while maintaining curative coverage against rice blast. |
| Subscription Agronomy Bundling | Advisory-procurement contracts lock recurring revenue from Mekong Delta cooperative aggregators. |
| Biological-synthetic Hybrid Development | Microbial antagonist integration opens premium positioning for export-oriented vegetable producers. |
| Soil Treatment Infrastructure Partnership | Central Highlands dragon fruit orchards seek root-zone protection against phytophthora root rot. |
Research Methodology
Bottom-up crop protection modeling reconciled against top-down formulation supply tracking forms the analytical core of this study. Primary interviews with Plant Protection Department registration officers, distributor procurement managers, Mekong Delta cooperative agronomists, and Red River Delta greenhouse operators were validated against secondary sources including Vietnam Standards and Quality Institute QCVN certification records, customs import data for active ingredient shipments, and ASEAN MRL harmonization framework documentation. Triangulation between farmer purchasing pattern surveys and manufacturer shipment disclosures ensures segment-level accuracy.
Historical trendline analysis of fungicide application rates across rice blast and sheath blight pressure cycles informed projection parameters. The forecast framework models segmentation dimensions including product type, application method, crop category, and formulation chemistry across the projection horizon. CAGRs were derived from regression analysis of cooperative procurement volumes, climate-driven disease pressure indices, and regulatory approval timeline compression. Industry-specific inputs include Plant Protection Department review queue lengths and EU-Japan MRL threshold convergence patterns.
Several conditions sit outside the modeled scope, including extreme weather event frequency beyond historical climate volatility patterns and unilateral import threshold changes by major destination markets. Forecasts reflect assumptions regarding Circular 24 enforcement consistency and ASEAN MRL harmonization timeline adherence. Deviation in Plant Protection Department registration review speed or EU-Japan MRL convergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Specialty Pesticides Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Tebuconazole Market
Crop Protection
Vietnam Insecticide Market
Crop Protection
Europe Nematicide Market
Crop Protection
Global Seed Treatment Fungicides Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Pest Control Market
Crop Protection
India Insecticide Market
Crop Protection
Metamifop Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
IPM Pheromones Market