
 Stored Grain Insecticides Market | 2026-2036
Stored Grain Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Stored Grain Insecticides Market Analytics
Precision application technology is reshaping how stored grain insecticides are delivered, shifting from blanket fumigation toward sensor-guided, variable-rate dispensing systems that reduce chemical load while maintaining efficacy. Syngenta AG leverages its digital agriculture platform to integrate pest monitoring with automated treatment triggers across commercial grain networks. BASF SE anchors its position through backward integration into pyrimiphos-methyl active ingredient production, securing supply continuity for phosphine alternatives. UPL Limited competes aggressively in emerging markets with localized formulation facilities that cut import dependency and logistics costs.
Stored grain insecticides comprise chemical formulations designed to prevent or eliminate insect infestations in harvested cereals, oilseeds, and pulses held in bulk storage, typically applied at concentrations measured in parts per million to achieve lethal exposure without grain residue violations. These products function through contact toxicity, fumigant vapor action, or disruption of insect development cycles to preserve commodity weight, germination rates, and food safety compliance during storage periods extending from weeks to multiple years. Among active ingredient categories, pyrethroids dominate volume sales for surface treatments due to their rapid knockdown profile and established residue tolerance databases, while insect growth regulators represent the fastest-expanding segment as regulators tighten restrictions on neurotoxic chemistries. Fumigant formulations retain the largest value share in large-capacity silo applications where phosphine tablets and aluminum phosphide preparations remain the only economically viable option for sealed-structure penetration.
The EPA governs stored grain insecticide registration under FIFRA, enforcing residue tolerances through FDA coordinated enforcement that directly determines which chemistries remain available for domestic grain handlers. REACH and the EU Green Deal are forcing reformulation across export-oriented suppliers, as MRL alignment with European import standards becomes a non-negotiable market access condition for multinational grain traders. Stakeholders must monitor regulatory divergence between major import jurisdictions, since misalignment in approved active ingredient lists threatens to fragment supply chains and strand inventory in cross-border commerce.
Market Dynamics
EPA's methyl bromide phase-down under the Montreal Protocol is forcing wholesale chemistry transitions across commercial grain storage infrastructure, compressing multi-decade fumigation practices into accelerated phosphine and insect growth regulator adoption cycles.
Growth Catalysts
- Integrated Pest Management Mandates:Commercial grain elevators in the United States are deploying sensor-guided application systems to meet FDA residue tolerance enforcement while reducing chemical load.
- REACH Reformulation Pressure:EU Green Deal alignment requirements are compelling export-oriented suppliers to redesign active ingredient portfolios for MRL compatibility with European import standards.
- Phosphine Tablet Demand:Large-capacity silo operators require aluminum phosphide preparations as the only economically viable sealed-structure penetration option for multi-year storage periods.
Market Restraints
- Active Ingredient Supply Concentration:Backward integration into pyrimiphos-methyl production remains limited to select manufacturers, creating vulnerability for phosphine alternative supply continuity.
- Regulatory Divergence Friction:Misalignment between EPA FIFRA registrations and EU REACH approved substance lists threatens to fragment cross-border grain commerce and strand inventory.
- Technical Efficacy Limitations:Insect growth regulators require extended exposure periods that conflict with rapid grain turnover schedules at high-velocity export terminals.
Strategic Opportunities
- Brazil Infrastructure Investment:Post-harvest storage expansion in Brazilian grain belts creates demand for localized formulation capacity to reduce import dependency and logistics costs.
- Digital Agriculture Convergence:Integration of automated pest monitoring with variable-rate dispensing systems enables precision fumigation protocols that reduce blanket chemical application.
- India PLI Scheme Tailwinds:Production-linked incentive frameworks for agrochemical manufacturing support domestic formulation facility establishment for import substitution.
Industry Challenges
- Fumigation Technician Certification Bottlenecks:EPA-certified applicator training programs face capacity constraints that delay workforce scaling for phosphine handling requirements.
- Legacy Silo Retrofit Costs:Sealed-structure phosphine fumigation demands capital-intensive infrastructure modifications at aging grain elevator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stored Grain Insecticides Market |
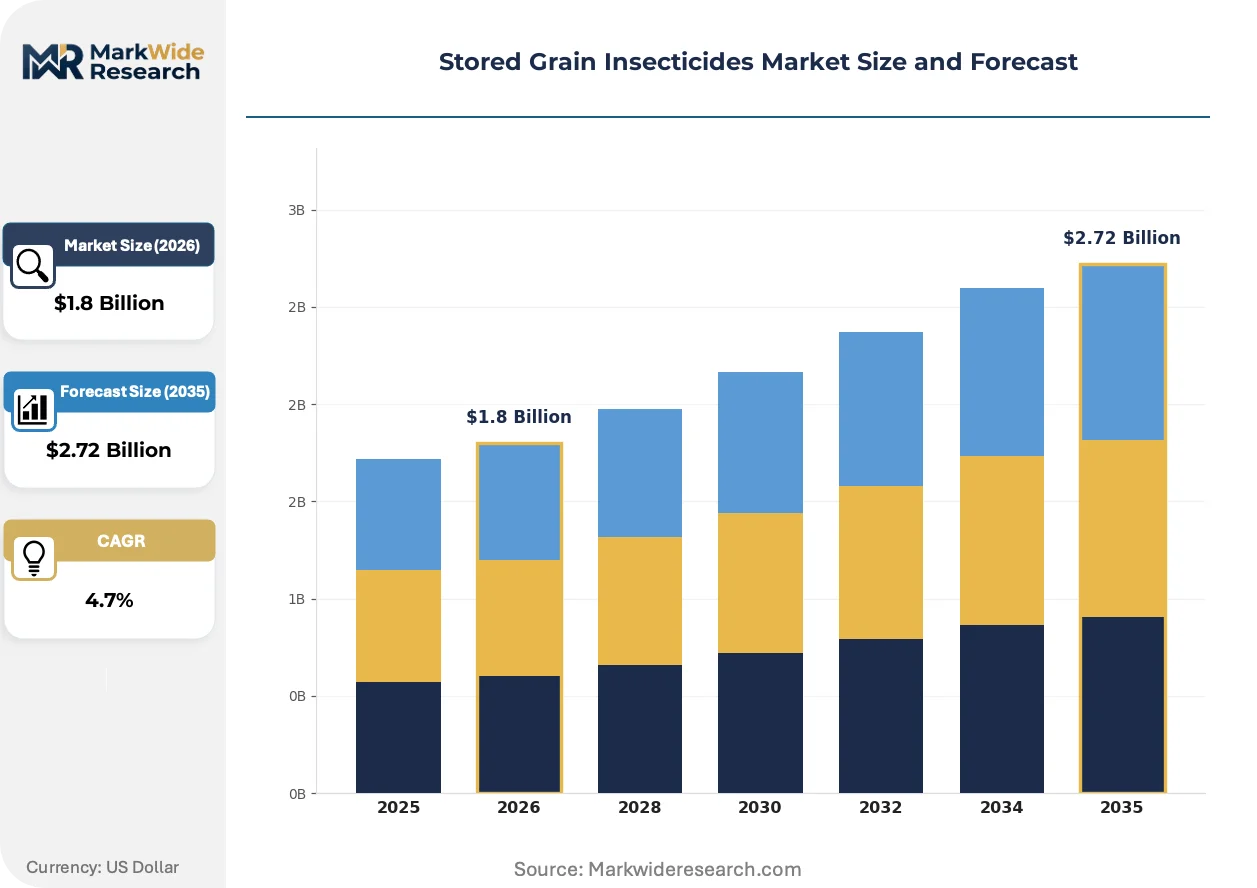
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Aerosol, Fumigant Active Ingredient: Organophosphates, Pyrethroids, Neem Oil, Insect Growth Regulators Application Method: In-Fumigation, Surface Treatment, Soil Treatment, Coating Grain Type: Wheat, Corn, Rice, Barley |
| Companies Covered | Syngenta AG, Corteva Agriscience, BASF SE, UPL Limited, Adama Agricultural Solutions Ltd, FMC Corporation, Bayer CropScience AG, Nufarm Ltd, Douglas Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stored Grain Insecticides Market Evolving Landscape
Sensor-guided dispensing systems are displacing manual fumigation across commercial grain networks, compressing application precision while regulatory chemistry restrictions accelerate active ingredient portfolio redesign.
Automated pest monitoring platforms combine thermal imaging with pheromone detection arrays to trigger treatment protocols. Large-scale warehousing operators in the United States are deploying these systems at commercial grain elevators to replace calendar-based fumigation schedules. This convergence of detection hardware with cloud analytics is digitizing how insecticide dosing decisions are executed across bulk storage facilities.
REACH authorization procedures and EU Green Deal chemical sustainability criteria are restricting neurotoxic active ingredient availability. Export-oriented grain suppliers must reformulate to maintain European market access, driving insect growth regulator development. Multinational traders are consolidating approved substance lists to prevent cross-border inventory stranding from regulatory misalignment.
Buyer procurement is compressing toward outcome-based service contracts that bundle pest monitoring with guaranteed residue compliance. Commercial grain elevators are unbundling chemical supply from application services, favoring vendors with integrated digital platforms. This restructuring is most visible in United States grain belt states where elevator consolidation has concentrated purchasing power among fewer operators.
Stored Grain Insecticides Market Segmentation
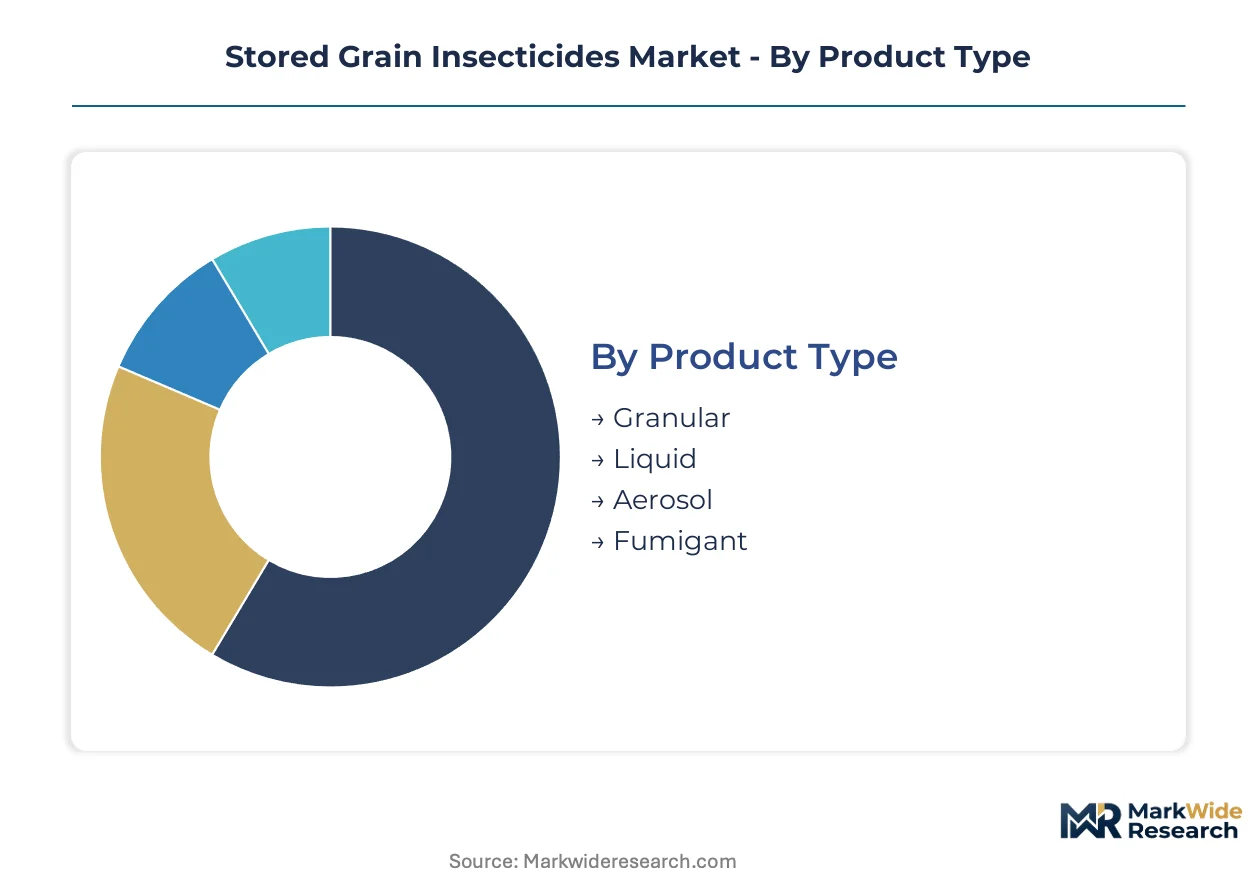
Segmentation in stored grain insecticides reflects divergent efficacy requirements across storage infrastructure types, chemistry portfolios, and commodity handling protocols. Formulation selection directly constrains application method compatibility and residue compliance thresholds.
Product Type:
Cost tier determines equipment compatibility and labor intensity across commercial storage operations.
- Fumigant:Aluminum phosphide tablets and phosphine gas formulations penetrate sealed silo structures for multi-year storage protection. Large-capacity grain elevators in the United States deploy these as the only economically viable option for bulk commodity penetration, though EPA-certified applicator shortages constrain deployment velocity.
- Liquid:Emulsifiable concentrates and suspension concentrates enable surface treatment and grain coating through standard spray equipment. Brazilian post-harvest infrastructure expansion is concentrating procurement of liquid formulations for their compatibility with mechanized handling systems and reduced labor dependency.
- Granular:Clay-based carriers impregnated with active ingredients provide localized application at grain entry points. These formulations suit small-scale warehousing with limited ventilation infrastructure.
- Aerosol:Pressurized formulations deliver rapid knockdown in confined space treatments. Empty bin applications and spot treatments dominate this segment's demand profile.
Fumigant holds installed capacity. Liquid is rotating up the share rankings.
Active Ingredient:
Application chemistry determines regulatory approval status across import jurisdiction boundaries.
- Pyrethroids:Synthetic compounds including deltamethrin and permethrin deliver rapid contact toxicity for surface treatments. These chemistries dominate volume sales due to established FDA residue tolerance databases and rapid knockdown profiles against primary storage pests.
- Insect Growth Regulators:Methoprene and hydroprene formulations disrupt insect development cycles rather than causing acute mortality. EU REACH authorization pressure and EU Green Deal sustainability criteria are accelerating reformulation toward these alternatives, though extended exposure requirements conflict with rapid grain turnover at export terminals.
- Organophosphates:Pyrimiphos-methyl and malathion formulations provide broad-spectrum contact toxicity. Backward integration into active ingredient production remains concentrated among select manufacturers, creating supply continuity vulnerability.
- Neem Oil:Botanical extracts with azadirachtin as the primary active compound serve organic-certified grain handling operations. Limited residual persistence constrains adoption in long-duration storage protocols.
Pyrethroids anchor current formulation volumes. Insect Growth Regulators are climbing the fastest as regulatory pressure intensifies.
Application Method:
Customer type dictates equipment investment and labor certification requirements.
- In-Fumigation:Phosphine gas introduction during grain loading achieves uniform distribution through commodity mass. Commercial grain elevators with sealed concrete silos represent the concentrated demand base for this method.
- Surface Treatment:Spray application to grain piles and bin walls targets perimeter infestation vectors. This method dominates small-to-medium warehousing operations with limited capital for sealed-structure retrofit.
- Coating:Active ingredient application directly to seed grain preserves germination rates for planting stock. Specialty seed handlers and agricultural cooperatives concentrate procurement here.
- Soil Treatment:Pre-storage ground application targets soil-dwelling pest populations at facility perimeters. Integrated pest management protocols are expanding adoption of this preventive approach.
In-Fumigation commands the capital-intensive infrastructure segment. Surface Treatment is gaining share fastest among retrofit-constrained operators.
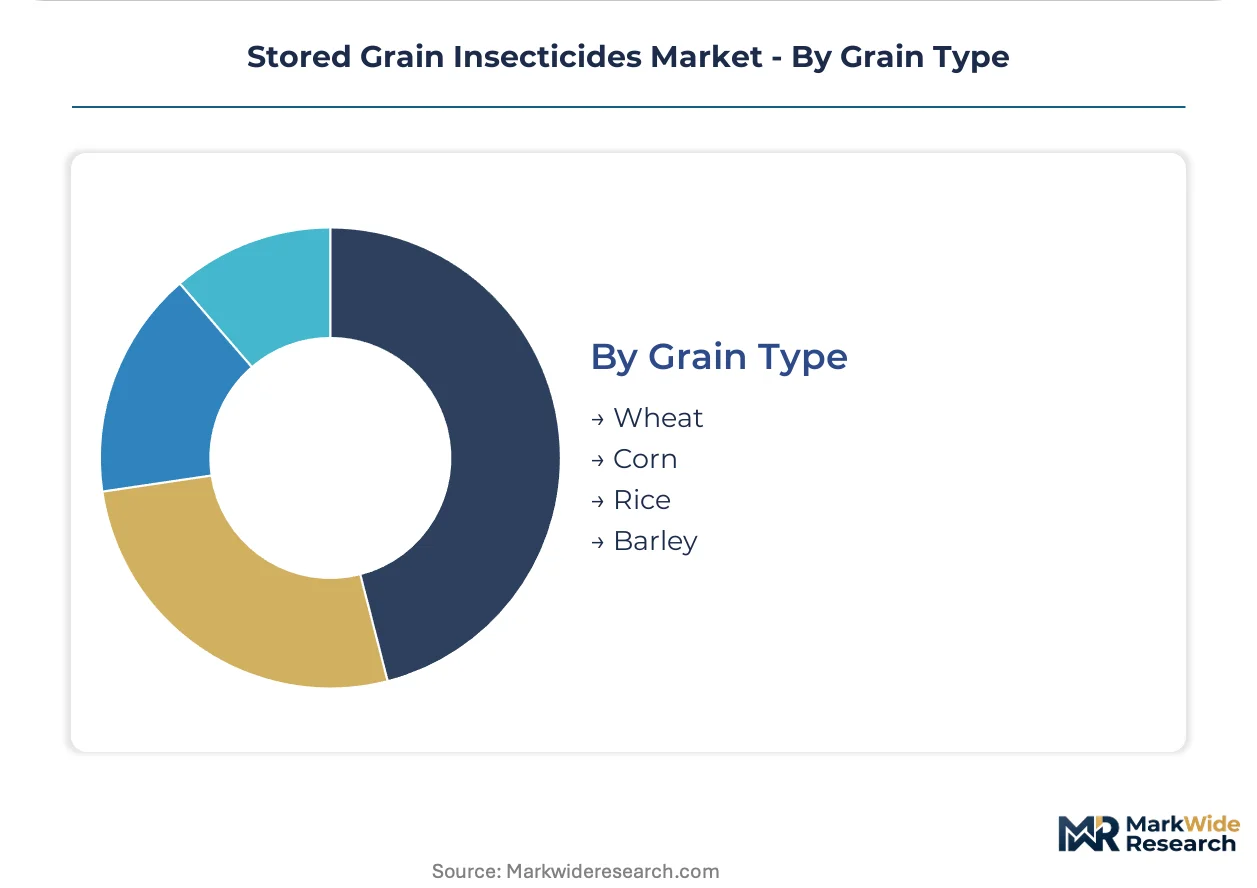
Grain Type:
Volume concentration varies with harvest calendar and export flow patterns.
- Corn:High-oil content and extended storage durations in the United States grain belt create sustained demand for phosphine-based protection. FDA residue enforcement and export MRL alignment constrain chemistry selection.
- Wheat:Global trade volume and multi-year strategic reserve storage in India drive formulation requirements. The country's PLI scheme for agrochemical manufacturing supports domestic production capacity expansion.
- Rice:Tropical storage conditions with elevated humidity accelerate infestation pressure. Southeast Asian handling facilities concentrate demand for rapid-acting contact insecticides.
- Barley:Malt quality preservation requirements in brewing supply chains impose strict residue thresholds. European import standards shape approved substance lists for this segment.
Corn dominates North American application volumes. Wheat is expanding most quickly in emerging market infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports soybeans and corn to European and Asian buyers, forcing its stored grain insecticide formulations to align with EU REACH MRL standards and Chinese import tolerances simultaneously. This trade-flow pressure shapes chemistry selection across South American post-harvest infrastructure.
United States
Commercial grain elevators in Iowa, Illinois, and Nebraska drive phosphine tablet demand for multi-year corn storage. EPA FIFRA registration enforcement under the Montreal Protocol methyl bromide phase-down accelerates transitions to aluminum phosphide preparations. The Gulf Coast export corridor concentrates automated fumigation system deployment at high-velocity terminals.
Brazil
Mato Grosso and Goiás grain belts expand post-harvest storage capacity to reduce harvest-time bottlenecks. ANVISA agrochemical registration requirements and EU export MRL alignment compel reformulation toward insect growth regulators. Localized production facilities in São Paulo state cut import dependency for phosphine alternatives.
India
Punjab and Haryana wheat procurement operations require fumigant protection for Food Corporation of India strategic reserves. The PLI scheme for agrochemical manufacturing supports domestic formulation capacity expansion. Mumbai-based traders consolidate approved substance lists to prevent EU-bound inventory stranding.
Germany
Bavarian grain cooperatives face ECHA REACH authorization pressure on neurotoxic chemistries. The EU Green Deal chemical sustainability criteria accelerate insect growth regulator adoption for malting barley protection. Hamburg port operators enforce residue documentation for re-export to Asian markets.
China
Shandong and Henan wheat storage facilities deploy phosphine-based protection for state grain reserves. NMPA agrochemical registration and dual carbon goals constrain fumigant emission intensities. Yangtze River Delta traders align active ingredient portfolios with EU import tolerances for premium grain exports.
Stored Grain Insecticides Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation and application service bundling. The market structure concentrates around agrochemical conglomerates with backward integration into active ingredient production and regional specialists with localized formulation flexibility. Three archetypes dominate: integrated life sciences conglomerates with digital agriculture platforms, mid-scale formulators with import-substitution capabilities, and fumigation service providers unbundling chemical supply from application execution. Competitive moves center on M&A for geographic footprint expansion and strategic partnerships for phosphine alternative supply continuity.
Among integrated life sciences conglomerates, Syngenta AG and BASF SE occupy positions defined by captive supply chains and platform integration. Syngenta leverages digital agriculture infrastructure to bundle pest monitoring with automated treatment triggers. BASF SE anchors the phosphine alternative segment through in-house pyrimiphos-methyl production. UPL Limited exemplifies the emerging-market specialist archetype with localized formulation capacity in India and Brazil.
| Leading Market Players |
|---|
| Syngenta AG |
| Corteva Agriscience |
| BASF SE |
| UPL Limited |
| Adama Agricultural Solutions Ltd |
| FMC Corporation |
| Bayer CropScience AG |
| Nufarm Ltd |
| Douglas Products |
| Others |
Value Network & Pricing Analysis
The Mississippi River grain corridor anchors cost dynamics for stored grain insecticides, where barge freight rates and port congestion at Gulf Coast terminals compress margins for phosphine tablet distributors while creating pricing power for regional blenders with localized formulation capacity.
Pricing Analysis
Sensor-generation pricing gaps separate legacy manual-application chemistries from precision-dispensing formulations and emerging automated monitoring bundles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EPA-licensed applicator service bundles commanding sustained premiums. Cost compression in liquid formulation tiers intensifies as Brazilian import-substitution capacity expands. Small-scale warehousing operators exhibit highest price sensitivity, while large commercial elevators prioritize residue compliance guarantees over unit cost.
Supply Chain Analysis
Export-control restrictions on phosphine precursor chemicals under the Chemical Weapons Convention limit aluminum phosphide tablet flows from concentrated manufacturing nodes. Active ingredient production centers on China, India, and Germany, with formulation finishing distributed across Brazil, the United States, and India to reduce logistics exposure. Supply chains draw from phosphorus rock, methyl bromide alternatives, and pheromone synthesis feedstocks. Single-source vulnerability in pyrimiphos-methyl active ingredient supply creates concentration risk. Distribution runs through agrochemical distributor networks with elevator-direct contracting at volume tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stored grain insecticides track agricultural commodity cycles, with elevator construction booms in Brazilian grain belts and Indian strategic reserve expansion signaling recovery-phase inventory rebuilding.
For Market Incumbents: Entrench phosphine alternative supply continuity through captive pyrimiphos-methyl production or long-term offtake agreements with Indian and Chinese active ingredient manufacturers. Expand EPA-certified applicator training partnerships to preempt workforce bottlenecks that constrain deployment velocity at commercial grain elevators. For New Entrants and Emerging Players: Mid-scale liquid formulation facilities in Mato Grosso and Goiás represent the most penetrable entry point, serving Brazilian post-harvest infrastructure expansion with import-substitution positioning. Target insect growth regulator production under ANVISA fast-track registration for EU export alignment. Partner with regional distributor networks rather than building direct elevator sales teams. For Investors and Strategic Acquirers: EPA's methyl bromide phase-down completion reshapes the acquisition landscape toward phosphine-handling service providers with certified workforce assets. Five-to-ten year viability favors integrated pest management platform operators with digital agriculture bundling capability. Monitor ANVISA registration approval velocity for Brazilian market access inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredients | BASF's captive pyrimiphos-methyl production secures supply continuity for phosphine alternatives amid regulatory transition. |
| Digital Agriculture Platform Integration | Syngenta's sensor-guided dispensing systems bundle pest monitoring with automated treatment triggers across commercial grain networks. |
| Localized Formulation Capacity Expansion | UPL's Brazilian and Indian facilities reduce import dependency and logistics costs for post-harvest infrastructure growth. |
| Regulatory Certification Investment | REACH authorization and EU Green Deal alignment enable continued European market access for export-oriented grain suppliers. |
| EPA-Certified Applicator Workforce Scaling | Training program partnerships address bottlenecks constraining phosphine deployment velocity at commercial grain elevators. |
Research Methodology
A standing panel of grain elevator operations managers, EPA-certified fumigation technicians, agrochemical procurement directors, and ANVISA regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with commercial storage facility operators and formulation plant managers combined with secondary validation from EPA FIFRA registration databases, FDA residue tolerance filings, customs trade data, and SEC 10-K disclosures for publicly traded agrochemical conglomerates. Bottom-up volume estimates triangulated against top-down market sizing from industry association reports.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions including formulation type, active ingredient chemistry, application method, grain commodity, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for regulatory phase-down schedules and infrastructure investment cycles. Forecast inputs incorporated elevator construction pipelines, methyl bromide stockpile depletion rates, and insect growth regulator registration timelines.
Practitioners should monitor EPA applicator certification program capacity, REACH authorization decisions for neurotoxic chemistries, and Brazilian ANVISA registration velocity for early signals of forecast deviation. Material shifts in Montreal Protocol enforcement timelines or EU MRL alignment requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Europe Feed Antibiotics Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
Global Crop Oil Concentrates Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Feed Pelletizing Agents Market