
 Nematicides Market | 2026-2036
Nematicides Market Size, Share, and Industry Trends Forecast 2026-2036
Nematicides Market Intelligence
Specialized agrochemical manufacturers in India is expanding production of generic organophosphate nematicides to serve African and Southeast Asian export markets. Syngenta leverages its integrated seed-and-crop-protection platform to bundle nematicide-treated soybean seeds in Latin America. BASF SE anchors European biological nematicide development through its proprietary fermentation-derived product lines. Bayer AG competes in the North American corn-soy complex with concentrated abamectin formulations.
Nematicides are biocidal agents formulated to kill or suppress plant-parasitic nematodes, typically delivered as soil-incorporated liquids, granules, or seed coatings containing active ingredients such as abamectin, fluopyram, or Purpureocillium lilacinum fungal biomass. These compounds function by disrupting nematode neuromuscular transmission or colonizing nematode eggs, thereby protecting root systems and preserving crop yield. Chemical nematicides still dominate volume sales across large-scale row-crop agriculture, though biological nematicides are capturing margin pools in organic-certified and export-oriented vegetable production where residue limits constrain synthetic use. Fruits and vegetables represent the fastest-growing crop-type segment as protected cultivation expands and root-knot nematode pressure intensifies under continuous cropping regimes.
EPA registration requirements under FIFRA govern nematicide efficacy claims and environmental fate testing in the United States, while EU REACH and the F-Gas Regulation constrain soil fumigant availability and push formulators toward lower-volatility alternatives. Brazil's ANVISA and the national environmental regulator enforce residue tolerance thresholds that shape export-oriented product selection. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which active ingredient portfolios will retain market access.
Market Dynamics
EU REACH phase-out of methyl bromide and 1,3-dichloropropene is compressing chemical nematicide availability while biological alternatives scramble to fill root-knot nematode control gaps in intensive vegetable systems.
Growth Catalysts
- Brazilian soybean cyst nematode pressure:Seed-treatment nematicide demand concentrates in Mato Grosso and Rio Grande do Sul as resistant cultivars lose efficacy and farmers seek chemical rotation partners.
- EU F-Gas Regulation:Restrictions on soil fumigant volatility push Spanish and Italian greenhouse operators toward Purpureocillium lilacinum-based biological nematicides for protected tomato and pepper crops.
- Abamectin formulation advances:Microencapsulation technologies extend residual activity in coarse-textured soils, opening nematode control in drip-irrigated orchards previously deemed uneconomical.
Market Restraints
- Active ingredient concentration:Three Chinese manufacturers control over 70% of technical abamectin supply, creating vulnerability to export quota disruptions and input cost spikes.
- Biological efficacy variability:Purpureocillium lilacinum performance depends on soil temperature, moisture, and indigenous microbial competition, limiting predictability versus synthetic standards.
- EU residue tolerance compression:EFSA maximum residue limit tightening for organophosphates in leafy vegetables constrains export-oriented product selection in Morocco and Egypt.
Strategic Opportunities
- India biological nematicide registration:Central Insecticides Board fast-track pathways for indigenous Trichoderma strains create first-mover positioning in untreated vegetable belts of Maharashtra and Karnataka.
- Seed-coating convergence:Integration of nematicides with biostimulant inoculants offers bundled value propositions to Latin American soybean cooperatives seeking input simplification.
- US specialty crop residue windows:EPA tolerance exemptions for biological nematicides in minor-use vegetables open premium pricing in organic-certified baby greens and heirloom tomato segments.
Industry Challenges
- Soil microbiome assessment capacity:Nematode diagnostic laboratories remain concentrated in university extension networks, delaying farmer recognition of population thresholds and treatment timing.
- Biological product stability:Shelf-life constraints for living-organism formulations complicate distribution logistics in tropical climates with inadequate cold-chain infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nematicides Market |
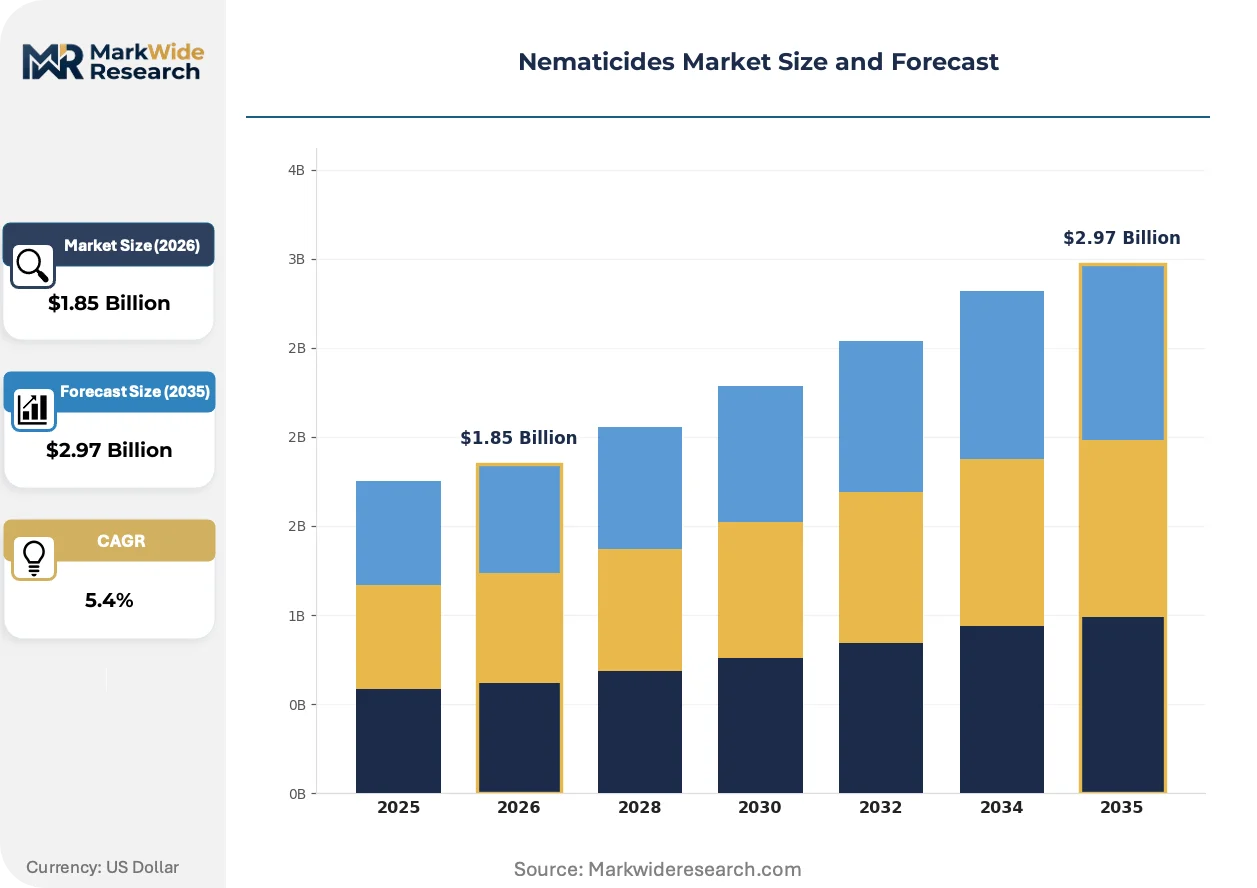
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Nematicides, Biological Nematicides, Organic Nematicides, Synthetic Nematicides Target Nematode: Root-Knot Nematodes, Cyst Nematodes, Lesion Nematodes, Stem Nematodes, Ring Nematodes Crop Type: Cereal & Grains, Fruits & Vegetables, Oilseeds & Pulses, Tubers & Root Crops, Plantation Crops Application Method: Soil Application, Seed Treatment, Foliar Spray, Drip Irrigation, Granular Application |
| Companies Covered | Syngenta, BASF SE, Bayer AG, Corteva, UPL, FMC Corporation, ADAMA Agricultural Solutions, Sumitomo Chemical, Nufarm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nematicides Market Strategic Shifts & Innovations
Formulation chemistry and delivery mechanisms are converging to extend nematicide activity windows while regulatory pressure compresses synthetic options. Biological agents are capturing technical attention as residue constraints harden in export corridors.
RNA interference nematicides targeting root-knot nematode-specific genes are overtaking conventional screening pipelines at major agrochemical R&D centers. Greenhouse vegetable producers in the Netherlands and Spain are piloting dsRNA seed coatings for tomato and cucumber systems. This technology is overtaking fumigant-dependent nematode management by eliminating pre-plant soil preparation delays and worker re-entry restrictions.
EPA registration timelines under FIFRA are compressing for biological nematicides through the agency's biopesticide division expedited review pathway. Manufacturers submitting Purpureocillium lilacinum and Bacillus firmus strains now face 12-18 month approval windows versus 36+ months for novel synthetics. Vegetable seed companies are responding by pre-loading biological nematicide coatings onto premium hybrid tomato and pepper varieties for the US Southeast.
Direct-to-farm digital procurement platforms are fragmenting traditional distribution in Brazilian soybean regions. Rural credit cooperatives in Mato Grosso are aggregating grower demand for generic abamectin seed treatments, bypassing multinational branded channels. This channel shift concentrates price leverage among organized producer groups while compressing margin pools available to traditional agrochemical distributors in the Cerrado frontier.
Nematicides Market Segmentation
Nematicide purchasing decisions pivot on regulatory compliance thresholds, residue tolerance requirements, and soil microbiome compatibility. Buyers weigh synthetic efficacy against biological registration speed and export market access constraints.
Product Type:
Crop protection managers select product categories based on certification requirements, re-entry intervals, and active ingredient availability in target export corridors.
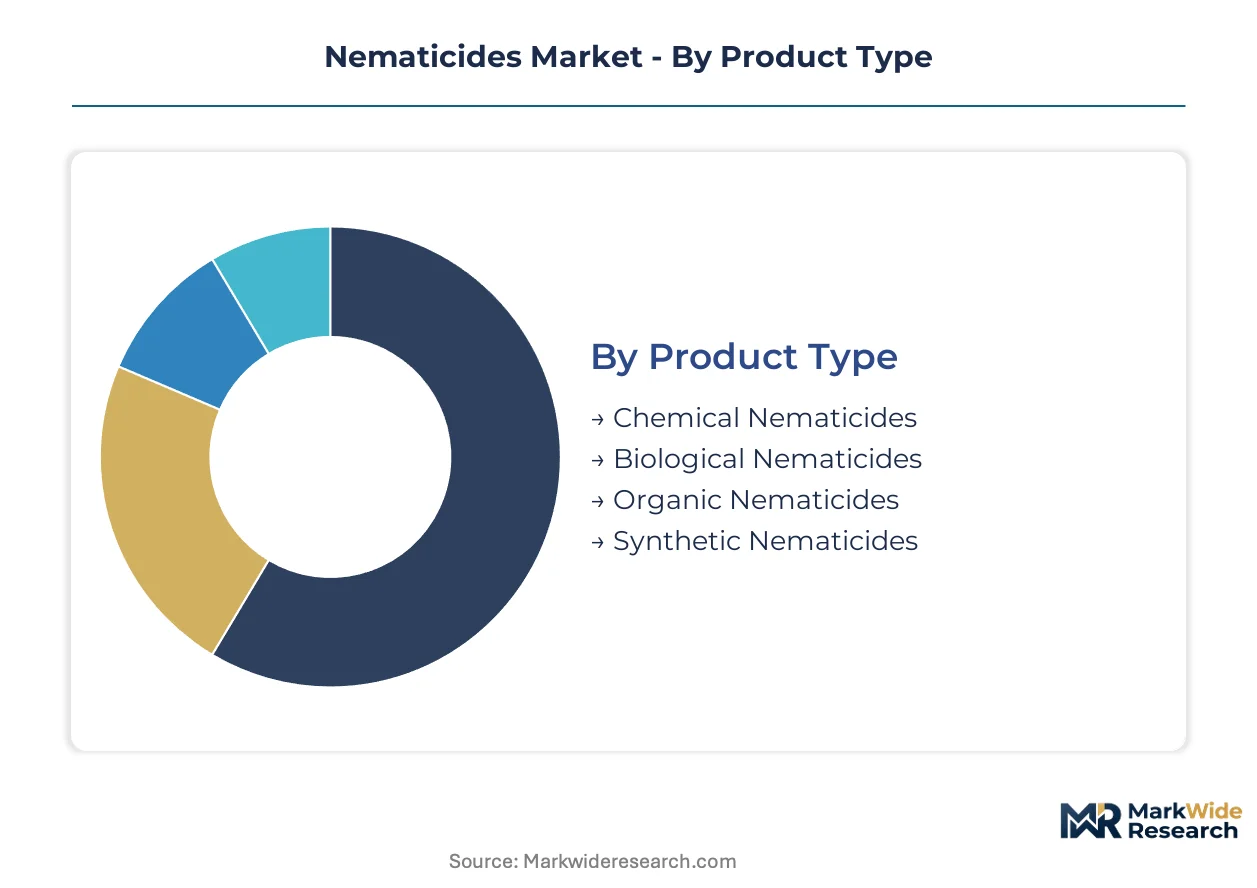
- Chemical Nematicides:Formulations containing abamectin, fluopyram, or organophosphates deliver rapid nematode mortality through neuromuscular disruption. Demand concentrates in Brazilian soybean seed-treatment channels where ANVISA residue thresholds shape product selection for export-oriented growers.
- Biological Nematicides:Fermentation-derived agents such as Purpureocillium lilacinum and Bacillus firmus colonize nematode eggs and penetrate cuticles through enzymatic action. Spanish and Italian greenhouse operators prioritize these formulations as EU F-Gas Regulation compresses soil fumigant availability for protected tomato and pepper cultivation.
- Organic Nematicides:Botanical extracts and plant-derived compounds certified for organic production systems.
- Synthetic Nematicides:Manufactured active ingredients excluding biological fermentation pathways, dominant in conventional row-crop agriculture.
Chemical nematicides lead on scale; biological nematicides lead on momentum.
Target Nematode:
Species-specific pressure patterns dictate R&D allocation and regional marketing focus across nematicide portfolios.
- Root-Knot Nematodes:Meloidogyne species induce characteristic gall formation on host roots, stunting vegetable crops in continuous cultivation systems. Moroccan and Egyptian export vegetable producers face EFSA maximum residue limit compression for organophosphate controls, accelerating biological alternative trials.
- Cyst Nematodes:Heterodera and Globodera species form protective cysts around eggs, enabling long-term soil survival. Mato Grosso and Rio Grande do Sul soybean belts concentrate seed-treatment demand as resistant cultivar efficacy declines and farmers seek chemical rotation partners.
- Lesion Nematodes:Pratylenchus species migrate through root cortex tissue, creating entry points for fungal pathogens.
- Stem Nematodes:Ditylenchus species penetrate above-ground plant tissue in humid cereal and forage systems.
- Ring Nematodes:Mesocriconema species feed ectoparasitically on root epidermis in perennial orchard and vineyard soils.
Cyst nematode-targeted products lead on scale; root-knot nematode solutions lead on momentum.
Crop Type:
Residue tolerance windows and cultivation intensity determine nematicide formulation selection and application frequency.
- Fruits & Vegetables:Protected cultivation of tomato, pepper, and cucumber faces intensifying root-knot nematode pressure under continuous cropping regimes. Dutch and Spanish greenhouse clusters pilot RNA interference seed coatings to eliminate pre-plant fumigation delays and worker re-entry restrictions.
- Oilseeds & Pulses:Soybean cyst nematode management drives seed-treatment bundling across Latin American cooperatives seeking input simplification.
- Cereal & Grains:Maize and wheat systems deploy nematicides primarily where lesion nematode thresholds exceed economic injury levels.
- Tubers & Root Crops:Potato cyst nematode pressure in temperate production zones sustains granular application demand.
- Plantation Crops:Banana and coffee root systems require extended residual protection in tropical coarse-textured soils.
Oilseeds and pulses lead on scale; fruits and vegetables lead on momentum.
Application Method:
Delivery mechanism selection reflects labor cost structures, equipment availability, and irrigation infrastructure maturity.
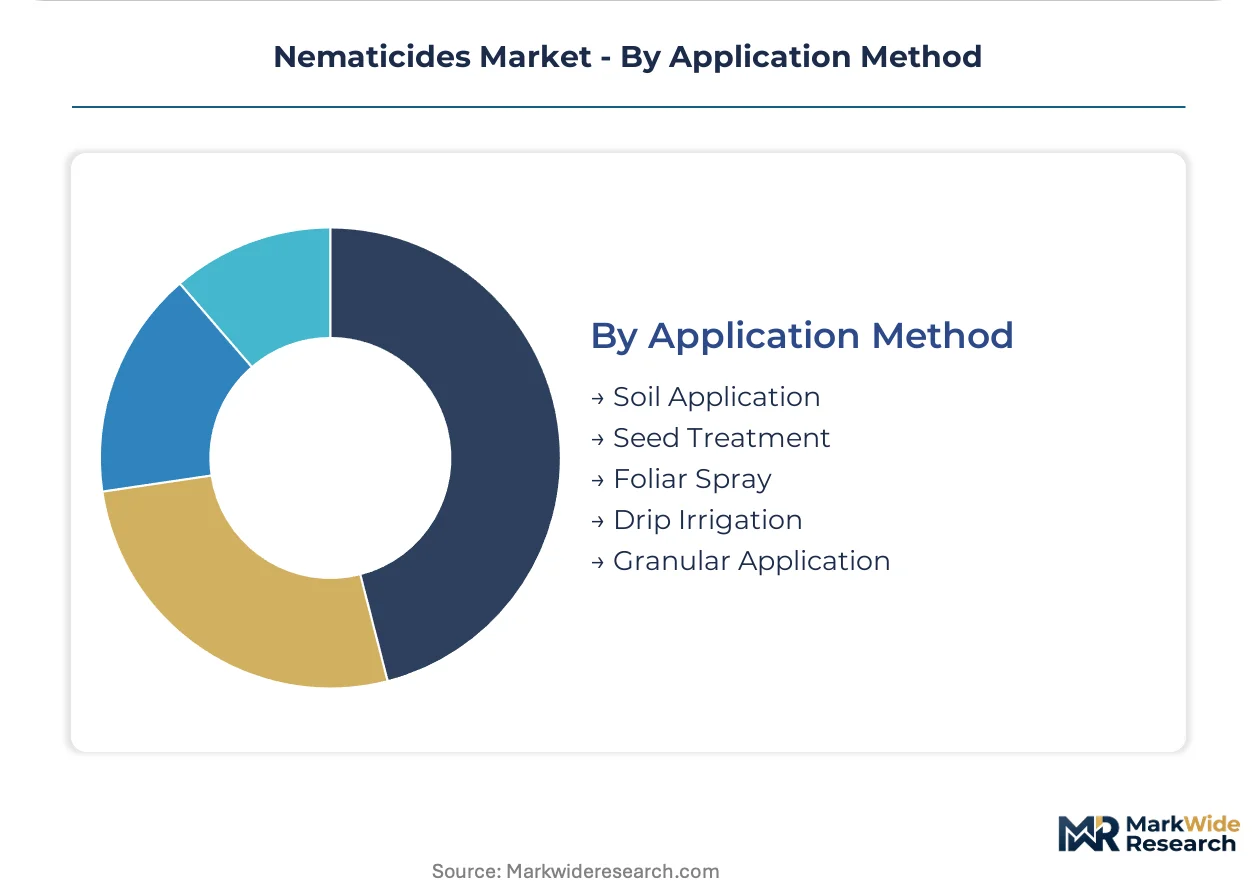
- Seed Treatment:Microencapsulated abamectin and biological inoculants applied directly to soybean and corn seed enable precision dosing with minimal environmental exposure. Brazilian rural credit cooperatives in Mato Grosso aggregate grower demand through direct-to-farm digital procurement platforms, bypassing traditional distribution channels.
- Drip Irrigation:Chemigation delivery of liquid nematicides through subsurface drip lines targets root zones in water-scarce orchard systems. Microencapsulation advances extend residual activity in coarse-textured soils, opening nematode control in drip-irrigated orchards previously deemed uneconomical.
- Soil Application:Pre-plant incorporation of liquids or granules into root zone profiles.
- Foliar Spray:Limited nematicide efficacy through leaf tissue drives niche use for stem nematode suppression.
- Granular Application:Broadcast or banded placement of clay-carrier formulations in row-crop establishment.
Soil application leads on scale; seed treatment leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting nematicide production toward jurisdictions with faster registration pathways and lower compliance costs. Manufacturers are relocating fermentation capacity for biological agents to India and expanding technical synthesis in China to serve price-sensitive export markets.
United States
Soybean cyst nematode pressure across the Corn Belt sustains seed-treatment demand. EPA FIFRA registration timelines compress for biological nematicides through the biopesticide division's expedited review pathway. Iowa and Illinois farm cooperatives aggregate procurement for abamectin-treated seed through direct-to-farm digital platforms.
Brazil
Mato Grosso and Rio Grande do Sul concentrate soybean cyst nematode management spending as resistant cultivars lose efficacy. ANVISA residue tolerance thresholds shape export-oriented product selection for China-bound shipments. Rural credit cooperatives in the Cerrado frontier bypass traditional distribution channels through aggregated digital procurement.
India
Maharashtra and Karnataka vegetable belts drive biological nematicide registration through Central Insecticides Board fast-track pathways for indigenous Trichoderma strains. The country's national agricultural regulator accelerates approvals for fermentation-derived products. Generic organophosphate manufacturers expand technical production for African and Southeast Asian export markets.
Spain
Andalusian and Murcian greenhouse clusters intensify Purpureocillium lilacinum adoption as EU F-Gas Regulation compresses soil fumigant availability. EFSA maximum residue limit tightening constrains synthetic options in export-oriented tomato and pepper systems. Almería province pilots RNA interference seed coatings to eliminate pre-plant fumigation delays.
China
Three manufacturers control over 70% of technical abamectin supply, creating concentration risk for global formulators. The Ministry of Ecology and Environment enforces dual carbon goals that constrain energy-intensive synthesis. Jiangsu and Zhejiang chemical parks expand fermentation capacity for biological nematicide intermediates.
Nematicides Market Key Industry Players
Swiss and German producers anchor the premium tier with integrated seed-and-crop-protection platforms; Indian and Chinese specialists hold the generic volume tier with technical manufacturing scale. The market structures around three strategic archetypes: multinational conglomerates bundling seed treatments, regional formulators serving price-sensitive export corridors, and biological specialists leveraging fast-track registration pathways. Dominant competitive moves include seed-coating convergence with biostimulant inoculants and backward integration into fermentation capacity.
Within the multinational tier, Syngenta and BASF SE exemplify integrated platform strategies. Bayer AG occupies a position in the North American corn-soy complex with concentrated synthetic formulations. Among Asia-Pacific-based specialists, Sumitomo Chemical represents the technical manufacturing archetype serving regional export markets.
| Leading Market Players |
|---|
| Syngenta |
| BASF SE |
| Bayer AG |
| Corteva |
| UPL |
| FMC Corporation |
| ADAMA Agricultural Solutions |
| Sumitomo Chemical |
| Nufarm |
| Others |
Cost & Logistics Intelligence
Abamectin technical price indices from Chinese chemical parks cascade through three distinct pricing tiers as formulators balance ANVISA residue compliance against Brazilian cooperative procurement leverage. Cost pass-through elasticity varies sharply between premium biological fermentation batches and generic organophosphate volumes.
Pricing Analysis
Distributor margin compression in Brazilian soybean belts is reshaping contract structures as rural credit cooperatives aggregate demand through direct-to-farm digital platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from Chinese export quota volatility on technical abamectin supply. Generic manufacturers face acute price sensitivity in African and Southeast Asian export corridors; integrated seed-and-crop-protection platforms command least sensitivity through bundled value propositions.
Supply Chain Analysis
Empty container repositioning and temperature-controlled return logistics for biological formulations add cost layers that synthetic producers avoid entirely. Technical abamectin supply concentrates in Jiangsu and Zhejiang chemical parks of China, with fermentation capacity expanding in India for biological intermediates. The chain draws from streptomyces fermentation biomass, petrochemical feedstocks, and specialized clay carriers. Single-source vulnerability concentrates in three Chinese manufacturers controlling majority technical supply. Distribution runs through multinational agrochemical distributors, regional formulators, and emerging direct-to-farm cooperative platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU REACH restriction timelines and Indian Central Insecticides Board fast-track pathways creates geographic production cost differentials exceeding formulation margin thresholds.
For Market Incumbents: Extend biological fermentation capacity into Maharashtra and Karnataka to capture Central Insecticides Board registration speed advantages before indigenous Trichoderma strains saturate local vegetable belts. Deepen backward integration into streptomyces culture collection banks to defend against Chinese technical supply disruption. Prioritize seed-coating convergence with biostimulant inoculants to lock Latin American cooperative procurement relationships.
For New Entrants and Emerging Players: RNA interference seed coating technology offers wedge positioning against fumigant-dependent greenhouse operators in Almería and Dutch clusters seeking pre-plant elimination. Target Moroccan and Egyptian export vegetable producers facing EFSA maximum residue limit compression for organophosphate alternatives. Pursue EPA biopesticide division expedited review pathway for Purpureocillium lilacinum strains to access organic-certified baby greens premium pricing.
For Investors and Strategic Acquirers: Asymmetric upside sits with biological specialists possessing captive fermentation capacity and fast-track registration relationships in India and the United States. The five-to-ten year viability window favors acquisition targets with validated dsRNA delivery platforms and established greenhouse pilot programs. Monitor EPA tolerance exemption expansions for biological nematicides in minor-use vegetables as inflection indicator for premium pricing sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Fermentation Capacity Expansion | Indian fast-track registration pathways reward local production with 12-18 month approval windows versus 36+ months for synthetics. |
| Seed-Coating Convergence with Biostimulants | Brazilian cooperatives seek input simplification through bundled nematicide-inoculant offerings on soybean seed. |
| RNA Interference Platform Development | Dutch and Spanish greenhouse pilots eliminate worker re-entry restrictions and pre-plant soil preparation delays. |
| Direct-to-Farm Digital Procurement Buildout | Mato Grosso rural credit cooperatives bypass traditional distributors, concentrating price leverage among organized producer groups. |
| Backward Integration into Technical Synthesis | Chinese dual carbon goals constrain energy-intensive abamectin production, favoring captive supply strategies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with crop protection managers at Syngenta and BASF SE, regulatory affairs leads at ANVISA and EPA, greenhouse operators in Almería, and procurement directors at Brazilian rural credit cooperatives with secondary validation through EPA FIFRA registration databases, EFSA maximum residue limit publications, ANVISA residue tolerance filings, and Central Insecticides Board approval records. Bottom-up acreage and application rate modeling triangulated against top-down manufacturer shipment data.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning chemical versus biological formulation type, root-knot versus cyst nematode target species, fruits and vegetables versus oilseeds and pulses crop categories, and seed treatment versus soil application delivery methods. CAGRs derived from regression against planted area trends, nematode pressure indices, and regulatory phase-out timelines incorporated ANVISA export tolerance thresholds and EU F-Gas Regulation compliance deadlines as structural constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese technical abamectin export quota disruptions and RNA interference regulatory approval trajectories in the European Union. Practitioners should monitor EFSA residue limit tightening schedules and EPA biopesticide division review queue lengths for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Crop Bactericides Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Global SDHI Fungicide Market
Crop Protection
Fogger Market
Crop Protection
North America Insecticide Market
Crop Protection
Europe Chemical Seed Treatment Market
Crop Protection
Corn Preemergence Herbicide Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Europe Insecticides Market
Crop Protection
South America Nematicides Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Global Aquatic Herbicides Market