
 Agricultural Spray Drone Market | 2026-2036
Agricultural Spray Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Spray Drone Market Insights
The EU Green Deal's Farm to Fork strategy is expanding regulatory pressure to cut chemical pesticide use by half, redirecting investment toward precision application technologies. DJI Agras leverages its manufacturing scale to dominate the multi-rotor segment across East Asian rice belts. Guardian Agriculture sustains its position through fixed-wing platforms designed for broad-acre row crops in North American operations. Yamaha anchors demand in Japan's aging agricultural workforce with automated flight systems that reduce operator fatigue during peak spraying windows.
Agricultural spray drones are unmanned aerial vehicles equipped with payload tanks, pressurized nozzles, and GPS-guided flight controllers, typically carrying ten to forty liters of liquid inputs per sortie. These systems deploy variable-rate application algorithms to deposit crop protection chemicals or nutrients with sub-meter accuracy, replacing ground-based sprayers and manned aircraft in terrain-sensitive or labor-scarce environments. Multi-rotor configurations lead current shipments due to lower capital thresholds and vertical takeoff flexibility, while hybrid platforms represent the fastest-expanding category as operators seek extended range for large-field operations. Pesticide application commands the dominant share of flight hours, though fertilization segments are capturing margin pools where drone-based urea spreading reduces soil compaction penalties.
FAA Part 107 waivers and EPA pesticide application certifications shape operational legality in the United States, while China's MEE enforces noise and chemical drift standards around populated rural settlements. EASA's specific category framework for unmanned aircraft governs spray operations across European member states, with CE marking required for commercial deployment. Stakeholders must monitor evolving beyond-visual-line-of-sight rules, as regulatory clarity on autonomous swarm spraying will determine whether capital continues flowing toward fleet-scale service models or remains anchored in single-unit ownership structures.
Market Dynamics
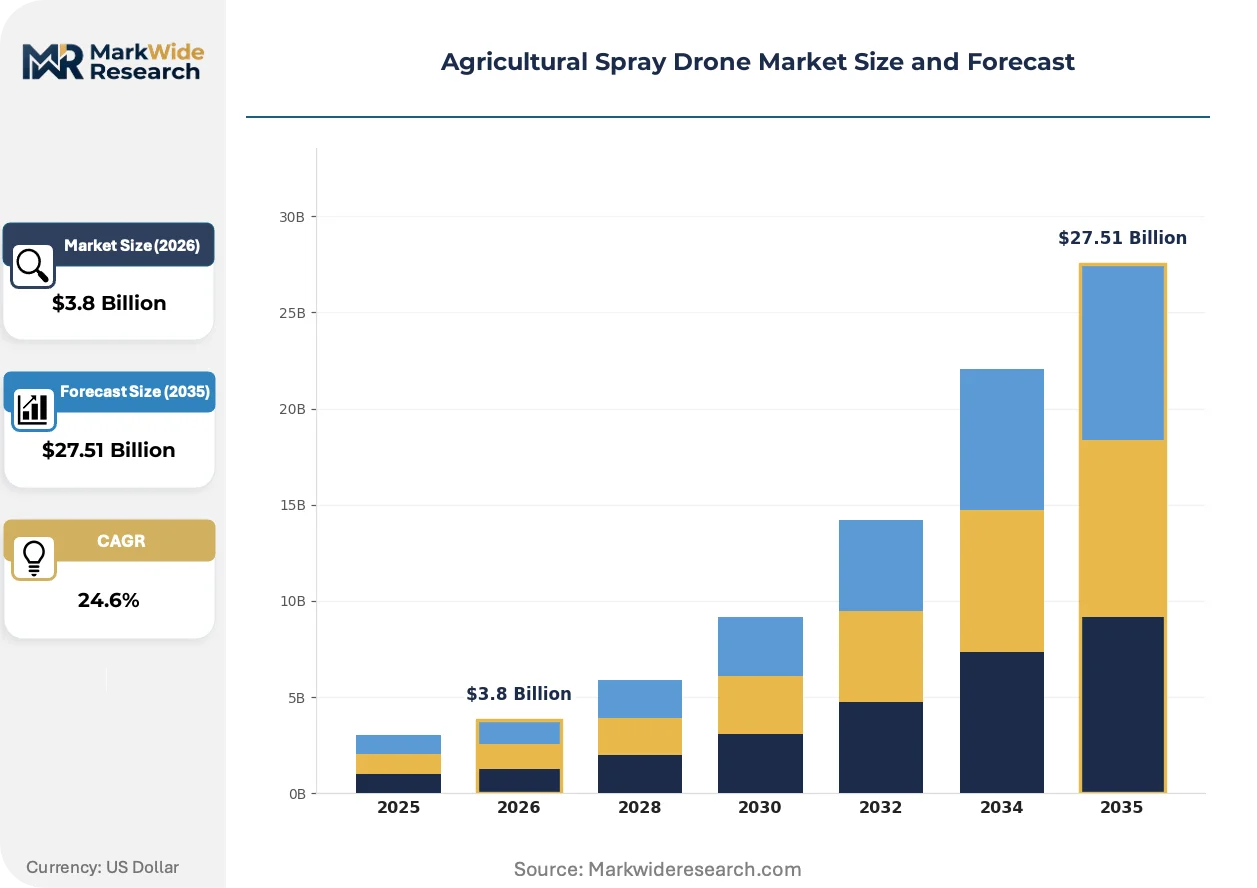
Precision agriculture adoption is compressing application windows and displacing ground-based sprayers as labor scarcity intensifies across major rice and wheat belts. Regulatory clarity on beyond-visual-line-of-sight operations now determines whether capital flows toward fleet-scale service models or remains locked in single-unit ownership structures.
Growth Catalysts
- EPA Part 107 waivers:The FAA's expanded certification pathways for agricultural pilots lower entry barriers for specialty crop growers across California's Central Valley.
- Variable-rate application algorithms:GPS-guided deposition systems achieve sub-meter accuracy, reducing chemical waste in terrain-sensitive orchards and vineyards.
- China's provincial subsidy schemes:Yangtze River Delta governments fund precision equipment procurement for rice and wheat cooperatives, accelerating fleet penetration.
Market Restraints
- Lithium battery cost volatility:Energy density requirements for extended-range hybrid platforms expose operators to raw material price swings in cobalt and nickel supply chains.
- Payload capacity ceilings:Current multi-rotor configurations max out at forty liters per sortie, forcing frequent return-to-base cycles on large-field operations.
- EASA specific category compliance:CE marking requirements and operational authorization timelines stretch deployment schedules for European service providers.
Strategic Opportunities
- EU Green Deal Farm to Fork mandate:The fifty percent pesticide reduction target redirects investment toward precision application technologies that minimize chemical drift.
- Fertilization segment expansion:Drone-based urea spreading reduces soil compaction penalties, opening margin pools in broad-acre row crop operations.
- Autonomous swarm coordination:Machine-to-machine communication protocols enable coordinated multi-unit spraying across contiguous fields without pilot redundancy.
Industry Challenges
- Part 107 remote pilot certification throughput:FAA examiner capacity constraints create backlogs during peak planting seasons when operator demand spikes.
- Legacy ground sprayer integration:Farm management software interoperability gaps force manual data reconciliation between aerial and terrestrial application logs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Spray Drone Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multi-Rotor Drones, Hybrid Drones, Single-Rotor Drones Crop Type: Cereals, Vegetables, Fruits, Cash Crops Application: Pesticide Application, Fertilization, Irrigation, Surveillance End User: Farmers, Agricultural Cooperatives, Crop Consultants, Agricultural Enterprises |
| Companies Covered | DJI Agras, Guardian Agriculture, Hylio, Parrot, Yamaha, XAG, ABZ Dronetech, Draganfly, EAVision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Spray Drone Market Trends and Innovations
Swarm intelligence and edge computing are redistributing operational control from centralized ground stations to airborne units. Three developments are compressing deployment cycles and reshaping competitive positioning.
Hybrid VTOL platforms are decentralizing flight planning authority by embedding real-time obstacle avoidance and dynamic route optimization directly on airframe processors. Large-field operators in Australia's wheat belt adopt these systems to eliminate base-station dependency during extended sorties. This architecture collapses infrastructure requirements for fleet-scale service providers.
China's MEE noise and chemical drift standards around populated rural settlements are forcing equipment redesigns with shrouded rotors and electrostatic nozzle systems. Manufacturers serving the Yangtze River Delta must recertify platforms under tightened environmental impact assessments. Domestic suppliers with established compliance pathways capture procurement contracts from subsidized cooperatives.
Service-based contracting is displacing equipment ownership among mid-scale specialty crop growers who lack capital for fleet acquisition or certified pilot retention. Third-party aerial application providers in California's Central Valley now bundle per-acre spraying with agronomic advisory. This model concentrates demand among vertically integrated service platforms with regulatory compliance infrastructure already in place.
Agricultural Spray Drone Market Segmentation
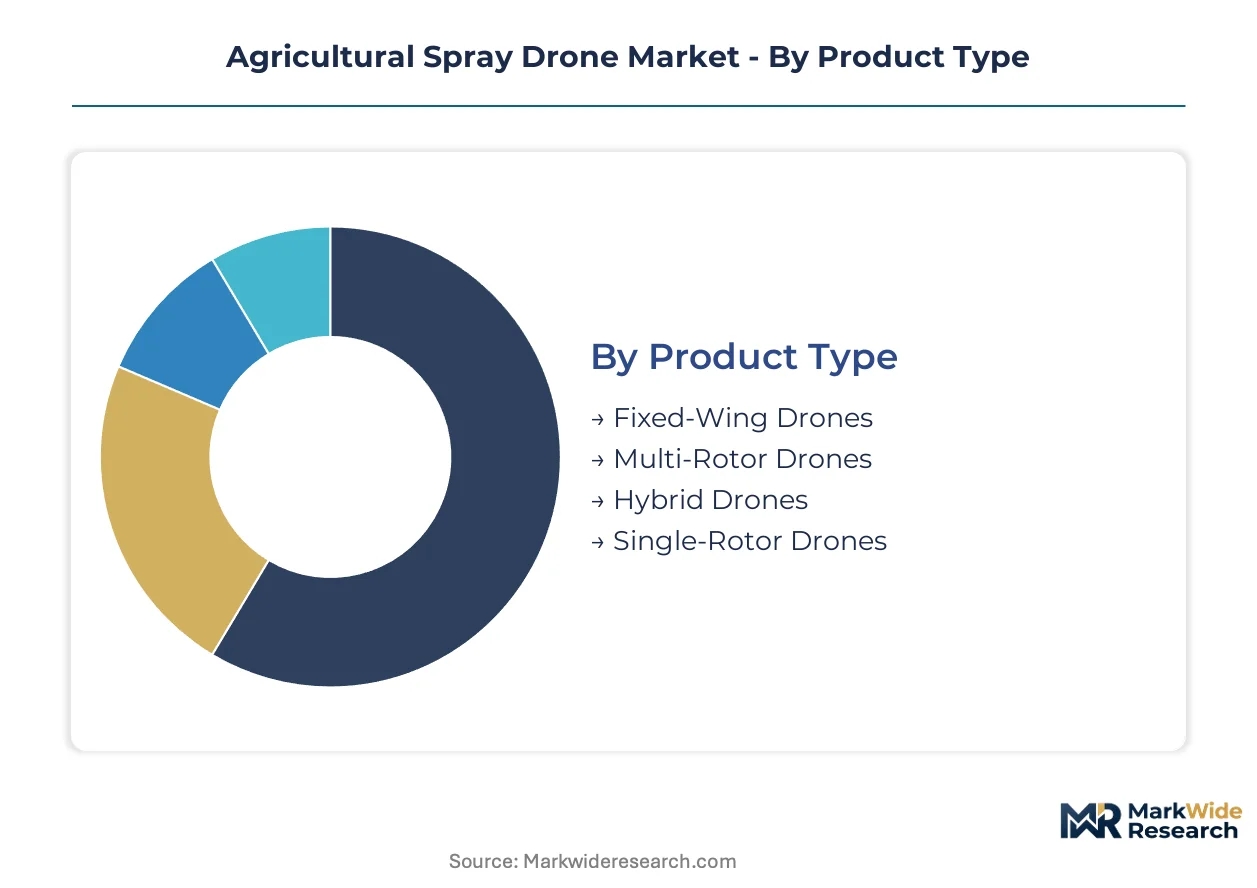
Equipment replacement cycles in agricultural aviation vary sharply by platform architecture and regional subsidy availability. Fleet operators prioritize payload efficiency and regulatory compliance pathways when segmenting procurement budgets across multi-rotor, fixed-wing, and hybrid configurations.
Product Type:
Upgrade decisions pivot on field geometry and sortie frequency, with operators in China's Yangtze River Delta subsidizing precision equipment refreshes every three to four seasons.
- Multi-Rotor Drones:Vertical takeoff capability eliminates runway infrastructure requirements. California specialty crop growers in the Central Valley deploy these platforms for vineyard canopy penetration where terrain sensitivity excludes ground-based sprayers.
- Hybrid Drones:VTOL architecture with fixed-wing cruise phases extends operational range beyond battery-only constraints. Australian wheat belt operators adopt these systems to collapse base-station dependency during extended contiguous-field sorties.
- Fixed-Wing Drones:Aerodynamic efficiency maximizes acreage per flight hour across broad-acre row crops.
- Single-Rotor Drones:Helicopter-style platforms dominate Japan's aging agricultural workforce with automated flight systems reducing operator fatigue.
Multi-rotor configurations sit at the top of the volume ranking, with hybrid platforms climbing the fastest.
Crop Type:
Application windows and chemical registration portfolios shape crop-specific fleet deployment, with rice and wheat cooperatives capturing provincial subsidy flows in East Asian procurement clusters.
- Cereals:Rice and wheat operations in China's subsidized procurement zones drive fleet-scale demand for standardized spray protocols across contiguous paddy fields.
- Fruits:Orchard canopy penetration requirements in California's Central Valley specialty crop zones concentrate variable-rate algorithm adoption.
- Vegetables:Shorter growth cycles and tighter pesticide residue limits demand precision timing in peri-urban supply zones.
- Cash Crops:Cotton and oilseed operations across broad-acre North American fields favor extended-range platforms with minimal pilot redundancy.
Cereals dominate current flight hours, with fruits expanding most quickly on precision agriculture margins.
Application:
Service revenue pools concentrate where drone operations displace legacy equipment categories, with fertilization segments opening margin pools through soil compaction avoidance.
- Pesticide Application:EPA Part 107 waivers and EPA pesticide certifications govern operational legality in the United States, with flight hours concentrated in chemical drift-sensitive terrain.
- Fertilization:Urea spreading via drone platforms eliminates ground compaction penalties in broad-acre row crop operations across Australia's wheat belt.
- Irrigation:Variable-rate water deposition targets moisture stress zones in precision agriculture deployments.
- Surveillance:Multispectral imaging for crop health monitoring extends platform utilization beyond spray windows.
Pesticide application commands the dominant share, with fertilization gaining share fastest on agronomic advisory bundling.
End User:
Capital availability and pilot certification infrastructure determine ownership-versus-contracting decisions, with service-based models displacing equipment acquisition among mid-scale operators.
- Agricultural Cooperatives:China's Yangtze River Delta rice and wheat collectives aggregate procurement volumes to capture provincial subsidy schemes for precision equipment.
- Agricultural Enterprises:Vertically integrated service platforms in California's Central Valley bundle per-acre spraying with regulatory compliance infrastructure.
- Farmers:Individual operators face FAA Part 107 examiner capacity constraints during peak planting season certification backlogs.
- Crop Consultants:Advisory-led service providers leverage flight data for agronomic prescription refinement.
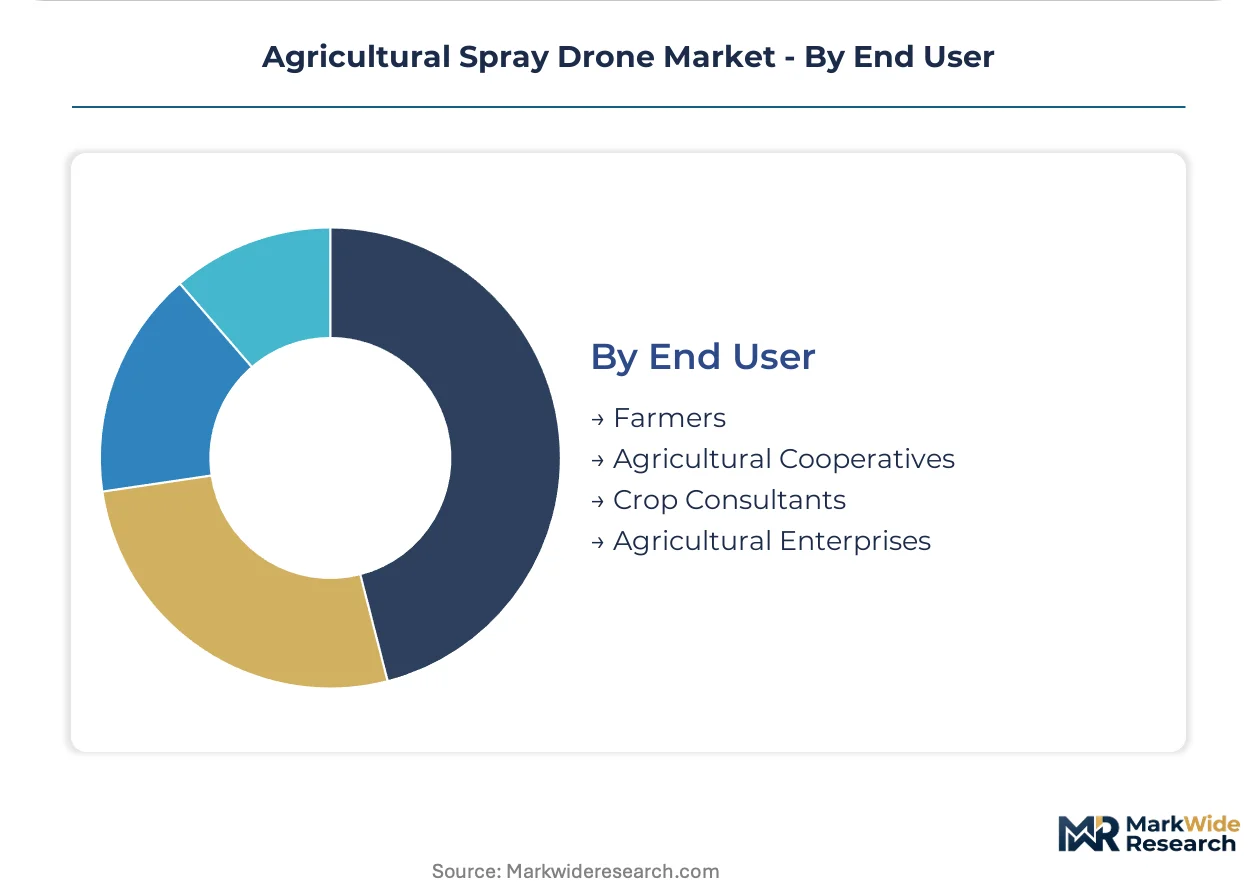
Agricultural cooperatives sit at the top of the volume ranking, with agricultural enterprises climbing the fastest on fleet-scale contracting expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural spray drone operations trace their commercial lineage to Japan's 1980s helicopter-based crop dusting automation, which seeded the precision application architectures now scaling across rice belts worldwide.
United States
California's Central Valley specialty crop zones drive variable-rate algorithm adoption for vineyard canopy penetration. FAA Part 107 waivers and EPA pesticide application certifications govern operational legality, with examiner capacity constraints creating certification backlogs during peak planting windows. Fresno County service providers bundle per-acre spraying with agronomic advisory to capture mid-scale growers lacking fleet capital.
China
Rice and wheat cooperatives in the Yangtze River Delta aggregate procurement volumes for subsidized precision equipment. MEE enforces noise and chemical drift standards around populated rural settlements, forcing equipment redesigns with shrouded rotors and electrostatic nozzle systems. Jiangsu Province manufacturers with established compliance pathways capture contracts from subsidized cooperatives.
Japan
An aging agricultural workforce sustains automated flight system demand to reduce operator fatigue during peak spraying windows. METI standards govern unmanned aerial vehicle certification for commercial agricultural deployment. Yamaha anchors demand in the Chubu region with helicopter-style platforms designed for automated rice paddy operations.
Australia
Wheat belt operators adopt hybrid VTOL platforms to eliminate base-station dependency during extended contiguous-field sorties. TGA-equivalent agricultural chemical registration frameworks govern aerial application legality. Queensland broad-acre row crop operations favor extended-range platforms with minimal pilot redundancy for urea spreading applications.
Germany
EASA's specific category framework for unmanned aircraft governs spray operations with CE marking required for commercial deployment. EU Green Deal Farm to Fork pesticide reduction mandates redirect investment toward precision application technologies. Bavarian precision agriculture equipment distributors face stretched operational authorization timelines stretching deployment schedules.
Agricultural Spray Drone Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance infrastructure and fleet-scale service bundling. The vendor base concentrates around multi-rotor specialists, fixed-wing broad-acre providers, and hybrid platform innovators. Three strategic archetypes dominate: vertically integrated service platforms, component-scale manufacturers, and advisory-led aerial application contractors. Competitive moves center on M&A for regulatory certification portfolios and strategic partnerships for agronomic data integration.
Within the manufacturing tier, DJI Agras and XAG represent the scale-driven archetype with established compliance pathways across East Asian rice belts. Guardian Agriculture occupies a position among North American fixed-wing specialists targeting broad-acre row crop operations. Yamaha exemplifies the automated flight systems segment with helicopter-style platforms serving Japan's aging agricultural workforce.
| Leading Market Players |
|---|
| DJI Agras |
| Guardian Agriculture |
| Hylio |
| Parrot |
| Yamaha |
| XAG |
| ABZ Dronetech |
| Draganfly |
| EAVision |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price indices cascade through agricultural spray drone manufacturing into three-tier pricing structures across premium, standard, and economy levels. Cobalt and nickel volatility in battery supply chains compresses margins at the mid-tier while premium-tier manufacturers absorb fluctuations through long-term offtake agreements.
Pricing Analysis
Per-unit transactional pricing dominates equipment sales, with certification grade and volume scale as primary differentiation drivers. Price erosion runs through the economy tier as Chinese manufacturers exploit provincial subsidy schemes to capture cooperative procurement volumes. Agricultural cooperatives in China's Yangtze River Delta exhibit highest price sensitivity, while vertically integrated service platforms in California's Central Valley prioritize regulatory compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium-ion cell manufacturers supplying the Yangtze River Delta assembly clusters. Raw material dependencies center on cobalt from the Democratic Republic of Congo, refined lithium from Chile and Australia, and rare earth magnets from China's Inner Mongolia processing facilities. Tariff exposure on finished aircraft components threatens North American service provider margins. Distribution runs through OEM-direct channels for fleet operators and agronomic advisory bundlers for mid-scale growers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural spray drone market functions as a stable compounder anchored by irreversible labor scarcity across major rice and wheat belts. Precision agriculture mandates from regulators worldwide ensure sustained equipment refresh cycles.
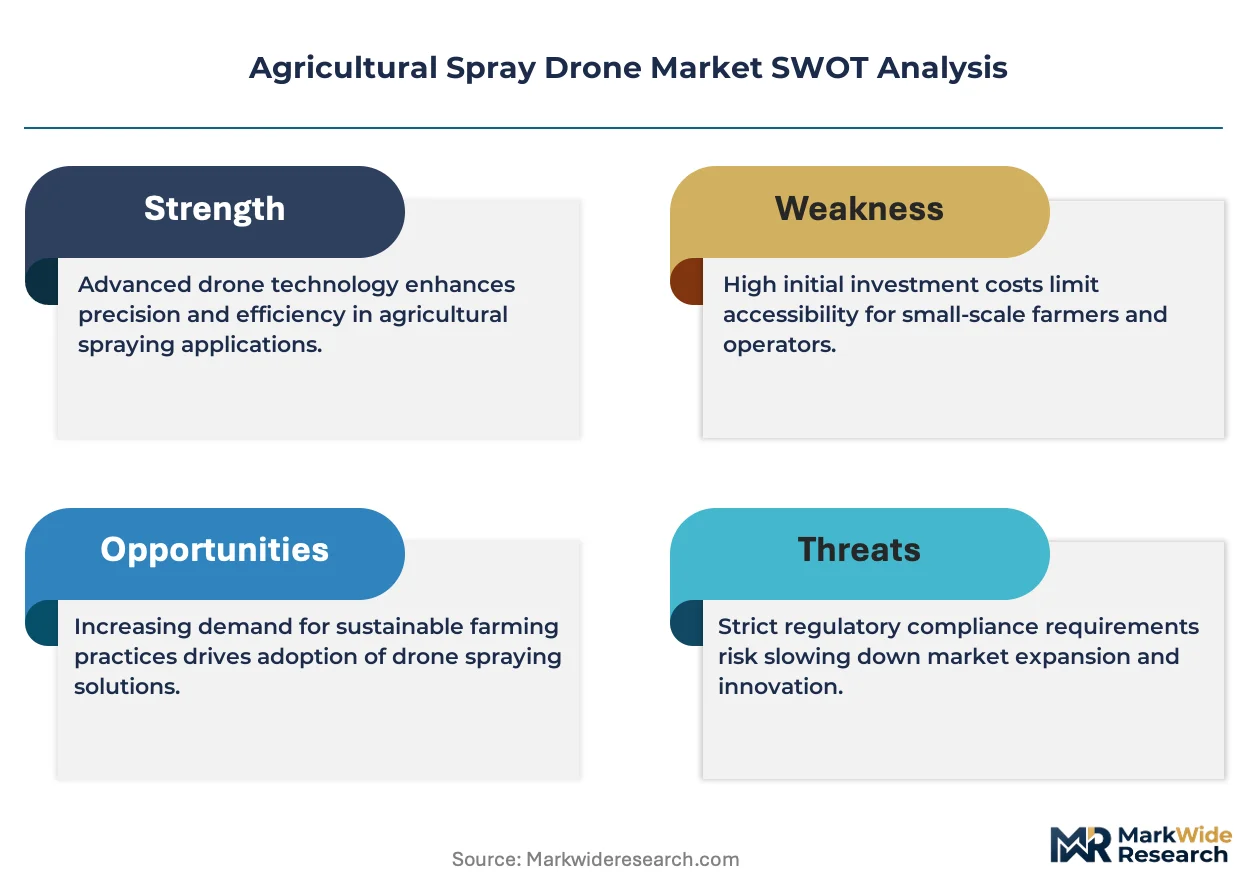
For Market Incumbents: To counter hybrid platform entrants from Australia's wheat belt, DJI Agras and XAG should deepen backward integration into lithium cell manufacturing and expand EPA Part 107 compliance infrastructure for California service provider certification backlogs. Captive battery supply secures cost advantage during raw material volatility.
For New Entrants and Emerging Players: Autonomous swarm coordination protocols offer a technology-first wedge into fertilization segments where drone-based urea spreading displaces ground compaction penalties. White-space targets include Queensland broad-acre row crop operations and European vineyard canopy penetration under EASA specific category frameworks. Go-to-market through agronomic advisory bundling captures price-insensitive specialty crop growers.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated service platforms possessing regulatory compliance infrastructure across multiple jurisdictions. Long-term viability hinges on beyond-visual-line-of-sight rule clarity enabling fleet-scale deployment. Acquisition targets include hybrid VTOL specialists with established MEE noise compliance pathways. Watch FAA examiner capacity expansion as inflection signal for US market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Portfolio Expansion | CE marking and EPA Part 107 infrastructure unlocks European and North American cooperative procurement. |
| Hybrid VTOL Platform Development | Extended-range architectures eliminate base-station dependency for Australian wheat belt operators. |
| Autonomous Swarm Coordination Investment | Machine-to-machine protocols enable coordinated multi-unit spraying without pilot redundancy. |
| Long-term Battery Supply Agreement | Cobalt and nickel offtake contracts insulate margins from raw material price volatility. |
| Agronomic Data Integration Partnership | Farm management software interoperability closes gaps between aerial and terrestrial application logs. |
Research Methodology
Direct dialogue with agricultural cooperative procurement managers, FAA-certified remote pilots, precision agriculture equipment distributors, and lithium battery supply chain specialists grounded the qualitative foundation. Secondary validation drew from EPA pesticide registration databases, FAA Part 107 waiver filings, EASA operational authorization records, and Chinese provincial subsidy disbursement reports. Bottom-up equipment shipment tallies and top-down agricultural aviation spend estimates were triangulated to anchor volume figures.
Segment-level outputs across the projection horizon reflect platform architecture, crop type, application method, and end-user ownership structure. CAGRs were derived from trend extrapolation of fleet penetration rates in subsidized procurement zones and replacement cycle compression in precision agriculture adoption clusters. Forecast inputs incorporated lithium carbonate price trajectory assumptions and evolving beyond-visual-line-of-sight regulatory clarity timelines.
The model holds under stable raw material supply conditions and progressive regulatory liberalization; deviation in battery chemistry disruptions or abrupt certification pathway restrictions would shift equipment refresh timing. Forecasts reflect documented assumptions about subsidy scheme continuity and pilot certification throughput capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
India Agricultural Tractor Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
Europe Utility Tractor Market
Agricultural Machinery
United States Agricultural Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Mexico Agricultural Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Brazil Agricultural Tractors Market