
 Critical Care Therapeutics Market | 2026-2036
Critical Care Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Therapeutics Market Analysis
Plasma-derived fractionation standards are unwinding competitive dynamics across the critical care landscape. Baxter International leverages its vertically integrated plasma collection network to sustain albumin and immunoglobulin supply security. Fresenius Kabi anchors European hospital contracts through centralized compounding and intravenous delivery specialization. Octapharma AG competes on fractionation yield efficiency, particularly in coagulation factor concentrates for trauma resuscitation.
Critical care therapeutics comprise pharmacological agents administered in life-threatening conditions requiring hemodynamic stabilization, sedation for mechanical ventilation, infection control, or organ support, typically formulated for immediate bioavailability via intravenous or inhalation routes with narrow therapeutic indices demanding continuous monitoring. These agents serve primarily to prevent multi-organ failure, reduce mortality in sepsis and cardiac arrest, and enable invasive procedures in intensive care settings. The analgesics and sedatives segment dominates current revenue as prolonged mechanical ventilation protocols expand across tertiary hospitals, while antimicrobial demand is accelerating fastest under stewardship mandates that prioritize targeted spectrum agents over broad-spectrum empiric therapy. Vasopressors concentrate margin pools where norepinephrine and vasopressin shortages have triggered supply security investments among hospital systems.
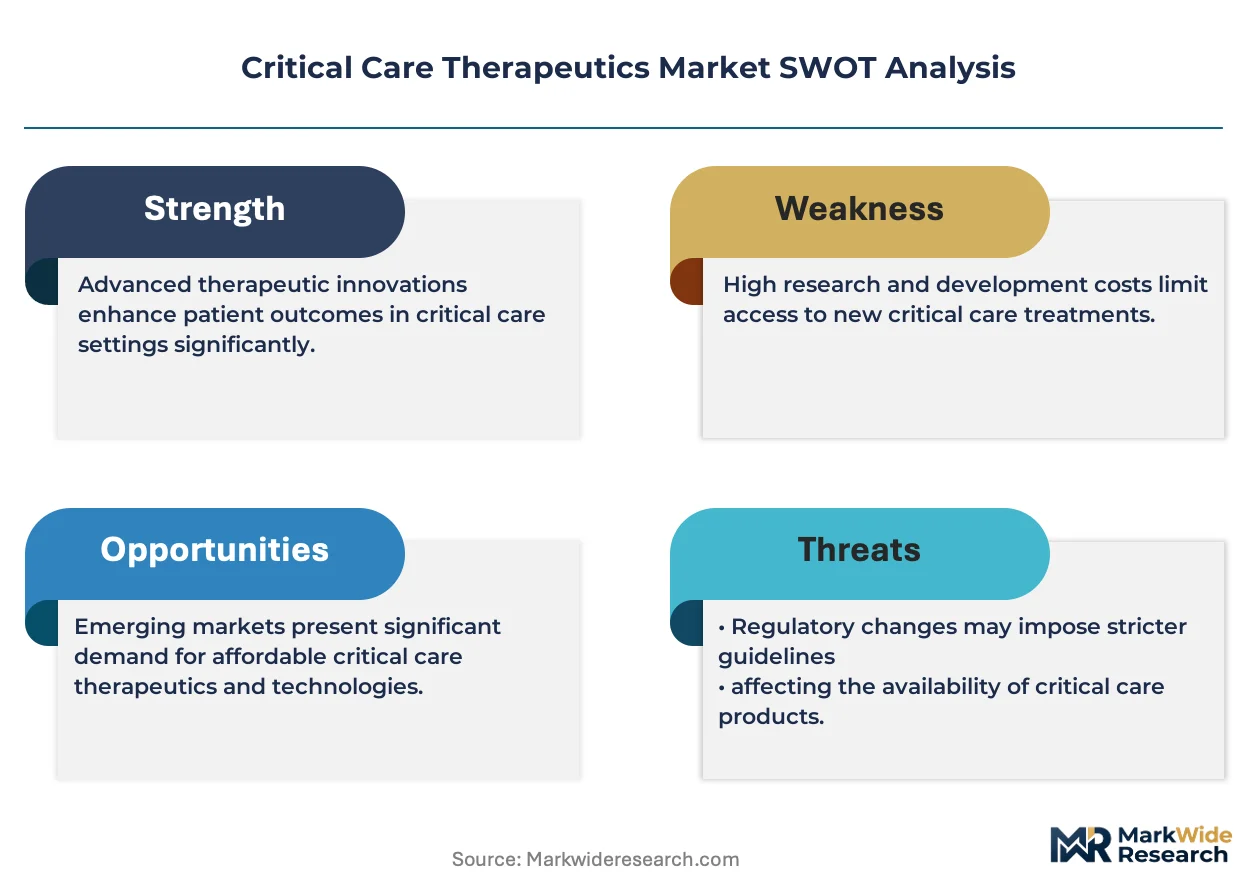
The FDA, EMA, and WHO pharmacovigilance frameworks collectively tighten manufacturing documentation, batch release testing, and post-market surveillance for parenteral critical care drugs, directly elevating compliance costs but also consolidating market access around GMP-certified producers. The FDA's antimicrobial stewardship requirements and EMA's good manufacturing practice inspections for plasma derivatives reshape procurement criteria toward suppliers with documented cold chain integrity and viral inactivation validation. Stakeholders must monitor evolving pharmacopeial standards for biosimilar sedatives and vasopressors, as regulatory convergence between FDA and EMA pathways will determine which manufacturers can scale across both markets without redundant clinical programs.
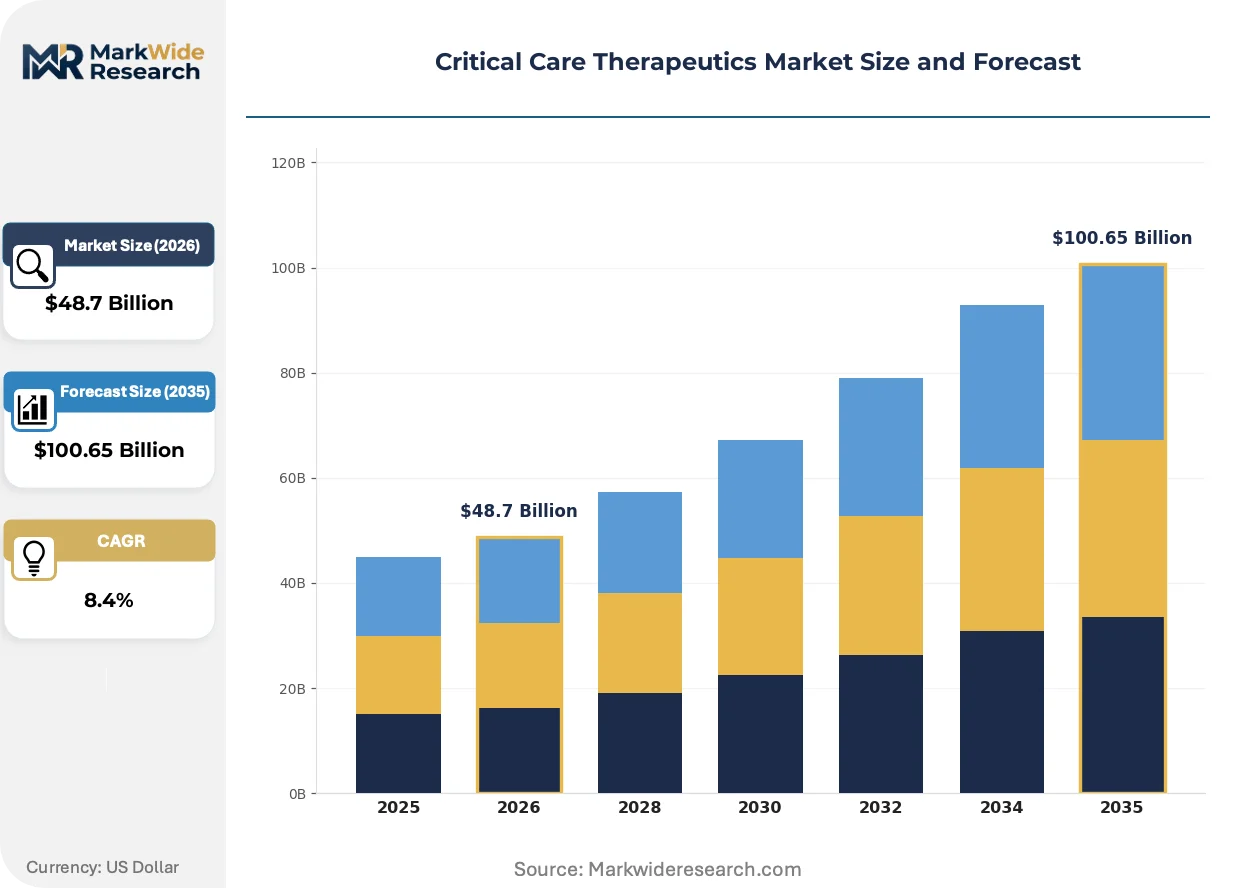
Market Dynamics
Plasma fractionation concentration among three dominant suppliers is compressing margin structures across albumin and immunoglobulin supply chains, while antimicrobial stewardship mandates reconfigure hospital formularies toward narrow-spectrum agents.
Growth Catalysts
- FDA Antimicrobial Stewardship Mandates:Acute care hospitals must implement prospective audit and feedback programs, accelerating demand for rapid diagnostic-guided therapy and targeted spectrum agents over empiric broad-spectrum use.
- Mechanical Ventilation Protocol Expansion:Tertiary hospitals in Germany and the United States are extending sedation-analgesia bundles for prolonged ventilation, driving volume in propofol, dexmedetomidine, and multimodal analgesia combinations.
- Vasopressor Supply Security Investments:Hospital systems are building strategic reserves of norepinephrine and vasopressin amid recurrent shortages, creating procurement consolidation around GMP-certified manufacturers with documented cold chain integrity.
Market Restraints
- Plasma Collection Bottleneck:Dependence on US-based donor centers and European collection networks limits immunoglobulin and albumin output expansion, with fractionation yield differentiating competitive positioning.
- EMA Viral Inactivation Documentation:Batch release testing requirements for plasma derivatives extend lead times and elevate compliance costs, disadvantaging smaller fractionators without integrated quality systems.
- Biosimilar Sedative Substitution:Patent expirations for midazolam and lorazepam enable lower-cost alternatives, compressing branded sedative margins in price-sensitive hospital systems.
Strategic Opportunities
- Centralized Compounding Services:Outsourced sterile preparation of patient-specific vasopressor and sedation infusions reduces pharmacy labor burden and medication error risk in high-acuity settings.
- Coagulation Factor Concentrate Trauma Protocols:Damage control resuscitation adoption in level-one trauma centers creates demand for fibrinogen concentrate and prothrombin complex concentrates with rapid reconstitution profiles.
- WHO Essential Medicines List Alignment:National procurement bodies are harmonizing critical care formularies with WHO recommendations, opening access pathways for prequalified norepinephrine and ketamine suppliers.
Industry Challenges
- Critical Care Pharmacist Workforce Scarcity:Specialized training programs for sedation protocol management and antimicrobial stewardship outpace graduation rates, constraining stewardship program expansion.
- Multi-Modal Infusion Pump Integration:Legacy device fleets lack interoperability with electronic health record systems and smart pump libraries, complicating closed-loop sedation and vasopressor titration implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Therapeutics Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Sedatives, Antimicrobials, Vasopressors Application: Trauma Care, Cardiac Arrest, Sepsis Management, Respiratory Failure End User: ICU, Emergency Department, Surgical Unit, Recovery Room Delivery Mode: Intravenous, Inhalation, Oral, Subcutaneous |
| Companies Covered | Octapharma AG, Baxter International, Shire plc, Bio Products Laboratory, Biotest AG, Kedrion S.p.A, Shanghai RAAS, Fresenius Kabi, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Therapeutics Market Emerging Trajectories
Real-time therapeutic drug monitoring and algorithm-driven dosing are displacing weight-based empiric protocols across mechanical ventilation and sepsis management, compressing adverse event rates and length of stay.
Closed-loop sedation systems integrating bispectral index monitoring with automated propofol infusion are supplanting manual nurse-driven titration in US academic medical centers. Anesthesiology and critical care departments at institutions including Mayo Clinic and Cleveland Clinic have piloted these platforms for post-operative ventilation weaning. The technology is enabling standardized sedation depth targets while reducing propofol consumption variability and associated delirium incidence.
EMA's 2023 revision to good manufacturing practice Annex 1 for sterile medicinal products mandates enhanced environmental monitoring and barrier technology for parenteral critical care drug production. Manufacturers must upgrade filling lines and isolator technology or exit the European supply base. Plasma derivative and small-molecule injectable producers with existing barrier isolator investments are capturing contract manufacturing organization opportunities from facilities requiring capital-intensive retrofits.
Hospital purchasing cooperatives are consolidating annual sedation, analgesia, and vasopressor contracts under single-source or dual-source arrangements with penalty clauses for supply interruption. HealthTrust, Premier, and Vizient in the United States have shifted from multi-vendor spot purchasing to multi-year agreements with guaranteed volume commitments and price protection mechanisms. This concentration is most advanced in cardiac surgery and neurocritical care service lines where protocol standardization reduces formulary complexity.
Critical Care Therapeutics Market Segmentation
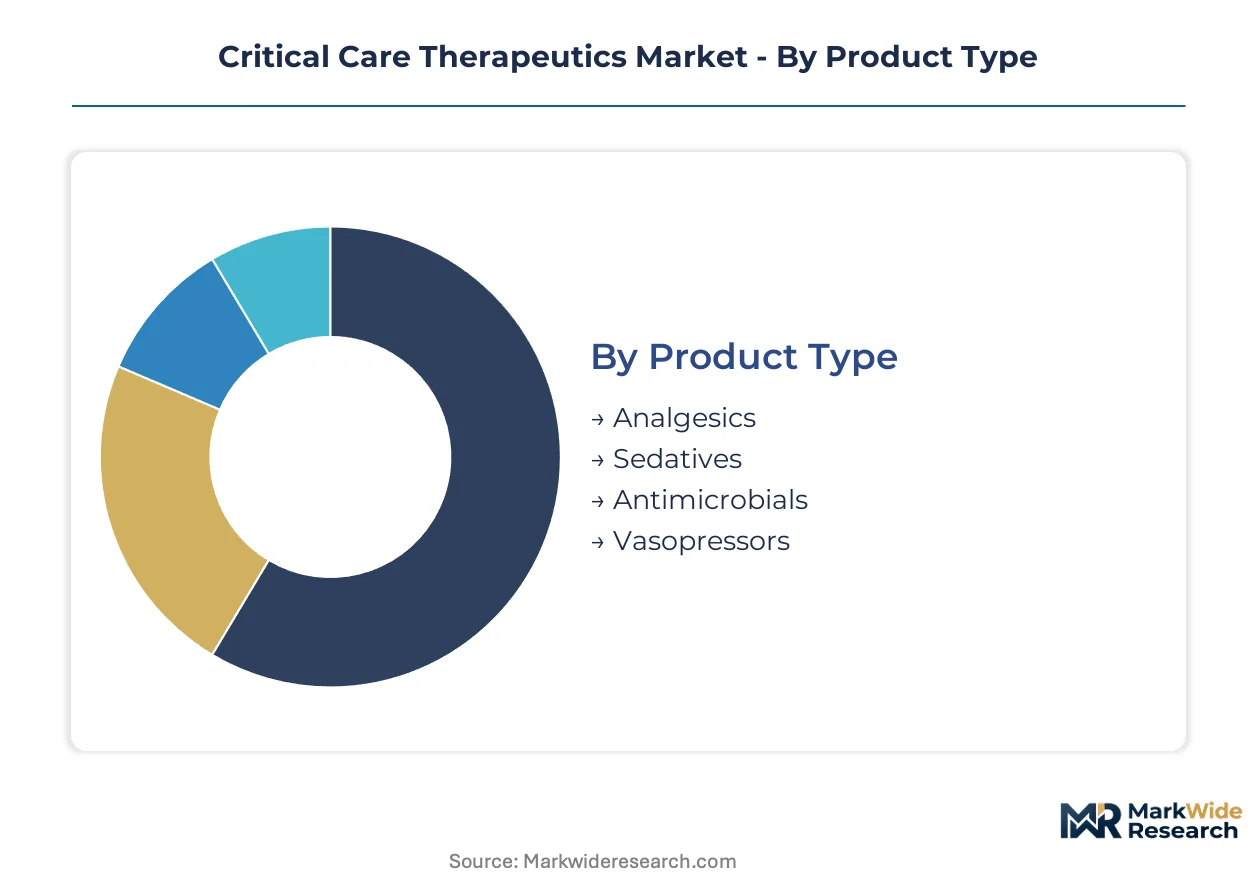
Critical care therapeutics demand diverges sharply across clinical settings, with regulatory pathways and reimbursement structures determining commercial viability for each product configuration. Segmentation reveals where formulation investments concentrate and which delivery innovations command premium positioning.
Product Type:
FDA antimicrobial stewardship mandates and EMA plasma derivative standards create divergent compliance burdens across pharmacological categories.
- Analgesics:Opioid and non-opioid formulations for acute pain control in mechanically ventilated patients. Demand clusters in US academic medical centers implementing multimodal analgesia protocols to reduce opioid exposure and delirium incidence.
- Sedatives:Propofol, dexmedetomidine, and benzodiazepine formulations enabling controlled consciousness reduction for invasive procedures. German university hospital networks are standardizing sedation bundles for prolonged ventilation, driving volume in target-controlled infusion compatibility.
- Antimicrobials:Narrow-spectrum antibacterial and antifungal agents aligned with stewardship requirements. Stewardship audit mandates in US acute care hospitals accelerate rapid diagnostic-guided therapy adoption.
- Vasopressors:Catecholamine and non-catecholamine agents for hemodynamic stabilization in shock states. Supply security investments among hospital systems concentrate procurement around cold chain-validated manufacturers.
Established volume favors sedatives; emerging adoption favors antimicrobials under stewardship alignment.
Application:
Clinical outcome metrics and length-of-stay incentives reconfigure therapeutic priorities across emergency scenarios.
- Trauma Care:Coagulation factor concentrates and massive transfusion protocols for hemorrhage control. Level-one trauma centers in the United States adopt damage control resuscitation with fibrinogen concentrate and prothrombin complex concentrates.
- Cardiac Arrest:Vasopressor cocktails and antiarrhythmic agents for return of spontaneous circulation. Post-cardiac arrest care in tertiary hospitals drives demand for targeted temperature management compatibility.
- Sepsis Management:Antimicrobial stewardship-aligned agents with pharmacokinetic optimization for organ dysfunction. Hour-1 bundle compliance requirements in US emergency departments compress empiric therapy decision windows.
- Respiratory Failure:Sedation-analgesia combinations enabling lung-protective ventilation and prone positioning. Prolonged ventilation protocols in German ICUs expand multimodal sedation depth targeting.
Sepsis management commands the steepest expansion trajectory as stewardship mandates tighten; trauma care anchors margin concentration through coagulation product premiumization.
End User:
Staffing models and protocol standardization maturity determine formulary complexity tolerance across care environments.
- ICU:Highest-acuity setting requiring continuous infusion capability and therapeutic drug monitoring integration. Closed-loop sedation systems pilot at Mayo Clinic and Cleveland Clinic target this environment for algorithm-driven propofol delivery.
- Emergency Department:Time-compressed decision environment favoring prefilled syringes and weight-based dosing aids. Antimicrobial stewardship hour-1 bundle compliance drives rapid diagnostic coupling.
- Surgical Unit:Perioperative anesthesia and post-operative ventilation weaning requirements. Standardized sedation depth targets reduce emergence delirium in cardiac surgery service lines.
- Recovery Room:Post-anesthesia care with multimodal analgesia transition protocols. HealthTrust and Premier purchasing cooperatives consolidate contracts across this and surgical units.
ICU concentration sustains premium pricing; emergency department volume expands fastest through stewardship mandate penetration.
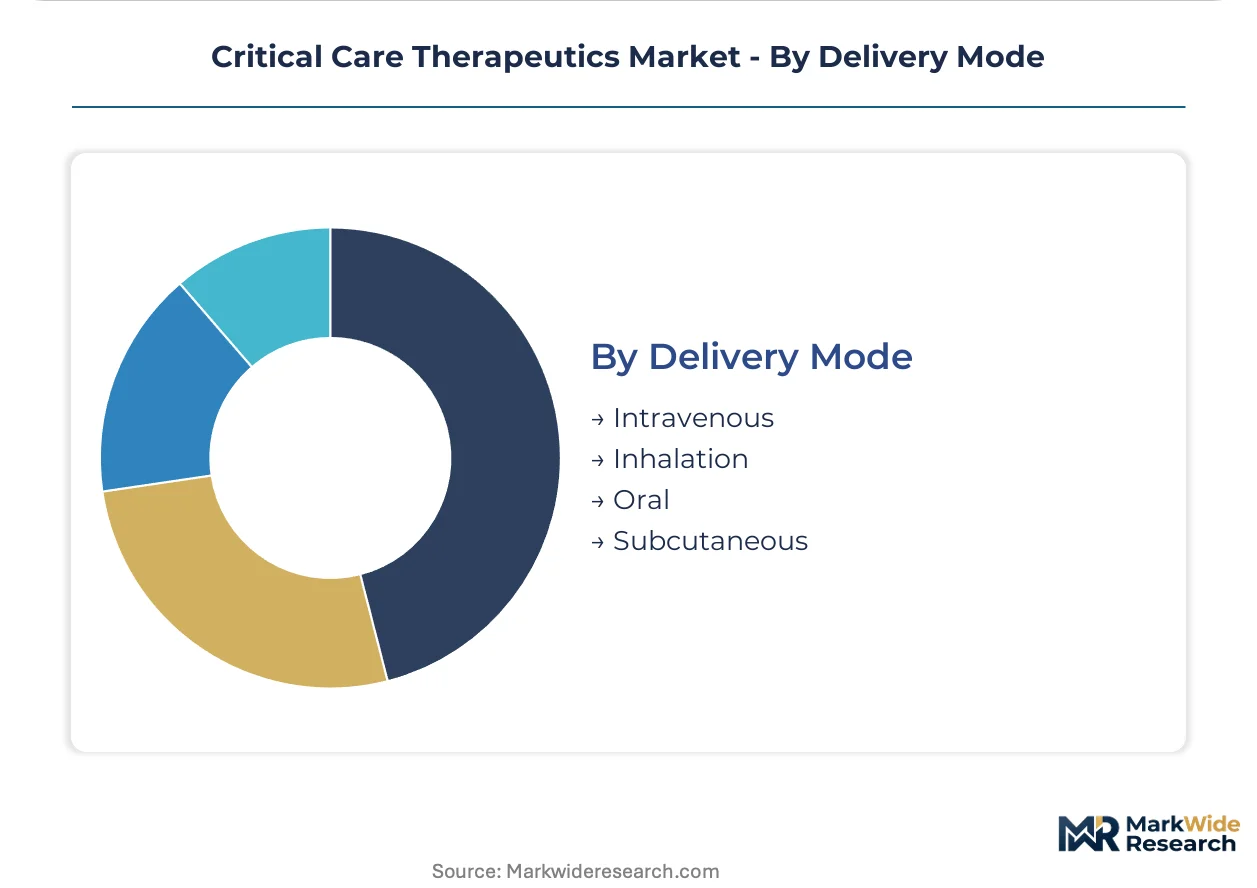
Delivery Mode:
EMA Annex 1 sterile manufacturing standards and device interoperability requirements reshape viable administration pathways.
- Intravenous:Primary route for critical care bioavailability with narrow therapeutic indices. Barrier isolator investments separate GMP-certified producers from facilities requiring capital-intensive retrofits.
- Inhalation:Aerosolized antimicrobial and bronchodilator delivery for respiratory failure. Ventilator-compatible nebulization systems concentrate demand in academic medical center ICUs.
- Oral:Transition and enteral administration for sedation weaning and antimicrobial step-down. Bioavailability constraints limit acute critical care application.
- Subcutaneous:Alternative vascular access for select analgesic and anticoagulant agents. Peripheral administration reduces central line complications in prolonged ICU stays.
Intravenous dominance persists through therapeutic index requirements; inhalation gains share fastest via ventilator-integrated delivery innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in Germany demonstrate the lowest price elasticity for critical care therapeutics, while procurement bodies in India and Brazil prioritize cost containment over formulation sophistication. This demand-elasticity contrast shapes where premium plasma derivatives versus biosimilar sedatives gain traction.
United States
Academic medical centers at Mayo Clinic and Cleveland Clinic pilot closed-loop sedation systems for mechanical ventilation weaning. FDA antimicrobial stewardship mandates compel acute care hospitals to implement prospective audit programs. HealthTrust and Premier purchasing cooperatives consolidate multi-year contracts with guaranteed volume commitments across cardiac surgery service lines.
Germany
University hospital networks standardize sedation-analgesia bundles for prolonged ventilation protocols. EMA good manufacturing practice inspections for plasma derivatives elevate compliance thresholds for albumin and immunoglobulin suppliers. The Rhine-Ruhr metropolitan region concentrates fractionation capacity where manufacturers compete on viral inactivation documentation.
China
Shanghai RAAS anchors domestic plasma collection networks serving tertiary hospital ICU expansion. The national pharmaceutical regulator tightens sterile manufacturing standards for parenteral critical care drugs. Yangtze River Delta medical centers adopt damage control resuscitation protocols with fibrinogen concentrate for trauma care.
India
Central government procurement bodies harmonize critical care formularies with WHO Essential Medicines List recommendations. CDSCO prequalification pathways accelerate market access for norepinephrine and ketamine suppliers. Maharashtra and Gujarat hospital networks concentrate demand for cost-optimized sedation and vasopressor agents.
Switzerland
Swissmedic batch release testing requirements extend lead times for plasma derivative imports from non-EU fractionators. University hospitals in Zurich and Geneva standardize coagulation factor concentrate protocols for trauma resuscitation. The Basel pharmaceutical cluster hosts manufacturers with barrier isolator investments capturing contract manufacturing opportunities from facilities requiring EMA Annex 1 retrofits.
Critical Care Therapeutics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the critical care therapeutics landscape. Plasma fractionation concentration among three dominant suppliers compresses margin structures for albumin and immunoglobulin, while antimicrobial stewardship mandates fragment antimicrobial procurement around rapid diagnostic compatibility. The competitive terrain separates vertically integrated plasma collectors, centralized compounding specialists, and biosimilar sedative manufacturers. Dominant competitive moves include backward integration into plasma collection networks and strategic partnerships for sterile compounding capacity.
Among European plasma fractionators, Octapharma AG and Biotest AG occupy positions emphasizing yield efficiency in coagulation factor concentrates. Baxter International exemplifies the vertically integrated archetype with captive control over albumin and immunoglobulin supply security. Fresenius Kabi anchors European hospital contracts through intravenous delivery specialization and centralized compounding services.
| Leading Market Players |
|---|
| Octapharma AG |
| Baxter International |
| Shire plc |
| Bio Products Laboratory |
| Biotest AG |
| Kedrion S.p.A |
| Shanghai RAAS |
| Fresenius Kabi |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake contracts with guaranteed volume commitments and price protection mechanisms lock in supply access for hospital purchasing cooperatives while compressing spot-market visibility for acute care therapeutics. HealthTrust and Premier in the United States have shifted procurement toward these structures, binding cardiac surgery and neurocritical care service lines to GMP-certified manufacturers with documented cold chain integrity.
Pricing Analysis
FDA antimicrobial stewardship mandates and EMA good manufacturing practice inspections dictate the pricing tier structure across critical care therapeutics. Three-tier pricing separates GMP-certified plasma derivatives with viral inactivation validation from standard sterile injectables and cost-optimized biosimilar sedatives. Price differentiation hinges on batch release documentation depth and after-sales technical support for infusion pump integration. Cost compression in the biosimilar sedative tier is intensifying because patent expirations for midazolam and lorazepam enable lower-cost substitution. Hospital systems in India and Brazil exhibit highest price sensitivity, while German university hospital networks demonstrate lowest elasticity for premium coagulation factor concentrates.
Supply Chain Analysis
Strategic stockpile preferences dominate vasopressor procurement amid recurrent norepinephrine and vasopressin shortages, while just-in-time inventory management persists for sedatives with stable manufacturing throughput. Plasma fractionation concentrates in the United States, Germany, and Switzerland, with Baxter International and Octapharma AG anchoring supply security through captive collection networks. Raw material dependencies rest on US-based donor plasma, European fractionation capacity, and specialized barrier isolator equipment for sterile fill-finish operations. Single-source vulnerability runs through concentrated plasma collection geography. Distribution feeds from fractionation facilities through hospital purchasing cooperatives and centralized compounding services to acute care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Critical care therapeutics sit in early-cycle expansion as closed-loop sedation systems and antimicrobial stewardship mandates penetrate academic medical centers, with mechanical ventilation protocol standardization extending addressable demand across tertiary hospital networks.
For Market Incumbents: Fortify plasma collection network control and barrier isolator manufacturing capacity to defend against biosimilar substitution pressure and EMA Annex 1 compliance escalation. Baxter International's vertically integrated donor center model and Fresenius Kabi's centralized compounding specialization demonstrate defensible positioning. Prioritize certification investment in viral inactivation documentation to maintain European hospital contract access.
For New Entrants and Emerging Players: Centralized sterile compounding service gaps in mid-tier hospital systems offer white-space entry points where incumbent logistics networks under-serve regional acute care facilities. Target emergency department rapid diagnostic coupling for antimicrobial stewardship compliance, where hour-1 bundle mandates outpace specialized pharmacist workforce availability. Pursue hospital system partnership go-to-market angles with prefilled syringe and weight-based dosing aid configurations.
For Investors and Strategic Acquirers: Regional plasma fractionators with yield efficiency technology and underdeveloped collection network infrastructure represent compelling acquisition targets for portfolio expansion. Long-term viability hinges on regulatory convergence between FDA and EMA pathways enabling scalable cross-market access without redundant clinical investment. Watch EMA Annex 1 retrofit capital requirements as inflection indicator for contract manufacturing organization opportunity capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive donor center control secures albumin and immunoglobulin supply security against collection bottlenecks. |
| Barrier Isolator Technology Upgrade | EMA Annex 1 compliance separates GMP-certified producers from facilities requiring capital-intensive retrofits. |
| Centralized Compounding Service Partnership | Outsourced sterile preparation reduces pharmacy labor burden and medication error risk in high-acuity ICUs. |
| Rapid Diagnostic Coupling Development | Stewardship audit mandates accelerate demand for diagnostic-guided therapy and targeted spectrum agents. |
| Closed-Loop Sedation System Integration | Algorithm-driven propofol delivery at Mayo Clinic and Cleveland Clinic reduces consumption variability and delirium incidence. |
Methodological Framework
A spread of perspectives from critical care pharmacists, hospital procurement managers, plasma fractionation executives, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary interviews with formulary directors at German university hospital networks and GPO contracts managers at HealthTrust and Premier validated demand concentration patterns. Secondary sources included FDA guidance documents, EMA inspection records, hospital procurement databases, and plasma derivative batch release testing protocols. Bottom-up therapeutic category volume estimates triangulated against top-down hospital spending data.
Segmentation dimensions modeled span product type, application, end user, and delivery mode, with regional regulatory cluster as an additional analytical layer. Value projections across the analysis window derive from price-volume elasticity assumptions by geography and therapeutic index requirements. CAGRs were computed from base-year market sizing through terminal-year penetration scenarios. Forecast inputs incorporated mechanical ventilation protocol expansion rates and antimicrobial stewardship mandate implementation timelines.
Forecasts assume regulatory continuity in FDA antimicrobial stewardship requirements and EMA good manufacturing practice enforcement; material policy shifts would require re-modeling supply security investment trajectories and plasma derivative compliance thresholds. Revision becomes warranted when plasma collection yield efficiency or closed-loop sedation system adoption crosses institutional penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Memory-Enhancing Drugs Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Intranasal Corticosteroids Market