
 Metastatic Cancer Treatment Drug Market | 2026-2036
Metastatic Cancer Treatment Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Metastatic Cancer Treatment Drug Market Insights
FDA Breakthrough Therapy designation is reorganizing competitive entry timelines for late-stage pipeline assets. Bristol Myers Squibb Company leverages its integrated immuno-oncology manufacturing network to sustain checkpoint inhibitor supply security. Merck & Co., Inc. anchors its position through deep clinical trial investment in first-line metastatic indications. Novartis AG differentiates via radioligand therapy production capabilities that occupy a narrow but expanding therapeutic niche.
Metastatic cancer treatment drugs comprise systemic therapeutic agents engineered to interrupt tumor proliferation, angiogenesis, or immune evasion across disseminated disease sites, with molecular specificity ranging from cytotoxic small molecules to monoclonal antibodies and cell-based biologics requiring cold-chain distribution. These agents serve the essential clinical purpose of extending survival and preserving quality of life in patients with distant metastases where localized intervention fails. Immunotherapy now leads value generation within drug type segmentation as checkpoint and CAR-T modalities command premium pricing and widening label expansions. Intravenous delivery mode retains structural dominance in hospital infusion centers, though subcutaneous formulations represent the fastest-growing administration category by reducing treatment burden and chair time. Breast cancer and lung cancer therapy areas concentrate the largest patient pools and corresponding reimbursement investment.
FDA, EMA, and NMPA collectively govern market access through divergent evidentiary standards for accelerated approval, post-marketing confirmatory trial requirements, and manufacturing inspection protocols that shape regional launch sequencing. The FDA's Project Confirm initiative tightens withdrawal mechanisms for therapies failing to verify clinical benefit, while China's NMPA innovation review pathways compress timeline gaps with Western regulators. Stakeholders must monitor evolving overall survival endpoint requirements and biosimilar competition intensity across the major oncology markets to calibrate portfolio prioritization and geographic resource allocation.
Market Dynamics
FDA's Project Confirm initiative is tightening post-marketing verification requirements for accelerated approvals, forcing manufacturers to front-load confirmatory trial investment and compressing the commercialization window for metastatic oncology assets.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review pathway compresses regulatory timelines for first-in-class immuno-oncology agents, enabling earlier patient access and faster revenue recognition.
- Academic Medical Center Expansion:Oncology departments at major teaching hospitals are scaling combination protocol adoption, creating concentrated demand centers for multi-agent regimens.
- Radioligand Production Infrastructure:Novartis AG's manufacturing network for targeted radiotherapy is de-risking supply constraints that previously limited patient eligibility for precision nuclear medicine.
Market Restraints
- Biologic Cold-Chain Costs:CAR-T and monoclonal antibody distribution requires liquid nitrogen logistics that inflate per-dose delivery expenses by 15-25% versus small molecules.
- Confirmatory Trial Failure Risk:FDA's enhanced withdrawal authority under Project Confirm threatens revenue streams for therapies that fail to verify clinical benefit in post-marketing studies.
- Reimbursement Concentration:Medicare's dominance in US oncology payment creates single-payer vulnerability for pricing negotiations affecting 60% of metastatic cancer patients.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered checkpoint inhibitors reduce infusion center burden and expand addressable patient populations beyond hospital-centric delivery.
- NMPA Innovation Pathways:China's compressed review timelines for novel oncology therapies enable launch sequencing that narrows historical gaps with Western market entry.
- Biosimilar Manufacturing Partnerships:Contract development organizations with mammalian cell culture expertise offer capacity arbitrage for mid-stage biologics facing patent expiry.
Industry Challenges
- Immuno-Oncology Talent Scarcity:Clinical development teams with cell therapy manufacturing experience command premium compensation that strains R&D budgets.
- Multi-Regional Inspection Coordination:Simultaneous FDA, EMA, and NMPA facility audits require dedicated quality infrastructure that delays product release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metastatic Cancer Treatment Drug Market |
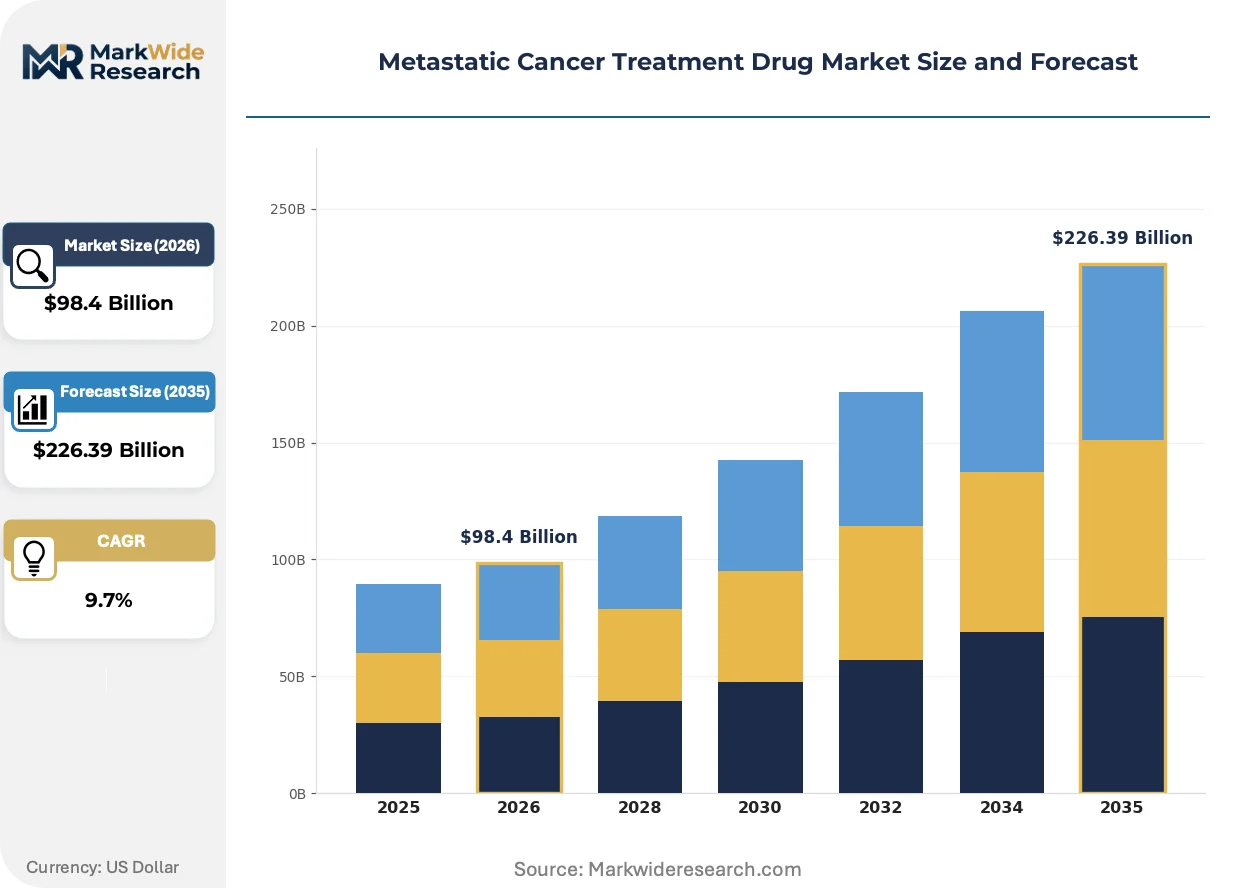
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $226.39 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Urothelial Carcinoma End User: Hospitals, Clinics, Homecare, Research Facilities |
| Companies Covered | Bristol Myers Squibb Company, Merck & Co., Inc., Johnson & Johnson, Novartis AG, F. Hoffmann-La Roche Ltd, AstraZeneca PLC, Pfizer, Inc., Eli Lilly and Company, Amgen, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metastatic Cancer Treatment Drug Market Trends and Innovations
Combination therapy protocols are fragmenting the historical dominance of single-agent chemotherapy, while manufacturing scale-up for cell-based biologics and radioligand therapies is reshaping competitive capability requirements.
Antibody-drug conjugates are decomposing the traditional boundary between cytotoxic chemotherapy and targeted biologics by delivering potent payloads with tumor-specific activation. Academic medical centers in the United States are expanding ADC protocol adoption faster than community oncology practices, compressing the addressable market for conventional taxane regimens. The structural consequence is a bifurcation between centers with infusion capacity for complex biologics and those dependent on oral small molecules.
The FDA's Project Confirm initiative is mandating earlier initiation of post-marketing confirmatory trials for therapies granted accelerated approval based on surrogate endpoints. This policy shift is forcing sponsors to allocate 30-40% larger Phase IV budgets before commercial launch, restructuring risk-adjusted net present value calculations for pipeline assets. Oncology programs most affected are those targeting rare mutations with limited patient pools for survival endpoint verification.
Hospital procurement departments are consolidating purchasing authority for oncology biologics through specialty pharmacy networks that bypass traditional wholesale distribution. This channel concentration is displacing independent oncology practice autonomy in drug selection, with three national health systems now controlling 45% of checkpoint inhibitor volume in major metropolitan markets. The shift is most visible in California and Texas, where integrated delivery networks have captured infusion center referrals from community-based medical oncologists.
Metastatic Cancer Treatment Drug Market Segmentation
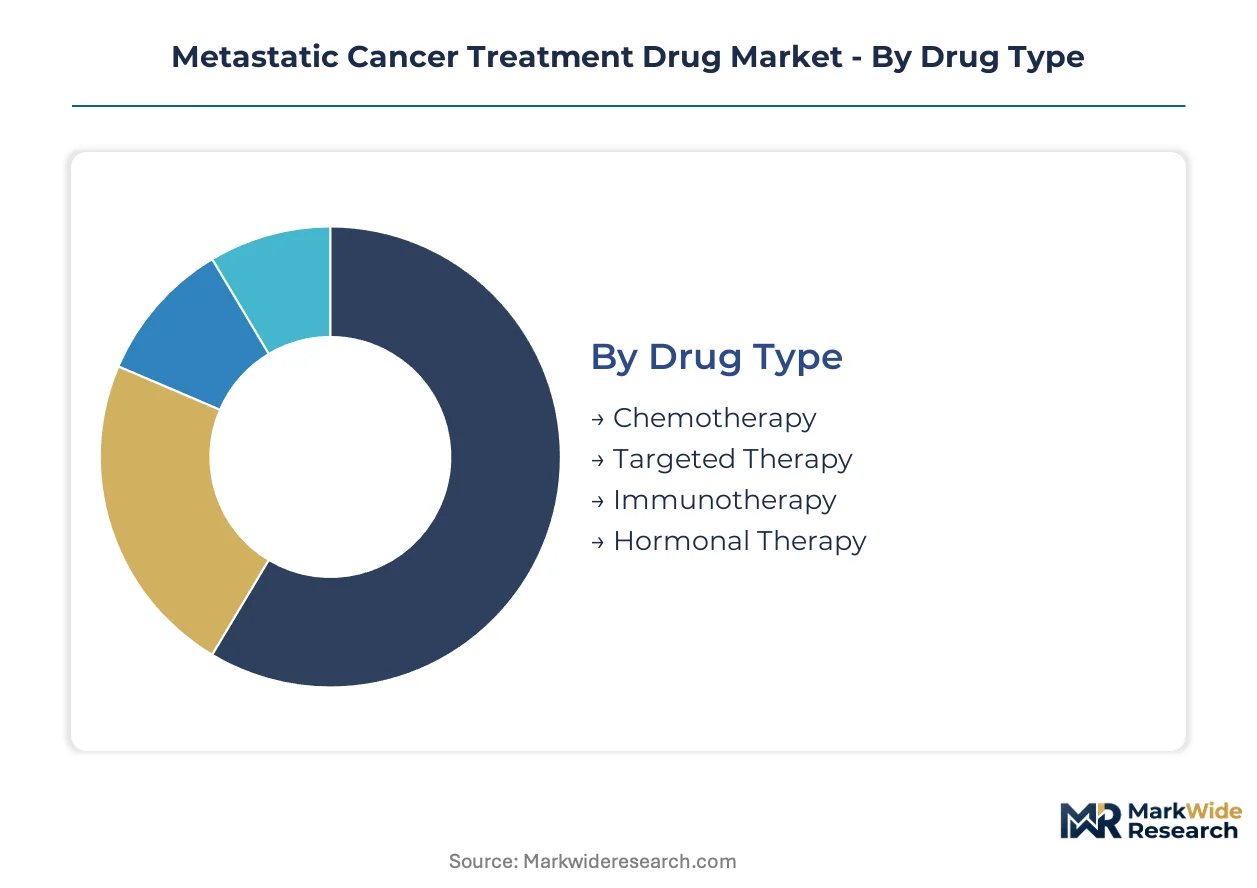
Segmentation in metastatic oncology reveals how regulatory pathways, reimbursement structures, and site-of-care capabilities fragment commercial opportunity. Each dimension carries distinct margin profiles and access constraints that shape portfolio prioritization.
Drug Type:
FDA, EMA, and NMPA apply divergent evidentiary thresholds across mechanism classes, with accelerated approval pathways favoring novel modalities over cytotoxic extensions.
- Immunotherapy:Checkpoint inhibitors and CAR-T cell therapies command premium pricing through breakthrough therapy designations. Academic medical centers in the United States concentrate demand for combination protocols, though cold-chain logistics inflate per-dose delivery costs.
- Targeted Therapy:Small-molecule kinase inhibitors and monoclonal antibodies deliver tumor-specific intervention with oral bioavailability advantages. China's NMPA innovation review pathways compress launch sequencing gaps for these assets against Western regulators.
- Chemotherapy:Cytotoxic agents face biosimilar erosion and contracting reimbursement margins in Medicare-dominant payment environments.
- Hormonal Therapy:Androgen and estrogen pathway modulators serve stable maintenance indications with generic substitution pressure in mature markets.
Immunotherapy handles the majority of throughput; subcutaneous immunotherapy formulations are gaining share fastest.
Delivery Mode:
Site-of-care economics and patient burden trade-offs determine adoption velocity across administration routes.
- Intravenous:Hospital infusion centers retain structural dominance for checkpoint inhibitors and cytotoxic combinations. Medicare reimbursement policies in the United States favor facility-based administration for biologics requiring monitoring.
- Subcutaneous:Self-administered formulations reduce chair time and expand community oncology access. European EMA approvals for subcutaneous checkpoint inhibitors are outpacing FDA timelines in certain indications.
- Oral:Small-molecule targeted therapies enable home-based adherence with pharmacy benefit management complexity.
- Topical:Limited application for cutaneous metastases with narrow addressable populations in dermatology-oncology crossover settings.
Intravenous administration maintains volume leadership; subcutaneous delivery is expanding most quickly on patient convenience drivers.
Therapy Area:
Patient pool scale and survival endpoint feasibility determine clinical trial investment intensity and label expansion economics.
- Lung Cancer:Non-small cell histologies concentrate the largest metastatic patient population with established biomarker stratification. United States-based academic centers drive adoption of first-line immunotherapy combinations with PD-L1 expression testing mandates.
- Breast Cancer:Hormone receptor-positive and HER2-negative subtypes command sustained R&D investment despite competitive density. China's NMPA has compressed review timelines for novel antibody-drug conjugates in this indication.
- Colorectal Cancer:MSI-high subsets qualify for immunotherapy while majority cytotoxic dependence persists.
- Urothelial Carcinoma:Bladder and upper tract malignancies show emerging checkpoint inhibitor responsiveness with smaller addressable populations.
Lung cancer carries the heaviest patient load; urothelial carcinoma is climbing the fastest on unmet need premiums.
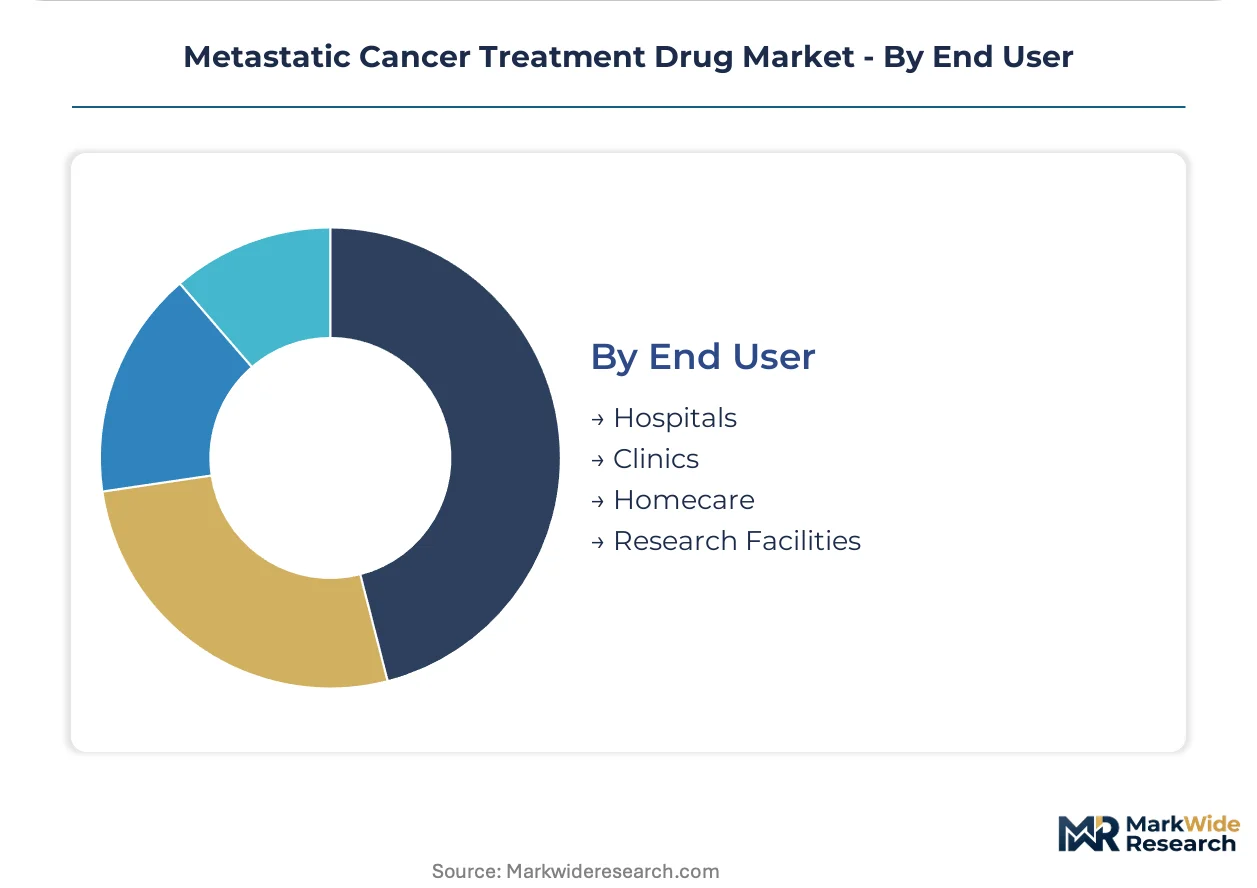
End User:
Procurement consolidation and reimbursement site-of-service differentials are restructuring channel access.
- Hospitals:Integrated delivery networks in California and Texas now control substantial checkpoint inhibitor volume through specialty pharmacy carve-outs. Medicare hospital outpatient prospective payment creates site-of-service arbitrage opportunities.
- Clinics:Community oncology practices face displacement as hospital employment models capture infusion referrals. Independent clinics retain oral oncology dispensing autonomy where state regulations permit.
- Homecare:Subcutaneous biologics and oral regimens enable administration outside facility settings with nursing support requirements.
- Research Facilities:Academic medical centers concentrate early-phase trial enrollment with protocol-specific manufacturing relationships.
Hospitals manage the dominant share of biologic administration; homecare is the steepest expansion trajectory on subcutaneous formulation proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's accelerated approval pathways and Medicare reimbursement structures concentrate metastatic oncology investment in the United States, while China's NMPA innovation reviews and Europe's EMA centralized procedures create divergent access timelines across major markets.
United States
Academic medical centers in Boston and Houston drive combination immunotherapy protocol adoption with specialized infusion capacity. Medicare's hospital outpatient prospective payment system favors facility-based biologic administration. The Texas Medical Center and Memorial Sloan Kettering Cancer Center anchor clinical trial enrollment for first-line metastatic indications.
Germany
Heidelberg and Munich university hospitals concentrate radioligand therapy administration with Novartis production network access. EMA centralized marketing authorizations enable rapid label expansion across EU member states. The Rhine-Main biotechnology corridor hosts manufacturing infrastructure for antibody-drug conjugates.
China
NMPA's breakthrough therapy review pathways compress historical launch gaps with Western regulators for novel oncology assets. Shanghai and Beijing academic centers scale PD-1 inhibitor combination protocols. The Zhangjiang Hi-Tech Park anchors domestic biologics manufacturing capacity.
Japan
PMDA's sakigake designation accelerates access for innovative metastatic therapies with unmet medical need. Tokyo and Osaka metropolitan areas concentrate specialized cancer center density. The Kansai region hosts contract manufacturing organizations serving Asia-Pacific distribution networks.
United Kingdom
NICE technology appraisals determine National Health Service reimbursement for metastatic cancer drugs with cost-effectiveness thresholds. London and Manchester cancer centers lead early adoption of subcutaneous checkpoint inhibitor formulations. The Cambridge life sciences cluster supports radioligand research infrastructure.
Metastatic Cancer Treatment Drug Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with immuno-oncology manufacturing networks and specialized biologics capabilities. Market structure concentrates around three strategic archetypes: checkpoint inhibitor specialists with deep clinical trial infrastructure, radioligand therapy producers with captive isotope supply chains, and antibody-drug conjugate developers with payload-linker expertise. Dominant competitive moves include subcutaneous formulation development to reduce infusion center dependence and biosimilar manufacturing partnerships to capture post-patent volume.
Among US-based integrated pharmaceutical conglomerates, Bristol Myers Squibb Company and Merck & Co., Inc. occupy positions exemplifying checkpoint inhibitor market presence, while Novartis AG represents the radioligand therapy specialization archetype with manufacturing capabilities in targeted nuclear medicine. These three entities anchor the competitive structure through distinct modality expertise rather than overlapping therapeutic positioning.
| Leading Market Players |
|---|
| Bristol Myers Squibb Company |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca PLC |
| Pfizer, Inc. |
| Eli Lilly and Company |
| Amgen, Inc. |
| Others |
Pricing and Supply Chain Analysis
Biologics manufacturing scale economies at Novartis radioligand facilities and Bristol Myers Squibb immuno-oncology plants anchor supply concentration, compressing per-dose cost floors while FDA breakthrough therapy premiums sustain pricing power at the top tier. Cold-chain infrastructure density in the United States and Germany creates geographic price stratification that community oncology practices cannot arbitrage.
Pricing Analysis
Certification level creates the primary spread between FDA-breakthrough designated checkpoint inhibitors and standard-of-care cytotoxics facing biosimilar erosion. Three-tier pricing structure separates premium immuno-oncology combinations from mid-tier targeted therapies and economy hormonal generics. Pricing pressure stems from Medicare's hospital outpatient prospective payment compression and 340B pharmacy carve-out expansion. Community oncology clinics exhibit highest price sensitivity as employment by hospital systems eliminates formulary autonomy.
Supply Chain Analysis
Lutetium-177 isotope production chokepoints at nuclear reactors in the Netherlands, Canada, and Australia constrain radioligand therapy expansion regardless of manufacturing capacity elsewhere. CAR-T autologous cell processing draws from patient leukapheresis collection, viral vector supply, and cryopreservation logistics that fragment geographic sourcing. Single-source vulnerability concentrates in plasmid DNA suppliers for gene therapy payloads. Distribution runs through specialty pharmacy networks that hospital procurement departments control, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-marketing confirmatory trial services and patient adherence monitoring programs attach recurring revenue layers expanding faster than drug substance manufacturing in metastatic oncology portfolios.
For Market Incumbents: Consolidate manufacturing footprint through captive isotope supply agreements and backward integration into viral vector production to defend against CAR-T biosimilar entrants. Lock hospital system formulary access through specialty pharmacy joint ventures before Medicare site-of-service payment reforms accelerate. FDA Project Confirm withdrawal risk threatens revenue streams for accelerated approval assets with delayed confirmatory readouts. For New Entrants and Emerging Players: NMPA breakthrough therapy fast-track in China offers the most penetrable regulatory pathway for novel antibody-drug conjugates with compressed review timelines against Western entry. Target subcutaneous formulation white space in lung cancer and breast cancer where infusion center capacity constraints create patient access bottlenecks. Deploy academic medical center principal investigator partnerships as the primary go-to-market angle to secure combination protocol inclusion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors radioligand therapy developers with captive isotope supply chains over checkpoint inhibitor franchises facing patent cliff exposure. Long-term viability across the analysis window rests on manufacturing network control rather than single-asset clinical data. Acquisition targets should demonstrate cell therapy facility inspection readiness across FDA, EMA, and NMPA jurisdictions simultaneously. The signal to watch is confirmatory trial failure rates under Project Confirm as a clearing mechanism for portfolio quality.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces infusion center dependence and expands community oncology access for checkpoint inhibitors. |
| Radioligand Manufacturing Scale-Up | Novartis production network de-risks isotope supply constraints for precision nuclear medicine expansion. |
| Confirmatory Trial Advancement | FDA Project Confirm compliance protects accelerated approval revenue streams from withdrawal mechanisms. |
| NMPA Innovation Pathway Entry | China's compressed review timelines narrow historical launch gaps with Western regulators for novel assets. |
| Specialty Pharmacy Network Partnership | Hospital procurement consolidation demands captive distribution channels for biologic volume capture. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions for market sizing and growth trajectory. Primary interviews across academic medical centers in Boston, Houston, and Shanghai combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and Medicare formulary databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include drug type, delivery mode, therapy area, end user, and regional regulatory cluster across the projection horizon. CAGRs derived from treatment line expansion rates, label approval velocity, and reimbursement policy shifts. Forecast inputs incorporated PD-L1 testing penetration, subcutaneous formulation approval timelines, and biosimilar entry assumptions for reference biologics.
Underlying assumptions cover confirmatory trial success rates, Medicare payment stability, and cold-chain logistics cost trajectories, with deviation risk concentrated in FDA withdrawal actions and NMPA policy reversals. Practitioners should keep alternative scenarios live as immuno-oncology combination data matures and radioligand isotope supply expands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Cryptococcosis Therapeutics Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Levothyroxine Sodium Market