
 South Africa Insulin Drugs and Delivery Devices Market | 2026-2036
South Africa Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Insulin Drugs and Delivery Devices Market Insights
Subscription-based insulin pump monitoring services is rebalancing how manufacturers capture recurring revenue beyond hardware sales. Novo Nordisk leverages its long-acting insulin portfolio to sustain dominance in public sector tenders across South African provinces. Sanofi anchors its position through integrated pen-and-cartridge ecosystems that reduce switching costs for Type 2 patients. Medtronic competes on closed-loop algorithm sophistication, differentiating its pumps through predictive low-glucose suspend features.
Insulin drugs and delivery devices comprise biologic hormone formulations and mechanical or electronic systems for controlled parenteral administration, with modern pumps achieving basal rates as precise as 0.025 units per hour and disposable pens calibrated to 1-unit dosing increments. Insulin pens occupy the largest volume share due to lower training barriers and reimbursement familiarity in South African medical aid schemes. Continuous glucose monitors represent the fastest-expanding product category as private insurers expand coverage for real-time data integration with smartphone platforms. Subcutaneous injection dominates delivery mode selection, though inhalation systems attract niche interest among needle-averse patients in urban private practice.
South Africa's South African Health Products Regulatory Authority (SAHPRA) governs insulin drug registration under biologic licensing pathways that require local stability data, while the National Department of Health sets essential medicines list inclusion criteria that determine public procurement volumes. ISO 11608 standards for needle-based injection systems shape technical compliance for pen and syringe manufacturers seeking market access. Stakeholders must monitor SAHPRA's evolving biosimilar interchangeability guidelines, as these will determine whether follow-on insulins displace originator products in tender allocations without prescriber consent.
Market Dynamics
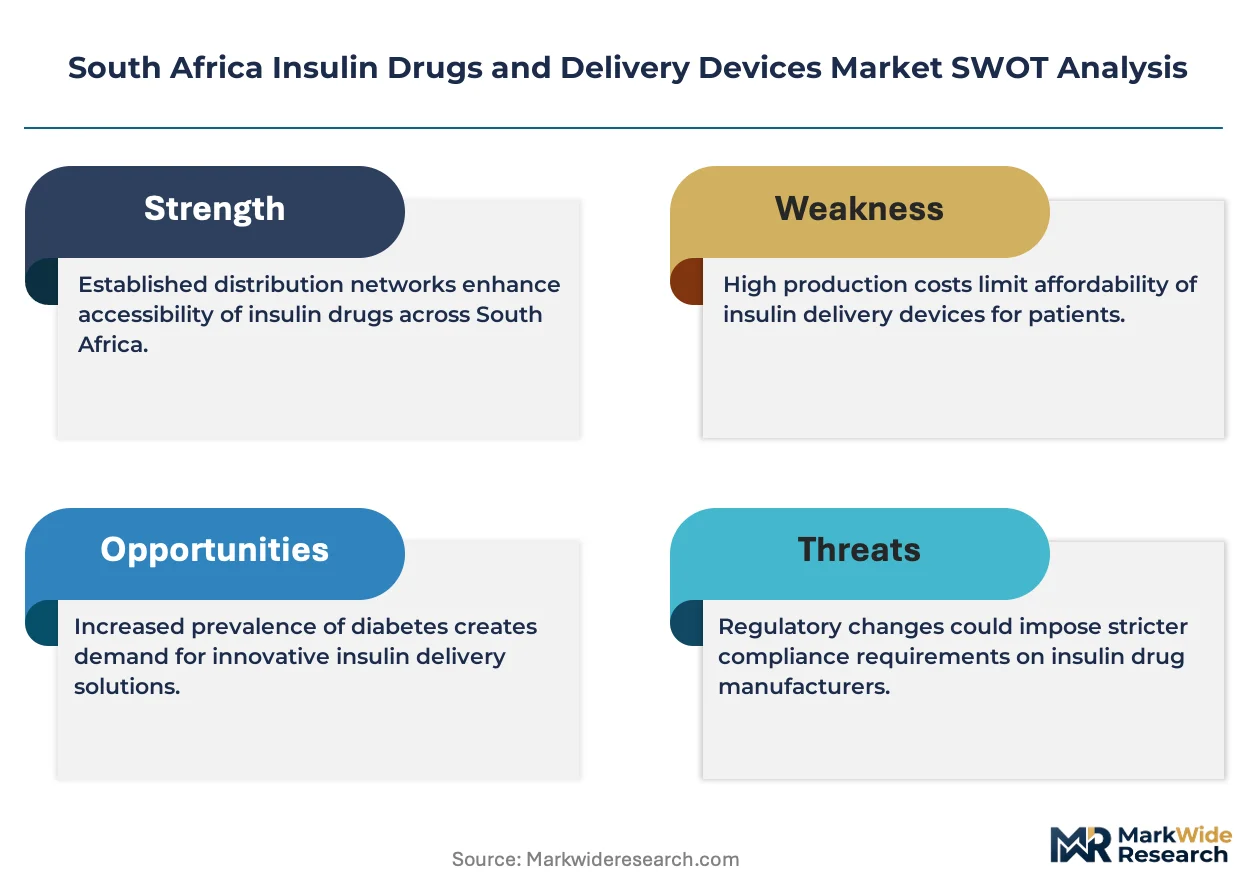
SAHPRA's evolving biosimilar interchangeability guidelines are compressing originator insulin margins while forcing manufacturers to rebuild value propositions around service integration rather than molecule exclusivity.
Growth Catalysts
- Homecare migration:Patients in Gauteng and Western Cape provinces are abandoning hospital-based diabetes management for self-administered pen and pump therapies, expanding addressable device volumes beyond clinical settings.
- ISO 11608 compliance harmonization:Standardized needle-based injection system requirements are reducing technical barriers for pen manufacturers entering South African distribution channels.
- CGM-smartphone integration:Real-time glucose data streaming to mobile platforms is creating upgrade cycles among privately insured Type 1 patients in urban centers.
Market Restraints
- Cold chain infrastructure gaps:Temperature excursions during last-mile distribution to rural Eastern Cape and Limpopo provinces degrade insulin potency and trigger wastage claims against suppliers.
- Originator concentration:Three multinational manufacturers control over 80% of public sector tender allocations, limiting price competition in provincial procurement.
- Needle phobia substitution:Inhalation delivery systems attract affluent needle-averse patients in Sandton and Cape Town private practice, fragmenting addressable demand for injectable formats.
Strategic Opportunities
- KwaZulu-Natal underpenetration:Durban's lower endocrinologist density relative to Gauteng creates whitespace for telemedicine-linked pump subscription services targeting undiagnosed Type 2 populations.
- National Health Insurance alignment:Preparatory work for NHI implementation is opening dialogue on risk-sharing models for continuous glucose monitor coverage in public facilities.
- Subscription revenue capture:Manufacturers bundling hardware with algorithm updates and remote monitoring are extracting recurring payments beyond single-device sales cycles.
Industry Challenges
- Endocrinology workforce scarcity:South Africa trains fewer than 30 diabetes specialists annually, constraining patient education capacity for complex pump onboarding.
- SAHPRA biologic stability requirements:Mandatory local storage testing adds 18-24 months to biosimilar registration timelines, delaying competitive entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Insulin Drugs and Delivery Devices Market |
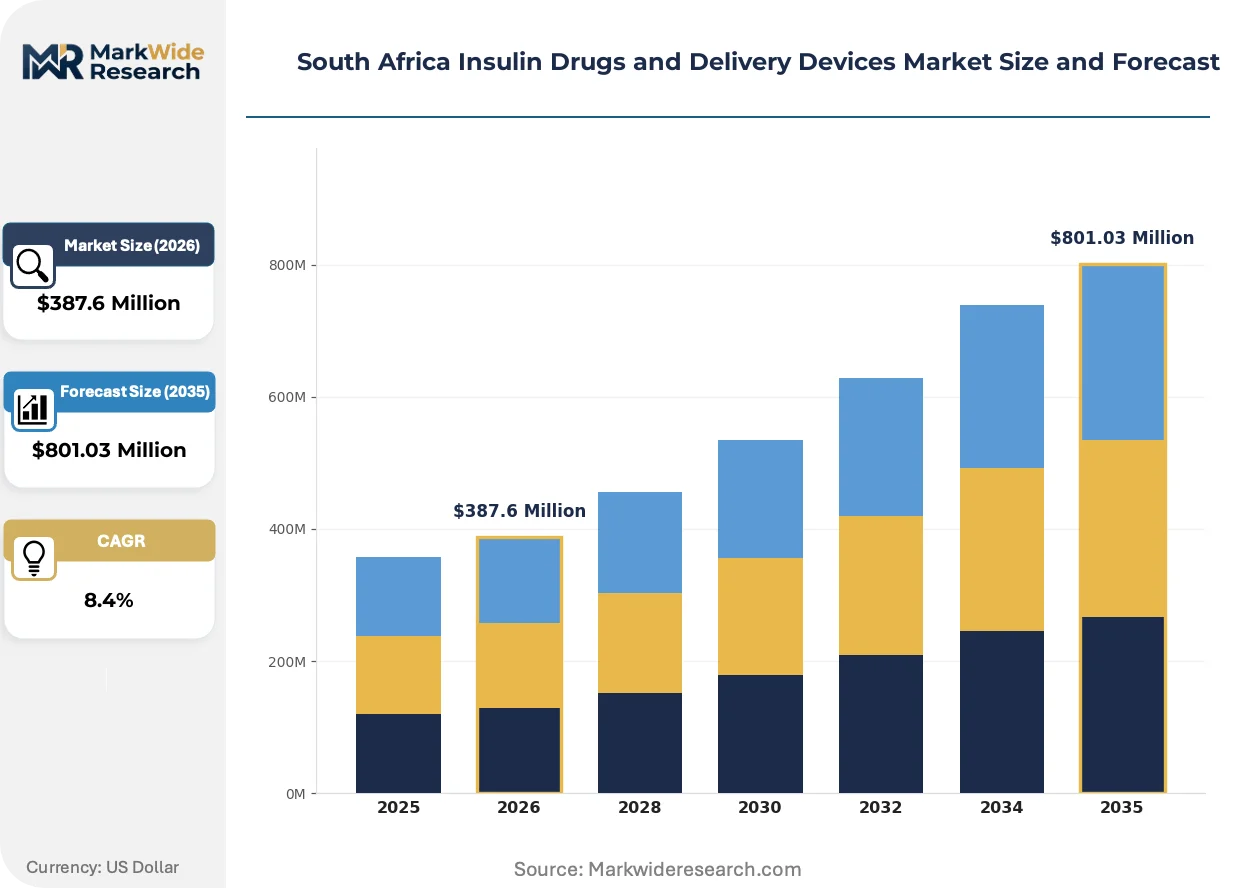
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Syringes, Insulin Pumps, Continuous Glucose Monitors Delivery Mode: Subcutaneous Injection, Intravenous Injection, Inhalation, Transdermal End User: Hospitals, Clinics, Homecare, Research Laboratories Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Insulin Resistance |
| Companies Covered | Novo Nordisk, Sanofi, Pfizer, Novartis, Julphar, Medtronic, Eli Lilly and Company, Embecta Corp., Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Insulin Drugs and Delivery Devices Market Trends and Innovations
Digital connectivity and algorithmic automation are displacing manual glucose management workflows across South African diabetes care, with implications for device procurement criteria and patient adherence monitoring.
Closed-loop insulin delivery systems are unifying pump, sensor, and algorithm functions into single-platform diabetes management. Private medical aid schemes in Johannesburg and Pretoria are accelerating prior authorization for these integrated systems among high-utilization Type 1 members. The technology is unifying previously separate device procurement decisions, compressing vendor selection cycles and favoring manufacturers with full-stack capabilities over component specialists.
SAHPRA's draft biosimilar interchangeability guidelines are mandating prescriber notification protocols for pharmacy-level substitution. Originators must now defend position through real-world evidence generation rather than patent exclusivity alone. Public sector tender allocations in Free State and Mpumalanga provinces are most affected, with provincial pharmacies awaiting final guidance before expanding formulary switches.
Medical aid schemes are unbundling continuous glucose monitor hardware from sensor subscriptions, allowing patients to purchase receivers outright while paying monthly for disposable components. Discovery Health and Bonitas have introduced tiered coverage structures that shift cost burden based on HbA1c improvement metrics. This behavioral shift is most visible among employed Type 2 populations in Gauteng's corporate health programs, where wellness incentives now tie device subsidies to glycemic control outcomes.
South Africa Insulin Drugs and Delivery Devices Market Segmentation
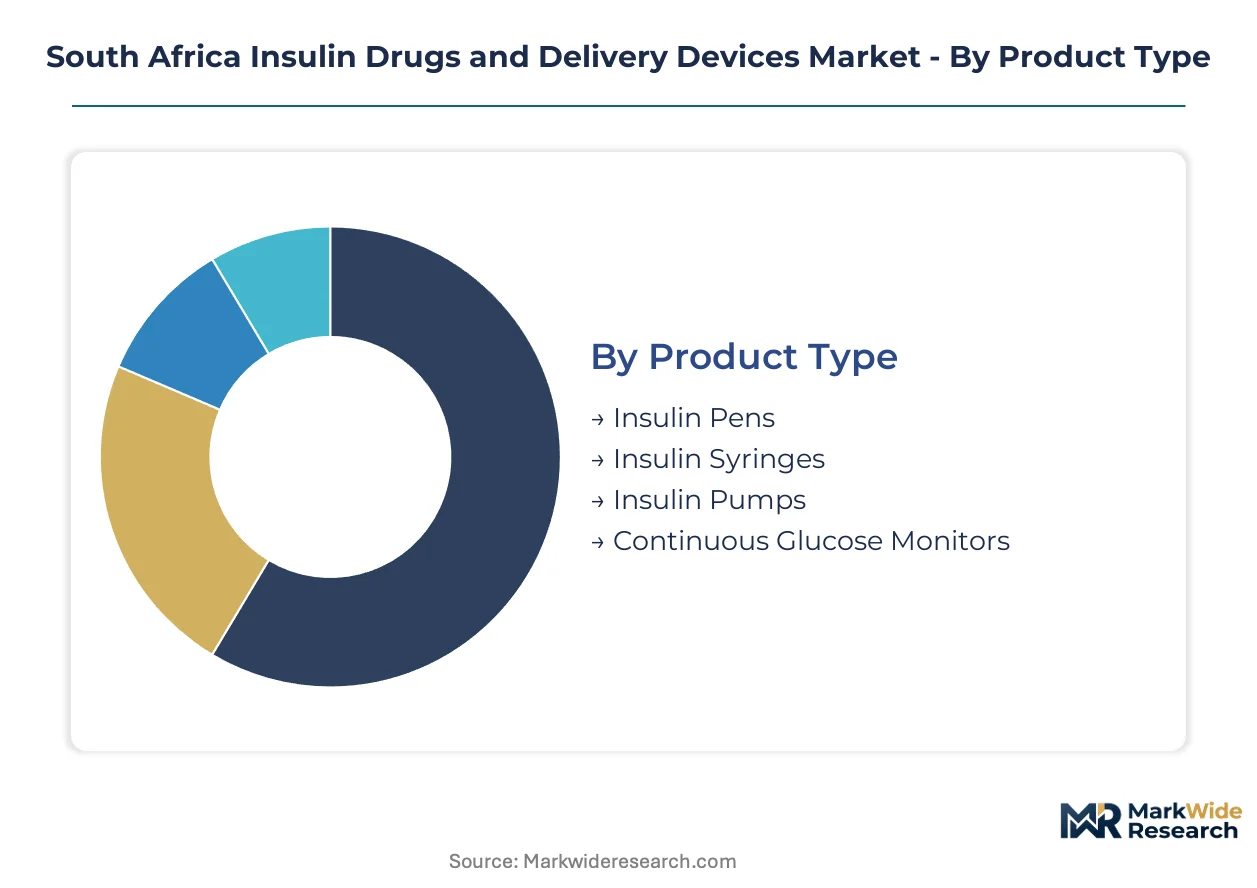
Segmentation in the South Africa insulin drugs and delivery devices market reveals divergent regulatory pathways and reimbursement dynamics across product formats. Each category carries distinct certification burdens from SAHPRA, shaping competitive entry timelines and margin structures for manufacturers.
Product Type:
SAHPRA biologic licensing pathways apply uniformly across all insulin delivery hardware, though ISO 11608 needle-based injection system compliance creates tiered technical barriers for pen and syringe manufacturers versus pump and CGM specialists.
- Insulin Pens:Disposable and reusable pen systems calibrated to 1-unit dosing increments dominate procurement volumes in South African medical aid schemes. Demand concentrates in Gauteng's private diabetes clinics, where lower training barriers accelerate patient onboarding and reduce nurse educator burden.
- Continuous Glucose Monitors:Real-time glucose data streaming to smartphone platforms requires SAHPRA medical device registration alongside software validation for mobile integration. Discovery Health and Bonitas members in Johannesburg corporate health programs drive fastest expansion as insurers unbundle hardware from sensor subscriptions.
- Insulin Syringes:Traditional vial-and-syringe administration persists in public sector facilities where unit cost minimization governs Free State and Mpumalanga provincial tenders.
- Insulin Pumps:Electronic basal-bolus delivery systems achieving 0.025 units per hour precision face extended SAHPRA stability testing timelines that compress competitive entry windows.
Insulin pens sit at the top of the volume ranking, with continuous glucose monitors climbing the fastest.
Delivery Mode:
Route of administration determines cold chain integrity requirements and patient training intensity, with implications for rural Eastern Cape and Limpopo distribution economics.
- Subcutaneous Injection:Abdominal, thigh, and arm tissue deposition via pen, syringe, or pump cannula constitutes the standard of care across South African endocrinology practice. Public and private sector procurement both prioritize this delivery mode for its established reimbursement codes and pharmacy familiarity.
- Inhalation:Pulmonary insulin delivery attracts affluent needle-averse patients in Sandton and Cape Town private practice, though limited formulary inclusion constrains volume scaling.
- Intravenous Injection:Hospital-only administration for diabetic ketoacidosis management in academic medical centers requires specialized infusion protocol training.
- Transdermal:Microneedle patch technologies remain pre-commercial in South Africa pending SAHPRA skin permeation safety data requirements.
Subcutaneous injection commands absolute volume leadership, while inhalation delivery gains share fastest among urban private-pay segments.
End User:
Care setting migration from institutional to self-managed environments is redistributing device procurement authority from hospital pharmacy committees to patient-directed retail channel selection.
- Homecare:Self-administered pen and pump therapies in patient residences now drive Gauteng and Western Cape device volume expansion as medical aid schemes expand chronic benefit limits.
- Hospitals:Academic centers in Johannesburg and Pretoria maintain concentrated insulin procurement for inpatient glycemic management and diabetic emergency protocols.
- Clinics:Outpatient diabetes services in KwaZulu-Natal face endocrinologist scarcity that limits complex pump onboarding capacity.
- Research Laboratories:Academic investigation sites conduct bioequivalence studies required for SAHPRA biosimilar registration pathways.
Homecare sits at the top of the volume ranking, with research laboratories climbing the fastest as biosimilar trials accelerate.
Application:
Disease phenotype determines device complexity requirements and insurer prior authorization stringency across South African medical aid scheme tiers.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive basal-bolus regimens or closed-loop pump systems, with private insurers in Pretoria and Johannesburg accelerating integrated CGM-pump prior authorization.
- Type 2 Diabetes:Progressive beta-cell failure drives pen-based insulin initiation in primary care, though oral agent failure timelines vary widely across public sector treatment protocols.
- Gestational Diabetes:Pregnancy-specific glycemic targets require rapid-acting insulin analog availability in obstetric units with neonatal intensive care backup.
- Insulin Resistance:Severe metabolic syndrome presentations in urban corporate health programs occasionally progress to high-dose insulin requirements.
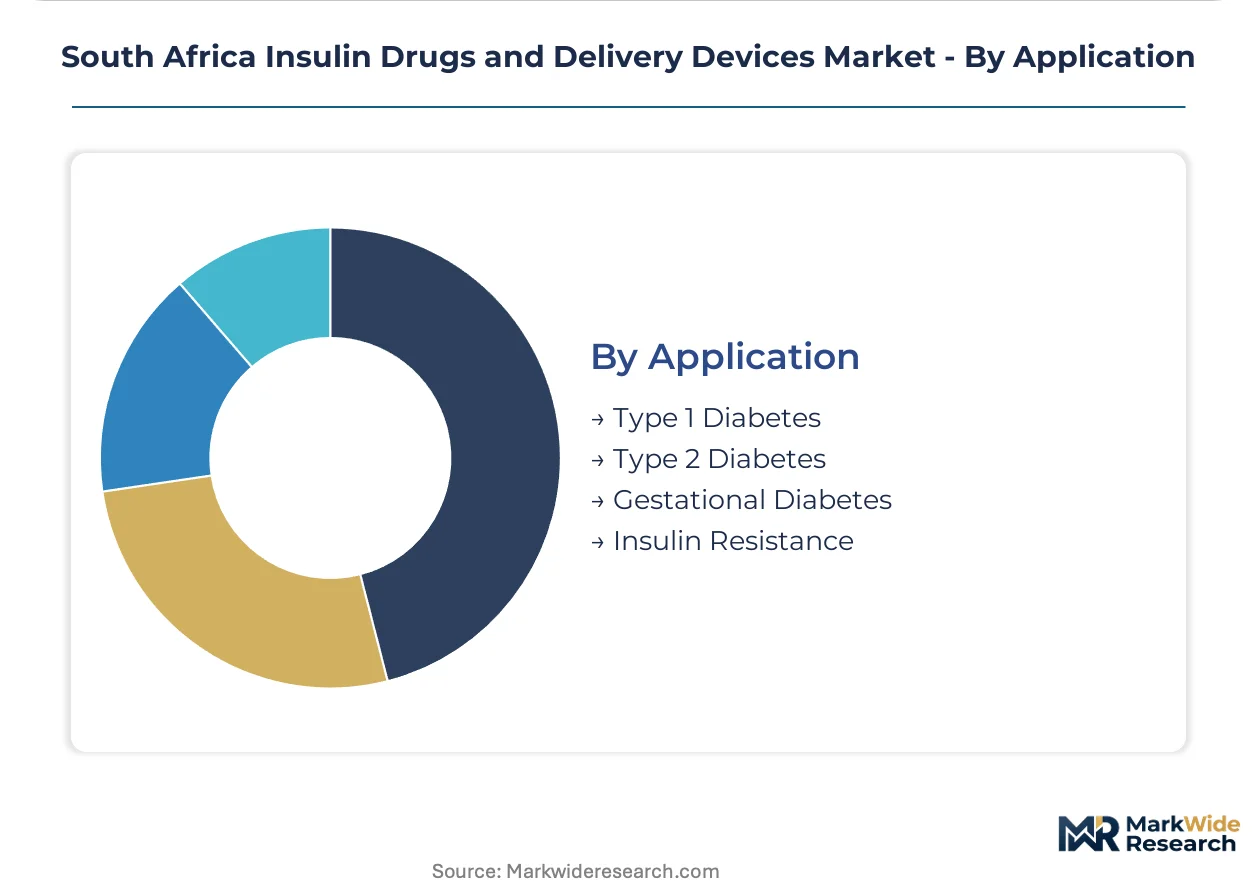
Type 2 diabetes sits at the top of the volume ranking, with Type 1 diabetes climbing the fastest as closed-loop technology penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's insulin market concentration diverges sharply from Nigeria's fragmented import dependency, with Gauteng province alone commanding device volumes that exceed total annual consumption in most sub-Saharan neighbors.
Gauteng
Johannesburg and Pretoria host the densest clusters of endocrinology services and private diabetes clinics nationwide. SAHPRA's biologic licensing pathways streamline registration for manufacturers targeting this corridor. Discovery Health's corporate wellness programs in Sandton drive CGM-smartphone integration adoption faster than any other metro.
Western Cape
Cape Town's private practice networks attract affluent needle-averse patients exploring inhalation delivery alternatives. The provincial health department maintains stricter cold chain protocols than Eastern Cape or Limpopo counterparts. Medical aid scheme penetration here exceeds national averages by substantial margins.
KwaZulu-Natal
Durban's lower endocrinologist density relative to Gauteng creates whitespace for telemedicine-linked pump subscription services. The National Department of Health's essential medicines list criteria govern public procurement volumes across provincial facilities. Undiagnosed Type 2 populations in peri-urban townships remain underserved by current distribution networks.
Eastern Cape
Rural distribution economics suffer from temperature excursions during last-mile insulin delivery. Provincial pharmacy committees await SAHPRA's final biosimilar interchangeability guidance before expanding formulary switches. Academic medical centers in Mthatha maintain concentrated procurement for diabetic emergency protocols.
Free State
Public sector tender allocations here prioritize unit cost minimization for traditional vial-and-syringe formats. The province's hospital pharmacy committees lack technical capacity to evaluate closed-loop pump prior authorizations. Bloemfontein's limited private endocrinology practices refer complex cases to Gauteng.
South Africa Insulin Drugs and Delivery Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational originators controlling public sector tenders while regional distributors capture retail pharmacy volumes. Three manufacturers dominate over 80% of provincial procurement allocations, compressing price competition. Strategic archetypes include integrated full-stack platform providers, pen-and-cartridge ecosystem builders, and algorithm-focused pump specialists. Competitive moves center on service bundling beyond hardware sales and real-world evidence generation for formulary defense.
Among the originator tier, Novo Nordisk and Sanofi exemplify divergent ecosystem strategies, with the former leveraging long-acting portfolios for tender dominance and the latter anchoring position through integrated delivery formats. Medtronic occupies a position on the technology-intensive vector, representing closed-loop algorithm sophistication. Eli Lilly and Company sits within the rapid-acting analog segment alongside Becton, Dickinson and Company, which anchors the injection device supply tier. Pfizer and Novartis exemplify diversified pharmaceutical conglomerates with diabetes as one vertical among broader portfolios.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Pfizer |
| Novartis |
| Julphar |
| Medtronic |
| Eli Lilly and Company |
| Embecta Corp. |
| Becton, Dickinson and Company |
| Others |
Pricing and Supply Chain Analysis
Public sector tender consolidation in Free State and Mpumalanga provinces is compressing supplier margins and forcing manufacturers toward service bundling to preserve value capture beyond per-unit transactions.
Pricing Analysis
Capacity additions in biosimilar manufacturing are reshaping price floors for originator insulin portfolios across South African provincial tenders. Three-tier pricing structure across premium analog, standard human insulin, and economy biosimilar levels stratifies procurement tiers, with Discovery Health and Bonitas members showing lowest price sensitivity for closed-loop systems. Cost compression in public sector vial-and-syringe segments is intensifying because of mandatory local stability testing timelines. Hospital pharmacy committees in Gauteng demonstrate highest price sensitivity for traditional delivery formats.
Supply Chain Analysis
Direct-to-pharmacy channels handle chronic patient demand in urban corridors, while depot-to-clinic distribution serves rural Eastern Cape and Limpopo facilities. Active pharmaceutical ingredient production draws from India, China, and Denmark, with pen device manufacturing anchored in Germany, Ireland, and China. Supply chain risk centers on single-source vulnerability for precision pump motors and CGM sensors. Cold chain integrity rests on temperature-controlled last-mile logistics to provincial pharmacy depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through SAHPRA's biosimilar interchangeability guidelines, which will trigger formulary switches and upgrade cycles across provincial procurement systems.
For Market Incumbents: Lock in formulary position through real-world evidence generation for originator insulin efficacy in South African populations. Secure backward integration into CGM sensor manufacturing to reduce component cost exposure. Defend against biosimilar substitution by embedding remote monitoring services that raise patient switching costs. For New Entrants and Emerging Players: Launch via telemedicine-linked subscription models targeting KwaZulu-Natal's endocrinology gap. Exploit whitespace in Durban's undiagnosed Type 2 population through algorithm-integrated pump services. Prioritize SAHPRA registration pathways for biosimilar interchangeability designation to accelerate provincial tender access. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-focused pump specialists possessing closed-loop software validation. Five-to-ten-year viability favors manufacturers bundling hardware with recurring sensor revenue. Monitor SAHPRA's final interchangeability guidance publication as inflection indicator for biosimilar market share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Biosimilar Registration Pathway | Accelerates market entry for follow-on insulins in Free State and Mpumalanga provincial tenders. |
| Closed-Loop Algorithm Development | Differentiates pump offerings through predictive low-glucose suspend features for Discovery Health members. |
| Telemedicine Platform Integration | Captures KwaZulu-Natal whitespace by linking remote monitoring to pump subscription services. |
| Sensor Manufacturing Scale-Up | Reduces CGM cost burden as Bonitas and Discovery Health unbundle hardware from disposable components. |
| Real-World Evidence Generation | Defends originator position in public sector tenders through South African population-specific efficacy data. |
Research Methodology
Coverage spans Gauteng, Western Cape, KwaZulu-Natal, Eastern Cape, and Free State provinces, with primary inputs from each region's hospital pharmacy committees and private endocrinology practices. The analysis combines structured interviews with SAHPRA regulatory affairs leads, provincial procurement managers, biomedical engineers at academic medical centers, and medical aid scheme formulary directors with secondary validation from SAHPRA registration databases, National Department of Health tender records, ISO 11608 compliance filings, and hospital procurement system data. Bottom-up device volume modeling and top-down insulin consumption estimates were triangulated against provincial pharmacy dispensing records.
Rate-of-change decomposition separates volume expansion from value-per-patient growth across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user setting, and application phenotype, with provincial regulatory cluster as an additional stratification layer. CAGRs were derived from trend extrapolation of historical tender allocations and medical aid scheme benefit expansion trajectories. Forecast inputs incorporate SAHPRA approval timeline probabilities and National Health Insurance preparatory work progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged biosimilar registration delays or accelerated NHI implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
US Pharmaceutical Warehousing Market