
 Memory-Enhancing Drugs Market | 2026-2036
Memory-Enhancing Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Memory-Enhancing Drugs Market Foresight
Single-source API supply for cholinergic compounds is decoupling from legacy contract manufacturing relationships as sponsors pursue geographic redundancy. Pfizer Inc. leverages captive fermentation capacity to secure racetam precursor supply chains. Novartis AG anchors its position through integrated peptide synthesis operations in Switzerland and Singapore. Eisai Co. Ltd. specializes in amyloid-targeting formulations, competing on regulatory submission velocity rather than manufacturing scale.
Memory-enhancing drugs comprise synthetic and naturally derived compounds that modulate acetylcholine, glutamate, or cerebral blood flow to improve synaptic plasticity and recall performance, with potency measured by standardized cognitive assessment batteries such as the ADAS-Cog or CANTAB protocols. Cholinergics dominate current prescription volumes due to established reimbursement for Alzheimer's treatment, while nootropics capture the fastest expansion as direct-to-consumer channels erode traditional gatekeeper control. Oral tablets retain the largest manufacturing footprint, though liquid formulations command premium positioning in pediatric ADHD management where dose titration flexibility determines formulary access.
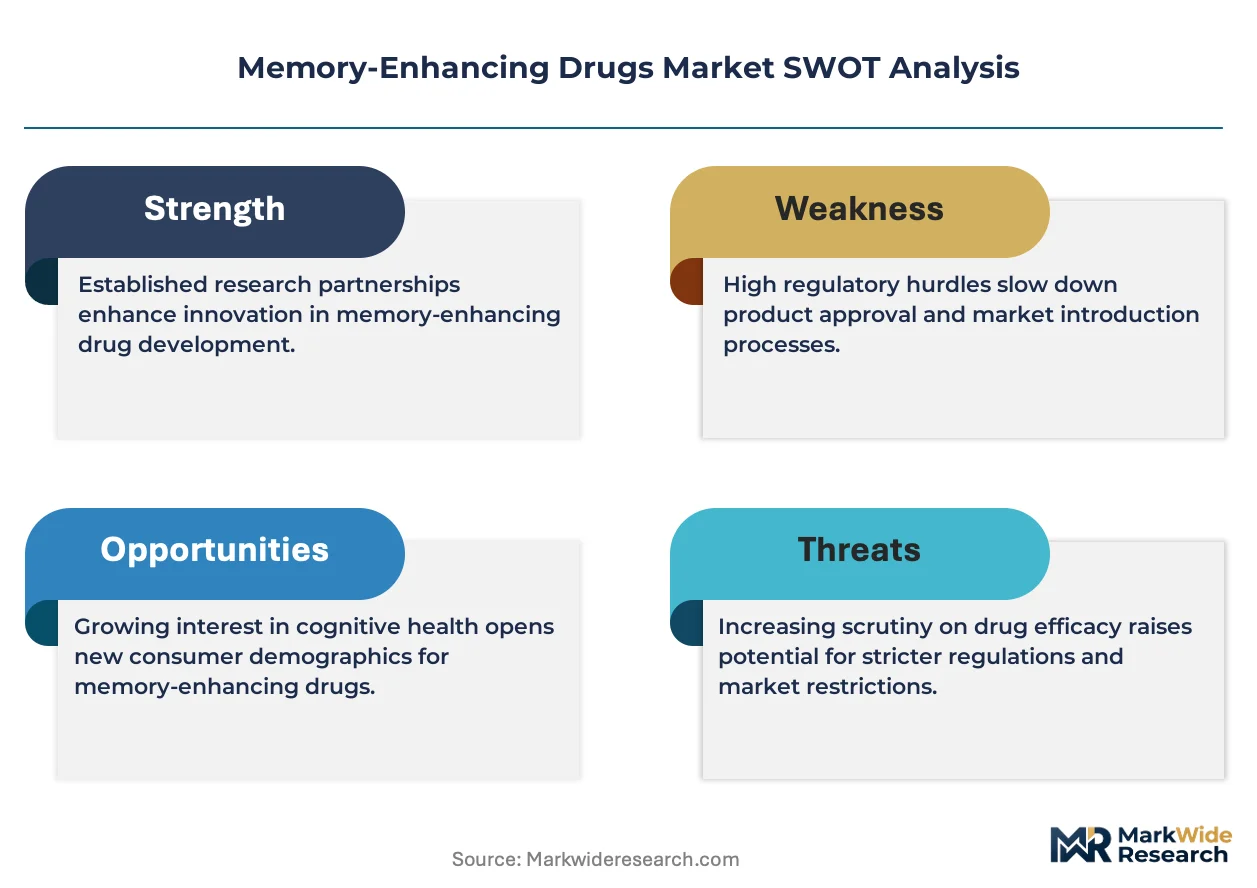
The FDA's Breakthrough Therapy designation and EMA's PRIME eligibility criteria compress development timelines for novel mechanisms, though post-marketing neuropsychiatric safety monitoring requirements intensify pharmacovigilance burdens. India's CDSCO and Japan's PMDA impose divergent bioequivalence standards for generic racetams, fragmenting regulatory submission strategies. Stakeholders must monitor how the EU AI Act and FDA's emerging digital biomarker guidance reshape endpoint validation for cognition-enhancing therapies.
Market Dynamics
The FDA's accelerated approval pathways for neurodegenerative therapies are compressing clinical trial timelines while intensifying post-market surveillance obligations for sponsors developing amyloid-targeting and cholinergic compounds.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review framework compresses development cycles for novel cognitive enhancers targeting Alzheimer's pathology.
- Aging Demographics:United States patient populations over 65 expand addressable prescription volumes for acetylcholinesterase inhibitors and emerging nootropic formulations.
- Direct-to-Consumer Channels:Digital health platforms erode traditional gatekeeper control over racetam and natural nootropic distribution.
Market Restraints
- API Supply Concentration:Single-source fermentation capacity for cholinergic precursors in legacy contract manufacturing regions creates geographic vulnerability.
- Divergent Bioequivalence Standards:India's CDSCO and Japan's PMDA impose incompatible generic racetam testing protocols, fragmenting regulatory submission strategies.
- Neuropsychiatric Safety Monitoring:Post-marketing pharmacovigilance requirements for cognition-enhancing therapies inflate compliance costs.
Strategic Opportunities
- Pediatric ADHD Liquid Formulations:Dose titration flexibility in non-tablet delivery systems commands premium formulary positioning.
- EU AI Act Compliance:Digital biomarker endpoint validation creates first-mover advantage for sponsors integrating machine learning into cognitive assessment protocols.
- Peptide Synthesis Integration:Captive manufacturing of amyloid-targeting compounds in Switzerland and Singapore reduces dependency on external API suppliers.
Industry Challenges
- Cross-Border Regulatory Arbitrage:Sponsors must reconcile FDA digital biomarker guidance with EMA's divergent evidentiary standards for CANTAB protocol validation.
- Legacy System Interoperability:Electronic data capture platforms for ADAS-Cog scoring resist integration with cloud-based pharmacovigilance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory-Enhancing Drugs Market |
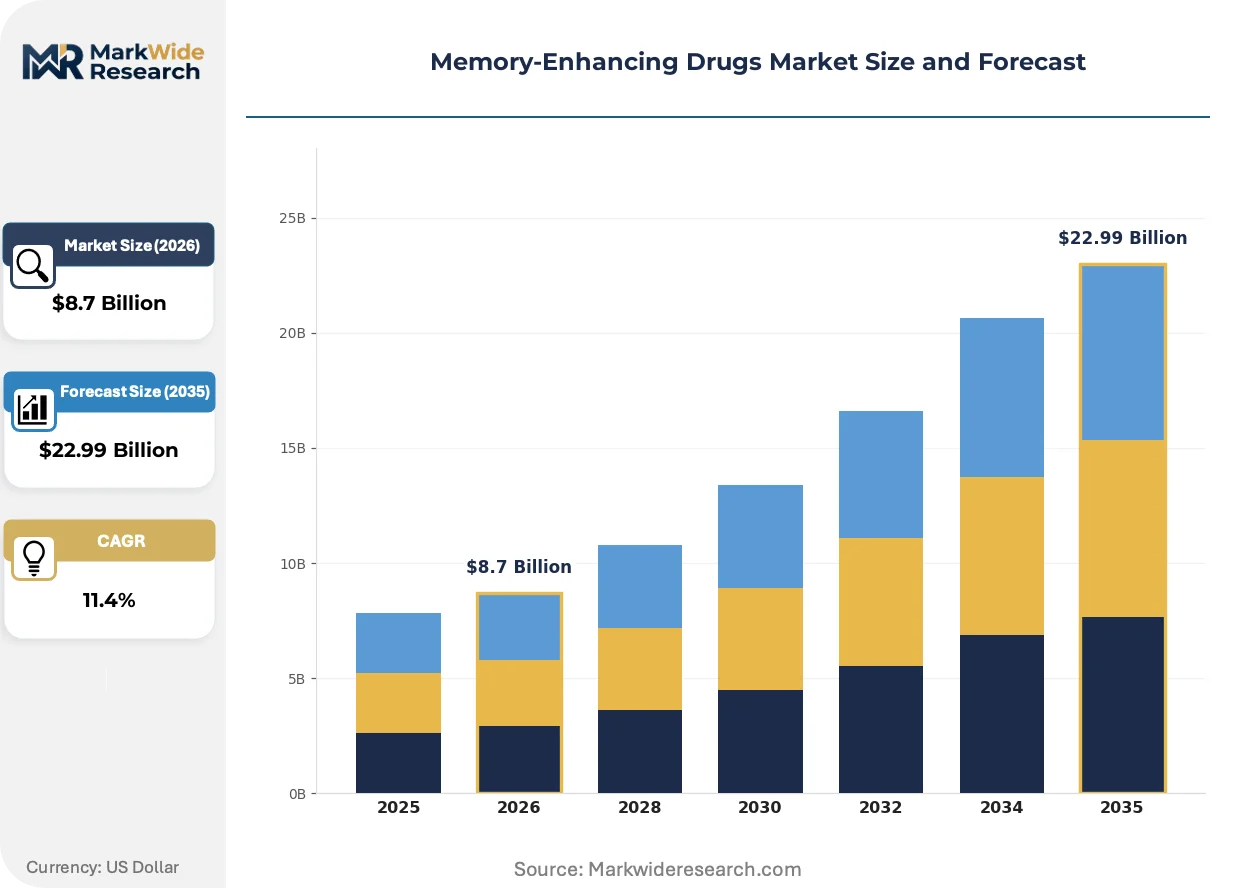
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Racetams, Cholinergics, Herbal Extracts, Nootropics Application: Alzheimer's Treatment, ADHD Management, Cognitive Dysfunction, General Memory Enhancement Delivery Mode: Oral Tablets, Capsules, Liquid Formulations, Injections End User: Clinics, Hospitals, Home Care, Research Institutions |
| Companies Covered | Pfizer Inc., Novartis AG, Johnson & Johnson, AbbVie Inc., Eisai Co. Ltd., Takeda Pharmaceutical Company Ltd., Teva Pharmaceutical Industries Ltd., Biogen Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory-Enhancing Drugs Market Shifts & Advancements
Digital biomarker platforms and decentralized trial infrastructure are displacing conventional cognitive assessment methodologies while synthetic biology approaches reshape API manufacturing economics for cholinergic compounds.
Continuous glucose monitoring-derived cerebral metabolic proxies are integrating with wearable EEG devices to enable real-time synaptic activity measurement during nootropic intervention studies. Academic research institutions in the United States and Germany are adopting these hybrid biosensor arrays at pilot scale. The technology is integrating pharmacokinetic modeling with ambulatory cognitive testing, compressing traditional 12-week efficacy readouts into 48-hour intensive monitoring windows.
The EU AI Act's risk classification framework for medical device software is forcing sponsors to revalidate algorithmic endpoints used in computerized cognitive batteries. EMA's parallel guidance on digital health technologies creates compliance overlap with existing MDR requirements for software-as-medical-device. Pediatric neurodevelopmental trials face the steepest reclassification burden, as adaptive algorithms for ADHD assessment fall under high-risk AI system definitions.
Specialty pharmacy networks are capturing nootropic distribution from traditional retail channels as prior authorization complexity for Alzheimer's therapies intensifies. United States Medicare Part D plans increasingly mandate specialty dispensing for cholinesterase inhibitors above threshold pricing tiers. This channel migration concentrates patient data capture with vertically integrated pharmacy benefit managers, altering prescriber access to real-world adherence metrics.
Memory-Enhancing Drugs Market Segmentation
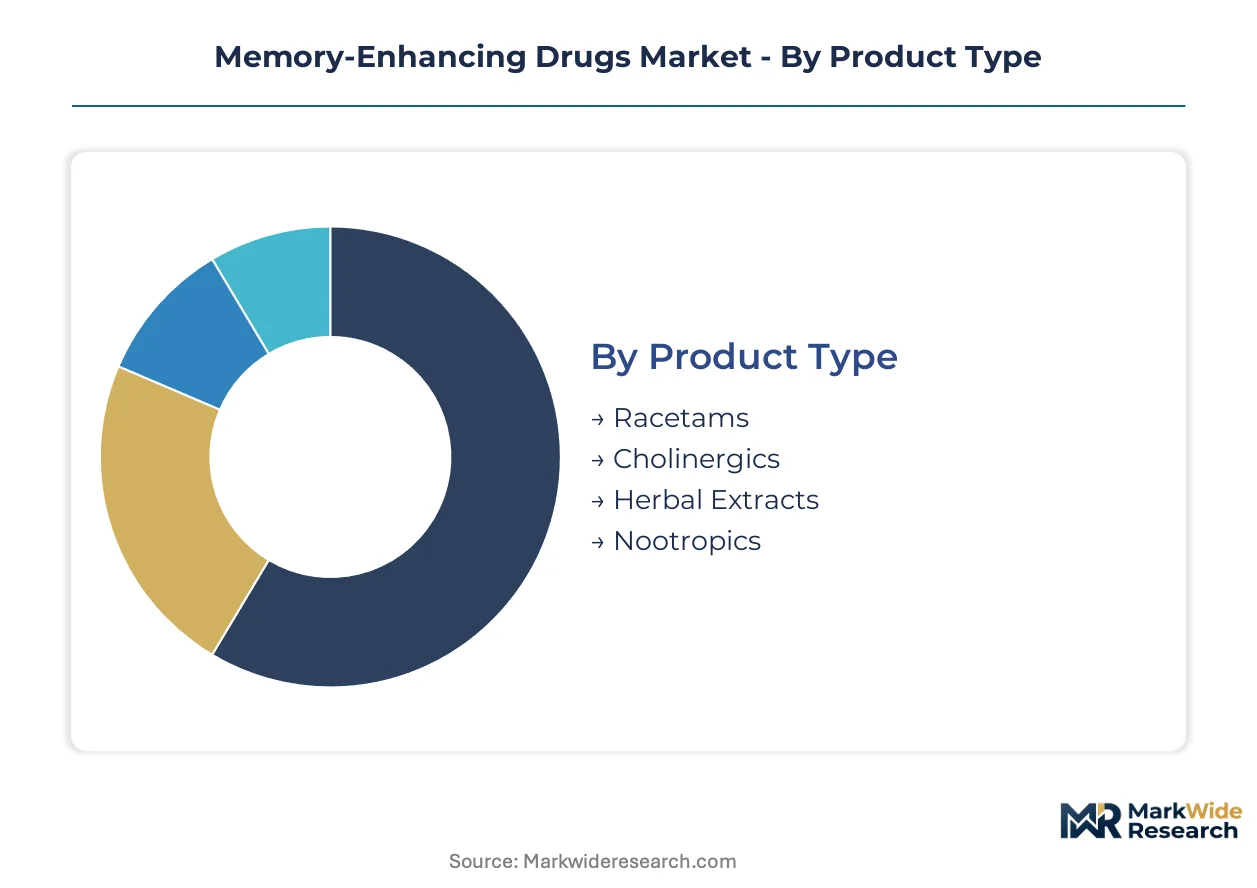
Memory-enhancing drugs fragment across four distinct segmentation axes, each reflecting divergent regulatory pathways and reimbursement economics. Product type stratification separates prescription-controlled cholinergics from unregulated nootropic compounds, while delivery mode selection directly determines pediatric versus geriatric market access.
Product Type:
Customization intensity spans from standardized synthetic racetams to proprietary botanical extraction protocols, with regulatory burden inversely correlating with formulation complexity.
- Cholinergics:Acetylcholinesterase inhibitors such as donepezil and rivastigmine constitute the prescription backbone for Alzheimer's therapeutics. United States Medicare Part D reimbursement concentrates demand among patients over 65, though generic erosion compresses margins for originator compounds.
- Nootropics:Synthetic and natural compounds targeting glutamate modulation and cerebral blood flow capture direct-to-consumer expansion through digital pharmacy channels. Regulatory arbitrage between FDA dietary supplement oversight and EMA pharmaceutical classification creates divergent commercialization strategies.
- Racetams:Piracetam and analogs occupy a regulatory gray zone in multiple jurisdictions, with CDSCO in India and PMDA in Japan imposing incompatible purity standards that fragment manufacturing scale.
- Herbal Extracts:Ginkgo biloba and bacopa monnieri formulations compete on standardized active compound certification, with European Pharmacopoeia monographs determining batch release acceptance in EU member states.
Leading the category by volume: Cholinergics. Growing fastest: Nootropics.
Application:
Clinical indication determines pricing power, with neurodegenerative disease commands securing premium reimbursement against lifestyle-oriented cognitive enhancement.
- Alzheimer's Treatment:FDA Breakthrough Therapy designation accelerates amyloid-targeting approvals, though post-marketing neuropsychiatric monitoring inflates compliance costs. The indication anchors prescription volumes for cholinesterase inhibitors across United States long-term care facilities.
- ADHD Management:Pediatric dose titration requirements favor liquid formulations over fixed-dose tablets, with United States school-based medication administration protocols driving formulary preferences. Stimulant versus non-stimulant mechanism selection varies by prescriber specialty and state-level controlled substance monitoring.
- Cognitive Dysfunction:Post-stroke and traumatic brain injury applications concentrate in hospital discharge protocols, with rehabilitation center partnerships determining regional prescribing patterns.
- General Memory Enhancement:Healthy adult demand flows through direct-to-consumer channels, evading traditional gatekeeper economics but exposing sponsors to FTC advertising scrutiny.
Highest reimbursement attaches to Alzheimer's Treatment. Steepest expansion trajectory belongs to General Memory Enhancement.
Delivery Mode:
Manufacturing asset intensity escalates from conventional oral solid dosage to aseptic injectable capacity, with pediatric flexibility commanding formulation premiums.
- Oral Tablets:Cholinergic standard of care leverages high-speed compression equipment with established bioequivalence frameworks. United States ANDA filings for generic donepezil tablets dominate FDA approval queues.
- Liquid Formulations:Dose titration flexibility in ADHD management commands specialty pharmacy dispensing premiums. Pediatric palatability engineering and stability testing extend development timelines versus solid dosage equivalents.
- Capsules:Encapsulation of racetam powders and herbal extracts accommodates smaller batch sizes for niche nootropic brands. Gelatin versus vegetarian shell selection influences European market access under EFSA labeling requirements.
- Injections:Amyloid-targeting biologics require cold chain infrastructure and infusion center networks, concentrating distribution with vertically integrated specialty pharmacy operators.
Dominant manufacturing footprint: Oral Tablets. Premium positioning: Liquid Formulations.
End User:
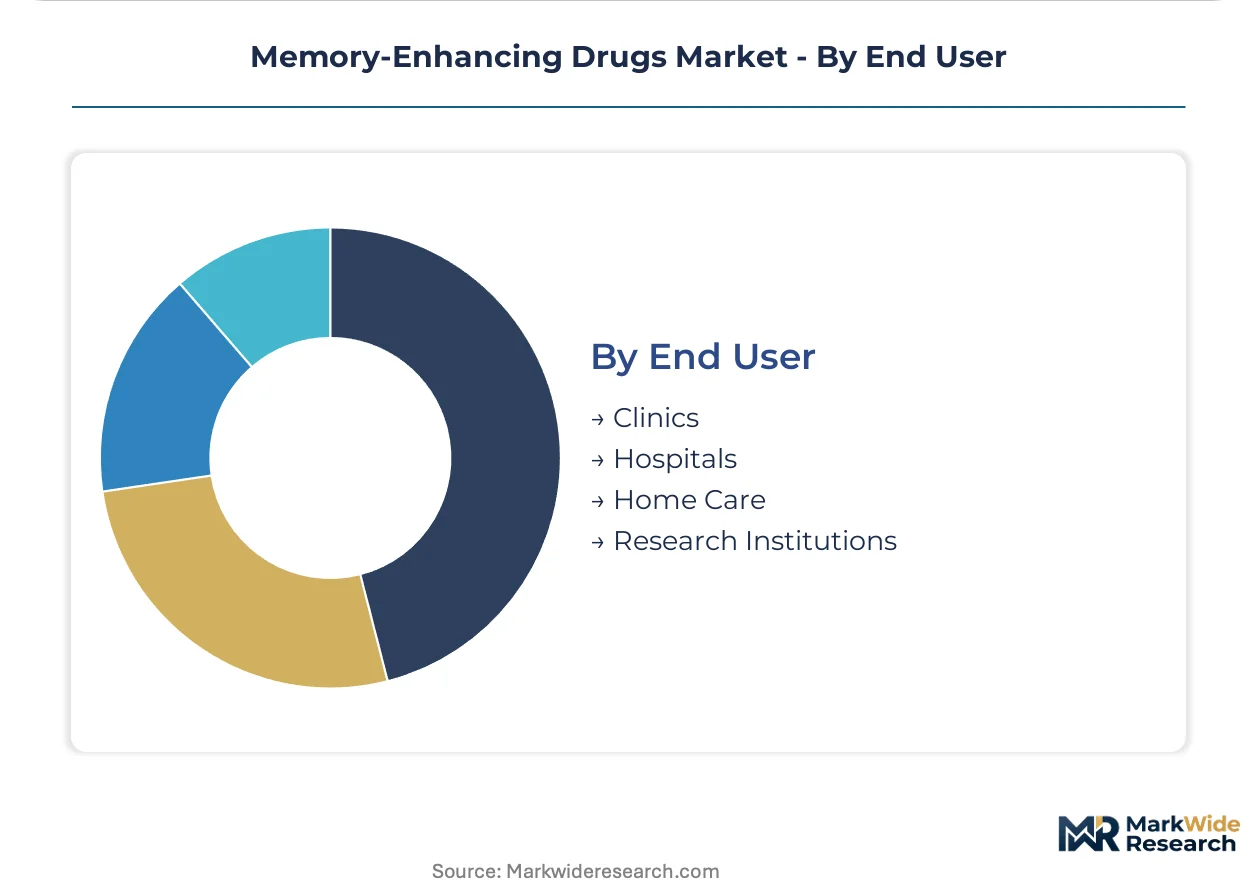
Site-of-care economics fragment procurement authority between centralized hospital formularies and decentralized home administration, with research institutions driving early adoption of novel mechanisms.
- Hospitals:Inpatient stroke protocols and perioperative cognitive protection drive acute care utilization. Pharmacy and therapeutics committees gate amyloid-targeting biologic access through restricted distribution policies.
- Clinics:Outpatient neurology and psychiatry practices concentrate Alzheimer's and ADHD prescription initiation. United States Medicare reimbursement for cognitive assessment administration influences diagnostic coding practices.
- Home Care:Caregiver-administered cholinesterase inhibitors in dementia populations shift monitoring burden to telehealth platforms. Medication adherence packaging innovations determine payer contract eligibility.
- Research Institutions:Academic medical centers in the United States and Germany pilot digital biomarker endpoints for nootropic efficacy trials. EMA PRIME eligibility criteria accelerate investigator-initiated studies.
Primary prescription volume: Clinics. Fastest-growing data capture: Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity for cholinergic precursors clusters in legacy manufacturing zones across Switzerland, Singapore, and the United States, creating geographic redundancy pressures for API supply chains.
United States
FDA Breakthrough Therapy designation accelerates amyloid-targeting approvals while Medicare Part D reimbursement anchors prescription volumes for cholinesterase inhibitors. The agency's digital biomarker guidance reshapes endpoint validation for cognition-enhancing therapies. Greater Boston hosts concentrated neuroscience research institutions piloting hybrid biosensor arrays for nootropic efficacy trials.
Germany
EMA PRIME eligibility criteria compress development timelines for novel cognitive enhancers targeting Alzheimer's pathology. The EU AI Act's risk classification framework forces sponsors to revalidate algorithmic endpoints used in computerized cognitive batteries. Academic medical centers in Munich and Heidelberg lead adoption of decentralized trial infrastructure for ambulatory cognitive testing.
Switzerland
Integrated peptide synthesis operations anchor amyloid-targeting compound manufacturing for European distribution. Swissmedic maintains alignment with EMA neuropsychiatric safety monitoring requirements while offering parallel consultation pathways. The Basel region concentrates captive fermentation capacity for racetam precursor supply chains.
Japan
PMDA imposes divergent bioequivalence standards for generic racetams that fragment regulatory submission strategies from FDA and EMA pathways. Aging demographics over 65 expand addressable prescription volumes for acetylcholinesterase inhibitors. The Kansai region hosts specialized formulation facilities for liquid ADHD preparations requiring dose titration flexibility.
India
CDSCO bioequivalence testing protocols for cholinergic compounds create regulatory arbitrage opportunities for export-oriented manufacturers. Domestic demand for herbal nootropic extracts flows through direct-to-consumer channels evading traditional gatekeeper economics. Hyderabad and Ahmedabad clusters specialize in generic donepezil tablet production for ANDA filings.
Memory-Enhancing Drugs Market Competitive Landscape
Capacity expansion dominates the current landscape as sponsors pursue geographic redundancy in API supply chains. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with captive fermentation assets, mid-cap peptide synthesis specialists, and generic manufacturers competing on regulatory submission velocity. Strategic archetypes include amyloid-targeting innovators, cholinergic standard-of-care defenders, and nootropic direct-to-consumer disrupters. Vertical integration and specialty pharmacy network partnerships represent the dominant competitive moves.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Novartis AG exemplify divergent supply chain strategies. Pfizer leverages captive fermentation capacity to secure racetam precursor supply chains, while Novartis anchors its position through integrated peptide synthesis operations spanning Switzerland and Singapore. Eisai Co. Ltd. occupies a distinct archetype as an amyloid-targeting specialist competing on regulatory submission velocity rather than manufacturing scale. These three companies represent the spectrum from scale-driven API security to mechanism-focused development speed.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| AbbVie Inc. |
| Eisai Co. Ltd. |
| Takeda Pharmaceutical Company Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Biogen Inc. |
| Sanofi |
| Others |
Supply & Pricing Matrix
Synthetic biology fermentation methods for racetam precursor production are compressing unit economics while redistributing manufacturing scale toward captive bioreactor networks in Switzerland and Singapore. This technological transition simultaneously erodes legacy contract manufacturing margins and concentrates pricing power with sponsors controlling in-house peptide synthesis operations.
Pricing Analysis
Service bundling separates amyloid-targeting biologics with mandatory post-marketing neuropsychiatric monitoring from unbundled nootropic compounds sold through direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Breakthrough Therapy certification status, geographic delivery cost to infusion centers, and volume scale of cholinesterase inhibitor procurement. Pricing pressure stems from generic erosion in donepezil tablets as ANDA filings accumulate in FDA approval queues. Hospital formularies exhibit highest price sensitivity for acute care cognitive dysfunction indications, while specialty pharmacy networks command premium capture for Alzheimer's therapies with restricted distribution requirements.
Supply Chain Analysis
Cholinergic precursor supply rests on fermentation capacity clusters in Switzerland, Singapore, and the United States, with peptide synthesis inputs drawing from German and Japanese specialty chemical producers. Raw material dependencies span acetylcholinesterase enzyme cultures, racetam synthetic intermediates, and amyloid-targeting monoclonal antibody cell lines. Single-source vulnerability concentrates in legacy contract manufacturing relationships for generic tablet production, exposing sponsors to geographic disruption risk. Distribution runs through vertically integrated specialty pharmacy networks for biologic formulations, while direct-to-consumer digital channels capture nootropic volume outside traditional gatekeeper control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The memory-enhancing drugs market reads as a cost-of-compliance story where FDA post-marketing neuropsychiatric safety monitoring requirements and EMA digital biomarker revalidation obligations create regulatory moats favoring sponsors with established pharmacovigilance infrastructure.
For Market Incumbents: Cement API supply security through captive fermentation capacity additions in Singapore and Switzerland, insulating against single-source vulnerability in legacy contract manufacturing zones. Defend formulary positioning for cholinesterase inhibitors by accelerating digital biomarker endpoint validation ahead of EU AI Act enforcement timelines, neutralizing emerging entrant threats from direct-to-consumer nootropic disrupters lacking regulatory submission velocity. For New Entrants and Emerging Players: Direct-to-consumer telehealth platforms offer the most penetrable route for racetam and herbal extract formulations evading traditional gatekeeper economics. Target pediatric ADHD liquid formulation white space where dose titration flexibility commands premium formulary positioning unavailable to fixed-dose tablet incumbents. Deploy outcome-based cognitive assessment partnerships with academic medical centers to establish efficacy differentiation against unregulated supplement competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated pharmaceutical conglomerates seeking amyloid-targeting pipeline assets and geographic redundancy in peptide synthesis operations. Five-to-ten-year viability favors sponsors with FDA Breakthrough Therapy designations and EMA PRIME eligibility securing compressed development timelines. Watch FDA digital biomarker guidance finalization as inflection indicator for algorithmic endpoint validation capabilities becoming table stakes for cognition-enhancing therapy development.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses amyloid-targeting development timelines against standard review queues. |
| Backward Integration | Captive fermentation capacity in Switzerland and Singapore secures racetam precursor supply against single-source vulnerability. |
| Digital Biomarker Validation | EU AI Act compliance for algorithmic cognitive endpoints creates first-mover advantage in EMA submissions. |
| Specialty Pharmacy Partnership | Vertically integrated distribution networks capture Alzheimer's therapy volume under Medicare Part D restricted dispensing mandates. |
| Pediatric Formulation Development | Liquid ADHD preparations with dose titration flexibility command premium positioning in school-based medication administration protocols. |
Research Methodology
Document review covered FDA Breakthrough Therapy designation records, EMA PRIME eligibility submissions, and ClinicalTrials.gov nootropic intervention protocols, complemented by interviews with drug development executives at amyloid-targeting sponsors, regulatory affairs leads navigating divergent bioequivalence standards, formulary directors at United States Medicare Part D plans, and procurement managers at specialty pharmacy networks. Secondary validation drew from SEC 10-K pharmaceutical filings, Swissmedic parallel consultation pathway documentation, and PMDA generic racetam approval records. Bottom-up prescription volume modeling triangulated against top-down market sizing from reimbursement database analysis.
Historical prescription trends for cholinesterase inhibitors and racetam compounds were cross-referenced against expert panel inputs from academic medical center investigators piloting digital biomarker endpoints. The analytical framework segmented across product type, application, delivery mode, and end user, with regional regulatory cluster effects modeled throughout the forecast period. CAGRs derived from patent expiration timelines for branded Alzheimer's therapies, generic erosion curves, and direct-to-consumer channel expansion trajectories for nootropic compounds. Inputs included FDA digital biomarker guidance development status and EU AI Act enforcement timeline assumptions.
The model holds under stable FDA accelerated approval pathway continuity and consistent EMA neuropsychiatric safety monitoring requirements; deviation in regulatory reclassification of nootropic compounds as pharmaceutical rather than dietary supplement status would shift volume projections materially. Forecasts reflect assumptions regarding specialty pharmacy network consolidation and digital health platform channel capture. A small set of named triggers warrants ongoing watch: FDA digital biomarker guidance finalization, EU AI Act high-risk AI system reclassification for pediatric cognitive assessment algorithms, and PMDA-CDSCO bioequivalence standard harmonization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
GLP-1 Receptor Agonist Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Multiple Sclerosis Drugs Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Anthelmintic Drugs Market