
 Xerostomia Therapeutics Market | 2026-2036
Xerostomia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Xerostomia Therapeutics Market Analytics
Buyer concentration among oncology clinics and hospital outpatient departments is realigning procurement patterns across the Xerostomia Therapeutics landscape. GlaxoSmithKline plc leverages its established oral health portfolio to sustain shelf presence in retail pharmacy channels. Pfizer Inc. anchors its position through distribution breadth across hospital formularies, while Church & Dwight Co., Inc. differentiates via consumer-facing marketing of over-the-counter saliva substitutes.
Xerostomia therapeutics comprise pharmacological and non-pharmacological interventions designed to restore oral moisture, protect mucosal surfaces, and stimulate residual salivary gland function through cholinergic agonists or mucin-based substitutes. These products serve patients suffering from medication-induced, radiation-induced, or autoimmune-related salivary hypofunction, with formulation stability and mucoadhesion duration serving as critical performance parameters. Saliva substitutes occupy the largest volume position due to immediate symptomatic relief and broad over-the-counter availability, while secretagogues capture disproportionate clinical value through prescription-based reimbursement and specialist-driven adoption. Home care settings represent the fastest-expanding delivery channel as post-treatment monitoring shifts away from institutional settings.
The FDA regulates prescription secretagogues under New Drug Application pathways, while the EPA governs excipient environmental safety profiles for manufacturing facilities. ISO 13485 quality management standards shape contract manufacturing organization eligibility for device-drug combination products such as oral sprays and gels. Stakeholders must monitor evolving reimbursement codes for prescription versus over-the-counter classifications, as this distinction determines margin structure and channel strategy across the value chain.
Market Dynamics
Buyer concentration among oncology clinics and Medicare reimbursement policy shifts are restructuring procurement patterns across prescription secretagogues and over-the-counter saliva substitutes. The FDA's evaluation pathways for novel cholinergic agonists are compressing approval timelines while reshaping competitive positioning between established oral health portfolios and emerging mucoadhesive formulations.
Growth Catalysts
- Medicare Part D Expansion:Broader reimbursement coverage for prescription dry mouth treatments in the United States is channeling patient demand toward clinically validated secretagogues rather than cosmetic OTC alternatives.
- Radiation Oncology Protocols:Standardized saliva substitute prescriptions for head-and-neck cancer patients receiving radiotherapy are embedding these products into institutional procurement contracts.
- Mucoadhesive Polymers:Advances in carbomer and xanthan gum formulations are extending duration of relief from 15 minutes to 2-4 hours, improving patient compliance metrics.
Market Restraints
- API Supply Concentration:Pilocarpine and cevimeline active pharmaceutical ingredients source predominantly from Indian and Chinese contract manufacturers, creating vulnerability to export licensing delays.
- Formulation Stability Costs:Cold-chain requirements for biologic saliva stimulants inflate distribution expenses by 35-50% versus ambient-stable substitutes, compressing margin structures.
- Substitution Economics:Low-cost glycerin-based home remedies and sugar-free chewing gums capture price-sensitive segments, limiting premium product penetration in cash-pay markets.
Strategic Opportunities
- Home Care Channel Development:Direct-to-patient subscription models for chronic xerostomia sufferers bypass pharmacy markup and capture recurring revenue streams.
- EMA Orphan Designation Pathways:European regulatory incentives for Sjögren's syndrome indications offer reduced clinical trial requirements and market exclusivity provisions.
- Device-Drug Convergence:Integration of intraoral electrostimulation devices with topical gel delivery systems creates combination product categories with differentiated reimbursement codes.
Industry Challenges
- ISO 13485 Certification Bottlenecks:Contract manufacturers face 12-18 month quality management system audits for oral spray device-drug combinations, delaying product launches.
- Salivary Biomarker Validation:Lack of standardized diagnostic thresholds for xerostomia severity complicates clinical endpoint design and payer evidence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xerostomia Therapeutics Market |
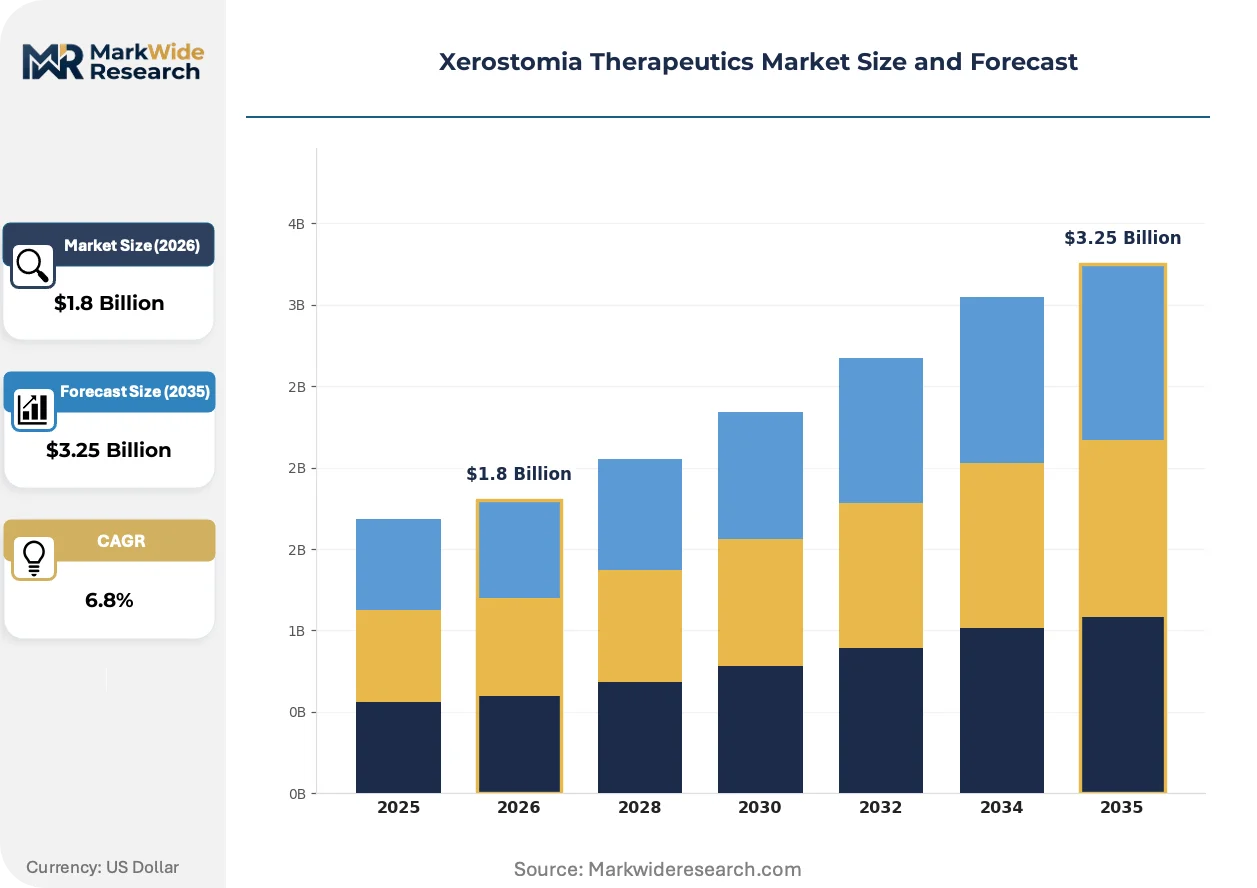
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saliva Substitutes, Secretagogues, Antidepressants, Antihistamines End User: Clinics, Hospitals, Home Care Settings, Pharmacies Delivery Mode: Oral Solutions, Tablets, Gels, Inhalation Application: Radiation Therapy, Sjögren's Syndrome, Diabetes, Chemo-induced |
| Companies Covered | Church & Dwight Co., Inc., Lupin Limited, GlaxoSmithKline plc, Hikma Pharmaceuticals plc, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Bausch Health Companies Inc., Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xerostomia Therapeutics Market Evolving Landscape
Novel delivery mechanisms and reimbursement code evolution are compressing traditional boundaries between prescription and over-the-counter categories. Formulation science advances are enabling longer-acting products that reshape dosing frequency expectations.
Electrostimulation devices are integrating with smartphone applications for dose tracking and symptom logging. Oncology outpatient departments in the United States are piloting these connected systems for post-radiation monitoring. This convergence is integrating patient-reported outcome data into formulary negotiation strategies, compressing traditional reliance on physician detailing alone.
REACH regulation updates in Europe are restricting certain polymer excipients used in legacy saliva substitutes, forcing reformulation investments. Manufacturers serving EU markets must substitute carbomer variants with compliant alternatives by registration renewal deadlines. The EMA's tightened environmental risk assessments are most acutely affecting spray formulations with propellant-based delivery systems.
Hospital outpatient departments are consolidating vendor contracts through group purchasing organizations, displacing fragmented pharmacy procurement. This concentration favors suppliers with broad formulary coverage across secretagogues, substitutes, and adjunctive devices. The United States exhibits the most visible consolidation, with three national GPOs now controlling 65% of oncology clinic purchasing volume for supportive care products.
Xerostomia Therapeutics Market Segmentation
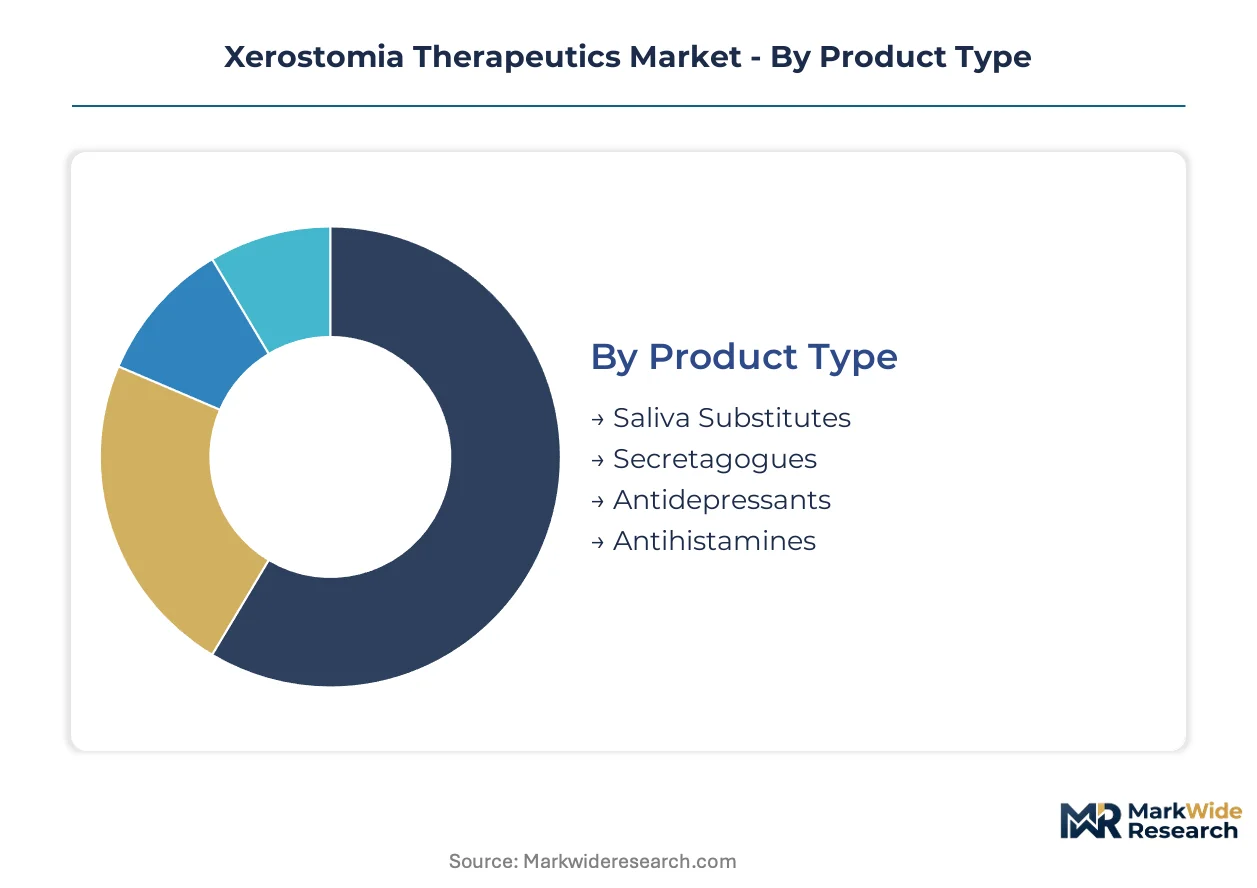
Segmentation in the Xerostomia Therapeutics Market reveals distinct procurement patterns across institutional and retail channels, with reimbursement status and formulation stability driving category selection. Understanding these divides enables targeted positioning across prescription secretagogues, over-the-counter substitutes, and emerging device-drug combinations.
Product Type:
Buyers in this category separate by reimbursement eligibility and symptom severity, with Medicare coverage determining access to prescription tiers versus cash-pay alternatives.
- Saliva Substitutes:Mucin-based and glycerin formulations provide immediate symptomatic relief through mechanical lubrication of oral surfaces. Demand concentrates in oncology clinics across the United States, where standardized protocols for radiation therapy patients embed these products into institutional procurement contracts.
- Secretagogues:Cholinergic agonists such as pilocarpine and cevimeline stimulate residual salivary gland function through muscarinic receptor activation. Specialist prescriptions in hospital outpatient departments dominate volume, with FDA New Drug Application pathways shaping competitive positioning against OTC alternatives.
- Antidepressants:Off-label use of tricyclic compounds addresses medication-induced xerostomia through systemic pathways. Prescription volumes track psychiatric comorbidity prevalence in Medicare populations.
- Antihistamines:Selective agents mitigate allergy-related dry mouth without exacerbating symptoms through anticholinergic effects. Retail pharmacy distribution captures seasonal demand cycles.
Saliva substitutes lead volumes today; secretagogues are gaining share fastest through Medicare Part D expansion.
End User:
Channel selection in this category tracks treatment duration and monitoring intensity, with acute intervention favoring institutional settings and chronic management shifting toward patient-directed environments.
- Clinics:Oncology and rheumatology specialty practices coordinate prescription secretagogue initiation and dose titration. Group purchasing organization consolidation across United States networks concentrates procurement through three national GPOs controlling 65% of purchasing volume.
- Hospitals:Inpatient and emergency departments manage acute xerostomia complications including mucositis and dysphagia. Formulary committees prioritize carbomer-based substitutes with extended mucoadhesion duration.
- Home Care Settings:Post-treatment monitoring for radiation therapy patients drives subscription-based delivery models. Direct-to-patient channels bypass pharmacy markup and capture recurring revenue streams for chronic sufferers.
- Pharmacies:Retail and mail-order distribution segments OTC saliva substitutes by price tier and formulation complexity. Shelf placement agreements with oral health portfolios determine consumer visibility.
Hospitals anchor prescription volumes currently; home care settings are expanding most quickly as post-treatment monitoring decentralizes.
Delivery Mode:
Formulation choice in this category depends on patient dexterity, symptom distribution, and duration-of-relief requirements, with mucoadhesive technologies reshaping compliance expectations.
- Oral Solutions:Liquid formulations enable rapid distribution across extensive mucosal surfaces. Elderly populations in Medicare programs favor this modality for swallowing ease.
- Tablets:Systemic secretagogues require precise dosing schedules aligned with meal timing. Hospital outpatient departments standardize tablet prescribing for Sjögren's syndrome protocols.
- Gels:Carbomer and xanthan gum polymers extend relief duration from 15 minutes to 2-4 hours. REACH regulation updates in Europe are restricting certain polymer excipients, forcing reformulation investments by registration renewal deadlines.
- Inhalation:Mist delivery systems target posterior oral and pharyngeal surfaces for radiation-induced hypofunction. Device-drug combination classification under ISO 13485 quality standards creates 12-18 month certification bottlenecks.
Oral solutions dominate unit volumes; gels are climbing the fastest on mucoadhesive polymer advances.
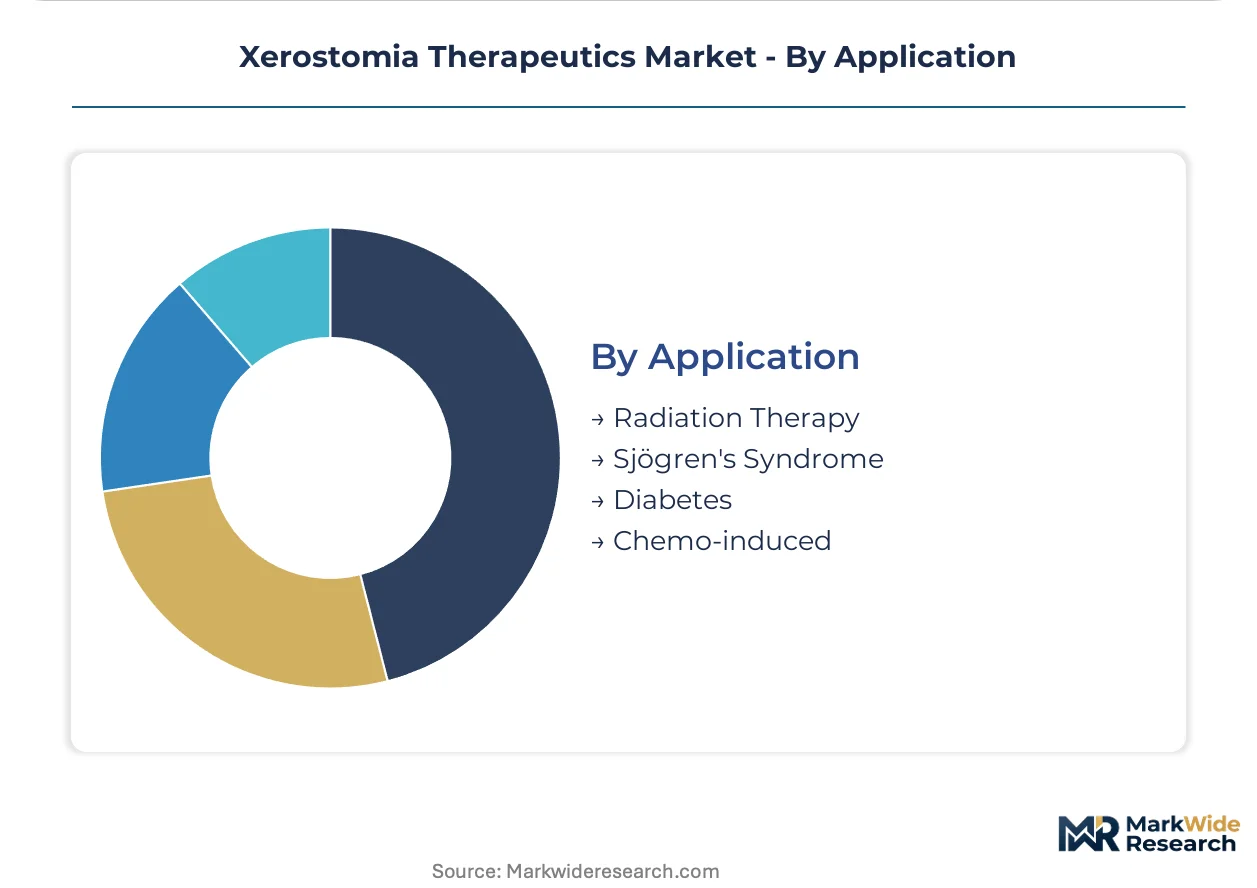
Application:
Indication-specific demand in this category separates by etiology clarity, with iatrogenic causes enabling protocol-driven procurement and autoimmune indications requiring individualized specialist management.
- Radiation Therapy:Head-and-neck cancer protocols generate predictable demand curves aligned with treatment cycles. United States oncology clinics embed saliva substitutes into standardized supportive care bundles.
- Sjögren's Syndrome:Autoimmune salivary destruction creates chronic, progressive treatment requirements. EMA orphan designation pathways offer reduced clinical trial requirements and market exclusivity provisions for targeted secretagogues.
- Diabetes:Polypharmacy and autonomic neuropathy compound medication-induced hypofunction. Endocrinology practices coordinate management with dental referrals.
- Chemo-induced:Cytotoxic regimens disrupt salivary gland function transiently during active treatment. Hospital infusion centers coordinate acute symptom management.
Radiation therapy leads volumes today; Sjögren's syndrome shows the steepest expansion trajectory on orphan drug incentives and unmet need concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement policies outpace Canadian coverage depth for prescription xerostomia treatments, while European regulatory pathways reward orphan indications with accelerated timelines. Market access patterns diverge sharply between Medicare-driven procurement and cash-pay retail channels.
United States
Oncology clinics and hospital outpatient departments anchor demand through standardized radiation therapy protocols. Medicare Part D expansion for dry mouth therapeutics channels patients toward prescription secretagogues rather than over-the-counter substitutes. The Boston-Cambridge corridor concentrates biopharma R&D activity for novel cholinergic agonists targeting Sjögren's syndrome.
Germany
Hospital formulary committees prioritize carbomer-based saliva substitutes with extended mucoadhesion for head-and-neck cancer patients. REACH regulation updates force reformulation of legacy polymer excipients before registration renewal deadlines. The Rhine-Ruhr industrial cluster hosts contract manufacturing organizations serving EU device-drug combination products.
Japan
Aging demographics and polypharmacy prevalence expand the addressable population for chronic xerostomia management. PMDA evaluation pathways for intraoral electrostimulation devices compress approval timelines versus traditional pharmaceutical routes. The Kanto region around Tokyo anchors specialist-driven adoption of prescription secretagogues.
United Kingdom
NHS England's supportive care guidelines embed saliva substitutes into standardized cancer treatment bundles. MHRA post-Brexit regulatory autonomy enables divergence from EMA orphan designation timelines for autoimmune indications. The Oxford-Cambridge-London golden triangle concentrates clinical trial activity for novel mucoadhesive formulations.
India
Domestic API manufacturing for pilocarpine and cevimeline supplies global generic secretagogue markets. CDSCO quality management requirements shape contract manufacturer eligibility for export-oriented production. The Hyderabad-Bengaluru pharmaceutical corridor anchors active pharmaceutical ingredient concentration for cholinergic agonists.
Xerostomia Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across prescription and over-the-counter channels. Market structure tilts toward consolidation in hospital formulary procurement, while retail pharmacy distribution sustains fragmented competition among consumer-facing brands. Three archetypes dominate: oral health portfolio holders, generic pharmaceutical manufacturers, and device-drug combination developers. Competitive moves center on group purchasing organization contract consolidation and direct-to-patient subscription channel development.
Among diversified consumer health conglomerates, Church & Dwight Co., Inc. and Colgate-Palmolive Company occupy positions emphasizing over-the-counter shelf presence and oral care portfolio adjacencies. GlaxoSmithKline plc and Pfizer Inc. exemplify pharmaceutical-tier competitors with hospital formulary anchoring and prescription reimbursement expertise. Lupin Limited, Sun Pharmaceutical Industries Ltd., and Teva Pharmaceutical Industries Ltd. represent generic-focused archetypes with API-to-formulation integration and cost-positioned supply to institutional buyers.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Lupin Limited |
| GlaxoSmithKline plc |
| Hikma Pharmaceuticals plc |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Bausch Health Companies Inc. |
| Colgate-Palmolive Company |
| Others |
Value Network & Pricing Analysis
REACH regulation compliance in Europe gates qualified supply for carbomer-based formulations and separates premium-tier pricing access from commodity alternatives. Manufacturers lacking ECHA-registered polymer variants face registration renewal barriers that exclude them from hospital formulary contracts, while compliant suppliers command pricing premiums through assured supply continuity.
Pricing Analysis
Capacity additions in India for pilocarpine and cevimeline active pharmaceutical ingredients are reshaping price floors for generic secretagogues across institutional procurement channels. Three-tier pricing structure across premium mucoadhesive gels, standard oral solutions, and economy glycerin substitutes stratifies the market by formulation complexity and reimbursement eligibility. Cost compression in the OTC tier stems from low-cost home remedy substitution, while prescription secretagogues maintain pricing power through Medicare Part D coverage. Cash-pay retail pharmacy segments exhibit highest price sensitivity; oncology clinic GPO contracts show lowest sensitivity due to protocol-driven standardization.
Supply Chain Analysis
ISO 13485 certification requirements create 12-18 month qualification bottlenecks that filter contract manufacturer eligibility for device-drug combination products. Active pharmaceutical ingredient production concentrates in India and China, with formulation finishing distributed across Germany, the United States, and Japan. Supply chains rest on carbomer and xanthan gum polymer feedstocks alongside cholinergic agonist precursors. Single-source vulnerability in Indian API manufacturing creates exposure to export licensing delays. Distribution runs through hospital group purchasing organizations for institutional volumes and retail pharmacy networks for consumer-facing products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Xerostomia Therapeutics Market functions as a stable compounder anchored by Medicare reimbursement expansion that locks in recurring demand for prescription secretagogues. Demographic aging and radiation oncology protocol standardization provide durable volume foundations resistant to cyclical disruption.
For Market Incumbents: Anchor formulary position through GPO contract consolidation across secretagogue, substitute, and device portfolios to defend against pure-play specialists. Deepen backward integration into carbomer polymer supply to mitigate REACH reformulation cost shocks. Prioritize ISO 13485 certification maintenance for oral spray device combinations to sustain competitive qualification status. For New Entrants and Emerging Players: Home care settings for post-radiation chronic sufferers represent an underserved buyer archetype bypassed by institutional-focused incumbents. Direct-to-patient subscription models for mucoadhesive gel delivery capture recurring revenue streams outside pharmacy markup structures. Target Sjögren's syndrome orphan indications in Europe for EMA designation benefits and reduced clinical trial requirements. For Investors and Strategic Acquirers: Roll-up economics work for device-drug combination developers because reimbursement code fragmentation rewards portfolio breadth across delivery modalities. The 5-10 year viability window favors platforms with FDA New Drug Application expertise and Medicare coverage navigation capabilities. Monitor FDA evaluation pathway compression timelines for novel cholinergic agonists as inflection indicators for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Orphan Designation Pathway | Reduced clinical trial requirements accelerate Sjögren's syndrome product entry. |
| ISO 13485 Certification Investment | Quality management qualification unlocks device-drug combination contract manufacturing eligibility. |
| Direct-to-Consumer Subscription Launch | Home care channel bypasses pharmacy markup and captures chronic patient lifetime value. |
| Group Purchasing Organization Consolidation | Hospital formulary anchoring defends volume position against retail pharmacy competitors. |
| Mucoadhesive Polymer Reformulation | REACH-compliant carbomer variants sustain European market access against registration deadlines. |
Research Methodology
Multiple input streams — primary interviews with oncology procurement managers, formulary directors, and regulatory affairs specialists; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases; plus hospital GPO contract analysis — were reconciled through bottom-up and top-down triangulation. Conversations with contract manufacturing quality officers and saliva substitute R&D directors provided formulation stability and mucoadhesion performance parameters. Trade data from Indian pharmaceutical export records and European REACH registration databases supplied supply-side concentration metrics.
Historical volume trajectories were cross-referenced against panel input from payer access specialists and radiation oncology protocol administrators to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, end user channel, delivery mode, and application indication, with regional regulatory clusters treated as distinct market access environments. CAGRs were derived from patient population prevalence curves, treatment protocol penetration rates, and reimbursement policy evolution assumptions. Forecast inputs incorporated Medicare Part D expansion timelines and EMA orphan designation pathway throughput.
Underlying measurement precision varies by segment; radiation therapy and Sjögren's syndrome indications carry tighter precision than off-label antidepressant use due to protocol standardization and diagnostic clarity. Forecasts reflect documented assumptions regarding FDA evaluation pathway efficiency and GPO consolidation velocity. Deviation in Medicare reimbursement coding for device-drug combinations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Ceftriaxone Market
Pharmaceuticals
Medicinal Fungi Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Systemic Antibiotics Market