
 Pain Management Drugs Market | 2026-2036
Pain Management Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Management Drugs Market Intelligence
The market's therapeutic focus is shifting from acute postoperative care towards long-term management of chronic pain conditions. This transition favors companies with deep portfolios in neuropathic and inflammatory pain. Pfizer leverages its extensive R&D capabilities to develop novel non-opioid analgesics. Novartis AG specializes in targeted therapies for specific pain pathways, while Teva Pharmaceutical Industries Ltd. competes on the strength of its generic and specialty drug offerings.
Pain management drugs are pharmaceutical agents designed to alleviate pain by acting on the central or peripheral nervous system. These compounds modulate pain signals through mechanisms like inhibiting cyclooxygenase enzymes or binding to specific neural receptors. While the NSAIDs product segment remains a high-volume category, significant investment is flowing into therapies for Neuropathic Pain. Concurrently, Online Pharmacies are expanding their share of the distribution channel mix for chronic condition management.
In the United States, the FDA's Risk Evaluation and Mitigation Strategies (REMS) for opioids place strict controls on prescribing and distribution. Similarly, the European Medicines Agency (EMA) maintains a high bar for clinical efficacy and safety data before granting market authorization for new analgesics. Navigating this complex regulatory environment while developing effective, non-addictive alternatives to traditional opioids is the central challenge for drug developers.
Market Dynamics
The central dynamic shaping the pain management drugs market is the intense regulatory pressure to shift away from opioids. This force, exemplified by programs like the FDA's REMS, is compelling a market-wide pivot towards developing novel, non-addictive analgesics.
Growth Catalysts
- Demographic Shifts:Aging populations in developed economies like Germany and Japan are experiencing a higher prevalence of chronic pain conditions, such as osteoarthritis and lower back pain, which require long-term pharmacological management.
- Neuropathic Pain Focus:Significant research and development investment is being directed toward understanding and treating neuropathic pain, creating a pipeline of targeted therapies for conditions like diabetic peripheral neuropathy and fibromyalgia.
- Regulatory Incentives:The FDA's provision of fast-track and breakthrough therapy designations for non-opioid analgesics shortens development and review timelines, encouraging innovation in safer pain relief alternatives.
Market Restraints
- Patent Expiration:The loss of market exclusivity for several high-revenue blockbuster pain drugs exposes them to competition from lower-priced generics, which erodes revenue streams that fund future R&D.
- Stringent Efficacy Hurdles:Regulatory bodies like the European Medicines Agency (EMA) maintain a high bar for demonstrating clinical superiority over existing treatments, making market authorization for new analgesics a costly and lengthy process.
- Payer Reimbursement Policies:In markets such as the United States, health insurers and pharmacy benefit managers often favor less expensive generic options, limiting market access for new, premium-priced branded drugs without substantial proven benefits.
Strategic Opportunities
- Biomarker Discovery:Identifying and validating specific biomarkers for pain can enable the development of personalized medicine approaches, improving patient stratification for clinical trials and tailoring treatments for higher efficacy.
- Digital Therapeutic Integration:Combining prescription analgesics with digital health applications for pain tracking, adherence monitoring, and behavioral therapy creates new value-added services and improves patient outcomes.
- Underpenetrated Disease Areas:There is significant opportunity in developing effective therapies for difficult-to-treat pain conditions, such as chronic pelvic pain or central sensitization syndromes, where current options are limited.
Industry Challenges
- High Placebo Response:The inherently subjective nature of pain and the significant placebo effect observed in clinical trials complicate the statistical demonstration of a drug's efficacy, requiring larger and more complex study designs.
- Translational Research Gap:Promising results from preclinical animal models of pain often fail to translate into effective treatments in human clinical trials, representing a major hurdle in drug development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Management Drugs Market |
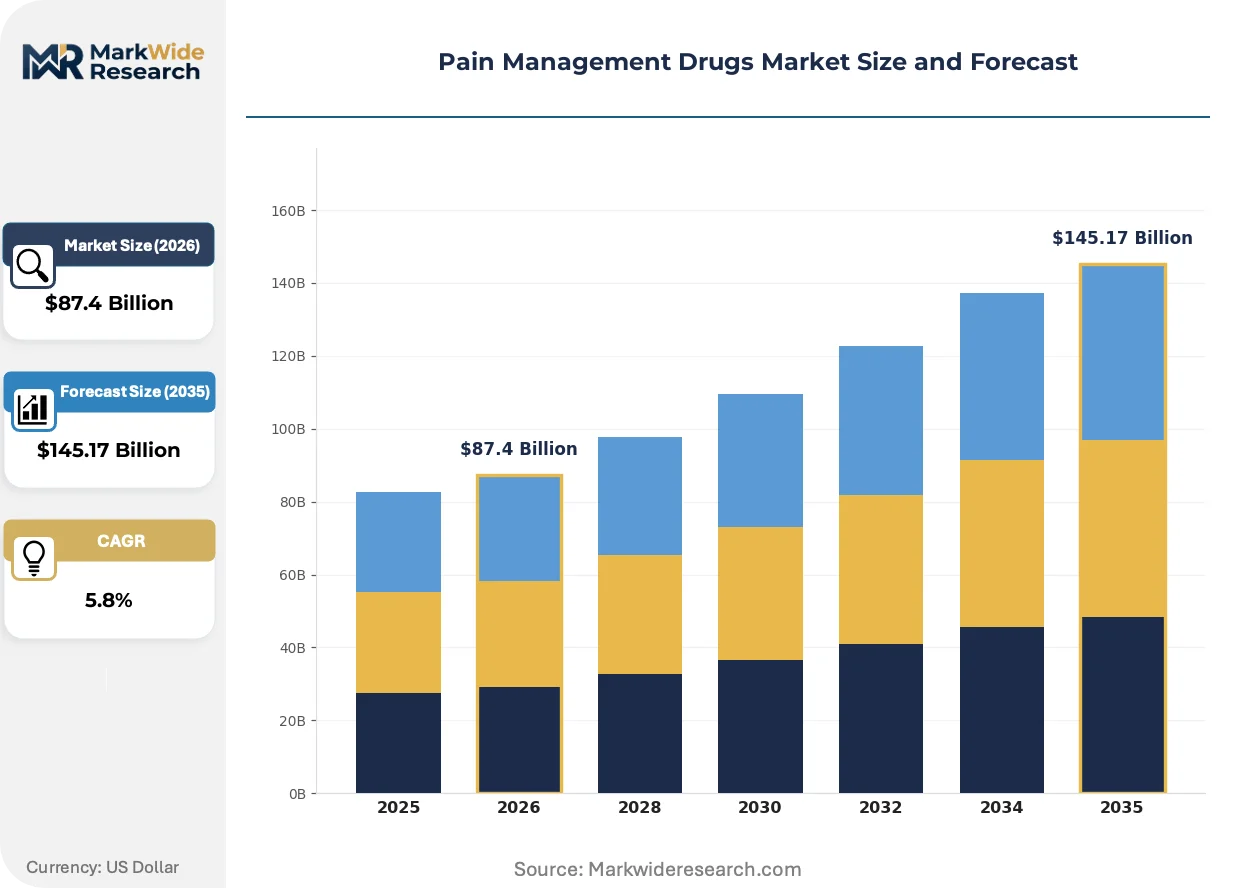
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Opioids, NSAIDs, Acetaminophen, Antidepressants, Anticonvulsants Therapy Area: Chronic Pain, Neuropathic Pain, Postoperative Pain, Inflammatory Pain, Cancer Pain End User: Hospitals, Ambulatory Surgical Centers, Pain Clinics, Home Healthcare Providers Distribution Channel: Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Pfizer, Teva Pharmaceutical Industries Ltd., Abbott Laboratories, Endo International, Novartis AG, GlaxoSmithKline, Merck & Co., Inc., Sanofi, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Management Drugs Market Strategic Shifts & Innovations
Regulatory mandates and technological advancements are creating a dual-sided pressure that is fundamentally reshaping the therapeutic landscape. This environment favors precision, safety, and new modes of patient engagement over broad-spectrum, high-risk legacy treatments.
Biologic therapies, particularly monoclonal antibodies, represent a significant evolution in treatment mechanisms. These large-molecule drugs function by targeting specific proteins involved in pain signaling, such as nerve growth factor or calcitonin gene-related peptide. Chronic pain specialists are increasingly adopting these for specific conditions like migraine and osteoarthritis. This precision-targeted approach is expanding into therapeutic areas historically dominated by less specific small-molecule drugs.
Mandates like the FDA's Risk Evaluation and Mitigation Strategies (REMS) for opioids have profound commercial consequences. The program's requirements for prescriber education and strict dispensing protocols create significant operational burdens for opioid manufacturers and distributors. Consequently, the opioid product category faces substantial headwinds, intensifying the search for non-opioid analgesics that are not subject to these controls.
Patient purchasing behavior is shifting with the rise of online pharmacies for managing long-term conditions. This trend disrupts the traditional distribution model centered on physical pharmacies, particularly for patients on stable, recurring prescriptions. This channel shift is most visible in the United States and parts of Europe, where convenience and potential cost savings drive adoption for chronic care medications.
Pain Management Drugs Market Segmentation
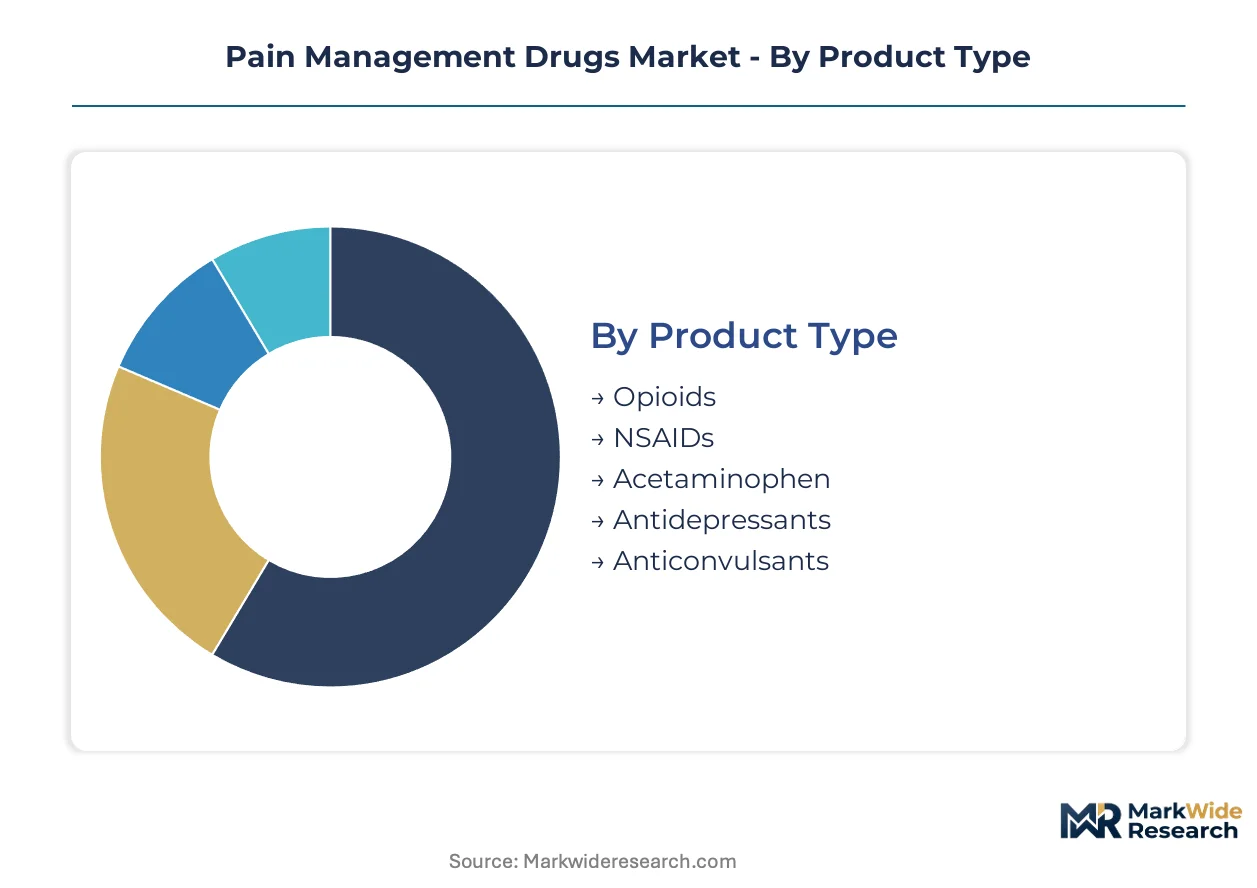
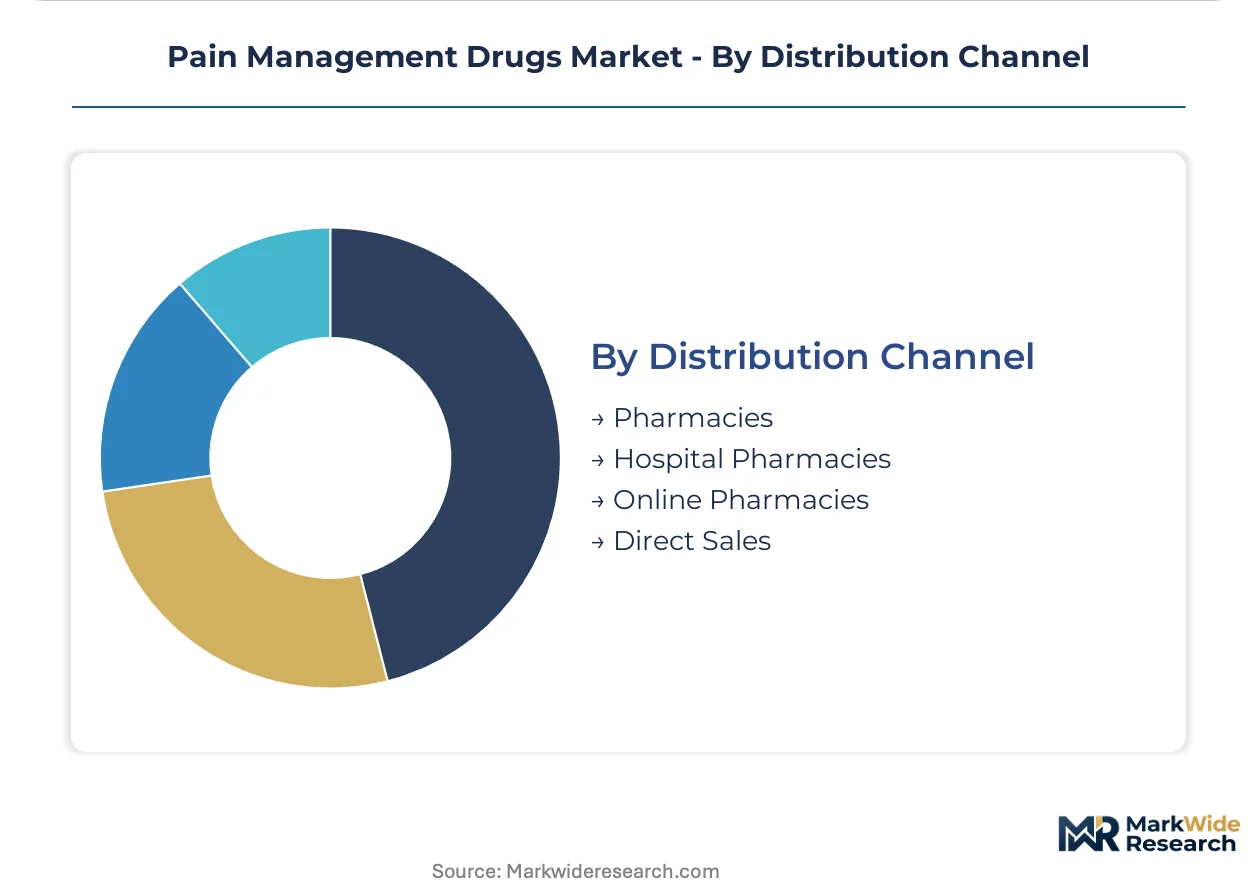
The pain management drugs market segments across distinct product types, therapy areas, end-user settings, and distribution channels. Understanding these divisions reveals where therapeutic innovation is occurring and how patient access is evolving within the complex pain treatment landscape.
Product Type:
Supply concentration for pain management drugs is currently distributed across several established pharmaceutical classes, each with unique mechanisms of action and regulatory profiles.
- NSAIDs:Non-steroidal anti-inflammatory drugs reduce pain and inflammation by inhibiting cyclooxygenase enzymes, making them a high-volume category for mild to moderate pain. Demand for these agents remains high in over-the-counter and prescription formulations across developed economies like Germany and Japan due to widespread chronic inflammatory conditions.
- Opioids:These potent analgesics bind to opioid receptors in the central nervous system, providing significant pain relief but carrying substantial risks of addiction and respiratory depression. Regulatory frameworks, such as the FDA's REMS program in the United States, are intensely focused on controlling their prescribing and distribution.
- Acetaminophen:This widely used analgesic reduces pain and fever, often serving as a first-line treatment for various acute and chronic pain conditions with a favorable safety profile at recommended doses.
- Antidepressants:Certain antidepressant classes, particularly tricyclic antidepressants and serotonin-norepinephrine reuptake inhibitors, are effective in managing neuropathic pain and chronic pain conditions beyond their mood-altering effects.
- Anticonvulsants:Originally developed for epilepsy, specific anticonvulsant drugs have demonstrated efficacy in treating neuropathic pain by modulating nerve excitability.
Today's leader: NSAIDs. Tomorrow's challenger: Antidepressants.
Therapy Area:
The volume of patients requiring treatment in specific therapy areas significantly influences research investment and market development within pain management.
- Chronic Pain:Defined as pain lasting longer than three to six months, chronic pain represents the largest and most complex therapy area, encompassing conditions like osteoarthritis and lower back pain. Demand is concentrating in aging populations globally, particularly in Europe and East Asia, where long-term management strategies are critical.
- Neuropathic Pain:This type of pain arises from nerve damage or dysfunction, characterized by symptoms like burning or shooting sensations, and requires targeted therapies. Significant investment is flowing into novel treatments for conditions such as diabetic peripheral neuropathy, driving the development of new drug candidates.
- Postoperative Pain:Acute pain experienced after surgical procedures, requiring short-term, effective analgesia to facilitate recovery and prevent complications.
- Inflammatory Pain:Pain associated with inflammation, common in conditions like rheumatoid arthritis, often managed with NSAIDs and corticosteroids.
- Cancer Pain:Pain caused by cancer itself or its treatment, which can be severe and requires a comprehensive, often multi-modal, approach to management.
The segment expanding most quickly is Neuropathic Pain, driven by increased R&D investment and targeted therapy development.
End User:
Patient access points and the specialized care required for pain management differentiate the end-user landscape, shaping drug procurement and administration practices.
- Hospitals:These institutions serve as primary sites for acute pain management, including postoperative care and severe pain conditions requiring inpatient monitoring and specialized interventions. Hospitals often manage complex formularies and high-volume purchasing.
- Pain Clinics:Specialized facilities focusing exclusively on diagnosing and treating chronic and complex pain conditions through a multidisciplinary approach, often integrating pharmacological and non-pharmacological therapies. These clinics are critical for long-term chronic pain management.
- Ambulatory Surgical Centers:Outpatient facilities performing surgical procedures that do not require an overnight hospital stay, focusing on acute pain management for a shorter duration.
- Home Healthcare Providers:Professionals delivering medical care in patients' homes, managing chronic conditions and assisting with medication adherence for long-term pain management.
Patient access is increasingly mediated by Pain Clinics, while Hospitals maintain a foundational role.
Distribution Channel:
Profit margins across distribution channels are influenced by volume, regulatory requirements, and the shift towards digital platforms for medication delivery.
- Pharmacies:Traditional retail and community pharmacies serve as the primary dispensing points for prescription and over-the-counter pain medications, offering broad patient access. This channel handles the largest volume of pain drug transactions.
- Online Pharmacies:These digital platforms facilitate convenient ordering and home delivery of medications, particularly for chronic condition management, gaining share in regions like the United States and parts of Europe. Their growth is redefining patient purchasing behavior.
- Hospital Pharmacies:These pharmacies operate within hospital settings, primarily supplying medications for inpatient care, emergency services, and discharge prescriptions.
- Direct Sales:A channel where pharmaceutical manufacturers sell directly to large institutional buyers or government programs, often for specialized or high-cost therapies.
The shift towards Online Pharmacies is redefining convenience, challenging the traditional dominance of Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dominant industrial clusters like the US Northeast Corridor drive significant innovation in pain management drugs. Aging populations and rising chronic pain prevalence fuel demand across developed economies. These regions also face intense regulatory scrutiny on opioid prescribing.
United States
High prevalence of chronic conditions like osteoarthritis and significant investment in non-opioid R&D drive demand. The FDA's REMS program for opioids strictly controls their distribution, pushing innovation towards safer alternatives. The Boston-Cambridge biotech hub actively develops novel analgesics and targeted therapies.
Germany
An aging demographic experiences rising cases of lower back pain and inflammatory conditions, increasing demand for pain management solutions. The EMA maintains rigorous standards for new analgesic market authorization, emphasizing clinical efficacy. Pharmaceutical research clusters in cities like Frankfurt and Berlin focus on advanced pain research.
Japan
A rapidly aging society contributes to a high incidence of chronic pain, particularly neuropathic pain, creating substantial market needs. The PMDA evaluates new pain therapies with a focus on safety and long-term efficacy for its population. Research centers in Tokyo and Osaka are at the forefront of developing personalized pain medicine approaches.
India
Expanding healthcare infrastructure and increased diagnosis of chronic pain conditions drive market expansion for pain management drugs. The CDSCO regulates drug approvals, balancing affordability with safety standards for pain management. Hyderabad and Ahmedabad are emerging as pharmaceutical manufacturing hubs for various pain drug formulations.
China
Growing access to healthcare and a large patient base with chronic conditions fuel demand for both generic and specialty pain medications. The NMPA streamlines approval processes for innovative non-opioid analgesics, incentivizing domestic development. Shanghai and Beijing host major pharmaceutical R&D parks focusing on novel pain pathway targets.
Pain Management Drugs Market Key Industry Players
Portfolio diversification dominates the current landscape as companies adapt to regulatory pressures and shifting therapeutic needs. The market structure is moderately consolidated, with large pharmaceutical companies holding significant shares alongside niche specialists. Strategic archetypes include diversified pharmaceutical giants, specialized biotech firms, and generic drug manufacturers. Competitive moves primarily involve R&D investment in non-addictive analgesics and strategic partnerships for pipeline acceleration.
Among the diversified pharmaceutical giants, Pfizer exemplifies extensive R&D capabilities across multiple therapeutic areas, representing a broad-spectrum approach to pain management solutions. Novartis AG, a Swiss-based pharmaceutical company, occupies a position focused on targeted therapies for specific pain pathways, often leveraging advanced biologic solutions for complex conditions. Teva Pharmaceutical Industries Ltd., an Israeli-based company, anchors the segment for generic and specialty drug offerings, providing accessible options across various pain conditions and maintaining a strong market presence.
| Leading Market Players |
|---|
| Pfizer |
| Teva Pharmaceutical Industries Ltd. |
| Abbott Laboratories |
| Endo International |
| Novartis AG |
| GlaxoSmithKline |
| Merck & Co., Inc. |
| Sanofi |
| AbbVie Inc. |
| Others |
Cost & Logistics Intelligence
Highly specialized R&D talent concentrated in regions like the US Northeast Corridor drives significant labor-cost differentials, which translate directly into the premium pricing tiers for novel pain management drugs.
Pricing Analysis
Input cost pass-through for specialized active pharmaceutical ingredients (APIs) significantly influences final drug pricing, especially for targeted pain therapies. The dominant pricing model for novel analgesics is value-based, reflecting clinical efficacy and patient outcome improvements. Price differentiation stems from brand premium and demonstrated clinical superiority in specific pain pathways. Pricing softness runs through the generic segment due to intense competition and payer reimbursement policies. Health insurers and pharmacy benefit managers exhibit high price sensitivity for established compounds, while patients with complex conditions seek effective branded solutions.
Supply Chain Analysis
Single-source vulnerability sits with specialized API manufacturers, often concentrated in India and China, creating potential supply disruptions. The pain management drug supply chain relies heavily on specific raw materials and complex chemical intermediates. Regulatory restrictions on controlled substances introduce additional complexity and tight oversight throughout the manufacturing and distribution process. Logistics chokepoints, particularly for temperature-sensitive biologics, pose a structural risk. Distribution runs through a hybrid model, encompassing traditional retail pharmacies, hospital pharmacies, and expanding online pharmacy platforms for chronic care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pain management drugs market functions as a stable compounder, driven by the persistent and expanding prevalence of chronic pain conditions within aging global populations.
For Market Incumbents: Anticipate continued regulatory pressure on traditional opioid formulations, necessitating a strategic pivot towards non-addictive alternatives. Diversify R&D portfolios into novel non-opioid analgesics and targeted biologic therapies to mitigate generic erosion. Form strategic partnerships with biotech firms specializing in pain pathway research to accelerate pipeline development. Invest in clinical trial infrastructure to meet stringent efficacy hurdles set by regulatory bodies like the EMA.
For New Entrants and Emerging Players: Launch via targeted therapies for underpenetrated disease areas, such as chronic pelvic pain or central sensitization syndromes. Focus on developing non-opioid analgesics with fast-track or breakthrough therapy designations to shorten market entry timelines. The neuropathic pain segment offers significant white space due to ongoing R&D investment and unmet patient needs. Integrate digital health applications with novel compounds to offer value-added services and improve patient adherence.
For Investors and Strategic Acquirers: Diversified pharmaceutical giants are the most active acquirers in this space, seeking to bolster their non-opioid portfolios. The market offers strong long-term viability, underpinned by increasing chronic pain prevalence and demographic shifts. Target specialized biotech firms with advanced non-opioid analgesic candidates or platforms for biomarker-driven pain management. A key signal to watch is successful Phase 3 clinical trial readouts for novel mechanisms of action, indicating future market disruptors.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for non-addictive pain therapies, addressing critical patient needs. |
| Regulatory Approval Pathway | Secures faster market access for innovative non-opioid drugs, enhancing competitive advantage. |
| Licensing Agreement | Accesses novel pain signaling targets and biomarker discovery platforms, fostering innovation. |
| Manufacturing Scale-Up | Ensures consistent supply of complex biologic therapies, meeting growing specialist demand. |
| Pipeline Diversification | Reduces reliance on opioid revenues and expands therapeutic reach into chronic pain conditions. |
Research Approach
Multiple input streams — primary interviews, regulatory filings, and industry reports — were reconciled to construct a robust market view. Primary interviews engaged drug development executives, regulatory affairs leads, formulary directors, and chronic pain specialists. Secondary validation involved analysis of FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed literature. This approach employed both bottom-up market sizing and top-down validation to ensure data accuracy.
Historical market data was cross-referenced with expert panel input to project future market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, therapy area, end-user, distribution channel, and regulatory approval status. Compound Annual Growth Rates (CAGRs) were derived from a weighted average of segment-specific growth projections. Key forecast inputs included pipeline success rates for novel non-opioid analgesics and demographic shifts impacting chronic pain prevalence.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unforeseen regulatory changes or clinical trial failures. These forecasts reflect inherent assumptions regarding market dynamics and technological advancements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market