
 Hydroxyzine Market | 2026-2036
Hydroxyzine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxyzine Market Foresight
Pharmaceutical-grade API purity tiers above 99.5% is bifurcating the competitive landscape between branded manufacturers and cost-optimized generic suppliers. Pfizer Inc leverages its vertical integration into active pharmaceutical ingredient sourcing to sustain margin stability across formulation stages. Teva Pharmaceutical Industries Ltd anchors its position through dense generic portfolio breadth, while Sun Pharmaceutical Industries Ltd specializes in high-volume oral tablet production for emerging market tenders.
Hydroxyzine is a first-generation antihistamine of the diphenylmethylpiperazine class, functioning as an H1 receptor inverse agonist with additional anxiolytic and antiemetic properties through suppression of subcortical neuronal activity. Oral tablets retain the dominant revenue position due to established reimbursement pathways and patient familiarity, though liquid formulations are gaining traction in pediatric and geriatric populations where swallowing difficulties constrain solid-dose adoption. Injectable solutions command premium pricing in acute hospital sedation protocols, while extended-release development programs target compliance improvement in chronic anxiety therapy.
FDA bioequivalence requirements under 21 CFR 320 govern generic hydroxyzine approval pathways, and EMA quality guidelines for chemically synthesized APIs shape European import standards. The EPA monitors pharmaceutical manufacturing discharge limits for piperazine derivative waste streams, adding environmental compliance costs to facility operations. Stakeholders must track evolving pharmacovigilance obligations for first-generation antihistamines as regulatory agencies reassess sedation risk profiles in ambulatory settings.
Market Dynamics
FDA bioequivalence enforcement under 21 CFR 320 is intensifying compliance costs for generic hydroxyzine manufacturers while consolidating API sourcing toward vertically integrated producers with captive piperazine derivative production.
Growth Catalysts
- Behavioral health integration:Primary care protocols in the United States now embed anxiety screening, expanding prescription eligibility pools beyond psychiatric specialty settings.
- EMA quality guidelines:Harmonized API purity standards across European import inspections reduce batch rejection rates for compliant manufacturers, smoothing cross-border supply flows.
- Liquid formulation demand:Geriatric swallowing difficulty and pediatric compliance needs are accelerating hospital formulary adoption of oral solutions alongside traditional tablets.
Market Restraints
- Piperazine feedstock volatility:Petrochemical-derived starting material costs fluctuate with crude oil indices, compressing margin stability for non-integrated formulators.
- First-generation antihistamine substitution:Second-generation H1 antagonists with reduced sedation profiles capture maintenance therapy scripts in ambulatory allergy management.
- EPA discharge limits:Wastewater treatment upgrades for piperazine derivative streams add facility-level capex burdens that disadvantage smaller batch manufacturers.
Strategic Opportunities
- Extended-release development:Once-daily hydroxyzine formulations address compliance gaps in chronic anxiety therapy, opening reimbursement pathways distinct from immediate-release commoditization.
- Injectable hospital protocols:Acute sedation applications in emergency departments command premium pricing insulated from outpatient generic competition.
- India CDSCO alignment:Domestic manufacturers leveraging BIS pharmaceutical standards can capture tender volumes across South Asian and African markets with cost-optimized oral tablet supply.
Industry Challenges
- Pharmacovigilance reassessment:Regulatory agencies are re-evaluating sedation risk profiles for first-generation antihistamines in ambulatory settings, requiring label update investments and prescriber education campaigns.
- API sourcing reconfiguration:Manufacturers dependent on external piperazine supply face qualification timelines and audit burdens as FDA intensifies foreign facility inspections under the Generic Drug User Fee Amendments framework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxyzine Market |
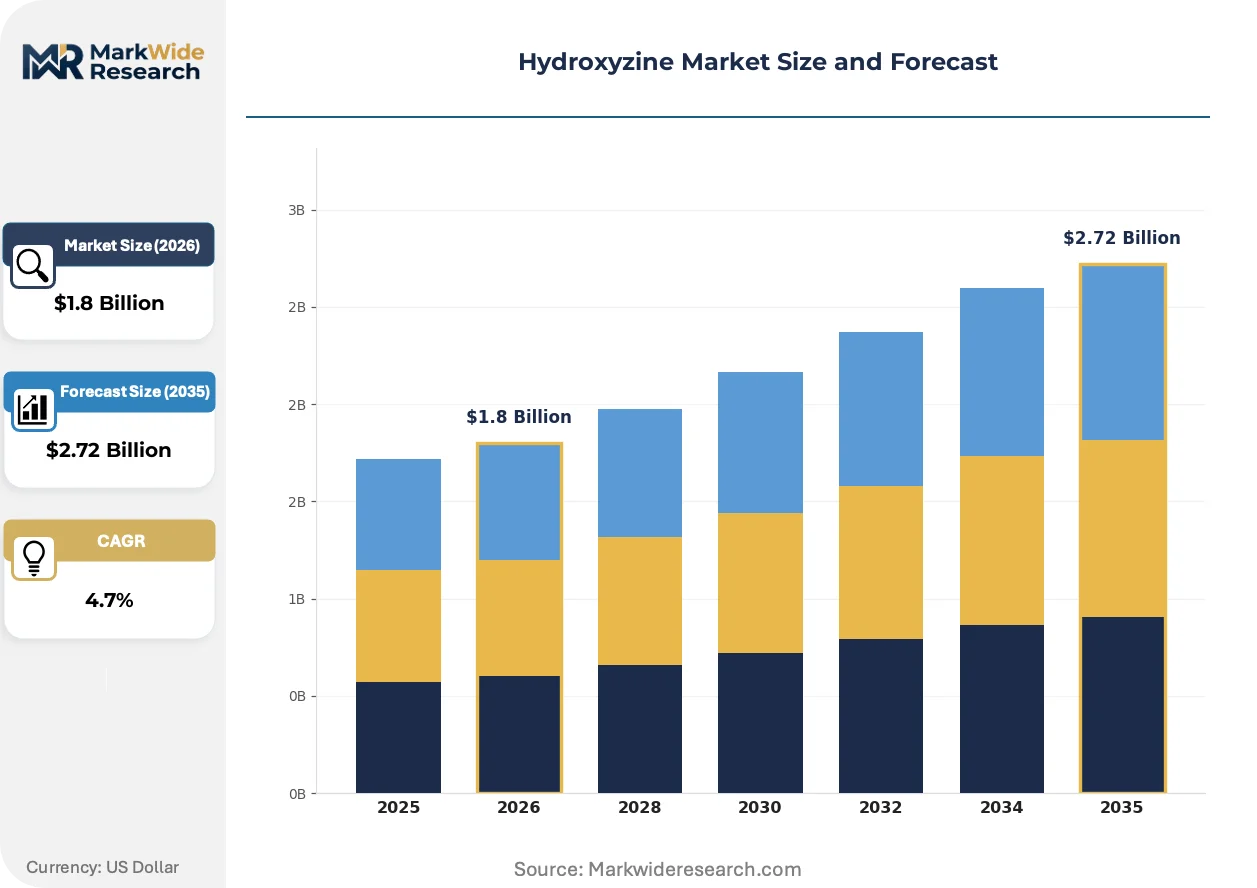
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Tablets, Oral Syrup, Injectable Solution, Topical Cream Therapy Area: Allergy Relief, Anxiety Management, Sedation, Antiemetic End User: Hospitals, Clinics, Home Care, Pharmacies Formulation: Immediate Release, Extended Release, Liquid Formulation, Compound Formulation |
| Companies Covered | Pfizer Inc, Teva Pharmaceutical Industries Ltd, GSK plc, Sun Pharmaceutical Industries Ltd, Piramal Healthcare UK Limited, Alliance Pharma PLC, Novartis International AG, Lupin Pharmaceuticals Inc, Dr. Reddy’s Laboratories Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxyzine Market Shifts & Advancements
Formulation science and regulatory science are converging to reshape hydroxyzine competitive positioning, with delivery mechanism differentiation emerging as the primary vector for margin protection against API commoditization.
Extended-release matrix technologies utilizing hydroxypropyl methylcellulose-based gelation systems are displacing immediate-release tablets in chronic anxiety maintenance scripts. Psychiatric practices in the United States are prioritizing these formulations for patient adherence programs. The technology is displacing twice-daily prescribing patterns that previously dominated long-term therapy protocols.
EMA's revised guideline on nitrosamine risk assessment in chemically synthesized APIs now requires validated analytical methods for piperazine-containing molecules. European contract manufacturers are investing in LC-MS/MS detection infrastructure to satisfy batch release requirements. Injectable hydroxyzine suppliers face the most stringent timeline pressure, with marketing authorization holders submitting risk evaluation data ahead of the regulatory deadline.
Hospital procurement consortia are consolidating anesthesia and sedation formulary decisions under centralized pharmacy and therapeutics committees. Integrated delivery networks in the United States are replacing individual hospital purchasing autonomy with system-wide contracts that favor dual-source injectable supply. This concentration is most visible in the southeastern United States, where regional health systems now negotiate hydroxyzine parenteral supply alongside propofol and midazolam bundles.
Hydroxyzine Market Segmentation
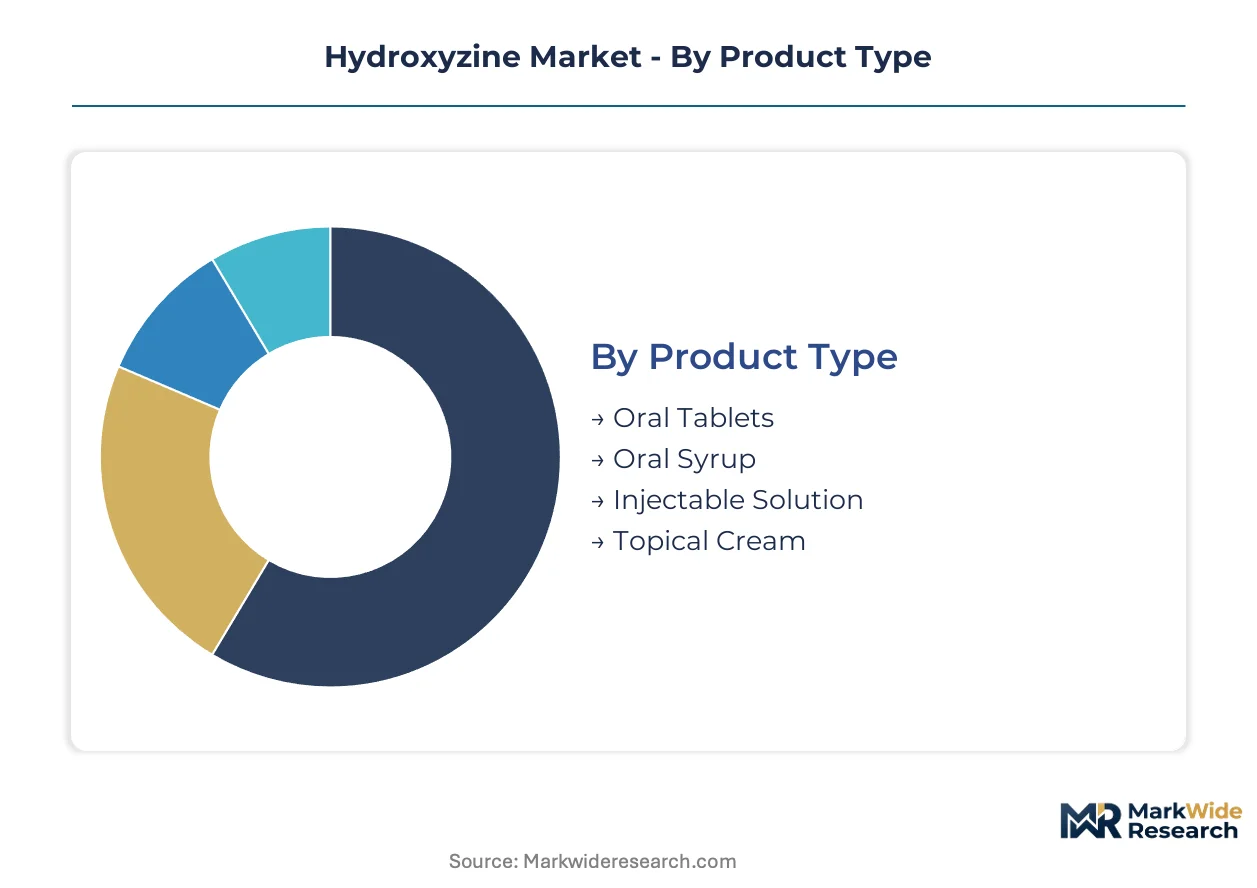
Hydroxyzine segmentation reflects divergent channel economics across acute care and ambulatory settings. Each category captures distinct margin profiles shaped by reimbursement pathways, regulatory complexity, and patient population characteristics.
Product Type:
Hospital procurement consortia and retail pharmacy chains channel different product formats based on reimbursement coding and dispensing infrastructure requirements.
- Oral Tablets:Immediate-release hydroxyzine hydrochloride and pamoate salts in 10mg, 25mg, and 50mg strengths dominate outpatient dispensing. United States retail pharmacy chains favor this format for anxiety maintenance therapy due to established Medicare Part D coverage and patient cost-sharing familiarity.
- Injectable Solution:Intramuscular hydroxyzine hydrochloride in 25mg/mL and 50mg/mL vials commands premium pricing in emergency department sedation protocols. Hospital formulary bundling with propofol and midazolam concentrates demand within integrated delivery networks.
- Oral Syrup:10mg/5mL hydroxyzine pamoate suspension serves pediatric and geriatric populations with dysphagia.
- Topical Cream:1% and 2% hydroxyzine formulations address pruritic dermatological conditions with localized H1 blockade.
Oral tablets dominate installed base. Injectable solution is where expansion concentrates.
Therapy Area:
Prescription volume distribution across therapeutic indications tracks primary care protocol adoption and specialty psychiatric referral patterns.
- Anxiety Management:Generalized anxiety disorder and pre-procedural anxiety represent the largest addressable prescription pool. United States primary care screening integration under collaborative care models expands prescriber eligibility beyond psychiatrists.
- Allergy Relief:Urticaria and pruritus management scripts face substitution pressure from second-generation H1 antagonists. Maintenance therapy concentration in allergy specialist practices preserves volume for refractory cases.
- Sedation:Pre-operative and emergency department acute agitation applications favor parenteral administration.
- Antiemetic:Post-operative nausea and chemotherapy-induced nausea prophylaxis represents niche utilization.
Anxiety management dominates installed base. Sedation applications are climbing the fastest.
End User:
Procurement authority concentration and reimbursement mechanism differentiation shape segment profitability profiles.
- Hospitals:Pharmacy and therapeutics committees govern formulary inclusion for both inpatient and emergency department utilization. Group purchasing organization contracts consolidate buying power across regional health systems.
- Clinics:Outpatient psychiatric and allergy specialty practices generate recurring maintenance prescriptions with higher generic substitution rates.
- Home Care:Hospice and palliative care agencies utilize liquid formulations for terminal agitation management.
- Pharmacies:Community and mail-order dispensing channels handle the majority of oral tablet volume for chronic therapy.
Hospitals dominate installed base. Home care is gaining share fastest.
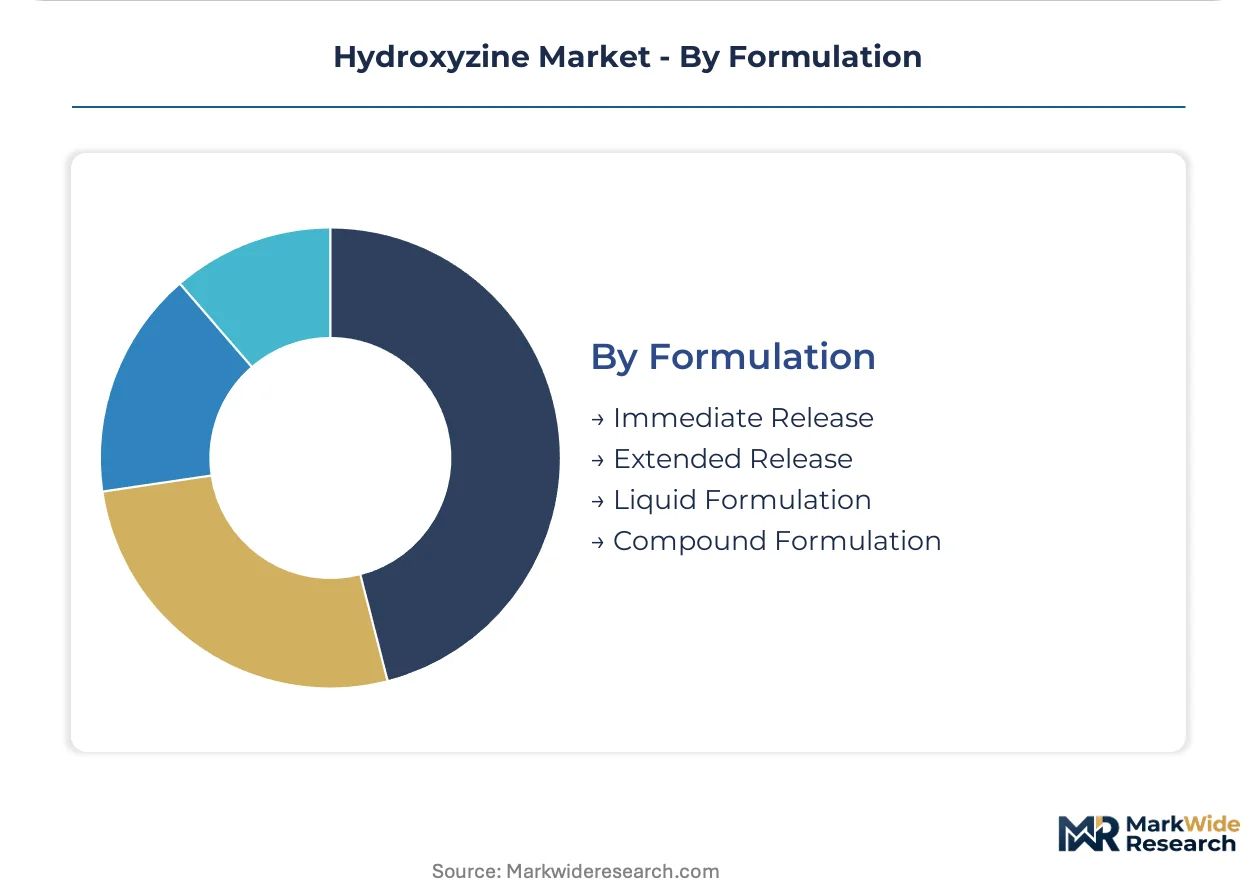
Formulation:
Development pipeline investment and manufacturing complexity separate premium-positioned formats from commoditized immediate-release supply.
- Immediate Release:Standard hydroxyzine hydrochloride and pamoate tablets face intense generic competition with bioequivalence-established interchangeability.
- Extended Release:Matrix-based hydroxypropyl methylcellulose gelation systems enable once-daily dosing for chronic anxiety adherence programs.
- Liquid Formulation:Oral solutions and suspensions address swallowing difficulty across pediatric and geriatric demographics.
- Compound Formulation:Pharmacy-compounded combinations with other agents serve niche dermatological and psychiatric applications.
Immediate release dominates installed base. Extended release represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for hydroxyzine clusters in jurisdictions with established piperazine derivative production infrastructure and favorable pharmaceutical export frameworks. Regulatory alignment on bioequivalence standards now determines cross-border market access more than tariff structures.
United States
Hospital procurement consortia and integrated delivery networks concentrate demand for injectable formulations in the Southeast and Midwest. FDA bioequivalence enforcement under 21 CFR 320 shapes generic approval timelines for oral tablet suppliers. New Jersey and North Carolina host the densest clusters of finished dose manufacturing facilities serving domestic distribution.
Germany
EMA quality guidelines for chemically synthesized APIs position German contract manufacturers as preferred suppliers for European hospital formulary tenders. The country's national pharmaceutical regulator enforces nitrosamine risk assessment protocols that exceed baseline EU requirements. Rhineland-Palatinate and Baden-Württemberg contain specialized facilities for high-purity piperazine derivative processing.
India
Domestic manufacturers leverage BIS pharmaceutical standards and CDSCO alignment to capture tender volumes across South Asian and African markets. Cost-optimized oral tablet production concentrates in Maharashtra and Gujarat, where state industrial policies support API-to-finished-dose vertical integration. Hyderabad and Mumbai anchor export-oriented formulation science capabilities.
United Kingdom
Pediatric and geriatric liquid formulation demand drives hospital formulary adoption distinct from tablet-dominant markets. The national health service procurement frameworks favor multi-source generic supply with established bioequivalence documentation. The M4 corridor and Greater Manchester host distribution infrastructure for European re-export.
Japan
PMDA quality guidelines for first-generation antihistamines impose stringent pharmacovigilance reporting requirements that filter supplier eligibility. Aging demographics amplify demand for swallowing-friendly liquid formulations in chronic anxiety maintenance. Osaka and Tokyo metropolitan areas concentrate psychiatric specialty prescribing and hospital pharmacy decision authority.
Hydroxyzine Market Competitive Landscape
Concentration sits with vertically integrated pharmaceutical conglomerates possessing captive API production and generic portfolio breadth. The competitive structure tiers between premium-positioned innovators with extended-release development pipelines and cost-optimized manufacturers competing on tender pricing. Three archetypes dominate: multinational conglomerates with full integration, mid-cap generic specialists with regional density, and emerging market exporters with scale-driven oral tablet production. Competitive moves center on backward integration into piperazine feedstock and strategic partnerships with hospital procurement consortia for injectable supply.
Within the multinational conglomerate tier, Pfizer Inc and Novartis International AG exemplify players with upstream control over active pharmaceutical ingredient sourcing. Teva Pharmaceutical Industries Ltd anchors the generic specialist archetype through portfolio breadth across dosage forms. Sun Pharmaceutical Industries Ltd occupies a position among emerging market exporters with high-volume production capabilities. Dr. Reddy's Laboratories Ltd represents the India-based manufacturer archetype targeting cost-sensitive tender markets. These named entities illustrate strategic positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Pfizer Inc |
| Teva Pharmaceutical Industries Ltd |
| GSK plc |
| Sun Pharmaceutical Industries Ltd |
| Piramal Healthcare UK Limited |
| Alliance Pharma PLC |
| Novartis International AG |
| Lupin Pharmaceuticals Inc |
| Dr. Reddy's Laboratories Ltd |
| Others |
Supply & Pricing Matrix
Second-generation H1 antagonist substitution for chronic allergy maintenance simultaneously redraws API demand geography and compresses margin structures for immediate-release hydroxyzine tablets. Petrochemical-derived piperazine feedstock volatility feeds through formulation economics, rewarding manufacturers with captive piperazine derivative production while squeezing non-integrated competitors.
Pricing Analysis
FDA bioequivalence standards under 21 CFR 320 dictate the pricing tier structure across hydroxyzine formulations, separating premium-positioned extended-release matrices from commoditized immediate-release tablets. Three-tier pricing stratifies across hospital injectable bundles, retail pharmacy oral solids, and tender-optimized generic supply, with bioequivalence documentation serving as the primary quality-grade differentiator. Cost compression in oral tablet channels intensifies as Indian CDSCO-aligned manufacturers scale export volumes, while emergency department sedation protocols preserve pricing power for parenteral formats. Retail pharmacy chains exhibit highest price sensitivity through aggressive generic substitution programs, whereas integrated delivery networks prioritize supply security over unit cost in injectable procurement.
Supply Chain Analysis
Strategic stockpiling of piperazine-derived APIs dominates inventory strategy among vertically integrated manufacturers, buffering against petrochemical feedstock volatility that disrupts just-in-time procurement for smaller formulators. API production concentrates in India, Germany, and the United States, with Maharashtra and Gujarat hosting cost-optimized oral tablet capacity while Rhineland-Palatinate specializes in high-purity piperazine processing. Manufacturing draws from piperazine, hydrochloric acid, and pamoate salt inputs, with single-source vulnerability in pharmaceutical-grade piperazine supply creating qualification bottlenecks under intensified FDA foreign facility inspections. Distribution runs through hospital group purchasing organizations, regional pharmacy wholesalers, and direct tender channels to emerging market health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary adherence programs represent a service-attach layer expanding faster than API commoditization, with psychiatric practices prioritizing compliance support over unit pricing in chronic anxiety therapy selection.
For Market Incumbents: Compound defensive positioning through backward integration into piperazine feedstock and extended-release matrix patent filings that insulate against immediate-release generic erosion. Pfizer Inc and Teva Pharmaceutical Industries Ltd exemplify the vertical integration imperative, while Sun Pharmaceutical Industries Ltd demonstrates scale-driven tender capture. FDA bioequivalence enforcement intensifies audit burdens for foreign facilities, making captive API production the priority lever for margin stability. For New Entrants and Emerging Players: Liquid formulation supply gaps in pediatric and geriatric channels present the most penetrable entry vector, with hospital formulary adoption of oral solutions outpacing tablet growth in dysphagia-prone demographics. Home care hospice agencies represent an under-served dispensing channel for terminal agitation management. A go-to-market angle anchored in BIS pharmaceutical standards alignment unlocks South Asian and African tender volumes without direct confrontation with entrenched retail pharmacy networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive piperazine supply and established hospital procurement consortia relationships. Long-term viability hinges on formulation differentiation rather than API scale, with extended-release development pipelines and injectable bundling capabilities commanding premium positioning. Watch FDA pharmacovigilance reassessments of first-generation antihistamine sedation risks as the signal for potential label-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Once-daily hydroxyzine matrices unlock distinct reimbursement pathways from immediate-release commoditization. |
| Backward Integration into Piperazine Feedstock | Captive API sourcing buffers margin volatility from petrochemical derivative price swings. |
| Hospital Procurement Consortium Partnership | Integrated delivery network contracts bundle injectable supply with propofol and midazolam formulary slots. |
| EMA Nitrosamine Risk Assessment Compliance | LC-MS/MS analytical infrastructure investments satisfy batch release requirements ahead of regulatory deadlines. |
| India CDSCO Export Alignment | BIS pharmaceutical standards certification enables cost-optimized tender capture across South Asian and African markets. |
Research Methodology
Desk research of FDA 483 inspection observations, EMA quality guideline drafts, and CDSCO tender award databases preceded structured interviews with hospital pharmacy directors, generic drug regulatory affairs leads, API procurement managers, and psychiatric formulary committee members. Secondary validation drew from EPA discharge monitoring reports, BIS pharmaceutical standard filings, and SEC 10-K pharmaceutical segment disclosures. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated against manufacturer production capacity declarations.
Variance decomposition across dosage form, therapy area, and end-user channel shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include administration route, patient population age cohort, regional regulatory cluster, and procurement authority concentration. CAGRs were derived from prescription volume trajectories, pricing elasticity coefficients, and API feedstock cost curves. Forecast inputs incorporated FDA bioequivalence approval timelines, EMA nitrosamine risk assessment compliance costs, and hospital formulary bundling contract renewal cycles.
Forecasts assume regulatory continuity in FDA 21 CFR 320 enforcement, EMA API quality guidelines, and EPA piperazine derivative discharge limits; material policy shifts would require re-modeling. Revision becomes warranted when pharmacovigilance reassessments trigger label restrictions or when piperazine feedstock price volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Liver Cancer Drug Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Pregabalin Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Norovirus Treatment Market