
 Global Anthrax Vaccine Market | 2026-2036
Global Anthrax Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anthrax Vaccine Market Foresight
Modular packaging of anthrax vaccine components is decoupling bulk antigen production from final fill-finish operations, allowing defense agencies to split procurement across multiple suppliers. Emergent BioSolutions leverages its domestic manufacturing footprint to anchor US strategic national stockpile contracts. Merck competes through sustained R&D investment in next-generation recombinant platforms. Zoetis specializes in veterinary immunization channels, occupying a distinct demand segment separate from human biodefense.
Anthrax vaccines are sterile biological preparations containing protective antigen derived from Bacillus anthracis, formulated to induce immunity against the bacterium's lethal and edema toxins through alum-adjuvanted or novel adjuvant suspensions administered via intramuscular injection. The recombinant protective antigen category leads value generation due to superior safety profiles and compatibility with modern regulatory pathways, while live attenuated vaccine demand persists in veterinary settings where cost sensitivity dominates procurement decisions. Intramuscular deployment captures the majority of military and occupational health volumes, though intranasal formulations represent the fastest-growing route as developers pursue needle-free administration for rapid mass immunization scenarios.
The FDA's Animal Rule framework and the EU's CE marking requirements under the Medical Device Regulation shape product approval trajectories, with EMA's centralized procedures adding compliance layers for European defense procurement. The WHO's prequalification standards and ISO 13485 quality management systems further constrain market access for manufacturers lacking documented GMP compliance across multiple regulatory jurisdictions. Stakeholders must monitor evolving biodefense procurement mechanisms as governments reassess pandemic-era stockpiling protocols and supplier diversification mandates.
Market Dynamics
Military biodefense procurement is fragmenting manufacturing contracts across multiple antigen suppliers, decoupling bulk production from fill-finish operations and eroding single-source dependencies in national stockpile management.
Growth Catalysts
- BARDA-funded procurement mechanisms:The US Biomedical Advanced Research and Development Authority sustains multi-year advanced development contracts for recombinant protective antigen candidates, creating predictable revenue visibility for qualified manufacturers.
- NATO member state stockpile expansion:Defense ministries across the alliance are mandating 90-day civilian prophylaxis coverage ratios, driving parallel procurement streams for both pre-exposure and post-exposure indications.
- FDA Animal Rule pathway maturation:This regulatory framework enables licensure based on efficacy in relevant animal models when human challenge studies are unethical, compressing approval timelines for biodefense-relevant formulations.
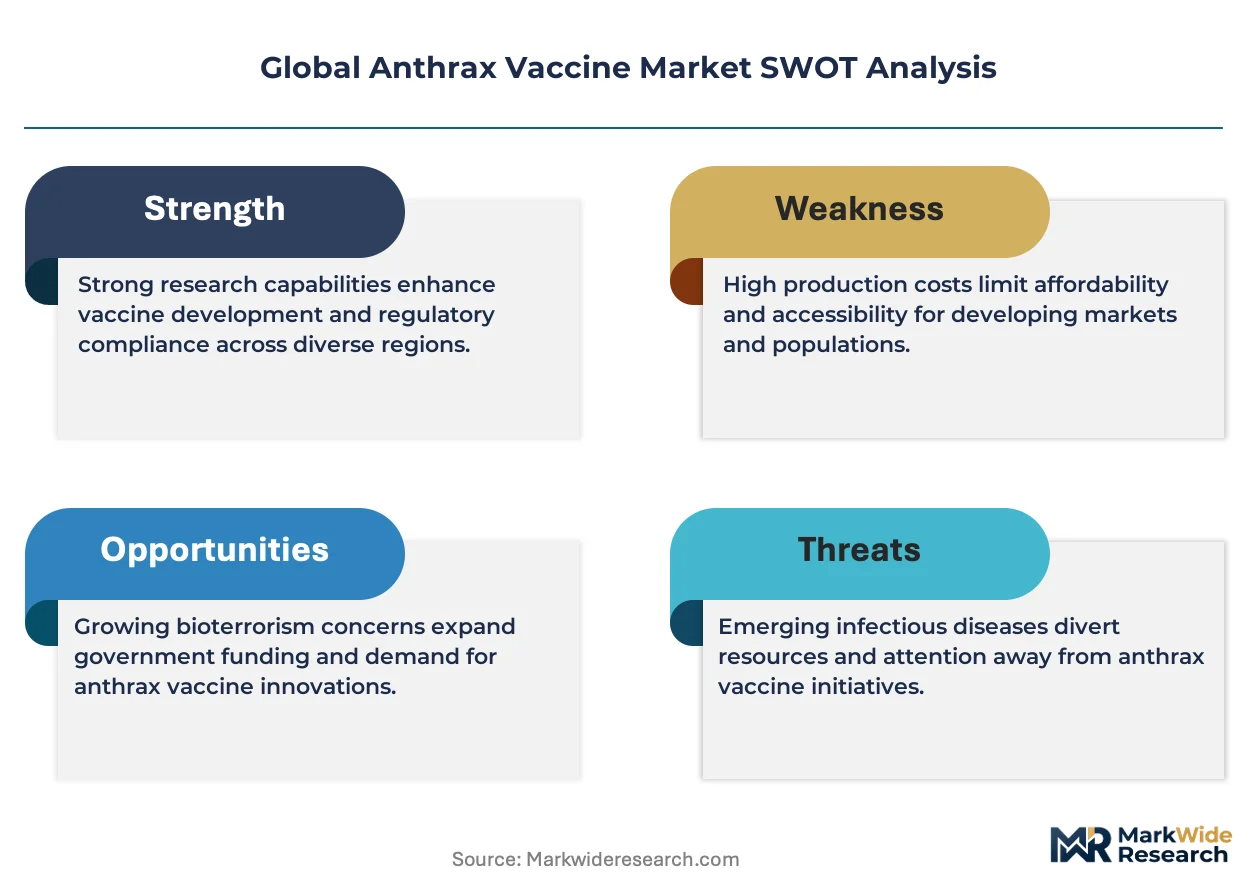
Market Restraints
- Alum adjuvant supply concentration:Bulk aluminum hydroxide production clusters among a handful of specialty chemical suppliers, exposing vaccine manufacturers to input cost volatility and qualification bottlenecks.
- Fill-finish capacity scarcity:Aseptic manufacturing infrastructure for biological products concentrates in the United States and Western Europe, constraining geographic diversification of finished dose supply.
- Long-term stability requirements:Strategic stockpile specifications demand validated shelf lives exceeding five years under temperature-controlled conditions, imposing formulation constraints that limit adjuvant innovation.
Strategic Opportunities
- Intranasal delivery platform development:Needle-free administration routes address mass immunization logistics for civilian populations, with several candidates advancing through preclinical stages targeting rapid deployment scenarios.
- Veterinary channel expansion:Live attenuated vaccines for livestock prophylaxis serve endemic disease management in agricultural economies, accessing procurement budgets distinct from human biodefense programs.
- EU Joint Procurement Agreement participation:The European Health Emergency Preparedness and Response Authority is consolidating member state demand into centralized tenders, creating new access pathways for qualified suppliers.
Industry Challenges
- Animal Rule clinical validation complexity:Correlating surrogate immune markers to survival outcomes across multiple species requires specialized biostatistical expertise that concentrates among contract research organizations with biodefense experience.
- Multi-jurisdictional GMP compliance:Simultaneous adherence to FDA, EMA, and WHO prequalification standards demands redundant quality management systems that inflate facility qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anthrax Vaccine Market |
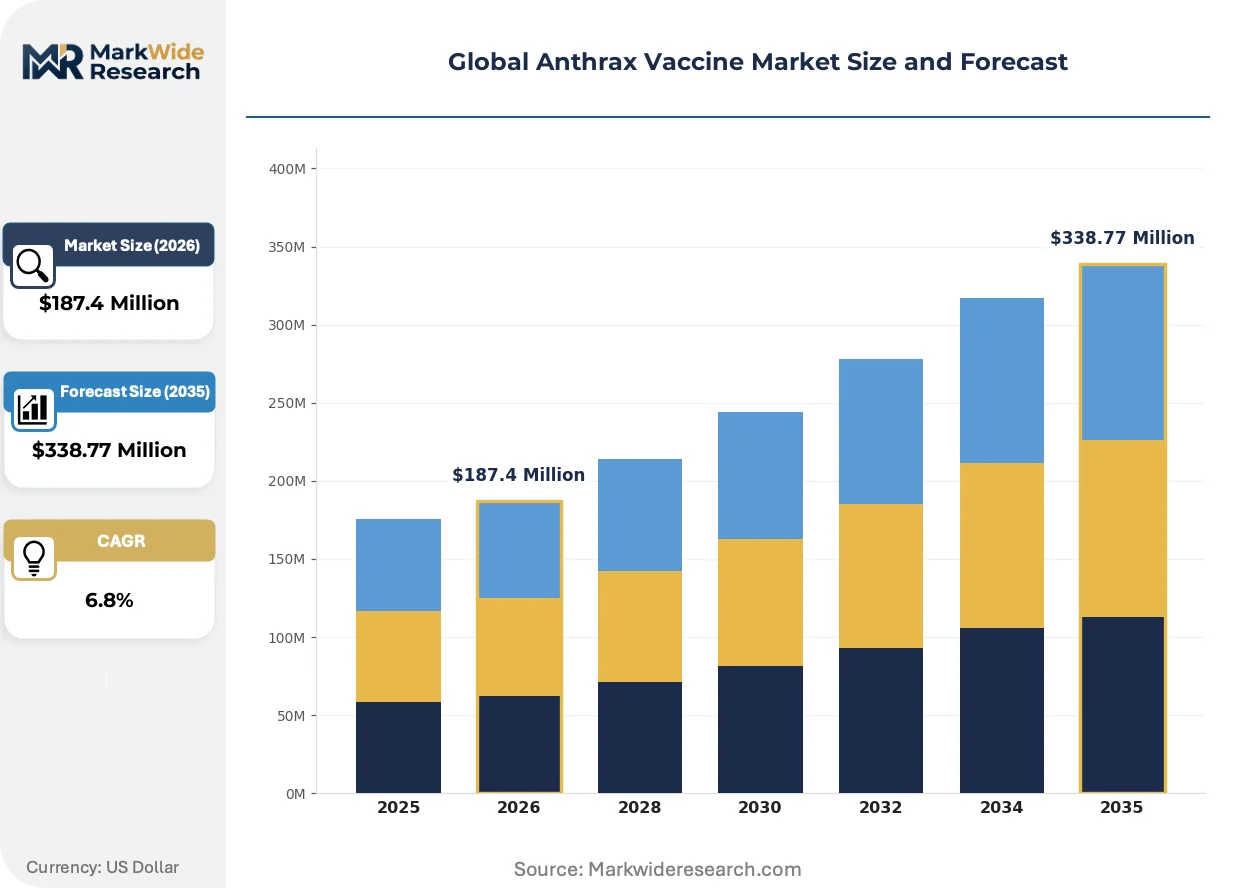
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated Vaccine, Recombinant Protective Antigen, Anthrax Spore Vaccine, Cell-Free Vaccine Application: Biodefense, Veterinary Immunization, Occupational Health, Laboratory Research End User: Military Forces, Pharmaceutical Companies, Research Institutions, Veterinary Clinics Deployment: Injectable, Intranasal, Oral, Intramuscular |
| Companies Covered | Emergent BioSolutions, Merck, Zoetis, GC Biopharma, Porton Biopharma, Valneva, Indian Immunologicals Limited, Colorado Serum Company, Bavarian Nordic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anthrax Vaccine Market Shifts & Advancements
Recombinant platform technologies are displacing legacy vaccine architectures, while regulatory frameworks adapt to evaluate efficacy without human challenge studies. Adjuvant science and delivery route innovation are converging to address stockpile logistics constraints.
Single-dose recombinant protective antigen formulations incorporating novel immunostimulatory adjuvants are unifying the previously separate objectives of rapid immune response induction and durable memory formation. Military medical services are prioritizing these candidates for pre-deployment immunization protocols. The technology is unifying procurement specifications across NATO member states around common performance benchmarks for seroconversion rates at day 14 post-vaccination.
The FDA's Animal Rule framework and its EU counterpart under the EMA's centralized procedure for exceptional circumstances are harmonizing evidentiary standards for biodefense vaccine licensure. Developers can now leverage survival data from non-human primate aerosol challenge studies to support marketing applications in both jurisdictions. Human recombinant protective antigen products are navigating these pathways most efficiently, while live attenuated candidates face additional safety characterization burdens.
Stockpile rotation cycles are compressing as defense agencies reassess pandemic-era shelf-life assumptions and demand real-time potency monitoring capabilities. The United States Department of Health and Human Services is replacing static inventory models with dynamic contracting mechanisms that link procurement to production rather than finished goods storage. This behavioral shift is most visible in BARDA's Project BioShield procurements, where advance purchase commitments now extend to bulk antigen reserves rather than filled vials alone.
Global Anthrax Vaccine Market Segmentation
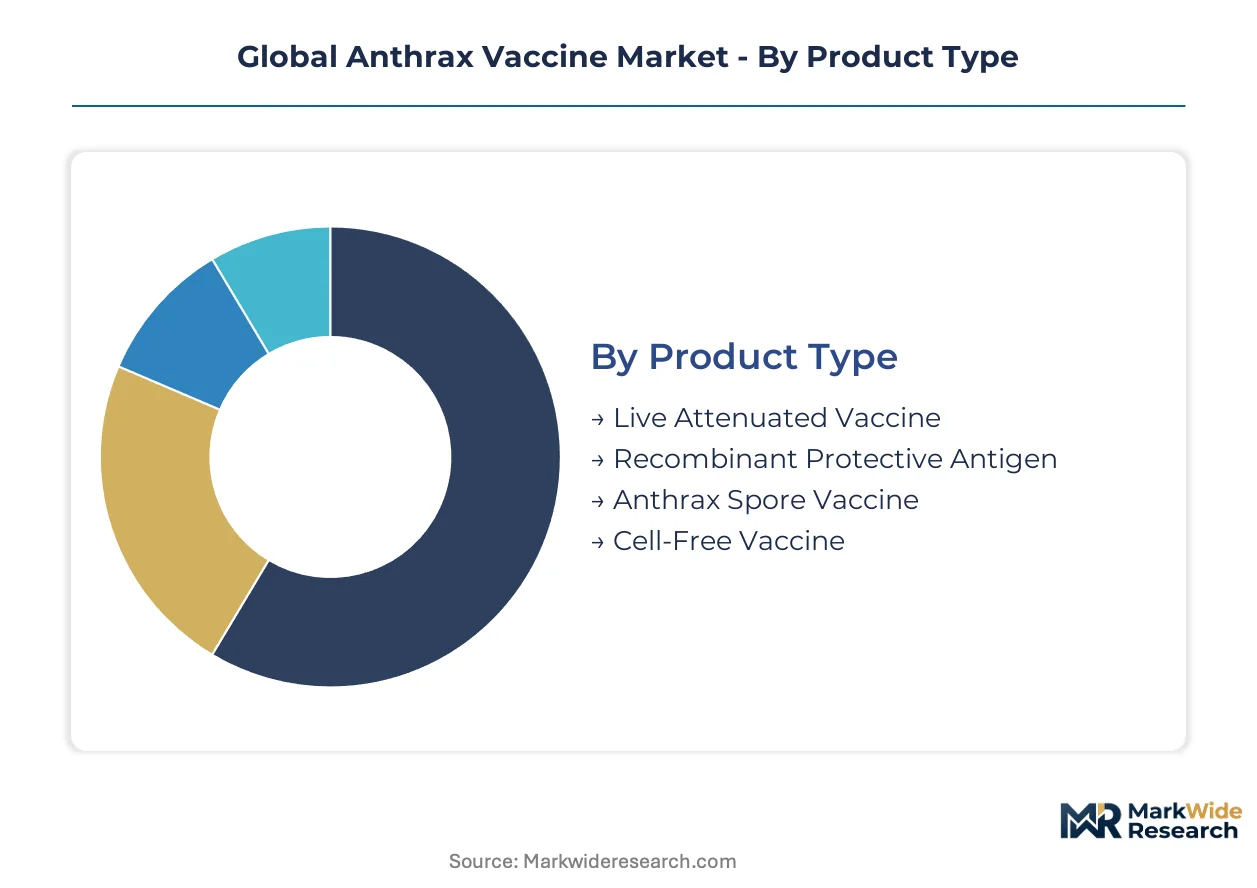
Anthrax vaccine procurement splits across four distinct dimensions, each governing supplier selection criteria and margin structures differently. Product type determines regulatory pathway complexity, while deployment route constrains manufacturing partnerships and cold-chain logistics.
Product Type:
Supply concentration clusters around recombinant platforms, with bulk antigen production separating from fill-finish operations across qualified GMP facilities.
- Recombinant Protective Antigen:Purified protein formulations derived from Bacillus anthracis protective antigen gene expression in recombinant systems. BARDA-funded procurement in the United States concentrates demand for this category, driven by FDA Animal Rule compatibility and superior safety profiles versus legacy alternatives.
- Live Attenuated Vaccine:Sterne strain or equivalent attenuated Bacillus anthracis preparations inducing cellular and humoral immunity. Veterinary demand in agricultural economies—particularly Brazil and India—sustains manufacturing capacity, constrained by human safety limitations and stricter handling protocols.
- Anthrax Spore Vaccine:Whole-spore preparations using avirulent strains for veterinary prophylaxis. Cost-sensitive livestock operations in endemic regions drive procurement.
- Cell-Free Vaccine:Non-living antigen formulations produced through cell culture systems. Emerging production technology with limited current procurement traction.
Today's leader: Recombinant Protective Antigen. Tomorrow's challenger: Cell-Free Vaccine.
Application:
Cost tier separation distinguishes biodefense premium procurement from veterinary commodity purchasing, with occupational health occupying a mid-tier position.
- Biodefense:National stockpile procurement for military and civilian prophylaxis against aerosolized anthrax exposure. NATO member states mandate 90-day coverage ratios, concentrating demand in the United States, United Kingdom, and Germany.
- Veterinary Immunization:Livestock protection in endemic regions where soil contamination persists. Brazil's agricultural ministry and India's veterinary services dominate procurement volumes, prioritizing cost-per-dose over formulation sophistication.
- Occupational Health:Pre-exposure prophylaxis for laboratory workers, tannery employees, and wool processing facilities. Fragmented employer-purchased demand across industrialized economies.
- Laboratory Research:Reference materials and challenge stocks for biodefense R&D. Limited volume, high-specification procurement from national laboratories.
Biodefense commands premium pricing; veterinary immunization anchors volume scale.
End User:
Customer type determines contracting mechanisms, with military forces demanding long-term supply agreements and research institutions purchasing on spot terms.
- Military Forces:Defense ministries procuring pre-deployment immunization and post-exposure prophylaxis stockpiles. The US Department of Defense and UK Ministry of Defence structure multi-year advanced development contracts.
- Pharmaceutical Companies:Licensees and contract manufacturers seeking bulk antigen supply for fill-finish operations. Partnerships concentrate around BARDA-qualified facilities.
- Research Institutions:National laboratories and university biodefense centers acquiring challenge materials and reference standards.
- Veterinary Clinics:Private and government livestock services administering routine prophylaxis in endemic agricultural regions.
Military procurement sets performance benchmarks; pharmaceutical companies enable supply diversification.
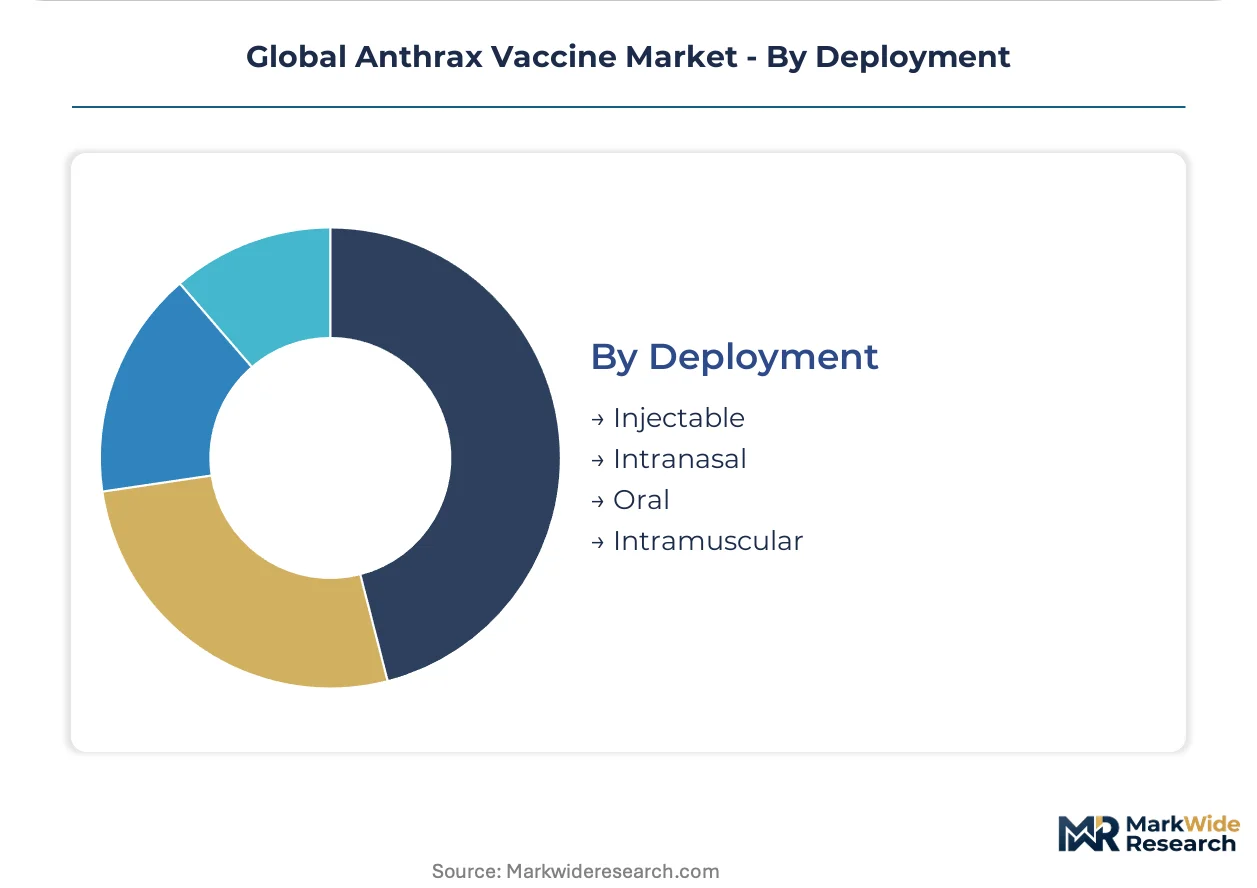
Deployment:
Route of administration shapes manufacturing partnerships, with intranasal delivery requiring distinct device and formulation expertise versus established injectable infrastructure.
- Intramuscular:Deep muscle injection of alum-adjuvanted suspensions, the established standard for military immunization protocols. Current NATO procurement specifications center on seroconversion rates at day 14 post-vaccination.
- Intranasal:Mucosal delivery platforms eliminating needle requirements for rapid mass immunization scenarios. Several candidates advance through preclinical stages targeting civilian deployment logistics.
- Injectable:General category encompassing subcutaneous and intradermal alternatives with limited current procurement traction.
- Oral:Experimental delivery route with stability and efficacy challenges constraining development investment.
Intramuscular dominates current procurement; intranasal platforms are gaining share fastest for next-generation stockpile specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The anthrax vaccine industry traces its modern scale to Cold War-era US biodefense investments, with Fort Detrick's research programs establishing the foundational manufacturing protocols that now propagate across NATO procurement networks.
United States
BARDA sustains multi-year advanced development contracts through Project BioShield, anchoring the world's largest strategic national stockpile. The FDA's Animal Rule pathway compresses licensure timelines for recombinant protective antigen candidates. Maryland's I-270 biotech corridor hosts Emergent BioSolutions' domestic fill-finish operations serving Department of Defense procurement.
Germany
The Bundeswehr Medical Service mandates 90-day civilian prophylaxis coverage ratios, driving parallel procurement for pre-exposure and post-exposure indications. EMA's centralized procedure for exceptional circumstances harmonizes evidentiary standards with FDA Animal Rule frameworks. Bavaria's Munich biotech cluster concentrates contract research organizations specializing in non-human primate aerosol challenge studies.
United Kingdom
The Ministry of Defence structures multi-year supply agreements for military pre-deployment immunization protocols. Porton Biopharma operates under the UK Health Security Agency's oversight, maintaining domestic manufacturing capacity for NATO-aligned stockpile specifications. Porton Down's research campus advances intranasal delivery platform development for rapid civilian deployment scenarios.
India
The Department of Biotechnology funds indigenous recombinant antigen development through the National Biopharma Mission. CDSCO's regulatory framework adapts WHO prequalification standards for veterinary and human biodefense applications. Hyderabad's Genome Valley cluster houses Indian Immunologicals Limited's bulk antigen production facilities serving agricultural ministry livestock programs.
Brazil
The Ministry of Agriculture's veterinary services prioritize cost-per-dose efficiency for endemic region livestock protection. ANVISA's regulatory alignment with OIE standards facilitates regional export of live attenuated vaccine formulations. São Paulo's Butantan Institute maintains Sterne strain production capacity for South American agricultural markets.
Global Anthrax Vaccine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the biodefense-veterinary divide, with recombinant protective antigen specialists commanding advanced development contract premiums while live attenuated manufacturers compete on agricultural procurement cost efficiency. The supplier base concentrates around BARDA-qualified facilities for human applications and diversified veterinary pharmaceutical networks for livestock markets. Three archetypes dominate: integrated biodefense contractors with domestic manufacturing footprints, recombinant platform technology licensors, and regional veterinary vaccine specialists. Competitive moves center on strategic partnerships decoupling bulk antigen from fill-finish operations, and geographic expansion into EU Joint Procurement Agreement frameworks.
Within the integrated biodefense contractor tier, Emergent BioSolutions exemplifies the archetype of domestic manufacturing-anchored stockpile suppliers. Merck occupies a position representing sustained R&D investment in next-generation recombinant platforms. Zoetis sits within the veterinary channel specialist archetype, occupying demand segments separate from human biodefense procurement networks.
| Leading Market Players |
|---|
| Emergent BioSolutions |
| Merck |
| Zoetis |
| GC Biopharma |
| Porton Biopharma |
| Valneva |
| Indian Immunologicals Limited |
| Colorado Serum Company |
| Bavarian Nordic |
| Others |
Supply & Pricing Matrix
Recombinant protective antigen procurement splits sharply from live attenuated veterinary formulations, with BARDA-funded biodefense contracts commanding advanced development premiums while agricultural ministries in Brazil and India optimize for cost-per-dose efficiency. This bifurcation concentrates manufacturing investment in FDA-qualified fill-finish facilities for human applications, while dispersing bulk antigen production across lower-cost veterinary networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with FDA Animal Rule-compliant recombinant products capturing premium tiers, occupational health programs occupying mid-tier contract positions, and veterinary live attenuated vaccines trading at commodity spot rates. Price differentiation hinges on regulatory certification tier and volume scale, with NATO member state stockpile orders securing preferential terms through multi-year offtake commitments. Pricing pressure stems from alum adjuvant supply concentration among specialty chemical suppliers, squeezing margins in standard-tier formulations. Veterinary clinics exhibit highest price sensitivity, while US Department of Defense procurement demonstrates lowest sensitivity due to national security mandate.
Supply Chain Analysis
Dual-sourcing requirements embedded in BARDA and EU Joint Procurement Agreement specifications compel defense agencies to qualify multiple bulk antigen suppliers, decoupling production from fill-finish operations. Geographic supply concentration centers on the United States, Germany, and the United Kingdom for human biodefense applications, with India and Brazil anchoring veterinary manufacturing. Raw material dependencies include recombinant expression systems, aluminum hydroxide adjuvant, and aseptic fill-finish components. Single-source vulnerability concentrates in alum adjuvant production, exposing manufacturers to input cost volatility. Distribution runs through national strategic stockpile depots for biodefense tiers, while veterinary channels deploy through agricultural ministry cold-chain networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in recombinant platform standardization and intranasal delivery route development, as formulation simplification reduces per-dose production costs while novel administration formats command development premiums.
For Market Incumbents: Extend BARDA-qualified manufacturing footprints into EU Joint Procurement Agreement jurisdictions to capture NATO stockpile diversification mandates. Deepen backward integration into recombinant expression system production to reduce dependency on contract biomanufacturing capacity. Lock in long-term alum adjuvant supply agreements before specialty chemical supplier consolidation accelerates. Prioritize intranasal platform R&D to defend against needle-free delivery entrants targeting civilian mass immunization scenarios.
For New Entrants and Emerging Players: Contract research organizations with non-human primate aerosol challenge capabilities represent the most penetrable entry point, as Animal Rule validation expertise concentrates among limited qualified providers. Target veterinary channel partnerships in Brazil and India where cost-competitive live attenuated production faces less regulatory barrier than human biodefense pathways. Pursue fill-finish subcontracting relationships with BARDA-qualified facilities to bypass capital-intensive aseptic infrastructure requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where Animal Rule validation capabilities overlap with underutilized recombinant manufacturing capacity, creating roll-up opportunities for integrated biodefense contractors. Five-to-ten year viability favors platform technology licensors with diversified antigen pipelines beyond anthrax-specific applications. Watch BARDA procurement mechanism shifts toward dynamic bulk antigen contracting rather than finished goods stockpiling as the critical inflection signal for facility valuation models.
| Strategic Initiative | Industry Significance |
|---|---|
| Intranasal Delivery Platform Development | Needle-free administration addresses NATO civilian prophylaxis logistics requirements for rapid deployment scenarios. |
| Animal Rule Validation Capability Acquisition | Non-human primate aerosol challenge expertise compresses licensure timelines for recombinant protective antigen candidates. |
| EU Joint Procurement Agreement Qualification | EMA centralized procedure alignment opens access to consolidated member state biodefense tenders beyond US BARDA channels. |
| Alum Adjuvant Supply Integration | Backward control over aluminum hydroxide inputs mitigates cost volatility from specialty chemical supplier concentration. |
| Veterinary Channel Geographic Expansion | Brazilian and Indian agricultural ministry contracts provide volume scale independent of human biodefense procurement cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biodefense procurement officers, regulatory affairs leads at recombinant vaccine developers, veterinary pharmaceutical distribution managers, and contract research organization executives with secondary validation against FDA Animal Rule guidance documents, EMA centralized procedure filings, BARDA contract award databases, and NATO standardization agreement references. Bottom-up segment sizing triangulated against top-down national stockpile budget allocations.
Segment-weighting approaches modeled product type, application tier, end-user contracting mechanism, and deployment route dimensions across the projection horizon. CAGRs derived from elasticity-adjusted procurement volume trajectories incorporating NATO member state coverage ratio mandates and pandemic-era stockpile rotation cycle compression. Forecast inputs included alum adjuvant supply capacity constraints and intranasal formulation development pipeline maturity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biodefense procurement mechanism shifts, regulatory pathway harmonization between FDA and EMA frameworks, and novel adjuvant qualification timelines. Deviation in BARDA contracting models toward dynamic bulk antigen reserves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Erdosteine Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Azathioprine API Market