
 Global Esketamine Market | 2026-2036
Global Esketamine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Esketamine Market Foresight
Intranasal delivery technology is fragmenting the traditional injectable antidepressant paradigm, forcing manufacturers to recalibrate formulation pipelines around patient-administered modalities. Janssen Pharmaceuticals dominates the branded esketamine landscape through its REMS-certified Spravato distribution network. Johnson & Johnson leverages its parent-company infrastructure to sustain hospital formulary access across North American and European psychiatric institutions. Teva Pharmaceutical Industries Ltd. competes through generic injectable capabilities, positioning itself for post-exclusivity market entry.
Esketamine, the S-enantiomer of ketamine, functions as a non-competitive N-methyl-D-aspartate receptor antagonist administered at sub-anesthetic doses for rapid-onset antidepressant effect; its intranasal formulation achieves therapeutic plasma concentrations within minutes, enabling supervised outpatient administration without intravenous infrastructure. The therapy area dimension shows treatment-resistant depression anchoring current revenue pools, while bipolar depression represents the fastest-expanding indication as investigators explore expanded labeling. Among delivery modes, prescription-based administration through certified psychiatric clinics controls the dominant margin pool, though telemedicine support is emerging as a structural growth vector by enabling remote patient monitoring between in-clinic dosing sessions.
FDA REMS requirements shape the United States market by mandating certified administration settings and patient registry participation, while EMA centralized review processes govern European market access and post-authorization safety study obligations. Health Canada and the United Kingdom's MHRA operate parallel regulatory frameworks that influence formulation standards and distribution controls across Commonwealth markets. Stakeholders must monitor REMS modification proceedings and pharmacovigilance data accumulation that will determine whether home-administration pathways gain regulatory acceptance.
Market Dynamics
FDA REMS protocols are compressing the esketamine administration model toward certified psychiatric clinics, creating a bottleneck that concentrates patient flow through REMS-certified sites while excluding general practitioners from prescribing authority.
Growth Catalysts
- Treatment-resistant depression protocols:EMA guidelines standardizing outpatient administration across Germany and the United Kingdom are expanding addressable patient populations beyond hospital settings.
- Intranasal delivery technology:Patient-administered spray formulations eliminate intravenous infrastructure requirements, enabling clinic-scale deployment without anesthesiology staffing.
- Bipolar depression labeling expansion:Investigational protocols for expanded indications are opening new prescriber categories in psychiatric and mood-disorder specialty practices.
Market Restraints
- REMS certification costs:Mandatory patient registry systems and certified administration site requirements impose fixed overhead that limits small-clinic participation.
- Supply concentration:Single-source API manufacturing and controlled-substance scheduling create import dependency risks for markets outside North America and Western Europe.
- Ketamine substitution threat:Compounded racemic ketamine infusions at lower price points compete for treatment-resistant depression patients outside formal esketamine protocols.
Strategic Opportunities
- Telemedicine monitoring integration:Remote patient observation between in-clinic dosing sessions enables geographic expansion into underserved rural and suburban catchment areas.
- Home-administration pathway development:Pharmacovigilance data accumulation supporting REMS modification petitions could unlock take-home prescription models.
- Asia-Pacific regulatory harmonization:PMDA and NMPA review timelines for novel antidepressant classes present first-mover positioning for standardized dossier submissions.
Industry Challenges
- Psychiatric nursing shortage:REMS-mandated two-hour post-dose observation requirements strain specialized staffing capacity at high-volume clinics.
- Controlled-substance logistics:DEA Schedule III storage and transport protocols impose compliance complexity on wholesale distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Esketamine Market |
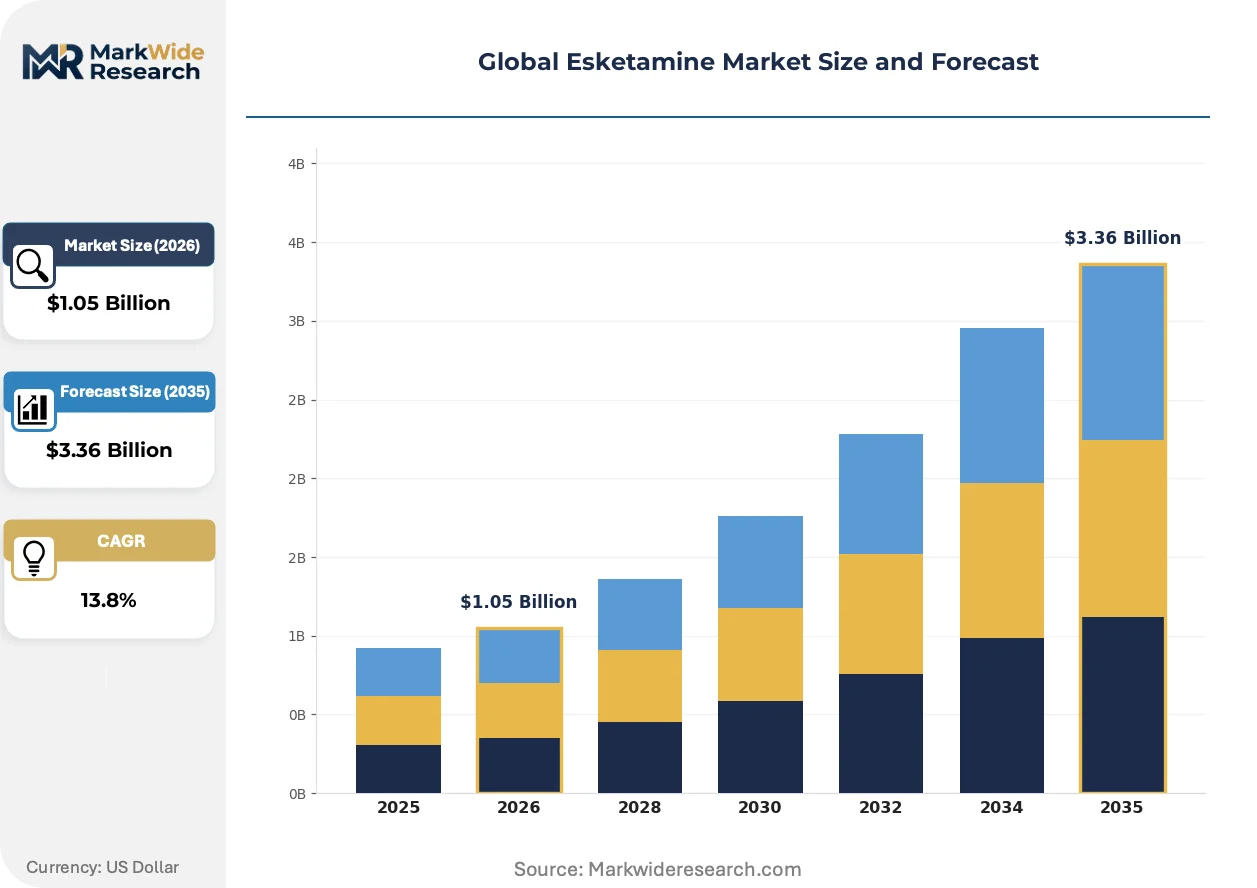
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intranasal Spray, Injectable Solution, Oral Formulation, Sublingual Tablet Therapy Area: Major Depressive Disorder, Treatment-Resistant Depression, Bipolar Depression, Anxiety Disorders End User: Psychiatric Clinics, Specialty Hospitals, Ambulatory Care Centers, Research Institutes Delivery Mode: Prescription-Based, Hospital Administration, Home Healthcare, Telemedicine Support |
| Companies Covered | Janssen Pharmaceuticals, Johnson & Johnson, Pfizer Inc., Merck & Co., Inc., Endo International plc, Hikma Pharmaceuticals plc, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Sage Therapeutics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Esketamine Market Shifts & Advancements
Intranasal bioavailability engineering is collapsing the traditional boundary between hospital-based anesthetic delivery and outpatient psychiatric administration. Three convergent developments are compressing the treatment infrastructure required for rapid-onset antidepressant therapy.
Sub-anesthetic spray formulations are collapsing the intravenous infrastructure requirement for esketamine administration. Psychiatric clinics in the United States and Germany are adopting intranasal protocols at accelerating pace, replacing anesthesiology-staffed infusion suites with nursing-supervised spray administration. This compression is enabling same-day patient throughput volumes that intravenous models cannot match.
EMA centralized review processes are harmonizing post-authorization safety study obligations across European member states. The standardization is reducing duplicate pharmacovigilance reporting burdens for multi-country prescribers. German and British psychiatric institutions are consolidating their compliance frameworks in response, streamlining cross-border patient registry participation.
Remote monitoring platforms are displacing in-clinic observation for inter-dose periods. Telemedicine vendors are capturing psychiatric practice workflows between mandatory administration sessions, unbundling the traditional bundled care model. This channel shift is most visible in United States markets where REMS protocols permit remote patient contact but mandate physical presence for dosing.
Global Esketamine Market Segmentation
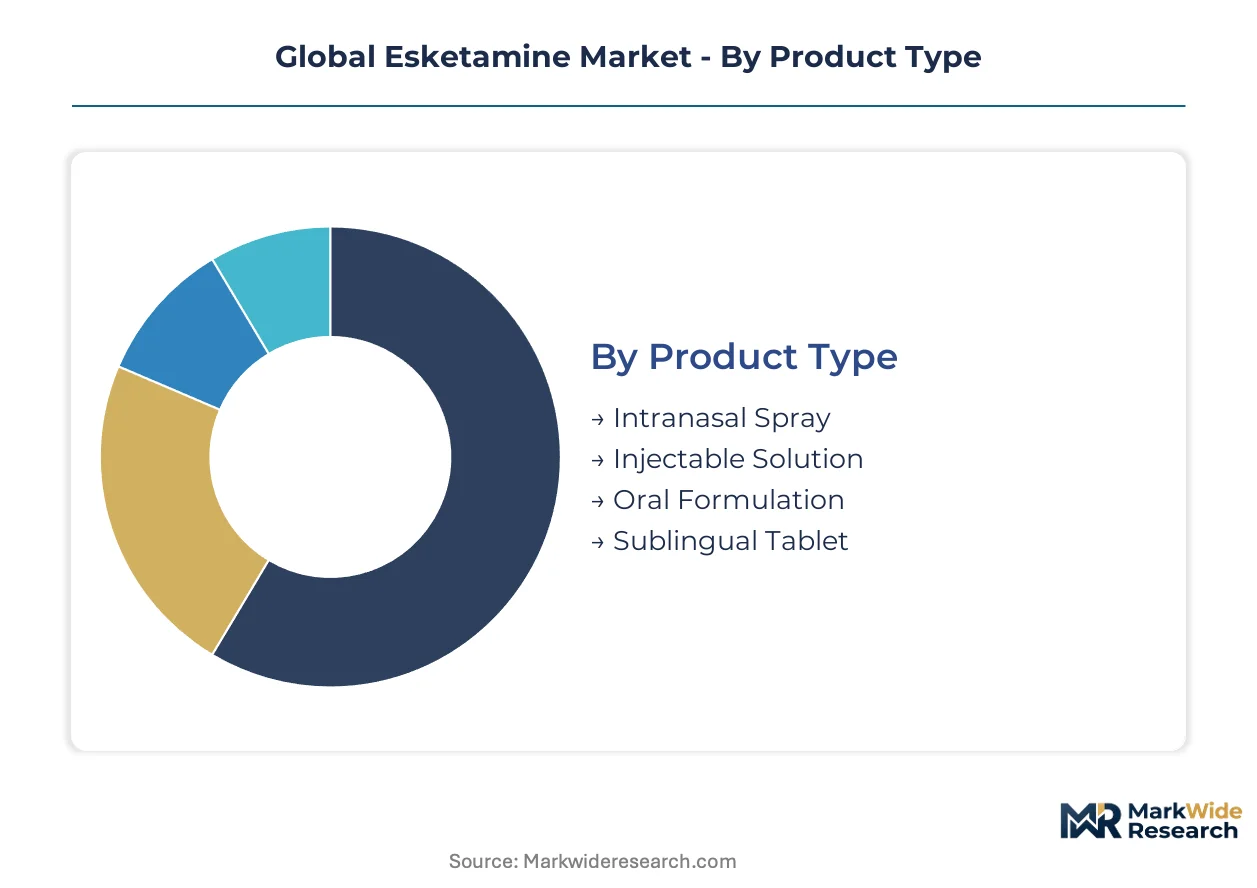
Esketamine market segmentation reveals how regulatory architecture and administration infrastructure shape commercial opportunity across formulation types and care settings. Each dimension carries distinct margin profiles, certification barriers, and patient throughput economics that determine competitive positioning.
Product Type:
Cycle times vary sharply across formulations, with intranasal protocols enabling same-day patient turnover while injectable models require extended observation windows and specialized staffing.
- Intranasal Spray:Patient-administered sub-anesthetic dosing achieves therapeutic plasma levels within minutes through nasal mucosa absorption. United States psychiatric clinics are expanding REMS-certified capacity specifically around this format, as the two-hour post-dose observation window compresses versus intravenous alternatives.
- Injectable Solution:Intravenous and intramuscular formulations demand anesthesiology-staffed infusion suites with extended monitoring protocols. German hospital networks maintain installed base concentration here, though outpatient migration toward intranasal alternatives is accelerating.
- Oral Formulation:Bioavailability challenges and first-pass metabolism effects limit current commercial deployment across regulated markets.
- Sublingual Tablet:Mucosal absorption kinetics remain under pharmacokinetic investigation with limited prescriber familiarity outside research protocols.
Intranasal spray dominates installed base expansion. Injectable solution is where legacy infrastructure concentrates.
Therapy Area:
Cost tier stratification separates acute intervention protocols from maintenance-phase regimens, with reimbursement density highest in formally designated treatment-resistant populations.
- Treatment-Resistant Depression:FDA and EMA-approved indication anchoring current revenue pools, defined as failure on two or more antidepressant trials. United Kingdom psychiatric clinics are standardizing stepped-care pathways that escalate to esketamine after documented SSRI and SNRI non-response, expanding addressable cohorts through protocol formalization.
- Bipolar Depression:Investigational protocols and expanded-access programs are opening prescriber categories beyond unipolar depression specialists. Clinical trial recruitment across United States academic medical centers is climbing fastest in this segment as sponsors pursue label extension.
- Major Depressive Disorder:Earlier-line positioning remains off-label with limited payer coverage outside research settings.
- Anxiety Disorders:Obsessive-compulsive and post-traumatic stress indications remain exploratory with nascent investigator-initiated study infrastructure.
Treatment-resistant depression anchors current reimbursement density. Bipolar depression is climbing fastest in clinical development investment.
End User:
Volume concentration tracks regulatory certification density, with REMS and EMA authorization requirements filtering patient flow toward specialized institutional categories.
- Psychiatric Clinics:REMS-certified outpatient facilities control the dominant margin pool through supervised administration protocols. United States standalone psychiatric practices and hospital-affiliated clinics are consolidating market access through registry participation and staff certification programs.
- Specialty Hospitals:Academic medical centers and psychiatric hospitals maintain institutional review board infrastructure for expanded-access protocols and post-authorization safety studies. German university hospitals anchor European pharmacovigilance data accumulation.
- Ambulatory Care Centers:General medical settings face REMS exclusion or EMA scope limitations without specialized psychiatric staffing.
- Research Institutes:Phase III and Phase IV trial sites concentrate in National Institute of Mental Health-funded networks and European Depression Network nodes.
Psychiatric clinics concentrate patient throughput volume. Specialty hospitals anchor pharmacovigilance and expanded-access infrastructure.
Delivery Mode:
Customer type stratification separates institutional purchasers from individual prescriber authority, with channel control varying by jurisdiction-specific scheduling and distribution regulations.
- Prescription-Based:Certified clinic dispensing with direct-to-patient administration under REMS or EMA protocols. United States DEA Schedule III controls mandate closed distribution through registered sites, creating channel concentration that pharmaceutical wholesalers navigate through specialized controlled-substance logistics.
- Telemedicine Support:Remote patient monitoring between mandatory in-clinic dosing sessions enables geographic expansion into rural catchment areas. United Kingdom NHS trusts are piloting digital health integration for inter-dose psychiatric assessment, unbundling traditional bundled care models.
- Hospital Administration:Inpatient psychiatric units utilize esketamine for acute suicidality intervention with 24-hour observation capacity.
- Home Healthcare:Take-home models remain precluded by REMS physical presence requirements and EMA supervised administration mandates.
Prescription-based administration dominates current revenue capture. Telemedicine support is gaining share fastest as remote monitoring infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Psychiatric clinic chains and hospital-affiliated mental health networks concentrate esketamine procurement decisions across major pharmaceutical markets. Regulatory certification density and REMS-equivalent protocols determine where administration capacity scales fastest.
United States
REMS-certified outpatient clinics and academic medical centers drive demand concentration. FDA mandates patient registry participation and two-hour post-dose observation that shapes site economics. Psychiatric practice clusters in Boston, New York Metro, and California's Bay Area anchor Spravato administration volume.
Germany
University hospital networks and statutory health insurance reimbursement protocols expand addressable patient pools. EMA centralized review harmonizes post-authorization safety obligations across Länder. Berlin and Munich psychiatric institutions lead outpatient protocol standardization for treatment-resistant depression.
United Kingdom
NHS England stepped-care pathways and specialized commissioning frameworks filter patient escalation to esketamine. MHRA operates parallel regulatory controls that influence formulation standards. London teaching hospitals and Manchester academic centers concentrate pharmacovigilance data accumulation.
Japan
PMDA review timelines for novel antidepressant classes create first-mover positioning opportunities. Metropolitan psychiatric hospitals in Tokyo and Osaka maintain institutional review board infrastructure for expanded-access protocols. National health insurance reimbursement decisions pending for intranasal formulations.
Australia
TGA scheduling controls and specialized psychiatrist prescribing authority limit administration site expansion. Private psychiatric hospital chains in Sydney and Melbourne pilot REMS-equivalent certification programs. PBS reimbursement negotiations determine patient access thresholds for treatment-resistant populations.
Global Esketamine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the esketamine landscape. Market structure consolidates around REMS-certified distribution networks and parent-company infrastructure leverage. Three archetypes dominate: pharmaceutical conglomerates with psychiatric franchise depth, generic injectable specialists positioning for post-exclusivity entry, and biotech innovators pursuing adjacent CNS indications. Competitive moves center on formulary access consolidation and telemedicine partnership formation to extend geographic reach.
Within the conglomerate tier, Janssen Pharmaceuticals and Johnson & Johnson exemplify channel-control strategies through REMS infrastructure deployment. Teva Pharmaceutical Industries Ltd. occupies a position among generic-capable specialists preparing for formulation diversification. These anchors represent distinct strategic postures—proprietary distribution depth versus manufacturing scale readiness—without prescribing specific tactical sequences.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| Johnson & Johnson |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Endo International plc |
| Hikma Pharmaceuticals plc |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Sage Therapeutics, Inc. |
| Others |
Supply & Pricing Matrix
Single-source API manufacturing dependency in controlled-substance scheduling determines both the premium-to-standard pricing spread across REMS-certified and non-certified administration tiers and the geographic concentration of supply chain nodes. DEA Schedule III storage protocols and EMA import licensing requirements compress margin flexibility while mandating specialized logistics infrastructure that few distributors maintain.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to narcotic raw material benchmarks and DEA quota allocation cycles. Pricing stratifies across REMS-certified premium tiers, hospital-affiliated standard tiers, and research-institute economy tiers based on certification investment and patient throughput scale. Cost compression in the standard tier is intensifying as generic injectable specialists prepare post-exclusivity entry. Academic medical centers exhibit lowest price sensitivity due to grant-funded expanded-access protocols; standalone psychiatric clinics face highest sensitivity due to fixed REMS overhead.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities enables API distributors to manage DEA-mandated inventory holding periods. Active pharmaceutical ingredient production concentrates in the United States, India, and Belgium, with nasal spray device manufacturing anchored in Germany and the United States. The supply chain rests on single-source esketamine API production and specialized controlled-substance logistics networks. Tariff exposure on pharmaceutical intermediates from India poses structural risk. Distribution runs through REMS-certified wholesalers with dedicated Schedule III storage infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified psychiatric nursing capacity functions as the binding constraint across administration site expansion, with REMS-mandated two-hour observation protocols creating a credential scarcity that determines competitive pacing.
For Market Incumbents: Build regulatory data moats through pharmacovigilance registry dominance that compounds with each patient enrollment. Janssen Pharmaceuticals and Johnson & Johnson should deepen backward integration into nasal spray device manufacturing to defend against supply disruption. Incumbents must invest in telemedicine platform certification to extend geographic reach without proportional nursing headcount expansion, countering ketamine infusion clinic substitution threats. For New Entrants and Emerging Players: Australia's private psychiatric hospital chains and Japan's metropolitan academic centers represent the most penetrable white-space targets, with TGA and PMDA review timelines creating first-mover windows ahead of formulary standardization. Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. should prioritize generic injectable dossier preparation for post-exclusivity EMA centralized review submission. A go-to-market angle through telemedicine-integrated clinic partnerships bypasses direct REMS certification overhead. For Investors and Strategic Acquirers: REMS modification proceedings reshaping home-administration pathways alter the acquisition landscape toward remote monitoring technology platforms and specialized psychiatric nursing staffing firms. Long-term viability across the analysis window favors targets with installed pharmacovigilance infrastructure and EMA rapporteur relationships. The signal to watch is Health Canada and MHRA pilot program announcements for take-home prescription models, which would revalue telemedicine-enabled clinic networks.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Certification Expansion | Psychiatric clinic chains in Boston and New York Metro capture patient throughput volume through registry participation. |
| Telemedicine Platform Integration | Remote monitoring vendors unbundle traditional bundled care models between mandatory in-clinic dosing sessions. |
| Generic Injectable Dossier Preparation | Teva Pharmaceutical Industries positions for post-exclusivity EMA centralized review through manufacturing scale readiness. |
| Bipolar Depression Label Extension | United States academic medical centers anchor Phase III trial recruitment for expanded indication revenue pools. |
| Asia-Pacific Regulatory Harmonization | PMDA and NMPA review timeline alignment enables standardized dossier submissions across Tokyo and Osaka networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at Janssen Pharmaceuticals, formulary directors at United States psychiatric clinic chains, and DEA-registered wholesale distributors; and secondary validation through FDA REMS modification filings, EMA post-authorization safety study submissions, and ClinicalTrials.gov protocol registries. Bottom-up patient throughput modeling at REMS-certified sites triangulated against top-down pharmaceutical revenue estimates.
Forecast inputs incorporated treatment-resistant depression prevalence cohorts, bipolar depression trial recruitment velocity, intranasal versus injectable formulation adoption curves, and REMS-certified site expansion rates across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user category, and delivery mode. CAGRs derived from patient volume elasticity to reimbursement decisions and administration infrastructure deployment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by generic injectable specialists or telemedicine platform entrants would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Dermatological Drugs Market