
 Denmark Pharmaceutical Market | 2026-2036
Denmark Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Pharmaceutical Market Outlook
Biologics manufacturing is tilting toward single-use bioreactor systems and continuous processing platforms that reshape production economics for Danish drug makers. Novo Nordisk anchors Denmark's insulin and GLP-1 peptide leadership through in-house fermentation scale. Ascendis Pharma leverages its TransCon technology platform to sustain extended-release product differentiation. Leo Pharma competes in dermatology and thrombosis through specialized topical and injectable portfolios.
Denmark pharmaceuticals encompass chemically synthesized small molecules, recombinant proteins, monoclonal antibodies, and nucleic acid therapies formulated for therapeutic intervention in human disease, with active pharmaceutical ingredients typically requiring purity exceeding 99.5% and stability validation under ICH Q1A guidelines. Biologics command premium pricing due to manufacturing complexity and biosimilar defense requirements. Prescription drugs dominate volume through chronic disease prevalence, while oncology applications attract concentrated R&D investment from hospital-based research institutions. Injectable delivery modes lead in biologics administration, though oral formulations retain share in cardiology and neurology maintenance therapy.
The Danish Medicines Agency enforces EU MDR-aligned pharmacovigilance and clinical trial transparency standards that shape product development timelines. The Danish Health Authority coordinates national reimbursement negotiations that determine market access for novel therapies across hospital formularies. Environmental permitting through the Danish Environmental Protection Agency governs active pharmaceutical ingredient discharge limits for manufacturing facilities. Stakeholders must monitor how EU pharmaceutical strategy revisions and national green transition mandates reshape capital allocation for domestic production expansion.
Market Dynamics
Denmark's pharmaceutical sector is reconfiguring around continuous bioprocessing and single-use manufacturing systems that compress capital cycles and accelerate batch turnover for peptide and antibody production.
Growth Catalysts
- EU MDR harmonization:The Medical Device Regulation streamlines clinical evidence requirements across member states, reducing redundant trial costs for Danish device-drug combination products.
- GLP-1 peptide demand:Hospital formularies in Zealand and the Capital Region are expanding procurement of injectable metabolic therapies, pulling fermentation capacity expansion.
- Medicon Valley clustering:Copenhagen-Malmö corridor concentration of CROs, CDMOs, and specialized logistics providers shortens development timelines for early-stage biotechs.
Market Restraints
- API import dependency:Denmark sources over 80% of small-molecule active ingredients from Asian contract manufacturers, exposing formulators to shipping volatility and customs delays.
- EMA centralized review bottlenecks:Novel therapy applications face 12-18 month assessment queues at the European Medicines Agency, compressing effective patent life.
- Biosimilar substitution pressure:Danish Health Authority tendering rules favor lowest-cost biologics, eroding originator pricing power in insulin and growth hormone segments.
Strategic Opportunities
- North Jutland manufacturing expansion:Municipalities around Aalborg offer brownfield industrial sites with upgraded utility infrastructure for large-scale biologics plants.
- TransCon technology convergence:Extended-release prodrug platforms combining peptide engineering with hydrogel delivery open new indication areas in endocrinology and hematology.
- Danish green transition mandates:National carbon-neutrality targets for 2045 create first-mover advantage for facilities deploying renewable-powered fermentation and solvent recovery systems.
Industry Challenges
- Bioprocess engineering talent scarcity:Danish universities produce insufficient graduates with hybrid skills in cell culture, automation, and quality systems to staff expanding manufacturing footprints.
- Legacy ERP integration:Established firms face 18-24 month implementation cycles connecting continuous manufacturing data streams to validated batch record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Pharmaceutical Market |
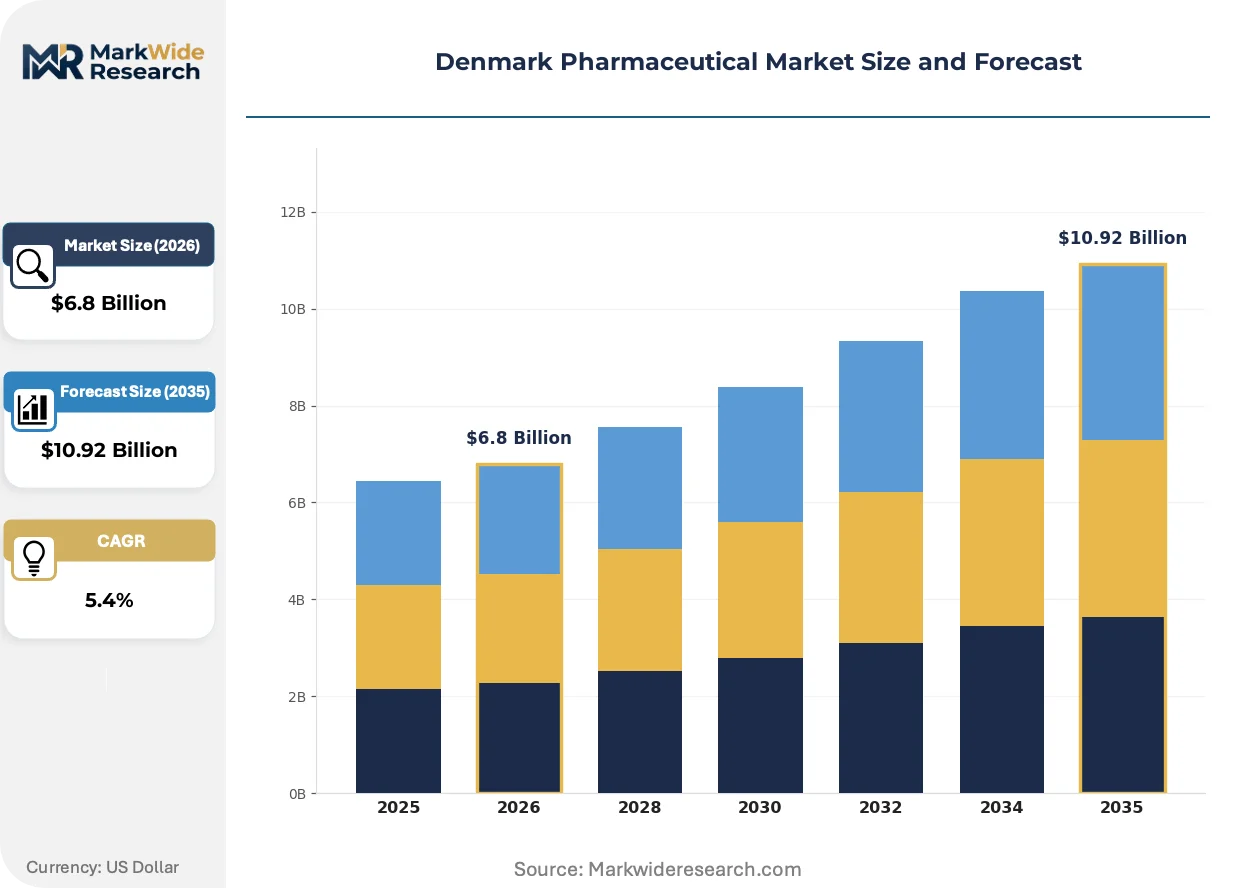
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Biologics, Vaccines Application: Oncology, Cardiology, Neurology, Infectious Diseases End User: Pharmacies, Hospitals, Clinics, Research Institutions Delivery Mode: Injectable, Oral, Topical, Inhalation |
| Companies Covered | Orifarm Group, Ascendis Pharma, Novo Nordisk, Muna Therapeutics, Gubra, H. Lundbeck, ALK-Abelló Nordic, SNIPR Biome, Leo Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Pharmaceutical Market Strategic Shifts
Biologics production is abandoning stainless-steel infrastructure in favor of modular, disposable manufacturing architectures that reduce cross-contamination risk and enable multi-product facility flexibility.
Single-use bioreactor systems are migrating from pilot-scale clinical supply to commercial bulk manufacturing for monoclonal antibodies and recombinant proteins. Danish CDMOs are retrofitting existing cleanrooms with 2,000-liter disposable stirred-tank units, cutting facility changeover time from weeks to days. This migration from fixed-asset to variable-cost production models is compressing break-even thresholds for orphan-drug manufacturers and enabling campaign-style manufacturing for niche indications.
The Danish Environmental Protection Agency has tightened discharge limits for pharmaceutical manufacturing effluent, forcing facilities to install advanced oxidation and membrane bioreactor systems for active ingredient removal. Industrial consequence includes 15-25% uplift in wastewater treatment capital allocation for new greenfield sites. Bulk API manufacturers in Kalundborg and Hillerød are responding by consolidating production into fewer, larger facilities with centralized treatment infrastructure rather than distributed small-scale plants.
Hospital procurement is consolidating volume through regional tendering consortiums that bypass traditional wholesaler relationships. Zealand Region and Capital Region have merged pharmaceutical purchasing, awarding multi-year framework agreements to single suppliers for therapeutic categories. This concentration is most visible in biologics and oncology injectables, where formularies now specify biosimilar alternatives unless clinical justification is documented, shifting margin capture from manufacturers to centralized procurement bodies.
Denmark Pharmaceutical Market Segmentation
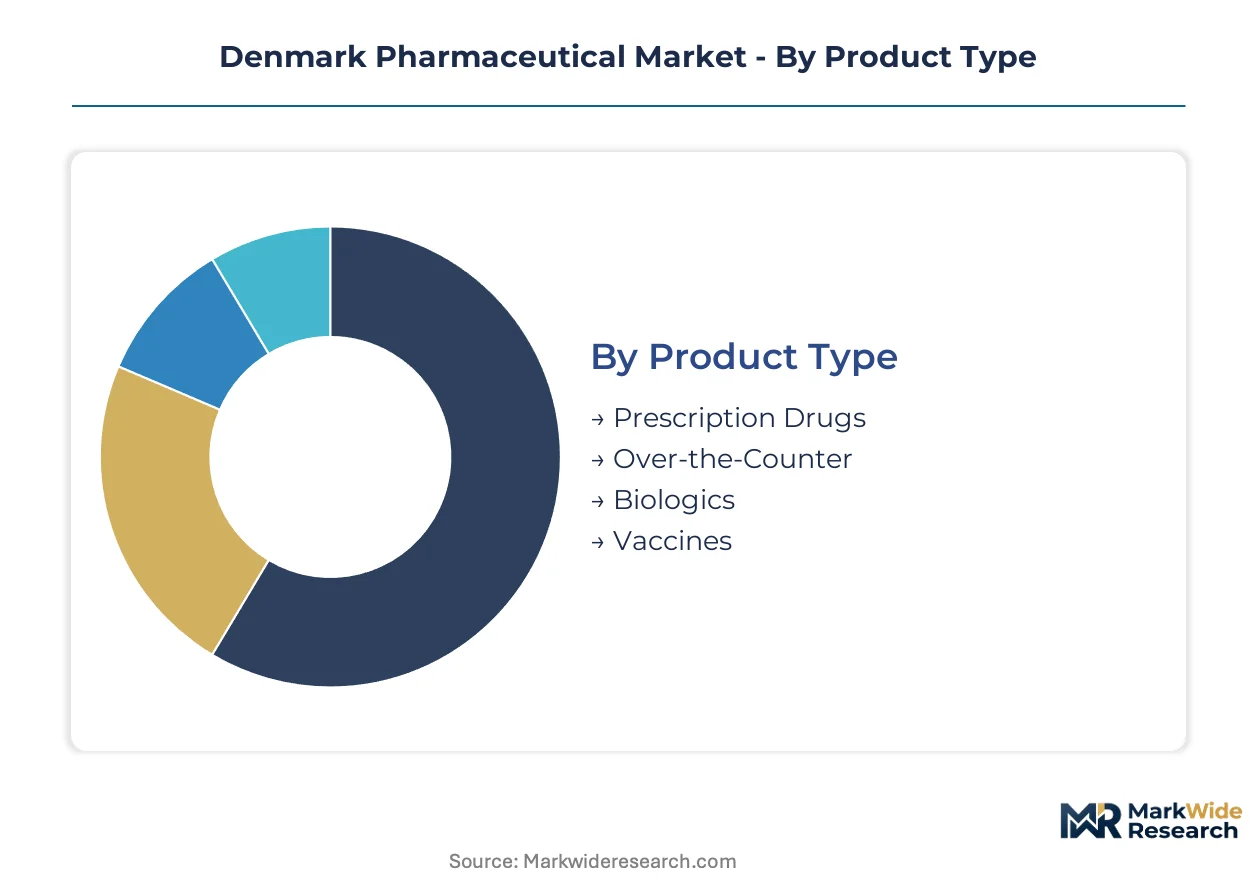
Segmentation in Denmark's pharmaceutical market reveals distinct procurement rhythms and margin profiles across product categories. Hospital tendering cycles, pharmacy reimbursement tiers, and manufacturing complexity create divergent commercial dynamics for each segment cluster.
Product Type:
Cycle times vary dramatically across product categories, with biologics requiring extended fermentation runs and cold-chain distribution while OTC formulations turn inventory rapidly through retail channels.
- Prescription Drugs:Chemically synthesized small molecules dominate chronic disease maintenance therapy with purity specifications exceeding 99.5% under ICH Q1A stability protocols. Danish Health Authority reimbursement negotiations concentrate demand for cardiovascular and metabolic prescriptions through hospital formularies in Zealand and Capital Region, though biosimilar substitution rules compress originator pricing power.
- Biologics:Recombinant proteins and monoclonal antibodies command premium positioning due to manufacturing complexity and temperature-sensitive supply chains. GLP-1 peptide demand from Zealand Region hospitals is pulling fermentation capacity expansion across Medicon Valley CDMOs, with single-use bioreactor systems accelerating batch turnover for clinical and commercial supply.
- Over-the-Counter:Self-medication products move through pharmacy and grocery retail channels with minimal regulatory friction. Danish Medicines Agency classification determines switch status from prescription to OTC, creating revenue inflection points for mature molecules.
- Vaccines:Prophylactic immunization products flow through national procurement frameworks with multi-year tender structures. Danish Health Authority coordinates childhood and seasonal vaccination programs, concentrating volume in pediatric and influenza segments.
Prescription drugs anchor the volume base while biologics gains share at the steepest rate.
Application:
Cost tier differentiation separates acute intervention therapies from chronic maintenance protocols, with oncology commanding the highest per-patient expenditure and infectious disease treatments facing procurement pressure from generic substitution.
- Oncology:Cytotoxic agents, targeted small molecules, and immuno-oncology biologics concentrate R&D investment from hospital-based research institutions. Capital Region oncology centers drive demand for novel checkpoint inhibitors and CAR-T cell therapies through accelerated access frameworks.
- Cardiology:Antihypertensives, anticoagulants, and lipid-lowering agents constitute high-volume chronic therapy with established generic penetration. Danish primary care prescribing patterns favor fixed-dose combinations that improve adherence metrics in national quality registries.
- Neurology:Disease-modifying therapies for multiple sclerosis and Parkinson's disease require specialized distribution through hospital pharmacies. Injectable biologics dominate multiple sclerosis maintenance, while oral formulations retain neurology share for epilepsy management.
- Infectious Diseases:Antibacterial and antiviral agents face concentrated tender pressure from regional procurement consortiums. Zealand Region framework agreements specify biosimilar alternatives unless clinical justification is documented, shifting margin capture to centralized purchasing bodies.
Cardiology underpins the volume base while oncology climbs the fastest.
End User:
Customer type determines channel economics, with hospitals capturing biologics margin through direct procurement and pharmacies retaining OTC and prescription dispensing fees.
- Hospitals:Regional tendering consortiums in Zealand and Capital Region bypass traditional wholesaler relationships for biologics and oncology injectables. Centralized procurement bodies now specify biosimilar alternatives in framework agreements, compressing manufacturer pricing power.
- Pharmacies:Community and hospital pharmacy dispensing channels handle prescription fulfillment with reimbursement determined by Danish Health Authority price lists. Self-medication products generate front-of-store revenue with lower regulatory burden.
- Clinics:Specialist outpatient facilities concentrate demand for dermatology and endocrinology injectables. Leo Pharma's topical and injectable portfolios flow through private dermatology clinics in Greater Copenhagen.
- Research Institutions:Academic medical centers and CROs in Medicon Valley drive early-stage clinical trial demand. University of Copenhagen and Technical University of Denmark anchor translational research partnerships with commercial sponsors.
Hospitals anchor the volume base while research institutions expand most quickly.
Delivery Mode:
Volume concentration favors injectable administration for biologics, though patient preference and adherence economics sustain oral formulation development in maintenance therapy segments.
- Injectable:Subcutaneous and intravenous delivery dominates biologics administration with prefilled syringe and autoinjector formats improving compliance. Novo Nordisk's GLP-1 peptide leadership relies on injection device engineering for patient experience differentiation.
- Oral:Tablet and capsule formulations retain cardiology and neurology maintenance therapy share due to patient convenience and lower administration cost. Immediate-release and extended-release technologies enable lifecycle management for mature molecules.
- Topical:Dermatology applications concentrate demand for cream, gel, and ointment formulations through pharmacy and clinic channels. Leo Pharma competes in psoriasis and eczema segments with specialized topical portfolios.
- Inhalation:Respiratory drug delivery requires device-drug combination expertise with dry powder and metered-dose formats. Danish Medicines Agency enforces EU MDR-aligned standards for device-drug combinations, shaping development timelines.
Injectable delivery anchors the volume base while inhalation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish pharmaceutical exports flow primarily toward Germany and Sweden, with cross-border supply chains integrating Kalundborg production hubs into Northern European hospital procurement networks.
Capital Region
Zealand Region hospitals drive GLP-1 peptide demand through centralized tendering, pulling fermentation capacity toward Medicon Valley. The Danish Health Authority coordinates reimbursement negotiations that determine formulary placement for novel metabolic therapies. Copenhagen anchors the biotech cluster with University of Copenhagen and Rigshospitalet feeding translational research partnerships.
North Jutland
Aalborg municipalities offer brownfield industrial sites with upgraded utility infrastructure attracting large-scale biologics manufacturing investment. The Danish Environmental Protection Agency enforces discharge limits that favor consolidated production facilities with centralized wastewater treatment. Kalundborg's bulk API manufacturers are responding by expanding fermentation footprint rather than maintaining distributed small-scale plants.
Region Zealand
Regional tendering consortiums bypass traditional wholesaler relationships for biologics and oncology injectables, compressing manufacturer pricing power through framework agreements. The Danish Medicines Agency's pharmacovigilance standards shape product development timelines for device-drug combinations. Slagelse and Næstved host specialized logistics providers serving hospital pharmacy networks.
Central Denmark Region
Aarhus University Hospital drives demand for novel immuno-oncology therapies through accelerated access frameworks. The Danish Health Authority's national quality registries track prescribing patterns for chronic disease maintenance therapy. Aarhus anchors CRO activity supporting early-stage clinical trials for Medicon Valley biotechs.
Denmark Pharmaceutical Market Competitive Environment
Channel-controlling players compete with product-specialist players across Denmark's pharmaceutical sector, with hospital procurement consolidation favoring scale while technology platforms sustain differentiation. The structure tilts toward concentrated biologics manufacturing alongside fragmented specialty therapeutics development. Three archetypes dominate: fermentation-scale peptide producers, extended-release technology specialists, and dermatology-focused topical formulators. Capacity expansion and strategic technology licensing constitute the primary competitive moves, with greenfield site selection increasingly driven by renewable energy access and wastewater treatment infrastructure.
Among Danish-based innovators, Novo Nordisk, Ascendis Pharma, and Leo Pharma occupy distinct positioning within the competitive structure. Novo Nordisk represents the fermentation-scale archetype with in-house peptide production capacity. Ascendis Pharma exemplifies platform-driven differentiation through its TransCon extended-release technology. Leo Pharma anchors the specialty therapeutics tier with focused portfolios in dermatology and thrombosis. Each occupies a position shaped by manufacturing modality rather than therapeutic category alone.
| Leading Market Players |
|---|
| Orifarm Group |
| Ascendis Pharma |
| Novo Nordisk |
| Muna Therapeutics |
| Gubra |
| H. Lundbeck |
| ALK-Abelló Nordic |
| SNIPR Biome |
| Leo Pharma |
| Others |
Value Chain & Pricing Dynamics
Asian contract manufacturers supplying over 80% of small-molecule active pharmaceutical ingredients concentrate upstream margin capture in Denmark's formulation sector, while hospital tendering consortiums in Zealand and Capital Region redirect downstream value toward centralized procurement bodies through multi-year framework agreements.
Pricing Analysis
Originator biologics command substantial premiums over biosimilar alternatives and legacy small molecules across Danish hospital formularies. Three-tier pricing structure across originator biologics, approved biosimilars, and generic small molecules reflects manufacturing complexity, Danish Health Authority reimbursement tiers, and patent status. Cost compression in insulin and growth hormone segments is intensifying because Danish Health Authority tendering rules favor lowest-cost biologics. Regional procurement consortiums exhibit highest price sensitivity, while specialized clinics retain willingness to pay for differentiated delivery technologies.
Supply Chain Analysis
Medicon Valley CDMOs and specialized fermentation facilities hold capacity for peptide and antibody production serving Danish formulators. Active pharmaceutical ingredient supply draws from India, China, and selected European synthesis hubs for chemical intermediates. Fermentation capacity rests on stainless-steel and single-use bioreactor infrastructure, with cold-chain distribution feeding from Kalundborg and Hillerød production sites. Single-source vulnerability concentrates in GLP-1 peptide fermentation capacity, where Novo Nordisk's in-house scale dominates. Distribution runs through regional hospital pharmacy networks and specialized logistics providers serving Zealand and Capital Region tendering consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's pharmaceutical sector operates as a regulatory entrenchment story, where Danish Medicines Agency pharmacovigilance standards and Danish Health Authority reimbursement negotiations create structural barriers that extend product lifecycles and protect incumbent positioning.
For Market Incumbents: Build manufacturing moats through backward integration into single-use bioreactor capacity and captive fermentation scale in North Jutland brownfield sites. Ascendis Pharma's TransCon platform demonstrates how extended-release technology differentiation defends against biosimilar substitution pressure. Incumbents should secure Danish Environmental Protection Agency discharge permits ahead of green transition mandates, locking in site approvals before competitors consolidate wastewater treatment infrastructure. For New Entrants and Emerging Players: Build out rare disease and orphan indication portfolios where Danish Health Authority accelerated access frameworks reduce tendering pressure. White-space concentrates in hematology and endocrinology segments underserved by existing GLP-1 and insulin portfolios. New entrants should target research institution partnerships through University of Copenhagen and Rigshospitalet translational channels, leveraging Medicon Valley CRO density to compress clinical trial timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with platform-technology biotechs holding validated delivery mechanisms but requiring commercial infrastructure. Five-to-ten year viability hinges on Danish green transition mandate compliance and EU MDR harmonization execution. Acquisition targets should demonstrate renewable-powered manufacturing roadmaps and centralized wastewater treatment capabilities. Signal to watch is Danish Environmental Protection Agency permit issuance velocity for new greenfield biologics sites.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor deployment in North Jutland compresses batch turnover for peptide production. |
| Regulatory Approval Pathway | Danish Medicines Agency parallel scientific advice accelerates EMA centralized review preparation. |
| Backward Integration | Captive fermentation capacity reduces API import dependency exposure to Asian supply volatility. |
| Green Manufacturing Transition | Renewable-powered production aligns with Danish 2045 carbon-neutrality targets and permit preferences. |
| Hospital System Partnership | Zealand Region framework agreements secure multi-year formulary placement for metabolic therapies. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors; and secondary validation through EMA submissions, ClinicalTrials.gov records, Danish Medicines Agency pharmacovigilance databases, and hospital procurement consortium tender documents. Bottom-up patient-flow modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Forecast inputs span product type, application, end user, and delivery mode segmentation across the projection horizon, with treatment line and regional regulatory cluster as additional modeled dimensions. CAGRs derive from trend extrapolation calibrated against historical reimbursement trajectory and manufacturing capacity expansion announcements. Danish Health Authority tendering rule changes and EU MDR implementation timelines feed scenario weights.
Sensitivities concentrate around EMA centralized review queue duration, Asian API shipping disruption frequency, and Danish Environmental Protection Agency discharge limit enforcement intensity. Forecasts embed assumptions regarding biosimilar substitution velocity and green transition mandate compliance costs. Quarterly review of hospital tendering consortium award patterns and CDMO capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Short-Acting Beta-Agonists Market