
 Migraine Nasal Spray Market | 2026-2036
Migraine Nasal Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Migraine Nasal Spray Market Outlook
The EU Green Deal's pharmaceutical sustainability framework is realigning packaging and manufacturing requirements across European supply chains. Pfizer Inc. leverages its established respiratory delivery infrastructure to sustain manufacturing scale for migraine nasal formulations. GlaxoSmithKline plc anchors its position through deep clinical data archives spanning triptan efficacy studies. Eli Lilly and Company differentiates via CGRP-targeting innovation pipelines that extend beyond traditional serotonin agonist mechanisms.
Migraine nasal spray constitutes a non-oral, transmucosal drug delivery system formulated as aqueous or powder suspensions propelled through nasal atomizers, achieving cerebrospinal fluid-adjacent absorption within minutes of administration. Its primary commercial purpose is rapid abortive treatment of moderate-to-severe migraine attacks, bypassing gastrointestinal delays and first-pass hepatic metabolism that compromise oral triptan onset. The triptan active ingredient category retains dominant volume share due to decades of prescriber familiarity and generic accessibility, while CGRP antagonists represent the fastest-expanding margin pool as novel mechanisms command premium positioning. Home care end users now constitute the largest addressable channel, reflecting patient preference for self-administered acute intervention outside institutional settings.
The FDA maintains stringent bioequivalence standards for nasal spray products through its Office of Generic Drugs, while the EMA's Committee for Medicinal Products for Human Use enforces comparable quality benchmarks across European markets. These frameworks elevate development costs for new entrants but simultaneously protect incumbent innovators from rapid commoditization. Stakeholders must monitor evolving pharmacovigilance requirements for CGRP antagonist classes and anticipate how decentralized clinical trial models reshape post-market evidence generation obligations.
Market Dynamics
The FDA's evolving bioequivalence guidance for nasal drug products is compressing generic approval timelines while simultaneously elevating incumbent protection, creating a bifurcated competitive structure where novel CGRP mechanisms and established triptan formulations pursue divergent value capture strategies.
Growth Catalysts
- Home care migration:Patient preference for self-administered acute intervention outside institutional settings is expanding addressable demand for portable nasal atomizer devices.
- EU Green Deal pharmaceutical sustainability framework:Packaging and manufacturing realignment requirements are accelerating supply chain modernization investments that improve production economics for aqueous suspension formats.
- Transmucosal absorption advantage:Cerebrospinal fluid-adjacent pharmacokinetics bypassing first-pass hepatic metabolism is electrifying prescriber adoption in emergency medicine and neurology practices.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for triptan classes clusters in select Asian contract manufacturers, exposing formulation sponsors to single-source vulnerability.
- Bioequivalence testing costs:FDA Office of Generic Drugs requirements for pharmacokinetic bridging studies and comparative clinical endpoint trials impose capital barriers exceeding small-cap development budgets.
- Injectable CGRP antagonists:Subcutaneous autoinjector formats with extended duration profiles present substitution risk for patients requiring prophylactic rather than abortive intervention.
Strategic Opportunities
- Pediatric indication expansion:Regulatory pathways for adolescent migraine populations remain underdeveloped relative to adult approvals, presenting first-mover advantage for sponsors with existing safety databases.
- Decentralized clinical trial infrastructure:Post-market evidence generation obligations are compressing through remote monitoring platforms, reducing per-patient trial costs for novel mechanism sponsors.
- Powder suspension technology convergence:Dry particle engineering with breath-powered delivery systems is opening formulation stability advantages over aqueous alternatives in tropical distribution environments.
Industry Challenges
- Pharmacovigilance talent scarcity:CGRP antagonist class-specific safety signal detection requires specialized expertise in monoclonal antibody adverse event profiling that outpaces current workforce supply.
- Legacy respiratory manufacturing retrofit:Established nasal spray production lines originally configured for steroid or antihistamine formulations require substantial capital reconfiguration to meet CGRP peptide handling specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Migraine Nasal Spray Market |
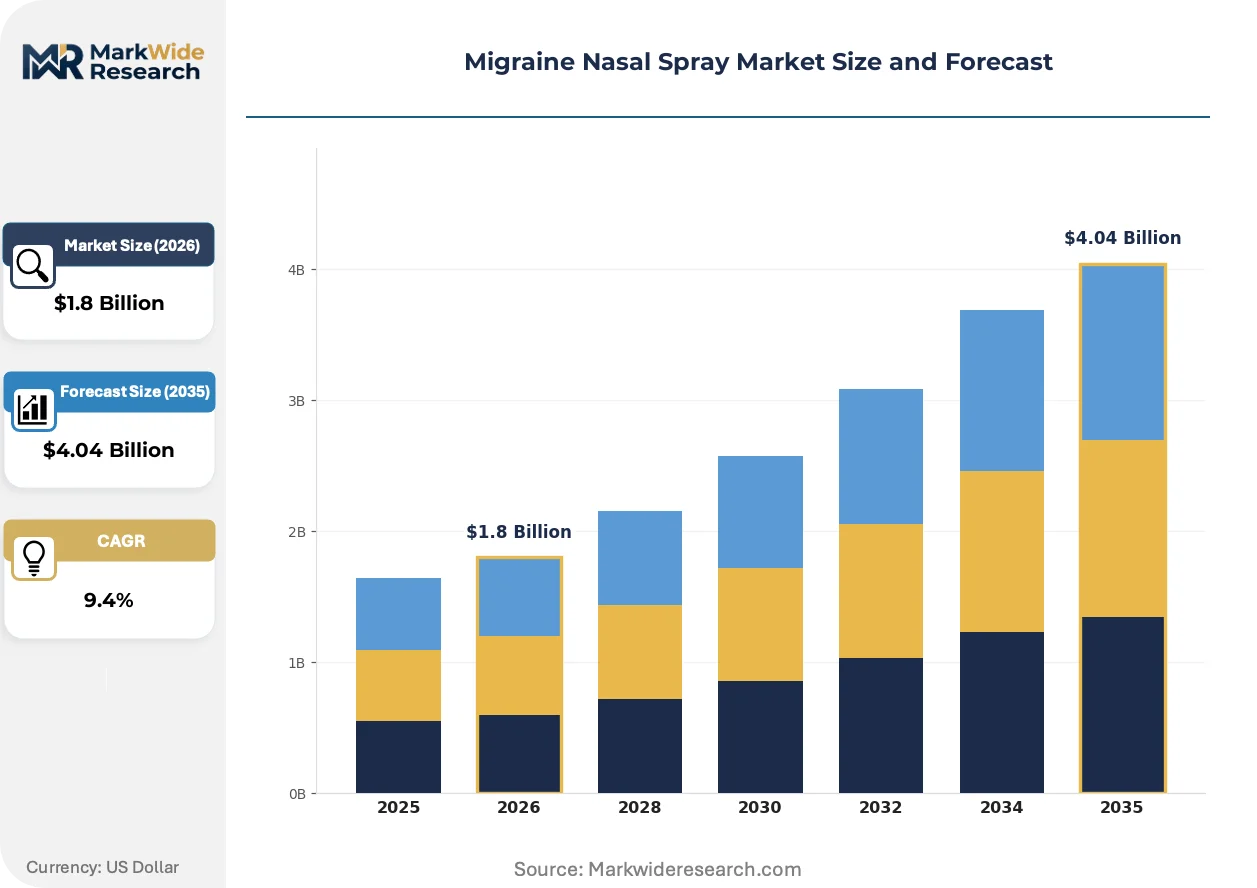
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sumatriptan, Zolmitriptan, Dihydroergotamine, Others Active Ingredient: Triptans, Ergots, CGRP Antagonists, Others End User: Hospitals, Clinics, Home Care, Emergency Services Packaging Type: Single-Dose, Multi-Dose, Bulk Packaging, Others |
| Companies Covered | Impel NeuroPharma, Pfizer Inc., GlaxoSmithKline plc, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Merck, Novartis AG, Dr. Reddy's Laboratories Ltd., Cipla Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Migraine Nasal Spray Market Strategic Shifts
Novel delivery mechanisms and regulatory data architectures are simultaneously reshaping product differentiation and evidence generation protocols, with sponsors investing in platform technologies that compress development timelines while expanding therapeutic indices.
Precision-engineered powder suspensions with aerodynamic particle sizing is electrifying absorption kinetics through optimized nasal cavity deposition patterns. Neurology practices in the United States are adopting these formats for patients with gastric motility disorders that compromise oral triptan efficacy. The structural consequence is compression of time-to-therapeutic-onset benchmarks that aqueous formulations struggle to match.
EMA Committee for Medicinal Products for Human Use quality benchmarks are tightening impurity thresholds for peptide-based nasal formulations, forcing sponsors to invest in continuous manufacturing monitoring systems. European supply chains are responding by consolidating analytical testing capabilities at centralized quality hubs rather than distributed release sites. This regulatory friction most acutely affects mid-cap sponsors lacking captive manufacturing infrastructure.
Direct-to-patient pharmacy fulfillment models are displacing traditional wholesale distribution for maintenance acute therapy regimens. United States migraine patients now receive automated refill shipments triggered by attack frequency algorithms, bypassing retail pharmacy inventory constraints. This channel innovation concentrates demand volume with specialty pharmacy networks capable of cold-chain handling and patient education protocols.
Migraine Nasal Spray Market Segmentation
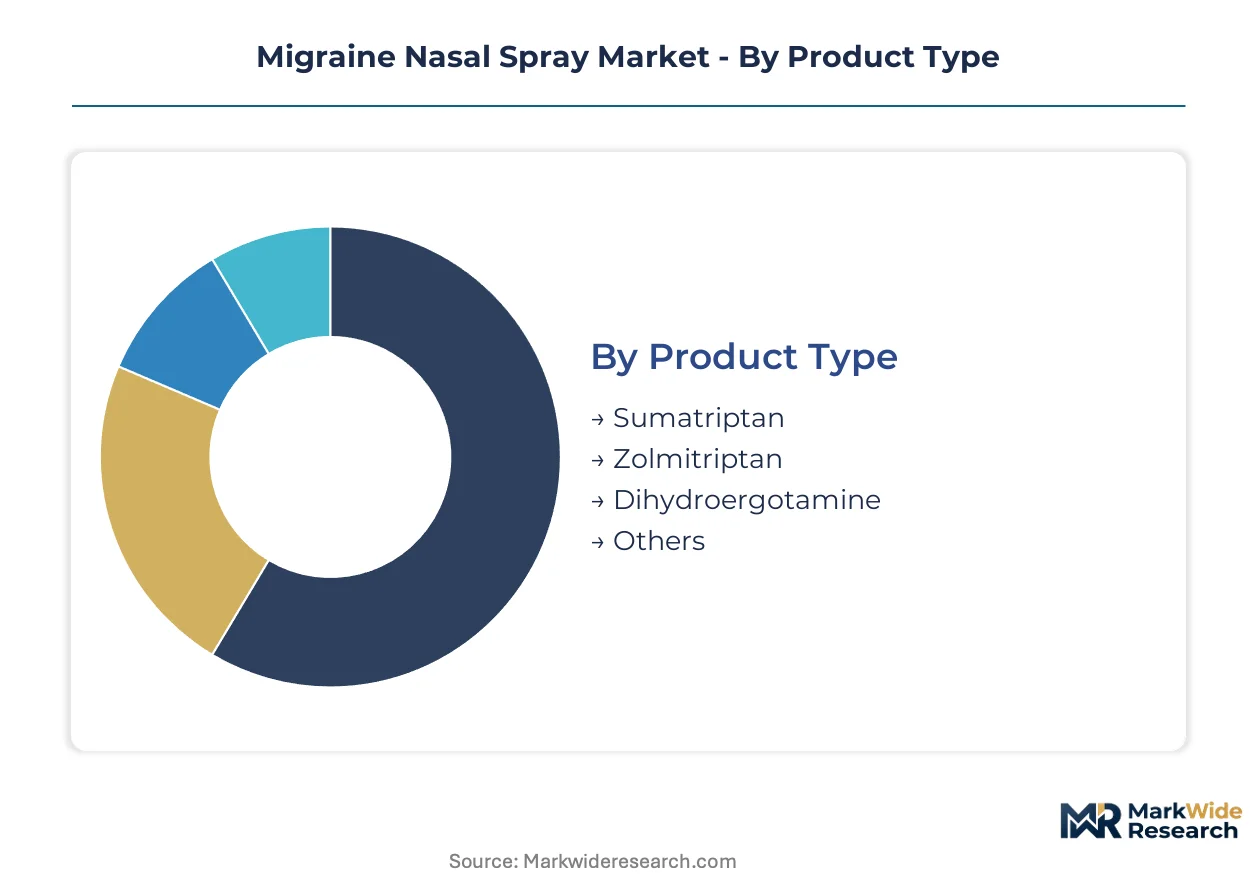
Segmentation in migraine nasal spray markets exposes how formulation chemistry, delivery specifications, and care setting economics create divergent margin architectures. Each axis reveals distinct competitive moats and substitution vulnerabilities that shape sponsor investment priorities.
Product Type:
Formulation chemistry and receptor binding profiles differentiate acute migraine therapies across the triptan and ergot classes.
- Sumatriptan:The first-generation selective serotonin receptor agonist achieves rapid cerebrovascular constriction through 5-HT1B/1D receptor binding. Demand concentrates in United States retail pharmacy channels where generic accessibility and decades of prescriber familiarity sustain volume leadership despite slower onset than newer alternatives.
- Zolmitriptan:Second-generation triptan with enhanced lipophilicity permits faster central nervous system penetration and superior efficacy in patients with allodynia. Neurology practices in Germany and France favor this specification for treatment-resistant cases where blood-brain barrier kinetics determine therapeutic outcome.
- Dihydroergotamine:Ergot alkaloid derivative with prolonged receptor occupancy suited for migraine attacks exceeding 24 hours duration. Hospital emergency departments in Italy and Spain deploy this formulation when triptan failure or cardiovascular contraindications exclude first-line options.
- Others:Emerging non-triptan abortive formulations including novel ion channel modulators and combination therapies.
Mature deployment sits with Sumatriptan. Newer deployment is concentrated in Zolmitriptan.
Active Ingredient:
Mechanism of action defines reimbursement tiering and prescriber switching economics across serotonin agonist, ergot, and peptide antagonist categories.
- Triptans:Serotonin 5-HT1B/1D receptor agonists comprising sumatriptan, zolmitriptan, rizatriptan, and related analogs. Volume concentrates in mature markets with established generic manufacturing infrastructure, though cardiovascular risk profiles restrict use in patients with coronary artery disease or uncontrolled hypertension.
- Ergots:Dihydroergotamine and ergotamine tartrate formulations with non-selective serotonin and dopamine receptor activity. United Kingdom hospital formularies retain these agents for status migrainosus protocols where prolonged vasoconstriction outweighs tolerability concerns.
- CGRP Antagonists:Calcitonin gene-related peptide receptor blockers including rimegepant and ubrogepant nasal formulations. These agents are climbing the fastest as United States specialty pharmacy networks promote mechanism-based differentiation for patients with cardiovascular comorbidities excluding triptan use.
- Others:Investigational agents targeting PACAP, orexin, and glutamate pathways in pre-commercial development stages.
Volume leadership belongs to Triptans. Margin expansion concentrates with CGRP Antagonists.
End User:
Care setting determines device portability requirements, clinical oversight intensity, and reimbursement pathway complexity.
- Home Care:Self-administered acute intervention outside institutional settings using portable nasal atomizer devices. Patient preference for treatment autonomy and pharmacy automation infrastructure are expanding this channel fastest in United States and United Kingdom markets.
- Hospitals:Inpatient neurology and emergency medicine departments managing refractory migraine or complicated presentations. France and Germany maintain higher hospitalization thresholds for migraine, sustaining institutional volume despite outpatient migration trends.
- Clinics:Outpatient neurology and headache specialty practices providing supervised initial dosing and device training.
- Emergency Services:Pre-hospital and ambulance-based acute intervention for severe attacks with vomiting or altered consciousness.
Institutional volume anchors in Hospitals. Patient-preferred deployment is expanding fastest in Home Care.
Packaging Type:
Primary container configuration balances sterility assurance, dosing precision, and supply chain economics across patient and institutional segments.
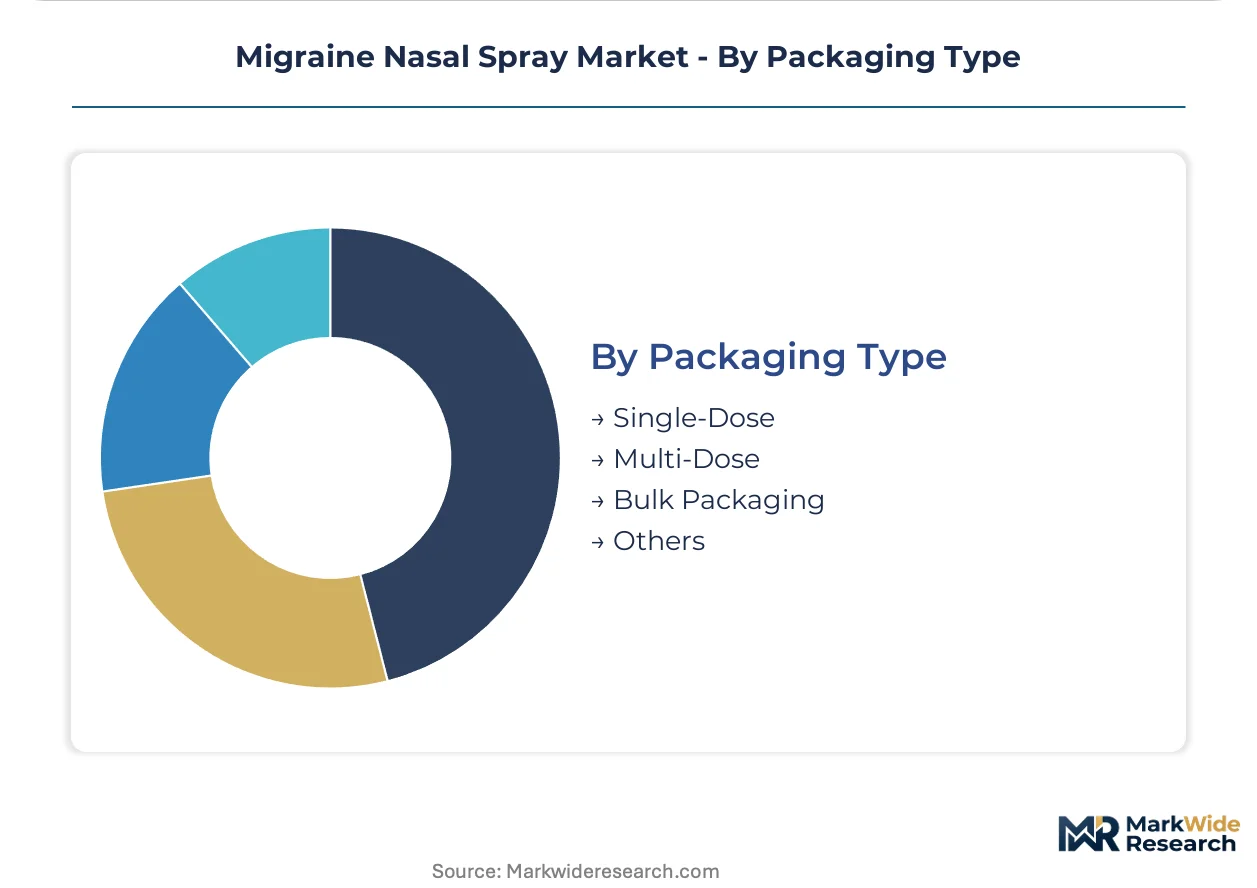
- Single-Dose:Unit-of-use vials or ampoules eliminating preservative requirements and cross-contamination risk. Cold-chain distribution in tropical markets favors this format for peptide-based CGRP formulations where multi-dose stability is compromised.
- Multi-Dose:Pump-actuated bottles with antimicrobial preservatives enabling 30-120 day use periods. Chronic migraine patients in United States maintenance therapy programs prefer this economics for predictable monthly costs.
- Bulk Packaging:Hospital and clinic inventory formats reducing per-unit procurement overhead for high-volume institutional purchasers.
- Others:Novel blister configurations and patient compliance packaging with integrated attack diaries.
Institutional procurement favors Bulk Packaging. Patient-directed volume is shifting toward Single-Dose formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cambridge, Massachusetts anchors North American migraine therapeutics development, hosting dense clusters of biotech incubators and FDA pre-submission consulting firms that compress regulatory pathway timelines for nasal delivery innovators.
United States
Specialty pharmacy networks in the United States concentrate acute migraine prescription volume through automated refill programs triggered by attack frequency algorithms. FDA Office of Generic Drugs bioequivalence standards for nasal spray products elevate development costs but protect incumbent innovators from rapid commoditization. The Research Triangle Park corridor in North Carolina hosts contract manufacturing organizations scaling aqueous suspension production for CGRP peptide formulations.
Germany
Neurology practices in Germany favor zolmitriptan specifications for treatment-resistant cases where blood-brain barrier kinetics determine therapeutic outcome. EMA Committee for Medicinal Products for Human Use quality benchmarks tighten impurity thresholds for peptide-based nasal formulations, forcing sponsors toward continuous manufacturing monitoring. The Rhine-Main metropolitan region consolidates analytical testing capabilities at centralized quality hubs serving European supply chains.
United Kingdom
Hospital formularies in the United Kingdom retain ergot alkaloid derivatives for status migrainosus protocols where prolonged vasoconstriction outweighs tolerability concerns. MHRA post-Brexit regulatory divergence creates parallel submission requirements that extend approval timelines for novel mechanisms. The Golden Triangle biotech corridor between London, Cambridge, and Oxford anchors translational research partnerships linking academic headache centers to commercial formulation sponsors.
India
Contract manufacturing organizations in India cluster active pharmaceutical ingredient production for triptan classes, exposing formulation sponsors to single-source vulnerability during supply disruptions. CDSCO accelerated approval pathways for nasal generic products compress market entry timelines relative to European benchmarks. The Hyderabad-Visakhapatnam pharmaceutical corridor specializes in aqueous suspension engineering for export markets requiring tropical stability specifications.
Japan
PMDA pharmacovigilance requirements for CGRP antagonist classes mandate extended post-market surveillance periods that delay commercial scaling for novel entrants. The Kansai region's Osaka-Kobe industrial zone hosts precision powder engineering facilities developing breath-powered delivery systems for dry particle suspensions. Japanese neurology practices demonstrate slower adoption curves for non-triptan mechanisms, preserving volume concentration with established serotonin agonist formulations.
Migraine Nasal Spray Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with captive respiratory delivery infrastructure. Incumbent sponsors leverage decades of prescriber familiarity with triptan mechanisms to defend volume positions against CGRP antagonist challengers. Three archetypes dominate: Big Pharma conglomerates with platform delivery capabilities, mid-cap specialists in peptide formulation engineering, and generic manufacturers exploiting bioequivalence pathway compression. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic partnerships with decentralized clinical trial platforms.
Among North American innovators, Impel NeuroPharma exemplifies the precision delivery archetype through its focus on engineered particle technologies, while Pfizer Inc. anchors the diversified pharmaceutical tier with established respiratory manufacturing scale. Eli Lilly and Company occupies a distinct position within the CGRP-targeting innovation vector. These three entities collectively represent the competitive spectrum spanning novel mechanism development, manufacturing infrastructure deployment, and commercial distribution reach.
| Leading Market Players |
|---|
| Impel NeuroPharma |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Merck |
| Novartis AG |
| Dr. Reddy's Laboratories Ltd. |
| Cipla Limited |
| Others |
Value Chain & Pricing Dynamics
Patient preference for single-dose CGRP antagonist formats in United States specialty pharmacy channels is forcing formulation sponsors toward cold-chain distribution infrastructure that elevates per-unit logistics costs and compresses margins on premium peptide therapies.
Pricing Analysis
Value-based pricing anchored to time-to-onset benchmarks separates premium CGRP antagonist positioning from standard triptan tiers. Price differentiation hinges on cardiovascular safety profiles and nasal deposition technology certification, with FDA bioequivalence tiering creating additional stratification. Pricing pressure intensifies in the generic triptan segment as Indian CDSCO accelerated approvals compress entry timelines. Hospital procurement committees exhibit highest price sensitivity, while United States maintenance therapy patients demonstrate lowest elasticity due to pharmacy automation lock-in.
Supply Chain Analysis
Freight cost volatility for temperature-controlled peptide shipments is reshaping geographic sourcing strategies across the migraine nasal spray supply base. Active pharmaceutical ingredient manufacturing concentrates in India and China for triptan classes, while CGRP peptide synthesis clusters in United States and Switzerland contract facilities. Formulation sponsors depend on single-source Asian suppliers for sumatriptan base materials, exposing production schedules to tariff disruption and customs clearance delays. Distribution runs through United States specialty pharmacy networks with cold-chain handling capabilities, bypassing traditional wholesale channels for maintenance therapy regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The migraine nasal spray market operates as a cost-of-compliance story where FDA Office of Generic Drugs bioequivalence standards and EMA impurity thresholds erect formidable barrier-to-entry moats favoring sponsors with captive analytical infrastructure and regulatory affairs depth.
For Market Incumbents: Anticipate CGRP antagonist substitution risk in cardiovascular-contraindicated patient populations by accelerating pediatric indication filings and powder suspension platform investments. Backward integration into peptide API supply and consolidation of decentralized clinical trial partnerships will defend margin position against mid-cap formulation challengers. For New Entrants and Emerging Players: The price-point gap between premium CGRP antagonists and economy-tier generic triptans creates white-space opportunity in adolescent migraine populations and tropical distribution markets requiring dry particle stability. Target India and Southeast Asia for CDSCO accelerated pathway exploitation, with breath-powered delivery technology as the primary go-to-market differentiator against aqueous incumbent formulations. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with peptide engineering capabilities and existing nasal delivery device partnerships over pure-play generic manufacturers. Long-term viability rests on CGRP pipeline diversification and regulatory approval velocity rather than manufacturing scale alone. Watch FDA pediatric guidance publication timelines as the critical inflection signal for first-mover valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Regulatory Pathway Advancement | FDA adolescent indication filings unlock underserved migraine populations with extended exclusivity protection. |
| Backward Integration into Peptide API Supply | Captive CGRP active pharmaceutical ingredient production insulates against single-source Asian supplier vulnerability. |
| Powder Suspension Technology Licensing | Breath-powered dry particle delivery opens tropical distribution markets where aqueous stability fails. |
| Specialty Pharmacy Network Partnership | Direct-to-patient fulfillment automation secures United States maintenance therapy volume against retail channel displacement. |
| Decentralized Clinical Trial Infrastructure | Remote monitoring platforms compress post-market evidence generation costs for novel mechanism sponsors. |
Study Parameters
Independent corroboration across regulatory submission databases, specialty pharmacy dispensing records, and contract manufacturing capacity reports underwrites the qualitative findings in this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing triangulate volume estimates across the forecast window.
Comparable-period anchoring to historical prescription volume trends and regulatory approval timelines established the forecast framework baseline. Segmentation dimensions modeled include active ingredient mechanism, formulation chemistry, end-user care setting, packaging configuration, and regional regulatory cluster. CAGRs were derived from patient prevalence projections, reimbursement pathway evolution, and generic entry timeline assumptions. Forecast inputs incorporated FDA bioequivalence guidance revision schedules and EMA quality benchmark tightening trajectories for peptide-based nasal formulations.
Underlying measurement precision varies by segment; mature triptan markets with established generic infrastructure carry tighter precision than emerging CGRP antagonist categories with limited commercial history. Forecasts reflect assumptions about regulatory pathway continuity, reimbursement stability, and API supply chain resilience that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Risedronate Sodium Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Czech Republic Pharmaceutical Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Germany Pharmaceuticals Market