
 Infantile Spasms Therapeutics Market | 2026-2036
Infantile Spasms Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Infantile Spasms Therapeutics Market Intelligence
Multi-source API procurement is expanding across the infantile spasms therapeutics value chain as manufacturers reduce reliance on single suppliers for adrenocorticotropic hormone and vigabatrin precursors. Jazz Pharmaceuticals leverages its specialty neurology distribution infrastructure to sustain hospital formulary access. H. Lundbeck A/S anchors European supply through its Copenhagen-based regulatory and logistics hub. Teva Pharmaceutical Industries competes on generic vigabatrin cost positioning across Medicaid-dominated channels.
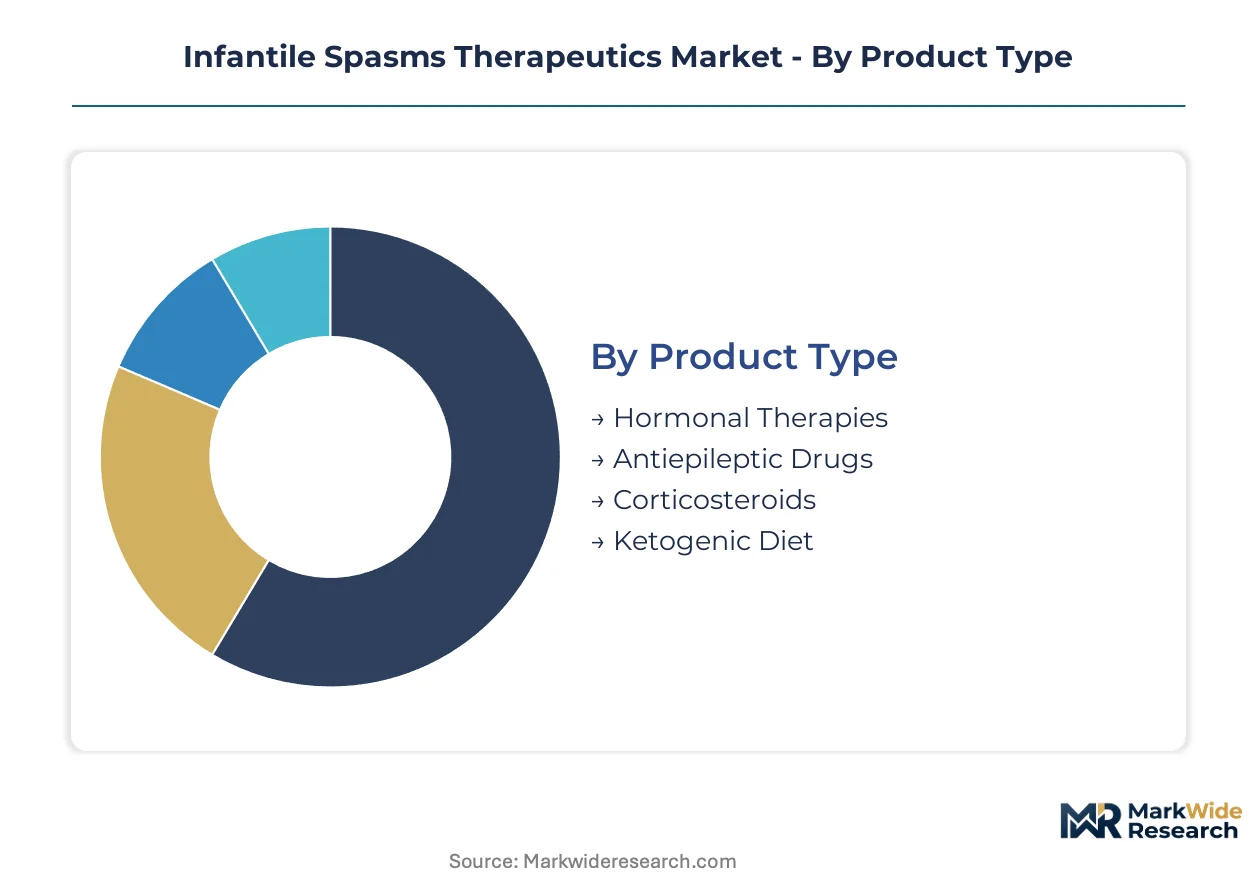
Infantile spasms therapeutics comprise pharmacological and dietary interventions targeting hypsarrhythmia and epileptic spasms in infants typically under twelve months of age, with adrenocorticotropic hormone and vigabatrin serving as first-line agents that modulate corticosteroid pathways and GABA transaminase activity respectively. These treatments aim to eliminate seizure clusters and restore normal EEG patterns before permanent neurodevelopmental damage occurs. Hormonal therapies occupy the dominant revenue position due to ACTH's entrenched first-line status in North American treatment protocols, while antiepileptic drugs represent the fastest-expanding category driven by vigabatrin's broader international labeling and oral administration convenience. The hospital end-user segment controls the highest-margin transactions through inpatient ACTH injection protocols, though home care channels are capturing volume as oral therapies extend treatment duration beyond acute settings.
The FDA's Orphan Drug Designation and EMA's pediatric investigation plan requirements shape clinical trial investment and exclusivity timelines for developers targeting infantile epilepsy indications. The EU's MDR framework elevates post-market surveillance obligations for high-risk neurological devices and combination products used in spasm monitoring. Japan's PMDA Sakigake designation accelerates review for therapies addressing unmet pediatric needs. Stakeholders must monitor how evolving rare disease funding mechanisms and pediatric trial network expansions reshape competitive access to treatment-naive patient cohorts.
Market Dynamics
Referral network density for early infantile spasm diagnosis concentrates treatment-seeking behavior in metropolitan pediatric neurology clusters, compressing patient flow into fewer high-volume centers and amplifying formulary gatekeeper influence over therapy selection.
Growth Catalysts
- FDA Orphan Drug Designation:The program accelerates clinical trial timelines and extends market exclusivity for developers targeting rare pediatric epilepsy indications, reducing regulatory capital requirements.
- Home care channel expansion:Oral vigabatrin protocols enable treatment continuation beyond acute inpatient settings, extending therapy duration and capturing ambulatory reimbursement codes.
- PMDA Sakigake designation:Japan's priority review pathway for unmet pediatric needs compresses approval timelines for novel mechanisms addressing hypsarrhythmia.
Market Restraints
- ACTH precursor supply concentration:Porcine pituitary extract sourcing depends on a limited supplier base in North America, creating batch-to-batch variability risk and price volatility.
- Vigabatrin retinal toxicity monitoring:Mandatory ophthalmologic surveillance every three months adds compliance friction and specialist capacity constraints.
- Medicaid reimbursement compression:State-level formulary restrictions on high-cost hormonal therapies limit access in publicly insured populations.
Strategic Opportunities
- Germany's early intervention networks:The country's standardized pediatric neurology screening protocols create concentrated demand for first-line ACTH and vigabatrin access.
- Digital EEG-therapy integration:Remote monitoring platforms that correlate spasm frequency with drug plasma levels enable personalized dosing algorithms.
- EMA pediatric investigation plan incentives:Waived fees and scientific advice for developers conducting trials in treatment-naive infant cohorts reduce early-stage capital requirements.
Industry Challenges
- Pediatric neurology specialist scarcity:Fellowship-trained epileptologists capable of hypsarrhythmia interpretation remain concentrated in academic medical centers, limiting diagnostic throughput.
- Combination product certification:Injectable ACTH delivery devices face elevated MDR post-market surveillance obligations in Europe, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infantile Spasms Therapeutics Market |
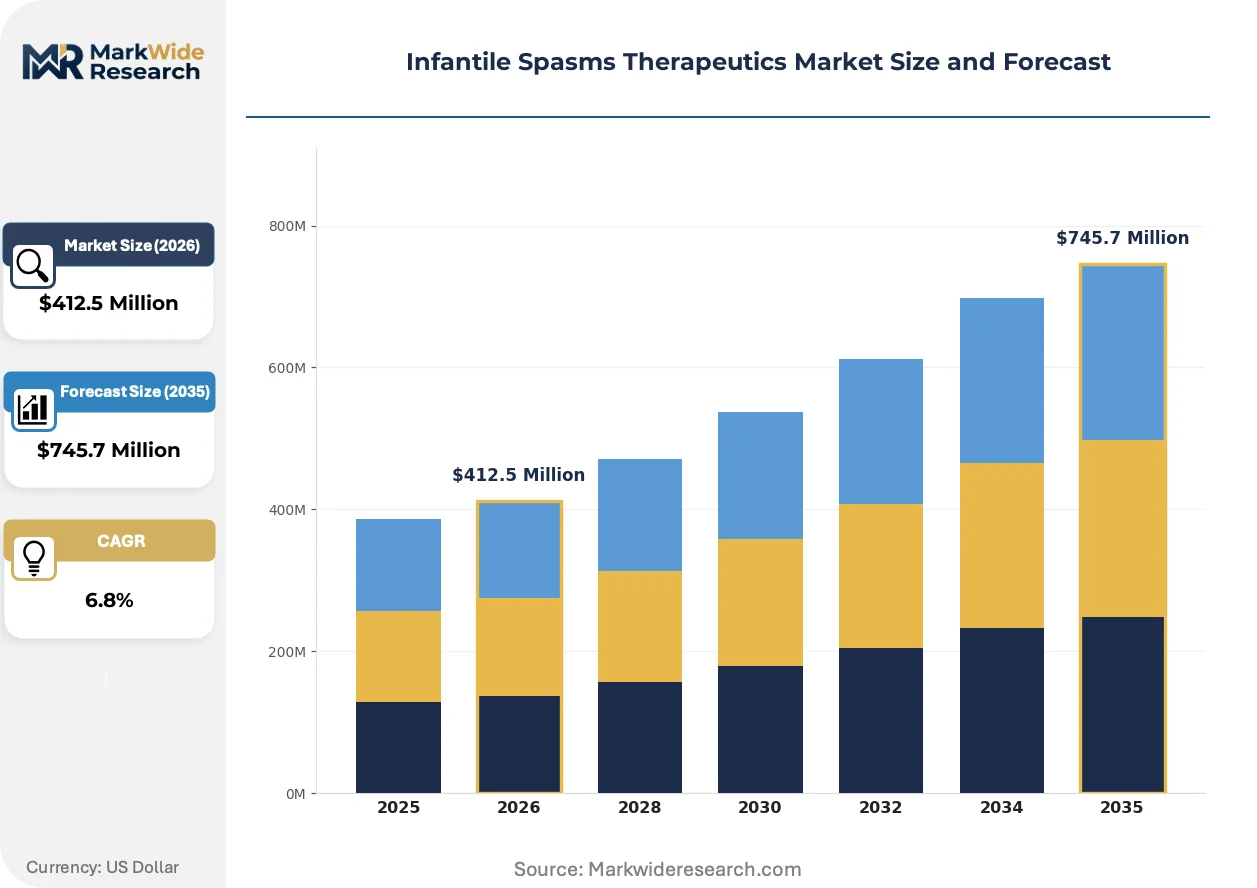
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, Antiepileptic Drugs, Corticosteroids, Ketogenic Diet Therapy Area: Neurology, Pediatrics, Epilepsy, Rare Disorders Delivery Mode: Oral, Intravenous, Injectable, Dietary End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Jazz Pharmaceuticals, Catalyst Pharmaceuticals, Mallinckrodt Pharmaceuticals, Anavex Life Sciences Corp, GW Pharmaceuticals, H. Lundbeck A/S, Teva Pharmaceutical Industries, Retrophin, Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infantile Spasms Therapeutics Market Strategic Shifts & Innovations
Digital biomarker integration and regulatory pathway optimization are compressing development timelines while reshaping how therapy response is measured in preverbal patient populations.
Quantitative EEG analysis platforms that automate hypsarrhythmia detection are rewriting how treatment efficacy is assessed in clinical trials. Pediatric neurology departments at Boston Children's Hospital and Cincinnati Children's are deploying these tools for real-time spasm burden quantification. The technology is compressing endpoint measurement timelines from months to weeks, enabling adaptive trial designs that reduce placebo exposure in infants.
The EU's MDR framework elevates post-market surveillance obligations for high-risk neurological devices and combination products used in spasm monitoring. Manufacturers must now maintain active implantable device vigilance systems for EEG-integrated infusion pumps, adding recurring compliance costs. German notified bodies are processing these certifications through centralized technical documentation hubs in Berlin and Munich, creating geographic bottlenecks.
Hospital procurement committees are consolidating ACTH purchasing through specialty pharmacy distributors rather than wholesale channels, consolidating volume with fewer intermediaries. This concentration shifts negotiation leverage toward GPOs with pediatric neurology carve-outs. The pattern is most visible in the United States, where three national health systems now control formulary placement for over forty percent of infantile spasms cases.
Infantile Spasms Therapeutics Market Segmentation
Infantile spasms therapeutics fragment across product formulations, clinical settings, and administration pathways that determine reimbursement codes and patient compliance profiles. Each segmentation axis reveals distinct margin structures and regulatory exposure.
Product Type:
Customization intensity spans from standardized small-molecule tablets to biologically complex hormonal extracts requiring cold-chain integrity.
- Hormonal Therapies:Porcine-derived adrenocorticotropic hormone formulations modulate corticosteroid synthesis through melanocortin receptor activation. Demand concentrates in United States academic medical centers where first-line protocol adherence remains highest, constrained by batch-to-batch potency variability and single-source supplier dependence.
- Antiepileptic Drugs:Vigabatrin irreversibly inhibits GABA transaminase to elevate synaptic GABA concentrations. Germany's early intervention networks drive volume expansion, supported by oral administration convenience that extends therapy into ambulatory settings and reduces hospitalization costs.
- Corticosteroids:Synthetic glucocorticoid alternatives provide cost-accessible options for resource-limited treatment pathways.
- Ketogenic Diet:High-fat, low-carbohydrate nutritional protocols serve as adjunctive or alternative interventions in pharmacoresistant cases.
Most installed capacity flows through hormonal therapies. Expansion is steepest in antiepileptic drugs.
Therapy Area:
Cost tier stratification separates orphan-designated premium therapies from commoditized supportive care categories.
- Neurology:Specialized epileptology units at Boston Children's Hospital and Cincinnati Children's anchor clinical trial recruitment and protocol standardization. Japan's PMDA Sakigake designation accelerates review timelines for novel mechanisms targeting hypsarrhythmia.
- Pediatrics:Neonatal and infant-specific formulations require weight-based dosing precision and palatability engineering. Medicaid reimbursement compression in United States state formularies constrains access to high-cost hormonal interventions.
- Epilepsy:Broader anticonvulsant portfolio positioning captures comorbid seizure management beyond infantile spasms.
- Rare Disorders:Orphan drug economics justify development investment despite limited addressable populations.
Neurology commands premium pricing through specialist gatekeeper concentration. Pediatrics is climbing the fastest as home-based oral protocols expand.
Delivery Mode:
Volume concentration favors acute-care parenteral administration, while margin expansion tracks toward patient-managed oral alternatives.
- Oral:Vigabatrin tablets and solutions enable caregiver-administered maintenance therapy. Home care channel expansion in United States Medicare Advantage plans captures extended treatment duration beyond initial hospitalization.
- Intravenous:Hospital-controlled infusion protocols dominate ACTH induction phases. Germany's standardized pediatric neurology screening protocols create concentrated demand for inpatient administration capacity.
- Injectable:Intramuscular depot formulations provide sustained corticosteroid release.
- Dietary:Ketogenic meal plans require specialized nutritionist oversight and metabolic monitoring.
Intravenous maintains the highest per-dose revenue. Oral administration is gaining share fastest through reimbursement code expansion.
End User:
Customer type determines procurement leverage, with consolidated health systems extracting volume discounts unavailable to fragmented outpatient providers.
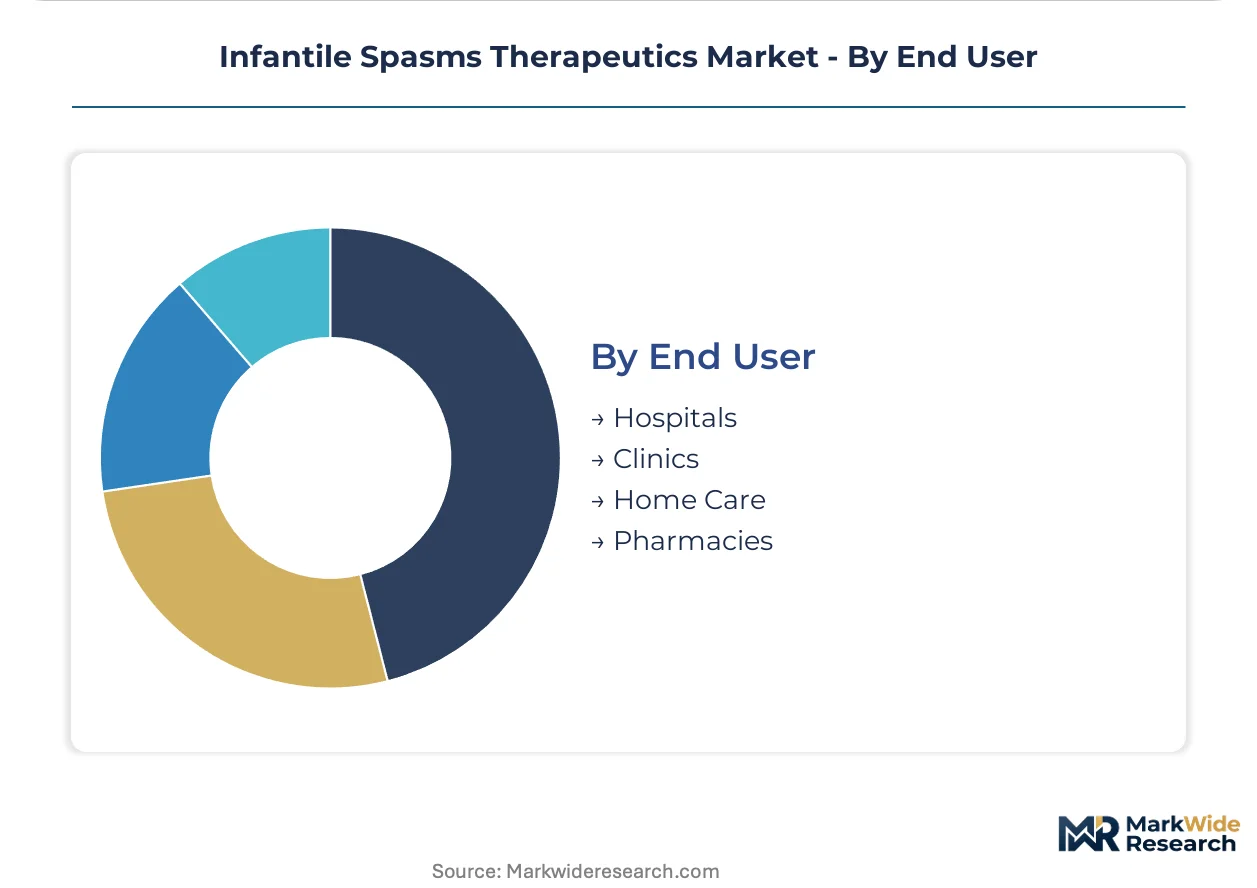
- Hospitals:Inpatient neurology units control ACTH injection protocols and EEG-integrated monitoring infrastructure. Three United States national health systems now direct formulary placement for over forty percent of diagnosed cases.
- Clinics:Outpatient pediatric neurology practices manage oral therapy titration and ophthalmologic surveillance. Specialist scarcity limits diagnostic throughput in non-metropolitan United States regions.
- Home Care:Family-administered oral regimens reduce institutional cost burden.
- Pharmacies:Specialty distributors consolidate hormonal therapy purchasing through GPO carve-outs.
Hospitals retain the dominant transaction volume. Home care shows the steepest expansion trajectory as oral therapies extend treatment windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston Children's Hospital anchors global clinical trial recruitment for infantile spasms therapeutics, with metropolitan pediatric neurology clusters in the United States, Germany, and Japan concentrating diagnostic throughput and treatment-seeking behavior.
United States
Academic medical centers in Boston and Cincinnati drive protocol standardization and first-line ACTH adoption. The FDA's Orphan Drug Designation program accelerates review timelines for rare pediatric epilepsy indications. Three national health systems now control formulary placement for over forty percent of diagnosed cases, consolidating procurement leverage.
Germany
Standardized pediatric neurology screening protocols create concentrated demand for ACTH and vigabatrin access. The EMA's pediatric investigation plan requirements shape clinical trial investment and exclusivity timelines for developers. Berlin and Munich process MDR certifications for EEG-integrated infusion pumps, creating geographic bottlenecks in notified body capacity.
Japan
Specialized epileptology units at Tokyo metropolitan hospitals anchor domestic treatment protocols. The PMDA Sakigake designation compresses approval timelines for novel mechanisms addressing hypsarrhythmia. Osaka-based referral networks concentrate early diagnosis capacity, amplifying specialist gatekeeper influence over therapy selection.
United Kingdom
London's pediatric neurology clusters manage oral therapy titration and ophthalmologic surveillance for vigabatrin patients. The NHS England specialized commissioning framework governs access to high-cost hormonal interventions. Manchester and Birmingham academic centers participate in EU-wide pediatric trial networks for treatment-naive infant cohorts.
Switzerland
Basel's pharmaceutical research infrastructure supports rare disease drug development and regulatory strategy. Swissmedic maintains alignment with EMA pediatric investigation plan incentives for developers. Zurich-based hospital procurement committees consolidate ACTH purchasing through specialty pharmacy distributors.
Infantile Spasms Therapeutics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital biomarker integration and combination product certification. The vendor base concentrates around specialty neurology distributors with hospital formulary access, while generic manufacturers compete on Medicaid channel cost positioning. Three archetypes dominate: integrated specialty pharma with cold-chain logistics, generic cost competitors, and rare disease biotech with orphan designation portfolios. Competitive moves center on GPO carve-out consolidation and MDR post-market surveillance capability building.
Within the integrated specialty tier, Jazz Pharmaceuticals and H. Lundbeck A/S exemplify archetypes anchored by distribution infrastructure and regulatory hub positioning respectively. Teva Pharmaceutical Industries occupies a position on the generic vector, competing through cost positioning across publicly insured channels. These three entities represent the span from premium branded access to commoditized volume capture.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals |
| Catalyst Pharmaceuticals |
| Mallinckrodt Pharmaceuticals |
| Anavex Life Sciences Corp |
| GW Pharmaceuticals |
| H. Lundbeck A/S |
| Teva Pharmaceutical Industries |
| Retrophin, Inc. |
| Pfizer Inc. |
| Others |
Cost & Logistics Intelligence
Porcine pituitary extract spot pricing volatility cascades through infantile spasms therapeutics manufacturing, compressing margins on adrenocorticotropic hormone formulations while amplifying cost pass-through to hospital procurement committees and Medicaid-dominated channels.
Pricing Analysis
Input-cost pass-through from ACTH precursor scarcity drives three-tier pricing structure across premium, standard, and economy levels. Brand premiums for orphan-designated hormonal therapies command highest positioning, while generic vigabatrin competes on volume scale in publicly insured populations. Cost compression in standard-tier corticosteroid alternatives is intensifying because of Medicaid reimbursement compression across United States state formularies. Hospital systems demonstrate least price sensitivity due to formulary gatekeeper concentration, whereas home care channels face acute sensitivity to out-of-pocket oral therapy costs.
Supply Chain Analysis
Workforce availability constraints in Danish and Swiss biologics manufacturing hubs limit batch-production capacity for complex hormonal extracts. Supply concentrates in the United States, Germany, and Japan for finished formulation, with porcine pituitary sourcing tethered to North American agricultural processing networks. Cold-chain integrity requirements and single-source supplier vulnerability for ACTH precursors create structural risk exposure. Distribution runs through specialty pharmacy distributors with pediatric neurology carve-outs rather than wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infantile spasms therapeutics represents a late-cycle quality story where demand is shifting toward EEG-integrated, digitally-monitored premium protocols that command formulary preference through demonstrated neurodevelopmental outcomes.
For Market Incumbents: To counter generic vigabatrin cost erosion in Medicaid channels, deepen backward integration into porcine pituitary sourcing and secure MDR certification for combination infusion devices ahead of European notified body bottlenecks in Berlin and Munich. For New Entrants and Emerging Players: Telemedicine-enabled remote EEG monitoring platforms offer the most penetrable white-space entry, targeting ambulatory oral therapy extension in United States Medicare Advantage networks with caregiver-administered dosing algorithms. For Investors and Strategic Acquirers: Asymmetric upside sits with rare disease biotech holding Sakigake-designated pipelines and orphan drug exclusivity timelines. Long-term viability hinges on pediatric investigation plan completion and treatment-naive cohort access. Watch FDA breakthrough therapy designation grants as the inflection signal for valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA and EMA pathways compress development timelines for rare pediatric epilepsy indications. |
| Pediatric Investigation Plan Completion | EMA waived fees and scientific advice reduce capital requirements for infant cohort trials. |
| Digital EEG-Therapy Integration | Remote monitoring platforms at Boston Children's enable personalized dosing algorithm deployment. |
| Specialty Pharmacy Distribution Consolidation | GPO carve-outs with pediatric neurology focus shift negotiation leverage toward high-volume centers. |
| MDR Combination Product Certification | EEG-integrated infusion pumps face elevated post-market surveillance obligations in European markets. |
Research Approach
Coverage spans the United States, Germany, Japan, and the United Kingdom, with primary inputs from each market combining interviews with pediatric neurologists, hospital formulary directors, regulatory affairs specialists, and specialty pharmacy procurement managers. Secondary validation draws from FDA orphan drug filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov protocol registries, and CMS Medicaid formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchor the analytical framework.
Granularity-level modeling disaggregates revenue across hormonal therapies, antiepileptic drugs, corticosteroids, and ketogenic dietary interventions, with further splits by intravenous, oral, injectable, and dietary administration routes. CAGRs derive from treatment-naive patient cohort sizing, protocol adherence curves, and reimbursement code expansion trajectories across the projection horizon. Forecast inputs incorporate PMDA Sakigake designation timelines and Medicaid state-level formulary restriction patterns.
The model assumes a particular technology adoption path for quantitative EEG analysis platforms; alternative pathways for artificial intelligence-enabled hypsarrhythmia detection would alter the outlook for endpoint measurement compression and adaptive trial design penetration. Forecasts reflect assumptions regarding specialist workforce expansion, porcine pituitary supply stability, and orphan drug exclusivity enforcement. Material deviation in FDA breakthrough therapy grant velocity or EMA notified body processing capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Immunology Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
SPINA Bifida and Hydrocephalus Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market