
 Europe Veterinary Pharmaceuticals Market | 2026-2036
Europe Veterinary Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Veterinary Pharmaceuticals Market Intelligence
The capital-intensity divergence between large integrated manufacturers and mid-tier formulation specialists is reorganizing competitive dynamics across Europe. Boehringer Ingelheim leverages captive biologics production and scale to dominate vaccine supply chains. Zoetis anchors its position through deep R&D pipelines in monoclonal antibody therapies for companion animals. Virbac differentiates via geographic focus on Mediterranean livestock markets and antiparasitic specialization.
Europe veterinary pharmaceuticals encompass chemically synthesized and biologically derived agents formulated for disease prevention, treatment, and productivity enhancement in food-producing and companion animals, with specifications covering active pharmaceutical ingredient purity, stability profiles, and species-specific pharmacokinetic parameters. Vaccines command the largest value share due to mandatory immunization programs in cattle and poultry operations across the continent, while monoclonal antibody therapies represent the fastest-expanding product class as patent cliffs open opportunities for novel biologics. Injectable delivery modes retain preference in livestock settings for assured dosing compliance, though oral formulations gain share in companion animal segments driven by owner convenience and palatability improvements.
EMA's veterinary medicines regulation, REACH chemical safety frameworks, and the EU Green Deal pharmaceutical strategy collectively tighten environmental risk assessments and residue monitoring requirements for market authorization holders. The F-Gas Regulation further constrains propellant choices in topical aerosol formulations, pushing reformulation investments toward aqueous and dry-powder alternatives. Stakeholders must monitor evolving EMA guidance on antimicrobial resistance containment measures and their cascading effects on product development priorities and portfolio rationalization decisions.
Market Dynamics
EMA's veterinary medicines regulation is compressing development timelines while REACH residue limits and the EU Green Deal pharmaceutical strategy force simultaneous reformulation investments across active ingredient portfolios.
Growth Catalysts
- EU Green Deal pharmaceutical strategy:Mandatory environmental risk assessments for all new veterinary authorizations are accelerating investment in biodegradable formulations and green chemistry platforms.
- Germany's livestock density:Concentrated cattle and swine operations in Lower Saxony and Bavaria sustain bulk vaccine procurement volumes that amortize manufacturing fixed costs.
- Monoclonal antibody platform expansion:Patent expirations on small-molecule antiparasitics are redirecting R&D budgets toward species-specific biologics for companion animal oncology and dermatology.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for veterinary antibiotics concentrates in Asian contract manufacturers, exposing European formulators to shipping cost volatility and customs delays.
- F-Gas Regulation constraints:The prohibition on hydrofluorocarbon propellants forces immediate reformulation of topical aerosol products toward aqueous spray systems with inferior skin penetration profiles.
- Antimicrobial resistance containment measures:EMA guidance restricting prophylactic antibiotic use in food-producing animals is eliminating historical revenue streams from metaphylactic product lines.
Strategic Opportunities
- Poland's veterinary service network expansion:Underpenetrated regions in Greater Poland and Silesia present first-mover advantages for companion animal preventive care franchises.
- Digital prescription platforms:Telemedicine integration with automated refill systems is opening direct-to-owner channels that bypass traditional veterinary clinic distribution markups.
- CSRD sustainability disclosure mandates:Early alignment with corporate sustainability reporting requirements positions portfolios favorably in procurement tenders from integrated livestock conglomerates.
Industry Challenges
- Biologics manufacturing talent scarcity:Cell culture and downstream purification expertise for veterinary monoclonal antibodies concentrates at human pharmaceutical specialists, forcing competitive recruitment against higher-wage sectors.
- Multi-jurisdiction authorization complexity:Divergent national implementation of EMA centralized procedures creates parallel track requirements for Germany, France, and the United Kingdom that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Veterinary Pharmaceuticals Market |
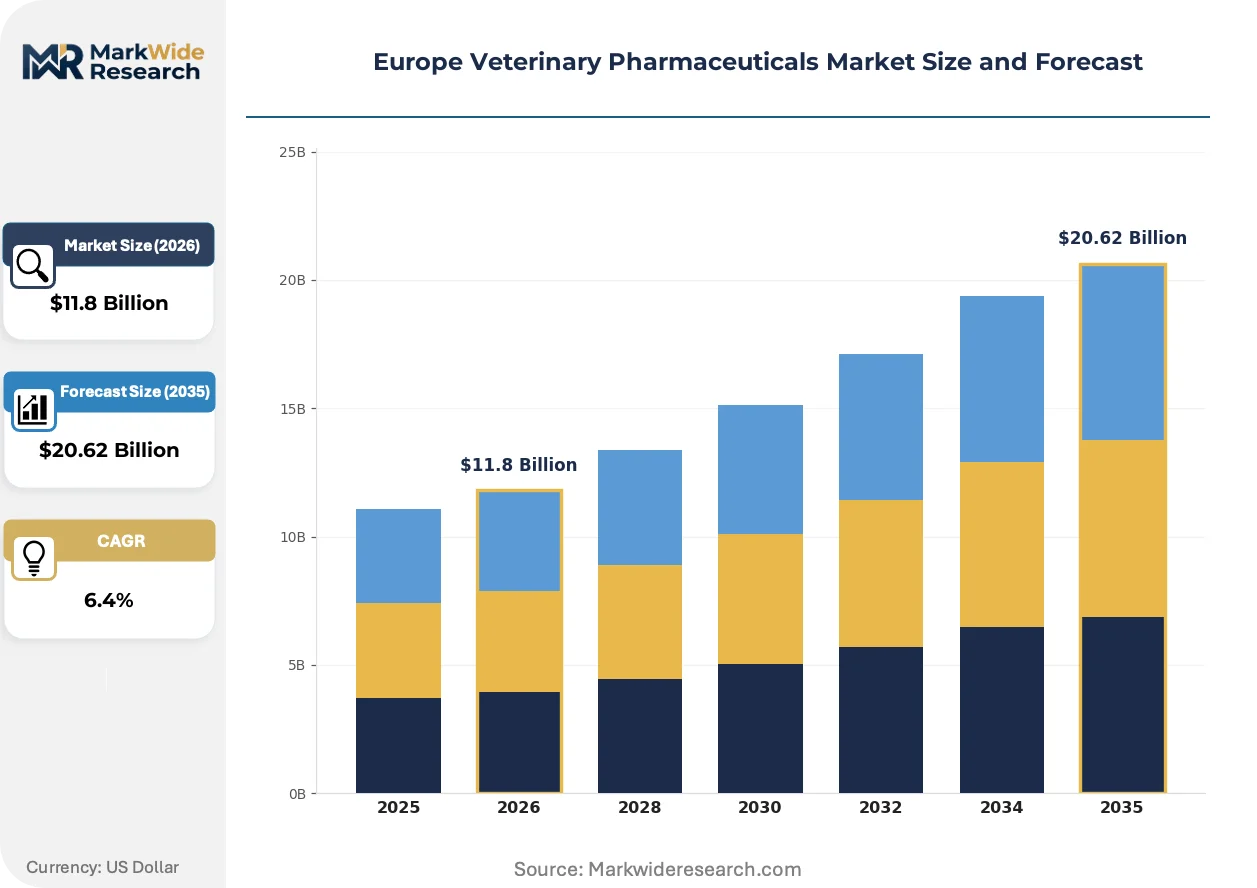
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Antiparasitics, Hormones Application: Livestock, Companion Animals, Aquaculture, Wildlife Delivery Mode: Injectable, Oral, Topical, Intranasal End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Animal Shelters |
| Companies Covered | Boehringer Ingelheim, Zoetis, Ceva Santé Animale, MSD Animal Health, Elanco, Virbac, Dechra Pharmaceuticals, Vetoquinol, Hipra, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Veterinary Pharmaceuticals Market Strategic Shifts & Innovations
Biologic delivery technologies and residue detection methods are compressing traditional formulation advantages while digital distribution platforms restructure historic channel relationships across European markets.
Oral palatability enhancers for companion animal therapeutics are fragmenting the injectable-dominant delivery landscape. Zoetis and Virbac have both launched chewable formulations with extended-release matrices that match parenteral pharmacokinetic profiles. German and French pet owners are adopting these products at rates that compel clinic inventory reconfiguration, fragmenting wholesale purchasing patterns that favored bulk injectable vials.
REACH chemical safety frameworks are tightening residue monitoring protocols for groundwater discharge from manufacturing facilities. The European Chemicals Agency now requires annual environmental fate studies for all veterinary pharmaceuticals with predicted environmental concentrations above threshold limits. Cattle vaccine producers in the Netherlands and Denmark are responding by installing closed-loop water systems that eliminate effluent discharge entirely.
Subscription-based preventive care bundles are displacing transactional product sales in companion animal segments. Mars Veterinary Health and IVC Evidensia are piloting monthly membership programs that include scheduled vaccinations, parasiticide delivery, and telemedicine consultations. This model concentrates purchasing decisions at corporate procurement functions rather than individual clinic veterinarians, compressing brand loyalty and price negotiation leverage for incumbent manufacturers.
Europe Veterinary Pharmaceuticals Market Segmentation
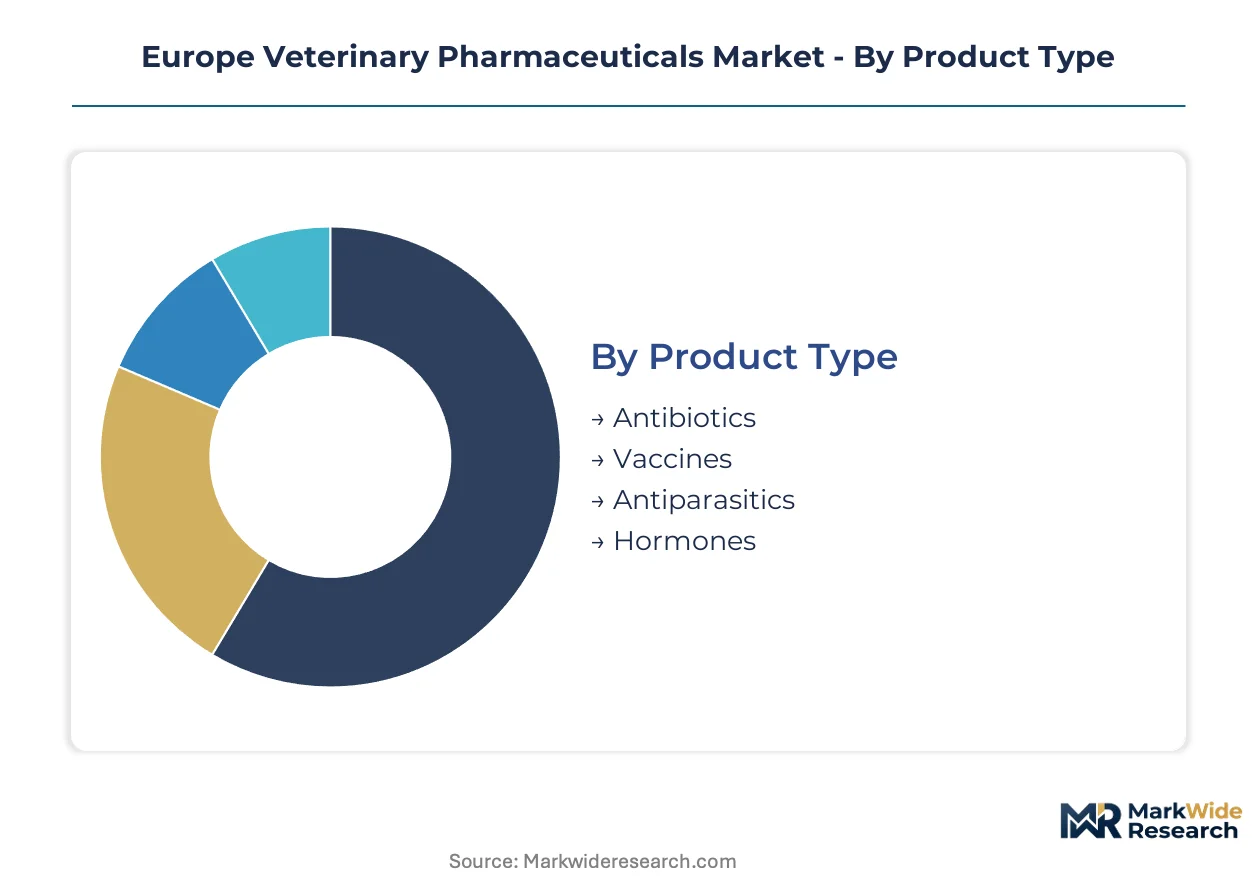
EMA authorization pathways diverge sharply across product categories, with biologics facing centralized procedures while chemically synthesized agents navigate national implementation variations. Understanding these regulatory fault lines enables portfolio positioning that aligns manufacturing investments with approval timeline realities.
Product Type:
EMA's veterinary medicines regulation imposes distinct environmental risk assessment tiers that reshape development economics across chemical and biological platforms.
- Vaccines:Inactivated and live-attenuated formulations for cattle and poultry dominate procurement volumes across Germany, France, and the United Kingdom. Mandatory immunization programs in concentrated livestock operations sustain bulk manufacturing amortization.
- Antiparasitics:Patent cliffs on small-molecule compounds are redirecting R&D toward species-specific biologics. Mediterranean livestock markets in Spain and Italy drive demand for endectocides targeting mixed helminth and ectoparasite burdens.
- Antibiotics:EMA guidance restricting prophylactic use in food-producing animals is eliminating historical metaphylactic revenue streams. Formulators now concentrate on therapeutic indications with documented resistance stewardship protocols.
- Hormones:Growth promoters face outright prohibition under EU residue monitoring frameworks; reproductive hormones for estrus synchronization retain authorization in cattle breeding programs.
Vaccines handle the majority of throughput; antiparasitics are expanding most quickly as patent expirations open biologic substitution pathways.
Application:
Cost tier differentiation separates commodity livestock therapeutics from premium companion animal biologics with tenfold pricing multiples.
- Livestock:Cattle and swine operations in Lower Saxony, Bavaria, and Denmark sustain vaccine procurement volumes that amortize fixed manufacturing costs. REACH residue limits and the EU Green Deal pharmaceutical strategy force simultaneous reformulation investments across antibiotic portfolios.
- Companion Animals:German and French pet owners are driving adoption of chewable extended-release formulations that match parenteral pharmacokinetic profiles. Mars Veterinary Health and IVC Evidensia subscription bundles concentrate purchasing decisions at corporate procurement functions.
- Aquaculture:Norwegian salmon farming operations dominate demand for parasiticides and vaccines against infectious pancreatic necrosis. Closed-containment systems in Scotland and Ireland are expanding addressable market scope.
- Wildlife:Oral vaccination programs for rabies control in fox and raccoon dog populations operate under national wildlife agency contracts with limited commercial scale.
Livestock commands the greatest procurement volume; companion animals climb the fastest on margin contribution per dose.
Delivery Mode:
Customer type fragmentation splits the market between clinic-administered injectables and owner-managed oral formulations with divergent compliance economics.
- Injectable:Parenteral routes retain preference in livestock settings for assured dosing compliance and rapid onset. Bulk vial procurement patterns in veterinary clinic networks favor established manufacturers with cold-chain distribution scale.
- Oral:Palatability-enhanced chewables for companion animals are fragmenting wholesale purchasing patterns that historically favored injectable inventory. Extended-release matrix technologies now match parenteral pharmacokinetic profiles.
- Topical:F-Gas Regulation constraints on hydrofluorocarbon propellants force immediate reformulation toward aqueous spray systems with inferior skin penetration profiles.
- Intranasal:Respiratory disease vaccines in poultry and cattle exploit mucosal immunity induction with reduced handling stress compared to parenteral administration.
Injectable routes retain volume leadership; oral formulations gain share fastest on owner convenience and palatability improvements.
End User:
Supply concentration in integrated livestock conglomerates is compressing price negotiation leverage for incumbent manufacturers.
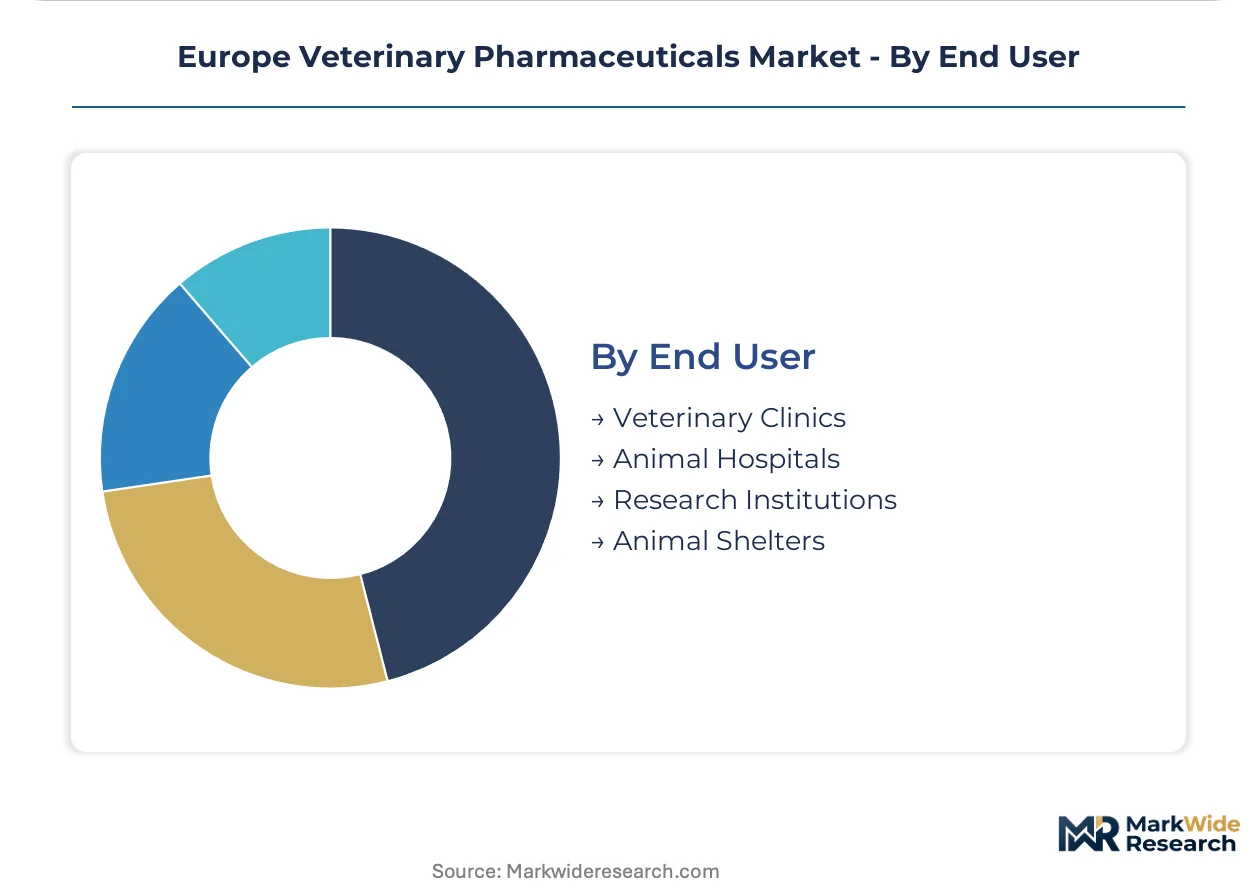
- Veterinary Clinics:Independent practices in Germany, France, and the United Kingdom remain the primary dispensing channel for companion animal therapeutics. Digital prescription platforms and telemedicine integration are opening direct-to-owner channels that bypass traditional distribution markups.
- Animal Hospitals:Corporate consolidation under Mars Veterinary Health and IVC Evidensia concentrates purchasing decisions at procurement functions with standardized formularies. Subscription-based preventive care bundles displace transactional product sales.
- Research Institutions:Academic veterinary schools and contract research organizations drive demand for reference standards and experimental formulations with limited commercial scale.
- Animal Shelters:Municipal and nonprofit operations in Poland and Romania represent price-sensitive volume for core vaccination protocols with minimal margin contribution.
Veterinary clinics handle the majority of dispensing volume; animal hospitals are gaining share fastest on corporate procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Europe, with Mediterranean livestock operators absorbing cost increases more readily than Polish dairy cooperatives operating on thin margins. German and French companion animal owners show the lowest sensitivity to premium biologics pricing, while Romanian and Bulgarian veterinary clinics remain anchored to generic antibiotic procurement.
Germany
Lower Saxony's concentrated cattle operations sustain bulk vaccine procurement volumes that amortize manufacturing fixed costs for suppliers. The country's national pharmaceutical regulator enforces REACH residue limits with particular stringency in groundwater protection zones. Bavaria's swine breeding complexes in Nuremberg-Forchheim corridor are installing closed-loop water systems to eliminate pharmaceutical effluent discharge entirely.
France
Île-de-France pet owners drive adoption of chewable extended-release formulations that match parenteral pharmacokinetic profiles at premium price points. EMA veterinary medicines regulation implementation here includes mandatory environmental risk assessments for all new authorizations. Lyon-based veterinary service networks are consolidating procurement decisions under corporate banners that compress brand loyalty for incumbent manufacturers.
United Kingdom
Post-authorization divergence from EMA centralized procedures creates parallel track requirements that extend time-to-market for biologics developers. The country's national pharmaceutical regulator maintains residue monitoring protocols aligned with EU Green Deal pharmaceutical strategy objectives. Cambridge-Oxford corridor research institutions anchor demand for reference standards and experimental formulations with limited commercial scale.
Spain
Mediterranean livestock markets in Castile-La Mancha and Andalusia drive demand for endectocides targeting mixed helminth and ectoparasite burdens in sheep and goat operations. F-Gas Regulation constraints on hydrofluorocarbon propellants force immediate reformulation of topical aerosol products toward aqueous alternatives. Zaragoza's veterinary pharmaceutical manufacturing cluster is pivoting toward biodegradable formulation platforms to satisfy tightening discharge rules.
Poland
Underpenetrated regions in Greater Poland and Silesia present first-mover advantages for companion animal preventive care franchises expanding from German border provinces. CSRD sustainability disclosure mandates are beginning to influence procurement tenders from integrated livestock conglomerates consolidating in Masovia. Kraków's emerging veterinary service networks are piloting digital prescription platforms that bypass traditional distribution markups.
Europe Veterinary Pharmaceuticals Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European veterinary pharmaceuticals sector. The market structure concentrates around large integrated manufacturers with captive biologics production and mid-tier formulation specialists serving geographic niches. Three archetypes dominate: scale-driven vaccine suppliers with continental distribution networks, R&D-intensive biologics developers targeting companion animal oncology, and antiparasitic specialists with Mediterranean livestock focus. Competitive moves center on portfolio diversification into monoclonal antibody platforms and strategic partnerships with digital prescription infrastructure providers.
Within the scale-driven tier, Boehringer Ingelheim and Zoetis occupy positions that exemplify divergent strategic emphases. Boehringer Ingelheim represents the archetype of captive manufacturing integration across vaccine supply chains. Zoetis anchors the biologics-specialist vector with emphasis on species-specific therapeutic development. Virbac sits within the geographic-focus archetype, concentrating formulation expertise on Mediterranean livestock markets where antiparasitic demand concentrates.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Zoetis |
| Ceva Santé Animale |
| MSD Animal Health |
| Elanco |
| Virbac |
| Dechra Pharmaceuticals |
| Vetoquinol |
| Hipra |
| Others |
Cost & Logistics Intelligence
EMA's centralized veterinary medicines authorization gates both supplier qualification and price differentiation simultaneously, as manufacturers must amortize environmental risk assessment costs across product tiers while REACH residue compliance separates premium biologics from commodity formulations. The resulting cost structure concentrates pricing power with integrated producers capable of captive biologics manufacturing, while mid-tier formulators compete on volume procurement contracts with livestock conglomerates.
Pricing Analysis
Preventive care subscription bundles now drive lifetime value beyond transactional product margins, with Mars Veterinary Health and IVC Evidensia consolidating purchasing decisions at corporate procurement functions. Three-tier pricing structure across premium, standard, and economy levels separates species-specific monoclonal antibodies from generic antibiotics and basic vaccines. Cost compression in the antibiotic segment intensifies because EMA guidance restricts prophylactic use in food-producing animals. Polish dairy cooperatives exhibit highest price sensitivity, while German companion animal owners absorb premium biologics with minimal elasticity.
Supply Chain Analysis
Just-in-time inventory preferences dominate livestock vaccine procurement, with Lower Saxony and Bavaria operations synchronizing delivery to breeding cycles rather than maintaining strategic stockpiles. Active pharmaceutical ingredient production concentrates in India and China, exposing European formulators to shipping cost volatility and customs delays. Cell culture media and specialized adjuvants draw from limited qualified suppliers. Single-source vulnerability persists for veterinary monoclonal antibody manufacturing expertise. Distribution runs through cold-chain logistics networks serving veterinary clinic chains and corporate hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monoclonal antibody platform expansion constitutes a high-growth disruption, as patent cliffs on small-molecule antiparasitics redirect R&D budgets toward species-specific biologics with tenfold pricing multiples and mandatory EMA environmental risk assessments reshape development economics.
For Market Incumbents: Compound manufacturing scale advantages in vaccine supply chains through backward integration into cell culture production, insulating against biologics talent scarcity at human pharmaceutical specialists. Prioritize captive supply of adjuvant formulations to defend margin position against Asian API cost volatility. Accelerate alignment with CSRD sustainability disclosure mandates to secure procurement tenders from consolidating livestock conglomerates. For New Entrants and Emerging Players: Anchor in Poland's underpenetrated Greater Poland and Silesia regions, where companion animal preventive care franchises expanding from German border provinces face limited incumbent presence. Target digital prescription platform partnerships with Kraków's emerging veterinary service networks to bypass traditional distribution markups. Emphasize chewable extended-release formulations matching parenteral pharmacokinetic profiles as the most penetrable product angle. For Investors and Strategic Acquirers: EU Green Deal pharmaceutical strategy implementation reshapes the acquisition landscape by privileging portfolios with biodegradable formulation platforms and closed-loop manufacturing capabilities. Position for five-to-ten year viability by targeting mid-tier antiparasitic specialists with Mediterranean livestock focus and reformulation-ready infrastructure. Monitor EMA guidance evolution on antimicrobial resistance containment measures as the critical inflection signal for portfolio rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Manufacturing Scale-Up | Captive cell culture capacity insulates Boehringer Ingelheim and Zoetis from talent scarcity at human pharmaceutical specialists. |
| Green Chemistry Platform Investment | Biodegradable formulation development satisfies REACH environmental fate studies and EU Green Deal discharge rules. |
| Digital Prescription Infrastructure Partnership | Telemedicine integration with automated refill systems opens direct-to-owner channels bypassing clinic markups. |
| Preventive Care Subscription Launch | Monthly membership programs concentrate purchasing decisions at Mars Veterinary Health and IVC Evidensia corporate procurement. |
| Regulatory Approval Pathway Optimization | Parallel track navigation of EMA centralized procedures and divergent national implementations compresses time-to-market. |
Research Approach
Desk research of EMA veterinary medicines authorization databases, REACH chemical safety filings, and EU Green Deal pharmaceutical strategy documentation preceded structured interviews with regulatory affairs leads at major manufacturers, procurement directors at integrated livestock conglomerates, formulary managers at corporate veterinary hospital chains, and distribution channel partners across Germany, France, and Poland. Secondary validation drew from European Chemicals Agency environmental fate studies, national pharmaceutical regulator residue monitoring protocols, and customs trade data on API imports. Bottom-up product-level demand modeling and top-down market sizing triangulated volume estimates.
Variance decomposition across product type, application, delivery mode, and end user dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory inflection timing. Modeled inputs included livestock density projections for Lower Saxony and Bavaria, companion animal ownership trends in Île-de-France, and F-Gas Regulation reformulation cost burdens on topical aerosol portfolios.
Decision-makers should treat outputs as directional under assumptions of sustained EMA authorization pathway stability and REACH enforcement continuity; material deviation would warrant model refresh. Forecasts embed assumptions regarding monoclonal antibody platform adoption curves and corporate procurement consolidation trajectories. Revision becomes warranted when antimicrobial resistance guidance stringency crosses thresholds eliminating metaphylactic product categories entirely.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Middle East and Africa Anti-Fungal Agents Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Live Attenuated Vaccines Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
Italy Opioids Market