
 Antibacterial Haemostatic Gels Market | 2026-2036
Antibacterial Haemostatic Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Antibacterial Haemostatic Gels Market Outlook
Software-defined dosing and remote monitoring integration in surgical workflows is restructuring how antibacterial haemostatic gels are procured and deployed. Pfizer Inc leverages its pharmaceutical distribution infrastructure to sustain hospital formulary access across North American markets. B. Braun SE anchors its competitive stance through specialized surgical site infection prevention portfolios. Medcura differentiates with chitosan-based platforms that occupy the emergency medicine channel.
Antibacterial haemostatic gels comprise biopolymer matrices—typically collagen, chitosan, or gelatin—impregnated with ionic silver or alternative antimicrobial agents, designed to achieve haemostasis within 2–5 minutes while suppressing bacterial colonization at wound sites. Collagen-based formulations dominate current surgical procedure volumes due to established clotting kinetics and broad compatibility with electrocautery. Silver-infused variants represent the fastest-growing product type as hospitals prioritize methicillin-resistant Staphylococcus aureus prevention in orthopedic and cardiovascular interventions.
FDA Class II device controls and the EU Medical Device Regulation (MDR) impose biocompatibility and antimicrobial efficacy validation requirements that filter market entrants and elevate R&D thresholds. ISO 10993 biological evaluation standards further govern material safety testing protocols for absorbable implantables. Stakeholders must monitor evolving EPA registrations for silver-based antimicrobials and anticipate how stricter European F-Gas Regulation analogues could affect sterilization processes in gel manufacturing.
Market Dynamics
FDA Class II device controls and EU MDR biocompatibility mandates are compressing product development timelines while elevating R&D thresholds for absorbable hemostat manufacturers.
Growth Catalysts
- Silver-ion antimicrobial platforms:Orthopedic and cardiovascular surgical units prioritize methicillin-resistant Staphylococcus aureus prevention protocols, accelerating ionic silver adoption over traditional antibiotic coatings.
- Trauma center infrastructure expansion:Emergency departments in the United States, Germany, and Japan are standardizing rapid bleeding control protocols that specify chitosan-based gel deployment.
- EU Medical Device Regulation harmonization:Centralized CE marking pathways for absorbable hemostats reduce national fragmentation and accelerate cross-border hospital formulary access.
Market Restraints
- Collagen raw material concentration:Bovine and porcine collagen supply chains concentrate in specific agricultural processing regions, exposing manufacturers to zoonotic disease-related import restrictions.
- Sterilization energy costs:European F-Gas Regulation analogues tighten industrial gas availability for ethylene oxide sterilization, elevating per-unit processing expenses.
- Electrocautery compatibility limitations:Gelatin-based formulations face thermal stability constraints that restrict use in high-frequency electrosurgical procedures.
Strategic Opportunities
- Remote surgical monitoring integration:Software-defined dosing systems that link haemostatic gel application to real-time coagulation feedback create premium positioning in academic medical centers.
- India surgical infrastructure buildout:Government hospital procurement schemes under the country's national health mission create volume pathways for cost-optimized chitosan formulations.
- EPA silver registration streamlining:Anticipated antimicrobial pesticide review efficiencies could accelerate ionic silver variant time-to-market for emergency medicine channels.
Industry Challenges
- ISO 10993 biological evaluation timelines:Extended cytotoxicity and sensitization testing protocols delay absorbable implantable gel launches by 18-24 months.
- Biopolymer formulation expertise scarcity:Cross-functional talent combining chitosan chemistry with hemostatic kinetics remains concentrated in specialized academic and contract research organizations.
- Legacy sterilization asset reconfiguration:Ethylene oxide facility upgrades to meet EPA National Emission Standards for Hazardous Air Pollutants require capital deployment that mid-scale manufacturers struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibacterial Haemostatic Gels Market |
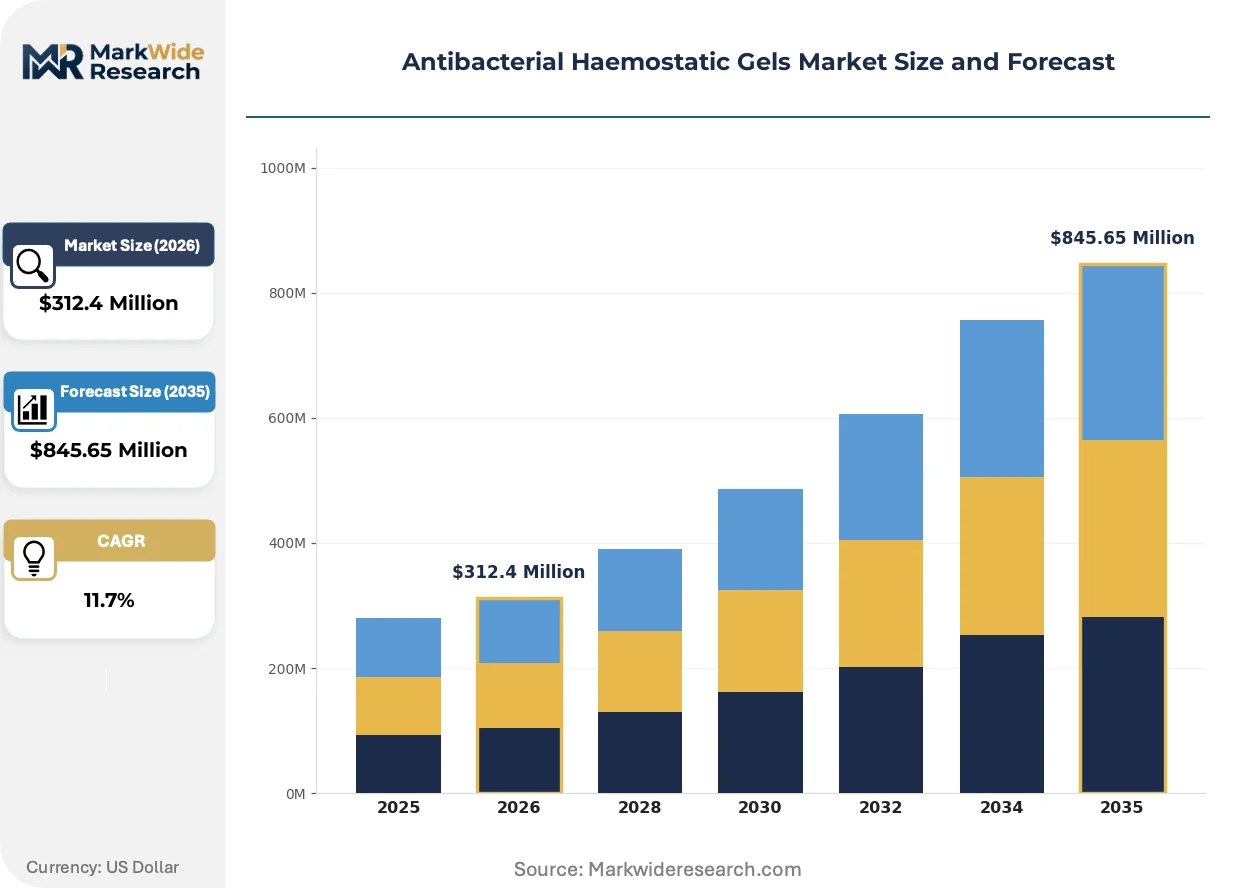
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen-Based, Silver-Infused, Chitosan-Based, Gelatin-Based Application: Surgical Procedures, Wound Care, Emergency Medicine, Traumatic Injuries End User: Hospitals, Clinics, Emergency Services, Military Facilities Technology: Spray Technology, Gel Technology, Hydrogel Technology, Liquid Technology |
| Companies Covered | DEXX Laboratories Inc, Medcura, Pfizer Inc, StopBleed, Zoetis Inc, Rapid-Seal, Coloplast Group, PREVESTDenPro, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibacterial Haemostatic Gels Market Strategic Shifts
Digital integration in surgical workflows is restructuring how antibacterial haemostatic gels are specified, procured, and deployed across acute care settings.
Chitosan-nanofiber composite matrices are integrating with electrosurgical platforms to deliver simultaneous mechanical hemostasis and antimicrobial protection. Cardiovascular surgery departments in tertiary hospitals are piloting these platforms for sternotomy closure procedures. The technology is integrating real-time impedance sensing that adjusts gel viscosity based on tissue perfusion metrics, compressing operative time and reducing transfusion requirements.
EU F-Gas Regulation constraints on hydrofluorocarbon propellants are forcing sterilization process redesigns for pre-filled gel applicators. Manufacturers serving European markets must validate alternative low-global-warming-potential sterilization modalities or reformulate packaging systems. Absorbable hemostat product lines with ethylene oxide dependencies face the steepest compliance timelines, with several suppliers accelerating gamma irradiation validation studies.
Hospital value analysis committees are consolidating vendor contracts around bundled surgical site infection prevention portfolios. Emergency medicine procurement in the United States is shifting from unit-based purchasing to procedure-kit integration, where haemostatic gels compete for inclusion in trauma tray configurations. This consolidation is most visible in Level I trauma centers, where standardization mandates reduce formulary slots for standalone gel products.
Antibacterial Haemostatic Gels Market Segmentation
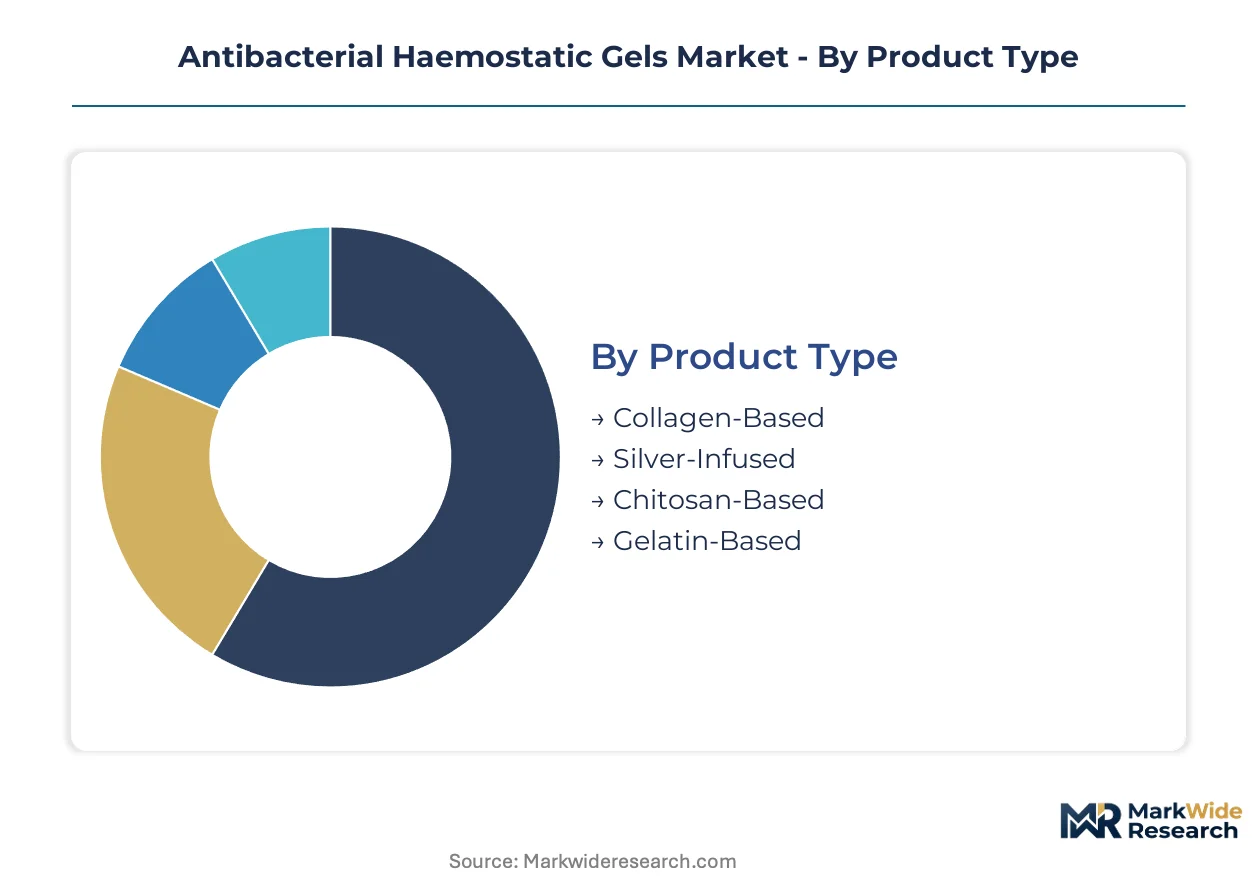
Antibacterial haemostatic gel procurement patterns diverge sharply across clinical settings, with formulation chemistry and delivery mechanism determining hospital formulary placement. Manufacturers must align product portfolios to distinct regulatory pathways and sterilization requirements that vary by application intensity.
Product Type:
Supply concentration in bovine and porcine collagen processing regions shapes raw material security for dominant formulation categories.
- Collagen-Based:Bovine and porcine-derived matrices deliver established clotting kinetics compatible with electrocautery protocols. United States surgical centers prioritize these formulations for orthopedic and cardiovascular procedures where thermal stability proves critical.
- Silver-Infused:Ionic silver-impregnated platforms achieve haemostasis within 2–5 minutes while suppressing methicillin-resistant Staphylococcus aureus colonization. German hospitals lead adoption in joint replacement protocols where infection prevention drives reimbursement outcomes.
- Chitosan-Based:Marine-derived polysaccharide matrices function independently of clotting cascade status. Japan's emergency medicine channels favor these for trauma applications involving anticoagulated patients.
- Gelatin-Based:Reconstituted collagen derivatives offer lower cost positioning but face thermal constraints limiting electrosurgical compatibility.
Today's leader: Collagen-Based. Tomorrow's challenger: Silver-Infused.
Application:
Procedure reimbursement intensity and infection risk profiles create tiered demand concentration across clinical use cases.
- Surgical Procedures:Operating room deployment demands ISO 10993-validated biocompatibility for implantable absorbables. United States tertiary hospitals drive volume through bundled payment models that incentivize reduced transfusion rates.
- Emergency Medicine:Pre-hospital and emergency department protocols specify rapid deployment without refrigeration. Trauma centers in Japan standardize chitosan gel inclusion in hemorrhage control algorithms.
- Wound Care:Outpatient and post-acute settings favor lower-cost gelatin variants for superficial bleeding management.
- Traumatic Injuries:Military and civilian mass casualty protocols require shelf-stable formats with extended temperature tolerance.
Surgical Procedures command current procurement volume. Emergency Medicine presents the steepest expansion trajectory as pre-hospital protocols mature.
End User:
Capital intensity and formulary governance sophistication separate institutional purchasing behaviors across care settings.
- Hospitals:Value analysis committees consolidate contracts around bundled surgical site infection prevention portfolios. Level I trauma centers in the United States reduce standalone gel slots through procedure-kit standardization.
- Emergency Services:Ambulance and air medical operators prioritize unit-dose packaging with extended shelf stability. Germany's pre-hospital networks specify chitosan platforms for rapid bleeding control in transit.
- Clinics:Outpatient surgical centers favor lower-cost collagen variants for minor procedures with limited infection risk.
- Military Facilities:Combat casualty care protocols demand temperature-stable formats validated for austere environments.
Hospitals anchor procurement volume. Emergency Services are climbing the fastest as pre-hospital hemorrhage control gains protocol priority.
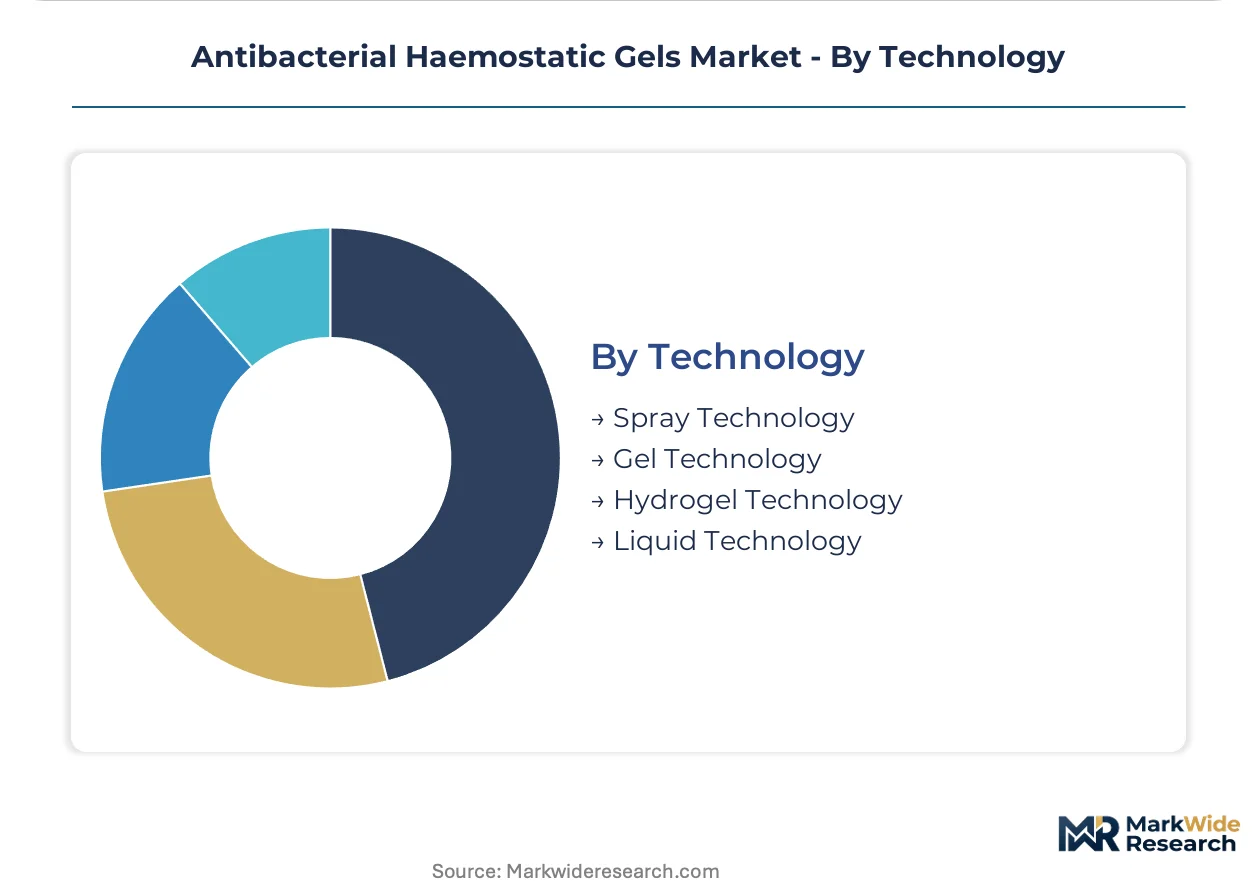
Technology:
Delivery mechanism precision and tissue adhesion properties determine clinical adoption across procedure types.
- Gel Technology:Viscous matrices provide mechanical hemostasis through direct pressure application. Cardiovascular surgery departments in Japan pilot impedance-sensing variants that adjust viscosity to tissue perfusion metrics.
- Hydrogel Technology:Water-swollen polymer networks maintain moist wound environments while releasing antimicrobial agents. German burn centers favor these for partial-thickness wound management.
- Spray Technology:Aerosolized delivery enables coverage of irregular wound geometries in laparoscopic and open procedures.
- Liquid Technology:Low-viscosity formulations penetrate deep wound tracks but require longer set times limiting adoption in high-bleeding scenarios.
Gel Technology holds current preference. Hydrogel Technology is gaining share fastest through wound care channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's trauma centers standardize chitosan gel protocols faster than United States equivalents, while Japan's cardiovascular surgical infrastructure drives premium collagen formulation demand.
United States
FDA Class II device controls shape absorbable hemostat development pathways for domestic manufacturers. Level I trauma centers in Texas and California consolidate vendor contracts around bundled surgical site infection prevention portfolios. Boston's academic medical centers pilot impedance-sensing gel technologies that adjust viscosity to tissue perfusion metrics.
Germany
Joint replacement units prioritize ionic silver-infused platforms for methicillin-resistant Staphylococcus aureus prevention. EU Medical Device Regulation harmonization accelerates cross-border hospital formulary access for CE-marked absorbables. The Baden-Württemberg surgical device cluster anchors chitosan chemistry expertise for emergency medicine applications.
Japan
PMDA biocompatibility validation requirements filter market entrants and elevate R&D thresholds for absorbable implantables. Tokyo and Osaka tertiary hospitals drive volume through bundled payment models incentivizing reduced transfusion rates. The Kansai region concentrates gelatin formulation manufacturing serving domestic cardiovascular procedure demand.
India
Government hospital procurement schemes under the national health mission create volume pathways for cost-optimized chitosan formulations. CDSCO medical device registration timelines compress as the regulator streamlines Class B and C absorbable reviews. Maharashtra's pharmaceutical manufacturing belt attracts contract research organizations specializing in biopolymer hemostatic kinetics.
United Kingdom
NHS value analysis committees reduce standalone gel formulary slots through procedure-kit standardization mandates. MHRA post-Brexit regulatory alignment with EU MDR biocompatibility standards maintains CE marking recognition for cross-border suppliers. London's trauma networks specify shelf-stable chitosan platforms for pre-hospital hemorrhage control algorithms.
Antibacterial Haemostatic Gels Market Competitive Environment
Top-tier vendors anchor hospital formulary access through pharmaceutical distribution infrastructure, while mid-scale specialists occupy emergency medicine and trauma channels. The competitive structure stratifies across diversified healthcare conglomerates, dedicated surgical device manufacturers, and biopolymer chemistry specialists. Three archetypes dominate: pharmaceutical distributors leveraging existing hospital relationships, surgical site infection prevention portfolio builders, and chitosan platform innovators. Capacity expansion in sterilization-compliant manufacturing and strategic partnerships for remote monitoring integration represent the dominant competitive moves.
Within the pharmaceutical-distributor archetype, Pfizer Inc and Zoetis Inc occupy positions that exemplify formulary anchoring through existing healthcare infrastructure relationships. Medcura and StopBleed represent the biopolymer-specialist tier, with Medcura exemplifying chitosan-based platform differentiation. B. Braun SE anchors the surgical-device-manufacturer archetype through specialized infection prevention portfolio construction. DEXX Laboratories Inc sits within the diversified healthcare conglomerate category alongside Coloplast Group, which represents European absorbable device manufacturing concentration.
| Leading Market Players |
|---|
| DEXX Laboratories Inc |
| Medcura |
| Pfizer Inc |
| StopBleed |
| Zoetis Inc |
| Rapid-Seal |
| Coloplast Group |
| PREVESTDenPro |
| B. Braun SE |
| Others |
Value Chain & Pricing Dynamics
Captive sterilization capacity in the United States and Germany anchors supply security for absorbable hemostat manufacturers while creating pricing power asymmetries between integrated majors and contract-dependent specialists. Vertical control over ethylene oxide and gamma irradiation assets insulates Pfizer Inc and B. Braun SE from European F-Gas Regulation-driven cost spikes that compress margins for mid-scale competitors sourcing sterilization services.
Pricing Analysis
Capacity additions in India's Maharashtra pharmaceutical belt are reshaping price floors for cost-optimized chitosan formulations serving government procurement schemes. Three-tier pricing structure across premium collagen-silver platforms, standard gelatin matrices, and economy chitosan variants separates ISO 10993-validated implantables from emergency-use products. Pricing pressure stems from NHS value analysis committee consolidation around bundled surgical site infection prevention portfolios. Emergency Services buyers exhibit highest price sensitivity due to budget-constrained ambulance operator procurement, while United States Level I trauma centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Biopolymer chemistry expertise scarcity in Germany's Baden-Württemberg cluster and Japan's Kansai region constrains formulation scale-up for absorbable hemostat innovators. Bovine collagen processing concentrates in United States Midwest agricultural regions, porcine derivatives in Danish and Dutch facilities, and chitosan extraction in Southeast Asian seafood processing hubs. Single-source vulnerability runs through ionic silver active pharmaceutical ingredient suppliers facing EPA registration renewal timelines. Distribution runs through pharmaceutical wholesalers serving hospital GPO contracts in North America and direct-to-hospital device specialists in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's CDSCO-fast-tracked Class C absorbable reviews and the EU MDR's extended CE marking timelines rewards manufacturers with dual-registered manufacturing footprints. Cost-optimized chitosan production in Maharashtra combined with premium collagen formulation in Baden-Württemberg captures margin spread across emerging and developed market price points.
For Market Incumbents: Anticipate chitosan-nanofiber composite platforms displacing traditional collagen dominance in cardiovascular surgery by accelerating impedance-sensing gel R&D partnerships with Tokyo academic medical centers. Defend hospital formulary slots through backward integration into bovine collagen rendering facilities, insulating against zoonotic disease-related import restrictions. Prioritize sterilization asset upgrades to meet EPA National Emission Standards for Hazardous Air Pollutants ahead of mid-scale competitor compliance failures. For New Entrants and Emerging Players: Ambulance and air medical operators in Germany's pre-hospital networks represent the most penetrable buyer archetype, with chitosan platform standardization creating first-mover advantage in procedure-kit integrations. Target India's national health mission government hospital procurement schemes with cost-optimized formulations validated for tropical storage conditions. Deploy direct clinical educator teams to bypass entrenched pharmaceutical distributor relationships blocking formulary access. For Investors and Strategic Acquirers: Roll-up economics work for specialized biopolymer chemistry contract research organizations because ISO 10993 biological evaluation expertise scarcity concentrates in academic and CRO settings, creating scarcity premium for acquisition targets. Five-to-ten year viability hinges on EPA silver registration streamlining efficiency and EU F-Gas Regulation sterilization process redesign completion rates. Monitor CDSCO medical device registration timeline compression as inflection signal for Indian manufacturing footprint value appreciation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR harmonization accelerates cross-border hospital formulary access for absorbable hemostats. |
| Hospital System Partnership | Bundled surgical site infection prevention portfolios consolidate vendor contracts around integrated suppliers. |
| Software Companion Development | Impedance-sensing gel technologies adjust viscosity to tissue perfusion metrics in Japanese cardiovascular departments. |
| Backward Integration | Captive collagen rendering insulates manufacturers from zoonotic disease-related supply disruptions. |
| Reimbursement Strategy | German joint replacement units prioritize ionic silver platforms for MRSA prevention reimbursement outcomes. |
Study Parameters
Multiple input streams — surgical device procurement databases, FDA 510(k) filings, and hospital GPO contract records — were reconciled with primary interviews across the analysis window. Conversations with hospital purchasing committee chairs, biomedical engineers specializing in absorbable implantables, GPO contracts managers, and emergency medicine procurement officers informed demand-side validation. Secondary sources included EU MDR notified body guidance documents, EPA antimicrobial pesticide registration databases, ISO 10993 biological evaluation standards, and customs trade data for collagen and chitosan raw material flows. Bottom-up procedure volume modeling and top-down healthcare expenditure allocation triangulated market sizing.
Segment-level outputs were constructed across product type, application intensity, end-user capital tier, and delivery mechanism technology dimensions. CAGRs derived from procedure volume elasticity to surgical infrastructure expansion, infection prevention protocol adoption curves, and reimbursement pathway maturation traversed the projection horizon. Industry-specific forecast inputs incorporated trauma center infrastructure buildout timelines in target geographies and EPA silver registration review efficiency assumptions.
Underlying measurement precision varies by segment; Surgical Procedures and Emergency Medicine carry tighter precision than Military Facilities due to procurement data availability. Forecasts reflect documented assumptions regarding regulatory pathway timelines and sterilization technology transition rates. Material deviation in EPA National Emission Standards enforcement intensity or EU F-Gas Regulation hydrofluorocarbon propellant restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Swab Cups Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Serological Pipettes Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Amniotic Products Market