
 Marine Derived Pharmaceuticals Market | 2026-2036
Marine Derived Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Derived Pharmaceuticals Market Analysis
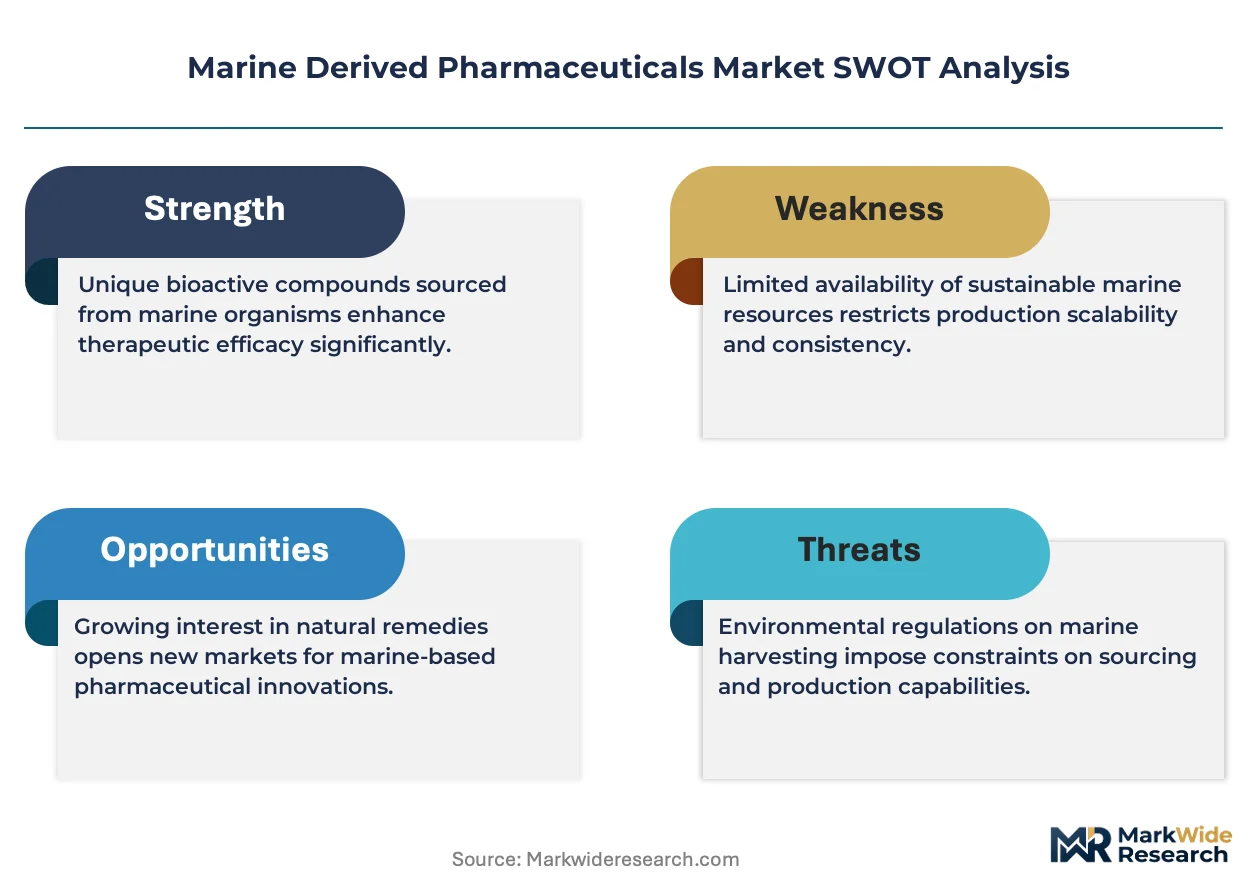
A widening capital-intensity gap between fully integrated marine drug developers and asset-light biotech licensors is bifurcating competitive returns in this sector. PharmaMar S.A. leverages end-to-end control from deep-sea specimen collection through GMP manufacturing to capture margin at every value chain node. Takeda Pharmaceutical Company Limited anchors its position through sustained R&D partnerships with Japanese oceanographic institutes, securing preferential access to novel extremophile-derived compounds. Marinomed Biotech AG specializes in antiviral glycoprotein platforms extracted from marine algae, occupying a defensible niche against broader oncology-focused competitors.
Marine derived pharmaceuticals comprise bioactive compounds, peptides, and secondary metabolites extracted from marine organisms including sponges, mollusks, tunicates, and microorganisms, typically requiring cold-chain extraction and specialized chromatographic purification to preserve structural integrity. These agents function primarily as cytotoxic, anti-inflammatory, or immunomodulatory therapeutics in precision medicine applications where terrestrial synthetic chemistry has failed to produce viable alternatives. Anticancer agents lead product type revenue pools due to the clinical success of trabectedin and eribulin mesylate, while antiviral agents represent the fastest-expanding category as marine polysaccharides demonstrate broad-spectrum efficacy against enveloped viruses. Injectable delivery dominates current commercialization, though oral formulation R&D is intensifying as pharmaceutical companies seek to expand addressable patient populations beyond hospital-based infusion centers.
FDA orphan drug designation and EMA's PRIME eligibility pathway jointly shape clinical development economics by compressing regulatory review timelines and extending market exclusivity for marine-derived novel entities. ISO 17025 accreditation for marine specimen biobanking and WHO prequalification standards for biological API sourcing increasingly determine which suppliers gain access to multinational pharmaceutical procurement networks. Stakeholders must monitor how biodiversity access and benefit-sharing frameworks under the Nagoya Protocol evolve, as these agreements directly constrain collection rights in key marine ecosystems and will dictate sustainable pipeline viability for decades ahead.
Market Dynamics
Deep-sea specimen collection is consolidating under vertically integrated biotech operators as biodiversity access agreements under the Nagoya Protocol restrict third-party harvesting rights in Pacific and Atlantic economic zones.
Growth Catalysts
- FDA Orphan Drug Designation:The expanded framework accelerates clinical translation timelines for marine-derived cytotoxic compounds by compressing regulatory review periods and extending market exclusivity periods for novel natural product therapies.
- Oncology Formulary Inclusion:Major hospital systems are integrating marine-derived therapeutics into standard-of-care protocols as trabectedin and eribulin mesylate demonstrate efficacy in refractory solid tumors.
- California and Massachusetts Clusters:Specialized marine biotechnology infrastructure in these coastal states anchors both discovery and commercialization capabilities, concentrating venture capital and GMP manufacturing capacity.
Market Restraints
- Cold-Chain Extraction Costs:Preservation of bioactive peptide structural integrity requires specialized chromatographic purification and continuous refrigeration, elevating unit economics above terrestrial synthetic alternatives.
- Pacific Biodiversity Access Concentration:Nagoya Protocol benefit-sharing agreements constrain collection rights to a limited set of contracted marine zones, creating supply vulnerability for novel extremophile-derived compounds.
- Injectable Delivery Dominance:Hospital-based infusion requirements limit addressable patient populations and create reimbursement friction against oral oncology competitors in outpatient settings.
Strategic Opportunities
- Oral Formulation R&D:Pharmaceutical developers are intensifying investment in bioavailability enhancement technologies to expand marine-derived therapeutics beyond infusion centers into community oncology practices.
- EMA PRIME Eligibility:The European Medicines Agency's priority medicines pathway offers accelerated assessment for marine-derived novel entities, creating regulatory arbitrage for sponsors willing to anchor European development strategies.
- Antiviral Glycoprotein Platforms:Marine polysaccharides demonstrating broad-spectrum efficacy against enveloped viruses represent white-space expansion beyond saturated oncology indications.
Industry Challenges
- ISO 17025 Biobanking Certification:Marine specimen repositories face extended accreditation timelines that delay multinational pharmaceutical procurement network access and compress development runway visibility.
- Deep-Sea Collection Talent Scarcity:The intersection of marine biology, extreme-environment diving operations, and pharmaceutical compliance requirements creates persistent recruitment bottlenecks for field collection teams.
- API Sourcing Prequalification:WHO standards for biological active pharmaceutical ingredient traceability impose documentation burdens that smaller marine biotechnology suppliers struggle to satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Derived Pharmaceuticals Market |
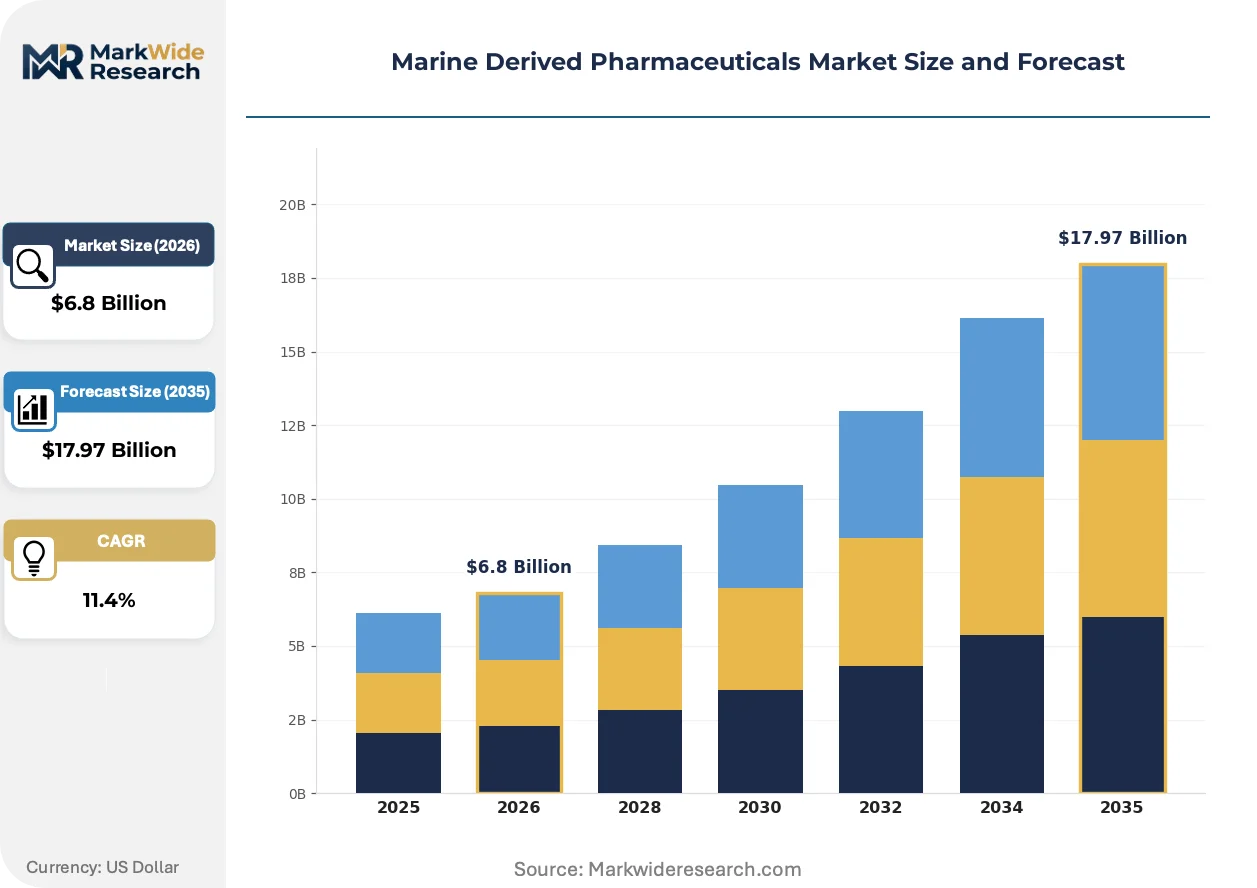
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Anticancer Agents, Antiviral Agents, Nutraceuticals Application: Oncology, Infectious Diseases, Cardiovascular Diseases, Neurological Disorders End User: Pharmaceutical Companies, Research Institutions, Academic Laboratories, Contract Research Organizations Delivery Mode: Oral, Injectable, Topical, Transdermal |
| Companies Covered | PharmaMar S.A., Eisai Co. Ltd., Takeda Pharmaceutical Company Limited, Pfizer Inc., Merck & Co. Inc., F. Hoffmann-La Roche AG, AbbVie Inc., Bristol-Myers Squibb Company, Marinomed Biotech AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Derived Pharmaceuticals Market Emerging Trajectories
Continuous processing technologies are displacing batch chromatography in marine compound purification, while regulatory sandboxes for natural product therapies reshape clinical development economics.
Microfluidic extraction platforms are miniaturizing the scale of marine specimen processing required for bioactive compound isolation. Contract development and manufacturing organizations serving mid-cap marine biotechs are adopting these systems to reduce solvent volumes and preserve rare deep-sea biomass. The technology is miniaturizing capital requirements for preclinical-stage developers, enabling asset-light licensors to retain pipeline control without captive GMP infrastructure.
EMA's PRIME eligibility pathway is compressing regulatory review timelines for marine-derived orphan indications by offering accelerated assessment and enhanced scientific dialogue. Sponsors gain conditional marketing authorization pathways that reduce time-to-revenue for novel cytotoxic agents. Oncology-focused developers with European anchoring strategies are restructuring clinical trial designs to maximize PRIME qualification probability.
Hospital procurement is consolidating marine-derived oncology agents under centralized pharmacy and therapeutics committees. Formulary inclusion decisions increasingly hinge on total cost-of-infusion modeling rather than drug acquisition price alone. This behavioral shift is most visible in United States academic medical centers, where pharmacy directors negotiate bundled reimbursement contracts covering drug, administration, and adverse event management.
Marine Derived Pharmaceuticals Market Segmentation
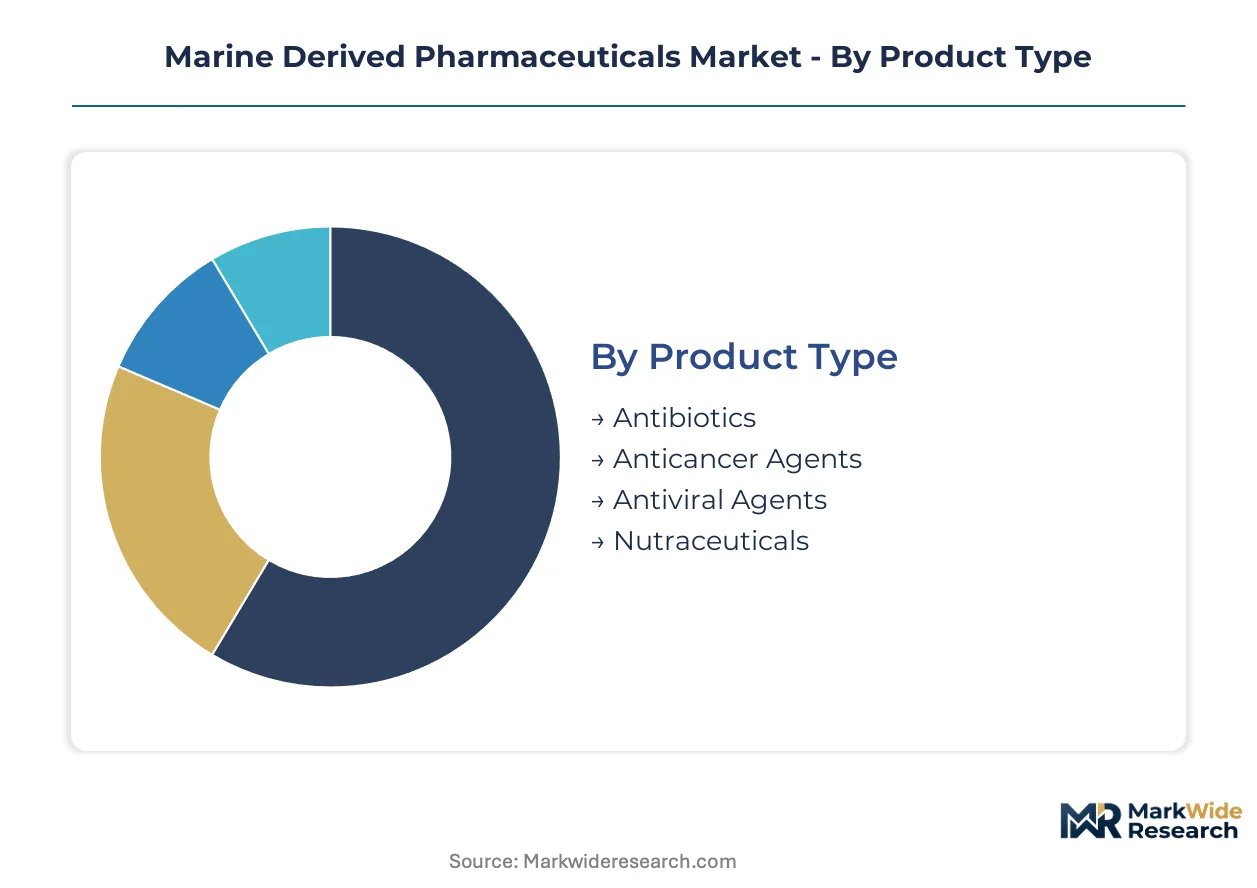
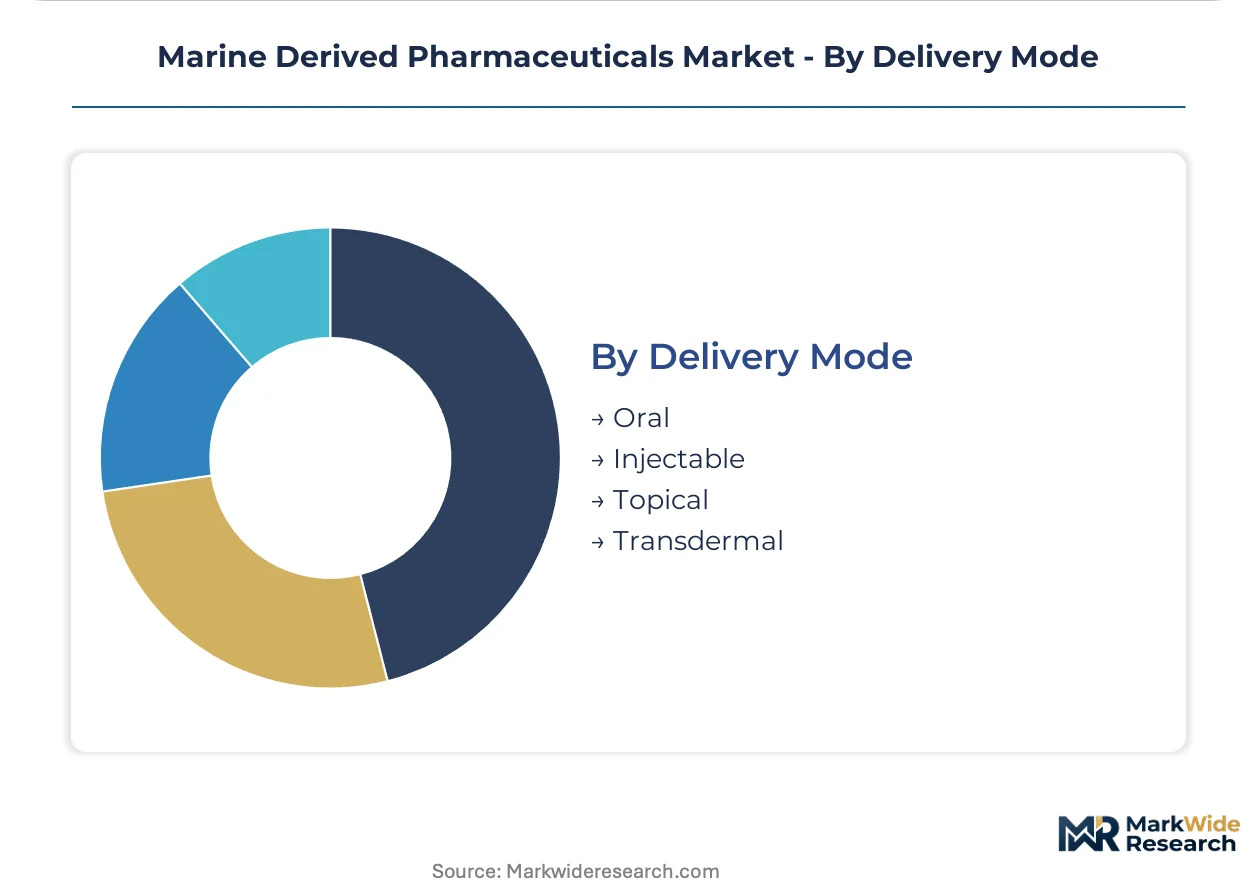
Marine derived pharmaceuticals exhibit pronounced segmentation asymmetries where therapeutic category and delivery mode jointly determine addressable patient populations and reimbursement economics. Substitute pressure from terrestrial synthetic alternatives varies sharply across product types, reshaping R&D allocation and partnership strategies among developers.
Product Type:
Anticancer agents face the most intense substitution pressure from antibody-drug conjugates and immuno-oncology biologics, forcing marine developers to demonstrate superior efficacy in refractory indications.
- Anticancer Agents:Cytotoxic compounds including trabectedin and eribulin mesylate target microtubule dynamics and DNA minor groove binding. Hospital oncology departments in the United States concentrate demand as these agents secure formulary inclusion for sarcoma and breast cancer protocols where synthetic alternatives have failed.
- Antiviral Agents:Marine polysaccharides and glycoproteins demonstrate broad-spectrum efficacy against enveloped viruses through membrane fusion inhibition. Research institutions in California and Massachusetts anchor early-stage demand as pandemic preparedness programs fund platform expansion beyond oncology saturation.
- Antibiotics:Bioactive peptides from extremophile bacteria address gram-resistant pathogens through novel cell wall disruption mechanisms.
- Nutraceuticals:Omega-3 fatty acids and carotenoid extracts serve preventive health applications with lower regulatory barriers but compressed margin structures.
Anticancer agents anchor the volume base while antiviral agents gain share at the steepest rate.
Application:
Cost tier stratification separates curative oncology indications from chronic disease management, with reimbursement premiums concentrating in acute care settings.
- Oncology:Precision targeting of refractory solid tumors and hematological malignancies drives the highest value per patient. Major hospital systems in the United States integrate marine-derived cytotoxics into standard-of-care protocols, with FDA orphan drug designation accelerating clinical translation timelines.
- Infectious Diseases:Antiviral glycoprotein platforms address emerging viral threats and drug-resistant bacterial infections. EMA PRIME eligibility in Europe compresses regulatory review for novel marine-derived anti-infectives, creating development arbitrage for sponsors anchoring European strategies.
- Cardiovascular Diseases:Anti-inflammatory marine peptides target atherosclerotic plaque stabilization with longer development horizons.
- Neurological Disorders:Neuroprotective compounds from deep-sea sponges address neurodegeneration through immunomodulatory mechanisms.
Oncology commands the premium pricing tier while infectious disease applications expand most quickly into government stockpiling contracts.
End User:
Customer type determines specification intensity, with pharmaceutical companies demanding full GMP traceability while academic laboratories prioritize discovery access over commercial scalability.
- Pharmaceutical Companies:Integrated developers and large-cap licensors seek captive pipeline control from specimen collection through commercialization. ISO 17025 biobanking certification and WHO API prequalification standards filter supplier access to multinational procurement networks.
- Contract Research Organizations:Mid-cap biotechs outsource manufacturing and toxicology to preserve capital for clinical development. Massachusetts and California clusters concentrate specialized CDMO capacity for marine compound purification using continuous processing technologies.
- Research Institutions:Oceanographic institutes and marine biology centers secure preferential biodiversity access under Nagoya Protocol frameworks.
- Academic Laboratories:University-based discovery programs generate preclinical data for subsequent licensing transactions.
Pharmaceutical companies dominate procurement value while contract research organizations expand most rapidly as asset-light strategies proliferate.
Delivery Mode:
Supply concentration in injectable formats reflects cold-chain infrastructure requirements, while oral formulation R&D intensifies to capture community oncology volume.
- Injectable:Intravenous infusion preserves structural integrity of complex peptides and secondary metabolites susceptible to gastric degradation. Hospital-based administration in the United States creates reimbursement bundling opportunities but limits addressable populations to infusion center capacity.
- Oral:Bioavailability enhancement technologies including lipid nanoparticle encapsulation and prodrug modification expand patient access. California biotechnology clusters anchor formulation R&D investment targeting outpatient oncology substitution.
- Topical:Dermal delivery serves localized anti-inflammatory and wound healing applications with lower regulatory complexity.
- Transdermal:Patch-based administration addresses chronic dosing requirements for cardiovascular and neurological indications.
Injectable formats anchor current revenue while oral delivery gains share at the steepest rate as developers target community practice expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets compress margins through reference pricing mechanisms. Japanese buyers command premium access to novel extremophile compounds through exclusive oceanographic partnerships. Emerging collection zones in Australia and South Korea are reshaping biodiversity access economics.
United States
Hospital oncology departments at academic medical centers in Boston and San Francisco drive formulary adoption of marine-derived cytotoxics. FDA orphan drug designation compresses regulatory timelines for natural product therapies. California's Monterey Bay marine biotechnology cluster anchors both deep-sea specimen collection and GMP manufacturing infrastructure.
Germany
EMA PRIME eligibility accelerates assessment timelines for sponsors anchoring European development strategies. The country's reference pricing system for oncology therapeutics compresses reimbursement premiums against US benchmarks. Heidelberg and Munich host specialized CDMO capacity for continuous processing chromatography of marine peptides.
Japan
PMDA's Sakigake designation system offers priority review for first-in-class marine-derived compounds addressing unmet oncology needs. Takeda Pharmaceutical Company Limited leverages sustained R&D partnerships with Japanese oceanographic institutes. Tokyo and Osaka anchor pharmaceutical procurement networks with preferential access to novel extremophile-derived agents.
Australia
TGA's provisional approval pathway enables early access schemes for marine-derived therapeutics in refractory cancer indications. The country's extensive exclusive economic zone in the Pacific Ocean secures biodiversity access under Nagoya Protocol frameworks. Brisbane and Perth marine research stations concentrate specimen biobanking capacity with ISO 17025 accreditation.
South Korea
MFDS fast-track designation for innovative biologics shortens development timelines for marine peptide platforms. Government-funded pandemic preparedness programs stockpile antiviral glycoproteins derived from marine algae. Busan and Incheon harbor specialized cold-chain logistics infrastructure for biological API import and distribution.
Marine Derived Pharmaceuticals Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with fully integrated developers commanding margin capture at every value chain node while asset-light licensors optimize capital efficiency. The market structure bifurcates between vertically integrated operators controlling specimen collection through commercialization and specialized platform companies licensing discovery capabilities. Strategic archetypes include end-to-end marine biotechnology developers, regional oceanographic partnership specialists, and antiviral glycoprotein platform innovators. Dominant competitive moves center on biodiversity access agreement consolidation and continuous processing technology licensing for purification cost reduction.
Within the vertically integrated tier, PharmaMar S.A. exemplifies end-to-end control from deep-sea collection through GMP manufacturing, while Takeda Pharmaceutical Company Limited anchors its position through sustained Japanese oceanographic institute partnerships. Marinomed Biotech AG occupies a defensible specialization in antiviral glycoprotein platforms extracted from marine algae, representing the asset-light platform archetype against broader oncology-focused competitors.
| Leading Market Players |
|---|
| PharmaMar S.A. |
| Eisai Co. Ltd. |
| Takeda Pharmaceutical Company Limited |
| Pfizer Inc. |
| Merck & Co. Inc. |
| F. Hoffmann-La Roche AG |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Marinomed Biotech AG |
| Others |
Supply Flow & Price Mechanics
ISO 17025 accreditation gates both supplier qualification to multinational procurement networks and the price premiums commanded by certified marine specimen repositories, compressing margin structures for uncertified operators while enabling certified biobanks to sustain configured-to-order pricing for GMP-grade biological APIs.
Pricing Analysis
Configured-to-order pricing for ISO 17025-certified marine specimen collections commands substantial premiums over standard uncertified biomass sourcing, with price differentiation driven by GMP-grade certification tier and cold-chain integrity assurance. Three-tier pricing structure across premium, standard, and economy levels separates fully traceable deep-sea extremophile extracts from bulk-harvested coastal specimens. Cost compression in standard-tier sourcing is intensifying because Pacific biodiversity access agreements under the Nagoya Protocol constrain supply volumes. Academic laboratories exhibit highest price sensitivity, while integrated pharmaceutical developers absorb premium tier costs to secure pipeline control.
Supply Chain Analysis
Strategic stockpiling of rare deep-sea biomass dominates over just-in-time preferences, as Nagoya Protocol collection windows and extremophile habitat seasonality force advance procurement commitments. Supply concentrates in the United States, Japan, and Australia, with raw material dependencies on specialized diving vessels, chromatographic purification resins, and cryogenic preservation infrastructure. Single-source vulnerability runs through Pacific deep-sea collection zones where exclusive economic zone agreements limit third-party access. Distribution runs through hospital-based infusion centers and specialized pharmaceutical CDMOs with captive GMP manufacturing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine derived pharmaceuticals are recovering from a cyclical trough as FDA orphan drug designation expansion and EMA PRIME eligibility jointly compress clinical translation timelines, accelerating capital redeployment into discovery-stage assets.
For Market Incumbents: Fortify biodiversity access positions by securing Nagoya Protocol benefit-sharing agreements in under-contracted Pacific zones before collection rights consolidate further. Incumbent developers must deepen captive GMP manufacturing capacity to defend margin structures against asset-light licensors exploiting continuous processing technology licensing. The priority defensive lever is backward integration into deep-sea specimen collection operations, neutralizing supply vulnerability to third-party harvesting restrictions.
For New Entrants and Emerging Players: Antiviral glycoprotein platform development represents the most penetrable white-space where oncology-focused incumbents under-serve pandemic preparedness demand. New entrants should target government stockpiling contracts in South Korea and Australia, where MFDS and TGA fast-track pathways compress regulatory timelines for novel marine-derived anti-infectives. The optimal go-to-market angle is asset-light platform licensing to established CDMOs, preserving capital for clinical data generation rather than captive infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across preclinical-stage marine biotechnology as microfluidic extraction platforms miniaturize processing requirements. Long-term viability over the next decade hinges on sustainable biodiversity access rather than compound novelty alone, favoring acquisition targets with secured Nagoya Protocol collection rights in Pacific and Atlantic economic zones. The critical inflection signal to watch is ISO 17025 accreditation completion timelines, which gate pharmaceutical procurement network access and compress development runway visibility for uncertified repositories.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodiversity Access Agreement Consolidation | Secures preferential collection rights under Nagoya Protocol frameworks in Pacific economic zones. |
| Continuous Processing Technology Licensing | Reduces chromatographic purification costs for mid-cap developers without captive GMP infrastructure. |
| EMA PRIME Eligibility Pathway Pursuit | Compresses regulatory review timelines for European-anchored oncology and antiviral development programs. |
| Oral Formulation R&D Investment | Expands addressable patient populations beyond hospital infusion centers into community oncology practices. |
| ISO 17025 Biobanking Certification | Enables access to multinational pharmaceutical procurement networks and sustains configured-to-order pricing premiums. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and marine biotechnology CDMO operations managers. Secondary validation drew from FDA orphan drug designation filings, EMA PRIME eligibility submissions, ClinicalTrials.gov protocol registrations, and WHO prequalification standards for biological API sourcing. Bottom-up patient population modeling and top-down therapeutic category sizing were triangulated to anchor volume and value estimates.
Across the analysis window, forecasts reflect segmented modeling by therapeutic category, delivery mode, end-user archetype, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to historical approval trajectories for marine-derived cytotoxic and antiviral agents, with inputs including biodiversity access agreement expansion rates and continuous processing technology adoption curves in contract manufacturing.
Underlying assumptions cover sustained FDA and EMA regulatory pathway stability for natural product therapies, with deviation risk concentrated in Nagoya Protocol renegotiation outcomes and Pacific economic zone access restrictions. Revision becomes warranted when biodiversity benefit-sharing framework modifications cross thresholds that materially alter collection rights economics or compress sustainable pipeline viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Zoledronic Acid Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Soft Capsules Drugs Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Carbapenem Antibiotics Market