
 Crawler Excavator Market | 2026-2036
Crawler Excavator Market Size, Share, and Industry Trends Forecast 2026-2036
Crawler Excavator Market Intelligence
The integration of factory-fitted telematics and GPS-guided control systems is redrawing the competitive landscape for crawler excavators. This technology enables remote fleet management, predictive maintenance, and improved operational efficiency on job sites. Caterpillar leverages its extensive global dealer network and technology portfolio to maintain a dominant market position. Komatsu differentiates through its focus on intelligent machine control and autonomous operation research, while Volvo Construction Equipment competes on fuel efficiency and advanced operator safety systems.
A crawler excavator is a heavy-duty earthmoving machine built on a tracked undercarriage for superior stability on uneven or soft terrain. These machines utilize a boom, dipper, and bucket, typically powered by a diesel engine and hydraulic system, to perform excavation, material handling, and demolition. Standard excavators command the largest market share for use in large-scale construction and mining applications. The mini excavator segment, however, represents the fastest-growing product type, driven by residential and utility work in dense urban environments.
Engine emission standards, such as the US EPA's Tier 4 Final, the European Union's Stage V, and China's GB standards, are primary drivers of technological development. These rules mandate significant reductions in particulate matter and nitrogen oxides, forcing investment in advanced after-treatment systems. Consequently, manufacturers face a critical strategic decision. They must balance investment in mature diesel engine compliance against the long-term shift toward fully electric and hybrid models to serve evolving market demands.
Market Dynamics
The central dynamic shaping the crawler excavator market is the strategic tension between investing in emissions compliance for mature diesel technologies and allocating capital for the development of next-generation electric and hybrid powertrains to meet future regulatory and customer demands.
Growth Catalysts
- Urban Infrastructure Projects:Sustained government spending on urban and suburban development in India and Southeast Asian nations creates consistent demand for both mini and standard excavators for utility, road, and residential construction.
- Stringent Emission Standards:Regulations including the EU's Stage V and the US EPA's Tier 4 Final rules compel fleet owners to upgrade older equipment, accelerating the replacement cycle for more efficient, compliant models.
- Precision Agriculture Adoption:The use of crawler excavators for specialized tasks like trenching for irrigation and land contouring in large-scale agricultural operations is opening a new, non-construction application vertical.
Market Restraints
- High Initial Capital Outlay:The substantial upfront investment required for new crawler excavators, particularly for advanced hybrid or electric models, acts as a significant barrier for small-to-medium-sized contractors and rental companies.
- Diesel Fuel Price Volatility:The operational budget for the vast installed base of diesel-powered excavators is directly exposed to unpredictable fluctuations in global fuel prices, impacting total cost of ownership calculations.
- Substitution by Wheeled Excavators:In urban and paved environments, wheeled excavators offer greater mobility and lower surface damage, presenting a direct substitute for crawler models in specific applications like road maintenance.
Strategic Opportunities
- Rental Market Penetration:Expanding equipment rental services in Latin American and African markets provides access to modern machinery for contractors who lack the capital for outright purchase, creating a new channel for unit placements.
- Aftermarket Technology Retrofits:Offering factory-certified telematics, GPS guidance, and safety systems as upgrade kits for the existing equipment population presents a high-margin service and parts revenue stream.
- Hydrogen Powertrain Development:Long-term investment in hydrogen fuel cell technology for heavy-duty excavators can address the range and refueling limitations of battery-electric models, especially for remote mining operations.
Industry Challenges
- Skilled Operator Shortage:A persistent lack of trained personnel proficient in operating machines equipped with modern GPS-guided controls and telematics systems limits the realization of full productivity benefits on job sites.
- Supply Chain for Key Components:Manufacturers face ongoing disruptions in the supply of critical components such as high-pressure hydraulic pumps, electronic control units, and specialized steel, leading to production delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crawler Excavator Market |
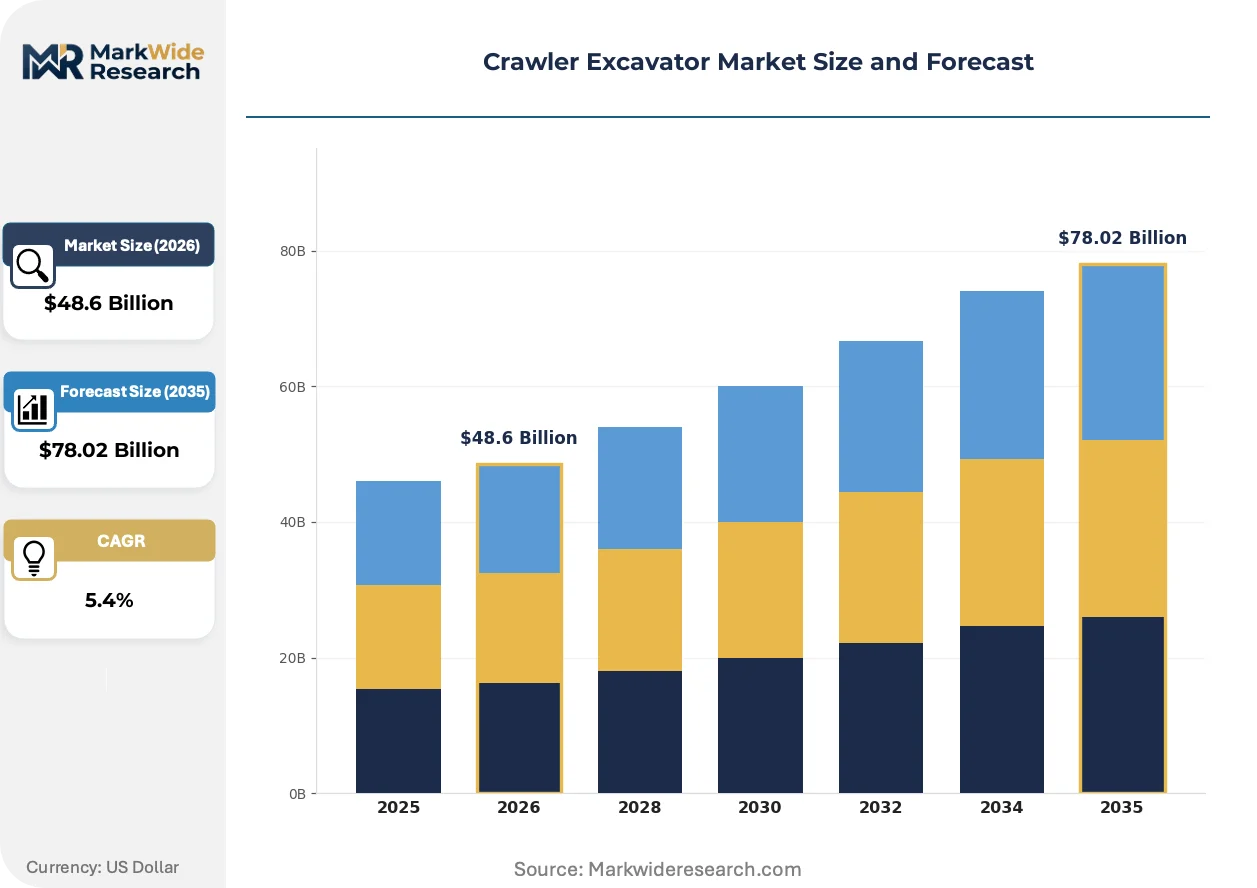
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Excavators, Midi Excavators, Standard Excavators, Heavy Excavators Technology: Hydraulic, Electric, Hybrid, Diesel Engine Application: Construction, Mining, Forestry, Demolition, Infrastructure Development End User Industry: Building Contractors, Mining Companies, Timber Operations, Road Builders |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Hitachi Construction Machinery, Volvo Construction Equipment, Liebherr Group, SANY Group, Doosan Infracore, J C Bamford Excavators, Hyundai Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crawler Excavator Market Strategic Shifts & Innovations
Digitalization is transforming the physical act of earthmoving into a data-driven process. The integration of on-board sensors, telematics, and automation software is changing how projects are planned, executed, and monitored, shifting the basis of competition from pure mechanical power to operational intelligence.
Autonomous and semi-autonomous machine control systems use GPS, LiDAR, and pre-programmed site plans to automate digging and grading functions. Large construction firms are the primary adopters for use on major infrastructure projects to improve accuracy and reduce rework. This technology is fragmenting the traditional equipment operator role into distinct specializations for manual control and system supervision.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory driver influencing equipment procurement. This rule mandates that large companies report on emissions across their value chain, directly impacting construction contractors. Consequently, the excavator segment serving European markets sees accelerated demand for electric and hybrid models to help customers meet their mandatory ESG reporting obligations.
A shift from long-term ownership to shorter-term, project-specific rental agreements is altering equipment acquisition patterns. This trend disrupts the traditional dealer sales channel, favoring large, national rental companies that can offer flexible terms and diverse fleets. This behavior is most pronounced in North America and Europe, where construction project financing models encourage minimizing capital tied up in fixed assets.
Crawler Excavator Market Segmentation
The crawler excavator market's segmentation reveals the diverse operational requirements and technological preferences across various end-use sectors. Understanding these distinct segments assists manufacturers in tailoring product development, sales strategies, and after-sales support for specific customer needs. This granular view highlights areas of concentrated demand and emerging growth opportunities.
Product Type:
The distribution of crawler excavators across product types reflects varied project scales and accessibility requirements, influencing sales channels from direct enterprise procurement to rental fleet acquisitions. Each type caters to distinct operational envelopes, from confined urban sites to expansive mining operations. This differentiation shapes how equipment reaches its end-users.
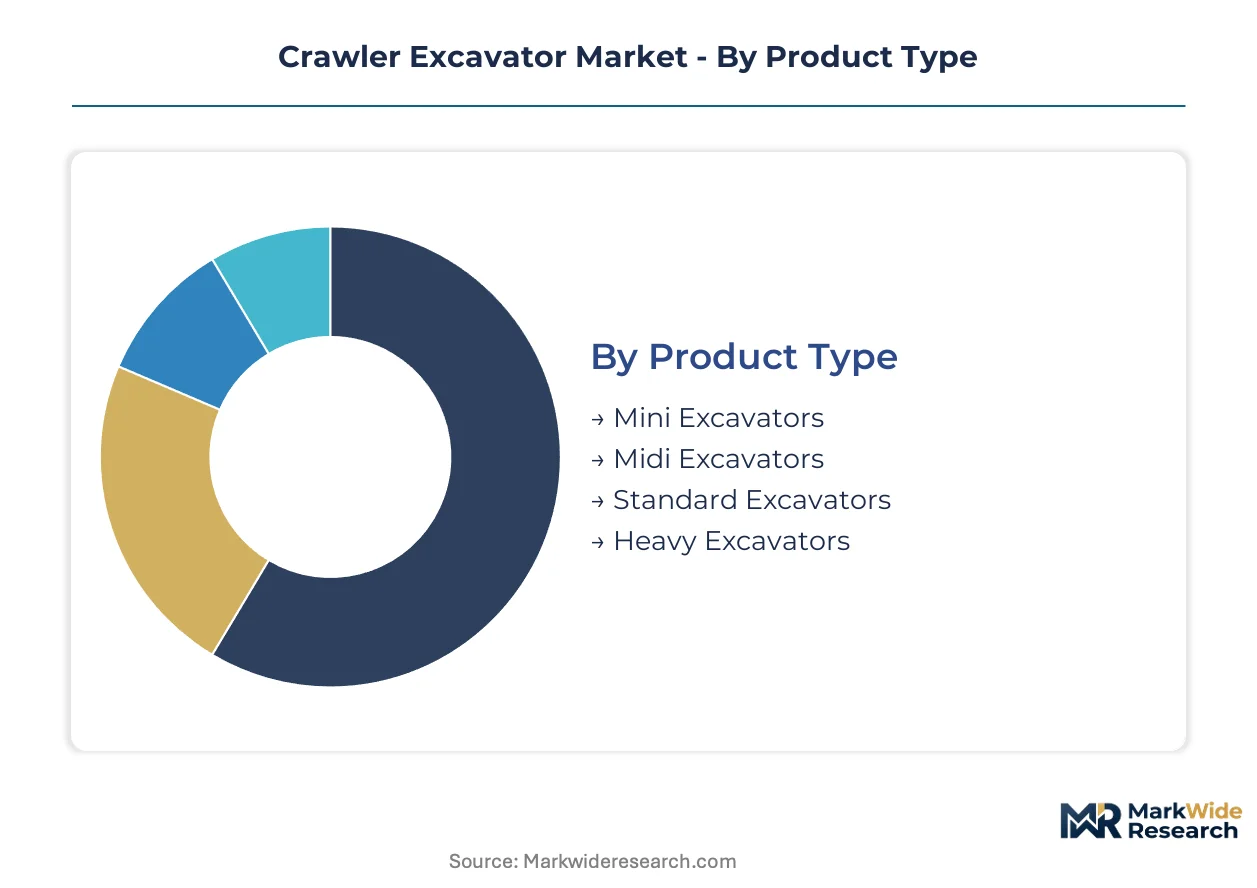
- Mini Excavators:These compact machines typically weigh under 6 metric tons, featuring rubber tracks and reduced tail swing for maneuverability in tight spaces. Demand concentrates in urban residential construction and utility installation projects across European and North American cities, driven by space constraints and lower environmental impact.
- Midi Excavators:Ranging from 6 to 10 metric tons, midi excavators offer a balance of power and agility, suitable for medium-scale construction and landscaping. These machines often serve general contractors and smaller infrastructure projects, providing versatility.
- Standard Excavators:Weighing between 10 and 45 metric tons, standard excavators are the workhorses of large-scale construction, road building, and infrastructure development. This segment commands the largest market share, with significant utilization in India and Southeast Asian nations for extensive urban expansion.
- Heavy Excavators:Machines exceeding 45 metric tons are designed for high-volume earthmoving, quarrying, and mining operations, characterized by powerful engines and large bucket capacities. Their deployment is critical in major resource extraction projects and large infrastructure endeavors globally.
By volume, standard excavators lead the market. By growth pace, the mini excavator segment is expanding most quickly.
Technology:
Technology segmentation highlights the varying maturity levels of powertrain and control systems, directly influencing manufacturers' R&D investment cycles and long-term strategic decisions. The balance between proven diesel reliability and emerging electric alternatives represents a critical industry pivot point. This categorisation also impacts operational costs and regulatory compliance.
- Hydraulic:The core operating principle for all modern excavators, relying on pressurized fluid to power the boom, dipper, and bucket movements. This fundamental technology underpins the mechanical functions of both diesel and electric models, ensuring precise control.
- Electric:These models utilize battery-electric powertrains, eliminating direct emissions and significantly reducing noise levels, making them ideal for urban and indoor applications. Demand for electric excavators is accelerating in European markets due to stringent emissions regulations like the EU's Stage V rules and corporate ESG mandates.
- Hybrid:Hybrid excavators combine a diesel engine with an electric motor and battery system, offering improved fuel efficiency and reduced emissions compared to conventional diesel models. This technology provides a bridge solution for operators seeking better environmental performance without full electrification.
- Diesel Engine:The traditional and dominant power source for crawler excavators, diesel engines offer robust power, long operating hours, and established refueling infrastructure. Sustained demand for diesel models remains strong in regions like India and Southeast Asia, where infrastructure development is extensive.
The market is witnessing a pronounced shift towards electric and hybrid models, driven by evolving environmental regulations and customer sustainability goals.
Application:
The application segmentation illustrates the specific operational demands placed on crawler excavators, influencing machine design, attachment compatibility, and required power output. Each application dictates unique performance characteristics, from precision digging to heavy material handling. This categorization directly informs purchasing decisions by end-users.
- Construction:This broad category encompasses general building construction, commercial developments, and site preparation, requiring versatile excavators for trenching, foundation digging, and material movement. Construction remains a foundational demand driver for all excavator types across global markets.
- Mining:Heavy excavators with robust structures and large capacities are essential for overburden removal, ore extraction, and pit development in surface mining operations. These applications demand machines capable of continuous, high-volume work in harsh environments.
- Forestry:Specialized crawler excavators equipped with felling heads, grapples, and delimbers are used for timber harvesting, land clearing, and road building in forested areas. Their tracked undercarriage provides stability on uneven terrain, crucial for efficient operations.
- Demolition:Excavators fitted with hydraulic breakers, shears, and pulverizers are deployed for dismantling structures, concrete breaking, and debris removal. This application requires machines with high reach, powerful hydraulics, and enhanced operator protection.
- Infrastructure Development:This segment includes road construction, bridge building, utility installation, and public works projects, driving demand for excavators of all sizes. Government spending on urban infrastructure in countries like India and Indonesia fuels consistent procurement.
The diversity of applications underscores the machine's versatility, with construction and infrastructure development demanding the largest fleet deployments.
End User Industry:
Segmentation by end-user industry reveals distinct customer types, each with specific procurement patterns, financial considerations, and operational scales. Understanding these industry-specific needs allows manufacturers to target sales efforts and develop tailored support services. This categorization highlights the varied economic drivers of demand.
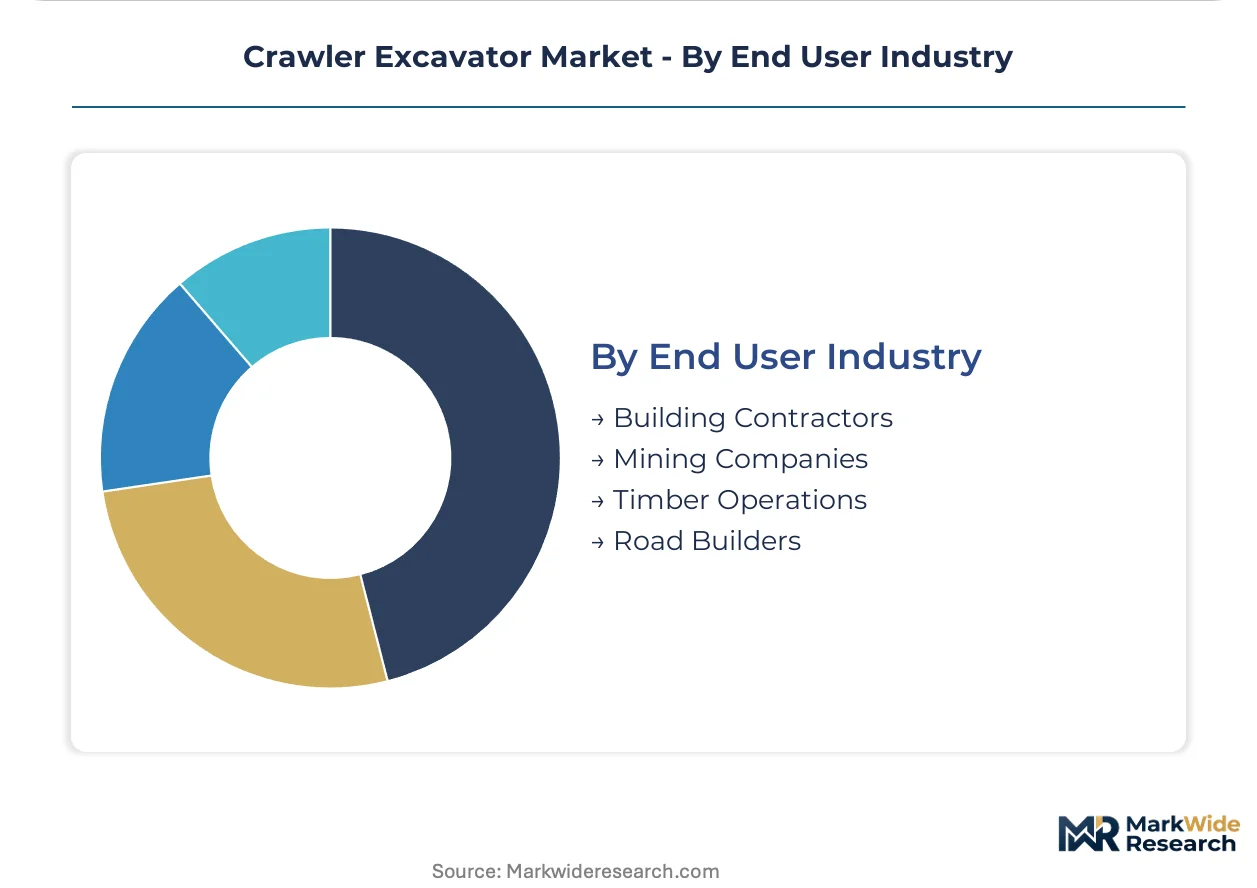
- Building Contractors:These firms, ranging from small local businesses to large general contractors, acquire excavators for residential, commercial, and industrial building projects. Their purchasing decisions are often influenced by project pipeline, equipment rental availability, and total cost of ownership.
- Mining Companies:Large-scale mining corporations and quarry operators invest in heavy-duty excavators for continuous, high-volume earthmoving and material handling. Their procurement is characterized by long-term capital expenditure cycles and a focus on durability and uptime.
- Timber Operations:Forestry companies and logging contractors utilize specialized excavators for felling, delimbing, and material handling in timber harvesting. Their equipment needs are dictated by terrain, tree size, and environmental regulations governing forest management.
- Road Builders:Companies specializing in road construction and maintenance, including government contractors, procure excavators for grading, trenching, and material placement. Their demand is directly tied to infrastructure spending and public works projects in countries like the United States and Germany.
The procurement patterns of building contractors and road builders dictate significant market volumes, while timber operations represent a specialized but consistent customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for crawler excavators varies significantly across global markets, with some buyers prioritizing initial capital outlay while others focus on long-term operational efficiency and emissions compliance. This divergence shapes regional procurement patterns and influences manufacturer investment strategies for different product types.
India
Sustained government investment in urban infrastructure and residential construction drives consistent demand for standard and mini excavators. The country's PLI scheme encourages local manufacturing and technology adoption in construction equipment. Major infrastructure projects around Delhi-NCR and Mumbai fuel significant equipment deployment.
United States
Large-scale public works and commercial construction projects generate substantial demand for heavy and standard excavators. The US EPA's Tier 4 Final regulations compel fleet modernization, accelerating the adoption of more efficient models. Construction hubs in Texas and California experience high equipment utilization rates.
Germany
Stringent environmental regulations, such as the EU's Stage V rules and the Corporate Sustainability Reporting Directive (CSRD), accelerate the shift towards electric and hybrid excavators. Road builders and utility companies in North Rhine-Westphalia demand advanced, fuel-efficient machinery. Berlin's urban development projects increasingly specify low-emission equipment.
China
Extensive infrastructure development, mining operations, and the Belt and Road Initiative underpin robust demand for a full range of crawler excavators. China's GB standards for non-road mobile machinery drive continuous improvements in engine emissions technology. Manufacturing clusters in Jiangsu and Shandong provinces are major production and consumption centers.
Indonesia
Rapid urban expansion and resource extraction projects create consistent demand for both standard and heavy excavators. The country's national infrastructure development plan fuels procurement for road building and port expansion. Jakarta and Surabaya's ongoing urban renewal initiatives require a diverse fleet of construction equipment.
Crawler Excavator Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the crawler excavator market, creating a tiered competitive structure. The market sees established global manufacturers dominating the premium segment, while regional players often compete on price and localized service. Strategic archetypes include innovation-driven multi-nationals, regional specialists, and emerging market challengers. Manufacturers primarily engage in portfolio diversification and strategic partnerships to strengthen their market presence.
On the premium-tier vector, companies such as Caterpillar Inc. and Komatsu Ltd. exemplify global reach and advanced technology integration. These firms leverage extensive dealer networks and significant R&D investments to offer high-performance, digitally integrated machines. Volvo Construction Equipment also occupies a strong position, focusing on fuel efficiency and operator safety systems to differentiate its product offerings globally.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| Liebherr Group |
| SANY Group |
| Doosan Infracore |
| J C Bamford Excavators |
| Hyundai Construction Equipment |
| Others |
Cost & Logistics Intelligence
Extended lead times for high-pressure hydraulic pumps directly influence manufacturing schedules, impacting equipment availability and strengthening pricing power for manufacturers. This concentration in component supply shapes the overall market's cost structure.
Pricing Analysis
Aftermarket technology retrofits and extended warranty programs generate significant lifetime value for crawler excavator manufacturers. The dominant pricing structure involves per-unit transactional sales for smaller buyers and contract-based long-term agreements for large fleet purchases. Price differentiation stems from brand premium and advanced telematics integration. Pricing softness stems from intense competition among global manufacturers. Small-to-medium contractors exhibit high price sensitivity, while major mining companies prioritize total cost of ownership and uptime.
Supply Chain Analysis
Ongoing disruptions in the supply of critical components affect lead times for new excavator deliveries. Manufacturing of key components like high-pressure hydraulic pumps, electronic control units, and specialized steel concentrates in China, Germany, and Japan. A structural risk involves single-source vulnerability for advanced electronic control units. Distribution primarily runs through extensive global dealer networks and specialized equipment rental companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crawler excavator market presents a significant service-attach opportunity, as aftermarket telematics subscriptions and predictive maintenance contracts are expanding faster than new equipment hardware sales. This shift redefines value creation for manufacturers and service providers.
For Market Incumbents: Compound investments in hybrid and electric powertrain research and development to counter stringent emissions regulations like the EU's Stage V rules. Expand global dealer networks to reinforce after-sales service capabilities, mitigating the threat from emerging market challengers competing on price. Leverage existing technology portfolios to offer advanced telematics retrofits, deepening customer loyalty and recurring revenue streams.
For New Entrants and Emerging Players: Lead with specialized mini excavator models targeting the fastest-growing urban utility and residential construction segments. Penetrate underserved rental markets in Latin American and African markets by offering flexible financing and robust local service partnerships. Focus on electric or hybrid models to meet evolving environmental mandates in European cities, creating a distinct value proposition against diesel incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from large industrial conglomerates seeking to divest non-core heavy equipment divisions. The market demonstrates long-term viability driven by global infrastructure development and urban expansion over the next decade. Identify mid-sized manufacturers specializing in electric or autonomous control systems as prime acquisition archetypes. The signal to watch is the accelerated adoption rate of hydrogen powertrain pilot projects in mining operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports regional infrastructure demand and reduces logistics costs for key growth markets. |
| Green Manufacturing Transition | Aligns with EU CSRD requirements and enhances brand reputation among environmentally conscious buyers. |
| Strategic Partnership with Battery Technology Providers | Secures critical component supply for electric and hybrid excavator models. |
| Platform Integration of Advanced Telematics and AI | Improves operational efficiency and enables predictive maintenance for fleet operators. |
| Aftermarket Technology Retrofits for Diesel Fleets | Generates high-margin service revenue and extends the lifespan of older equipment. |
Research Approach
A standing panel of construction equipment engineers, fleet managers, procurement specialists, and rental company executives provided ongoing calibration. Primary interviews with these industry stakeholders were rigorously validated against secondary data from EPA Tier 4 Final reports, EU Stage V guidelines, national infrastructure spending reports, and OEM financial disclosures. This approach ensured comprehensive bottom-up and top-down triangulation of market insights.
Forecast outputs underwent rigorous consistency checks against external benchmarks and historical market trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and regional regulatory cluster. Compound annual growth rates were derived from volume and value projections. Key forecast inputs included infrastructure spending forecasts and emissions regulation timelines.
The analysis sits within stated boundaries; outcomes outside major geopolitical shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding regulatory stability and economic growth trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Surface Mining Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Africa Mining Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Global Dozers Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Auger Drilling Machine Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Rock Duster Market
Mining Equipment
North America Mining Equipment Market