
 Underground Mining Equipment Market | 2026-2036
Underground Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Mining Equipment Market Intelligence
Adoption of tele-remote and automated systems is bifurcating the market between high-specification and standard diesel-hydraulic machinery. Caterpillar Inc. leverages its extensive global dealer network to support its advanced equipment fleets. Sandvik Mining and Rock Technology specializes in automation and digital solutions for rock excavation. Komatsu Mining Corp. competes on the durability and performance of its mechanical and electric drive systems.
Underground mining equipment encompasses heavy machinery engineered for subterranean excavation and material transport. This machinery must operate within confined spaces and withstand extreme conditions, often featuring reinforced steel frames and high-torque hydraulic systems. Load-Haul-Dump machines constitute a core equipment category, essential for material handling applications. The segment for electric drives shows significant growth, displacing traditional diesel engines in new mine developments.
Safety regulations from bodies like the US Occupational Safety and Health Administration (OSHA) and China's Ministry of Ecology and Environment (MEE) mandate specific equipment features. In Europe, CE marking requirements for machinery safety set stringent design and manufacturing standards. Future investment decisions for mining operators will balance the high initial cost of automated, electric equipment against long-term operational efficiency and regulatory compliance.
Market Dynamics
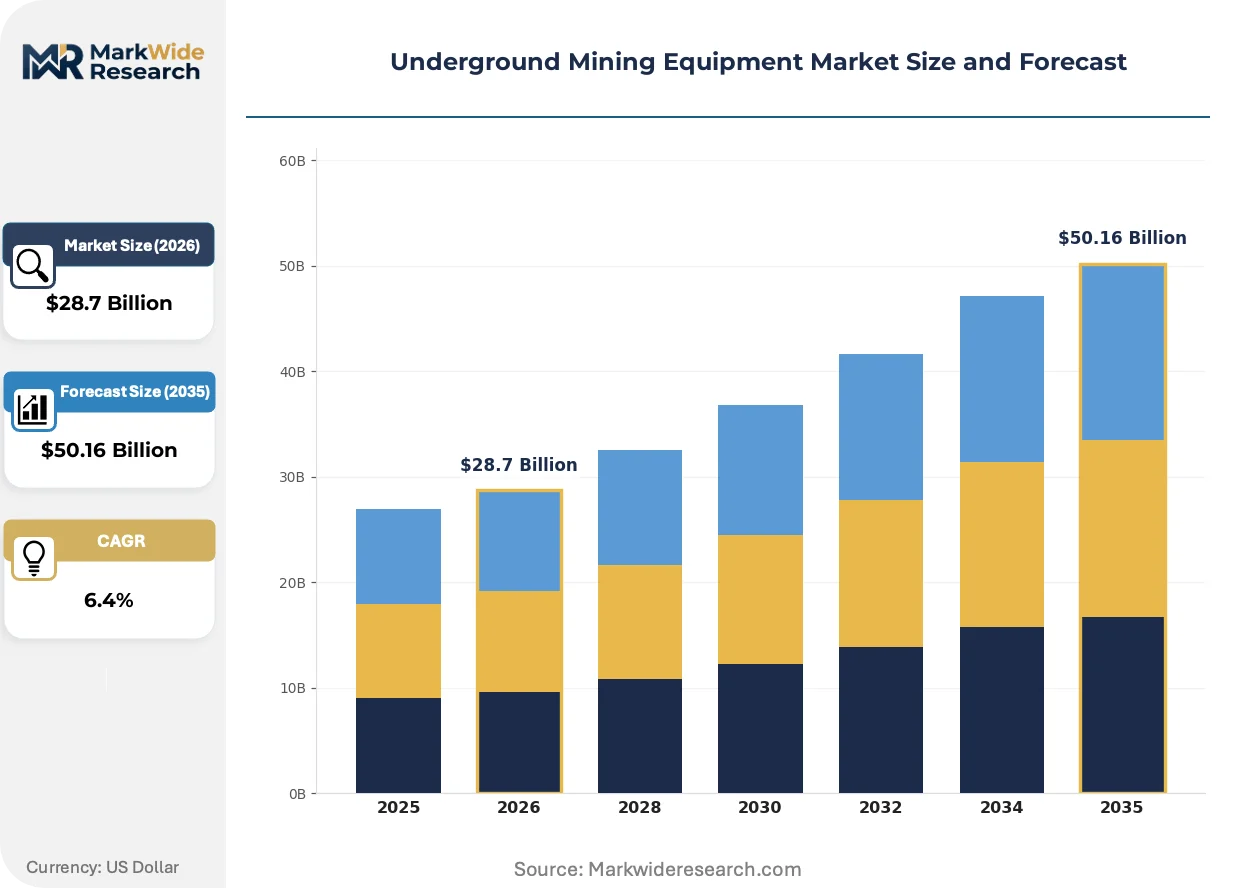
The market's central dynamic is the bifurcation between advanced, automated electric equipment and conventional diesel-hydraulic machinery. This split forces operators to choose between high upfront capital for long-term efficiency and lower initial costs with higher operational and compliance risks.
Growth Catalysts
- Deep Ore Body Exploitation:Demand for industrial metals requires accessing deeper and more complex deposits, necessitating specialized equipment with advanced automation and remote operation capabilities to ensure safety and productivity.
- Electrification Mandates:Stricter emissions regulations from bodies like China's Ministry of Ecology and Environment (MEE) and decarbonization goals in Europe are compelling mine operators to invest in battery-electric vehicle fleets.
- Digitalization of Mining:The integration of IoT sensors and telematics into equipment provides operational data that improves asset utilization, predictive maintenance, and overall mine efficiency, creating a strong pull for connected machinery.
Market Restraints
- High Capital Expenditure:The significant initial investment required for automated and battery-electric equipment presents a substantial barrier for junior miners and operators of smaller, short-life mines.
- Mine Infrastructure Deficits:Many existing underground mines lack the requisite high-bandwidth communication networks and electrical charging infrastructure needed to support modern, automated, and electric fleets.
- Specialized Component Dependency:Production of high-torque hydraulic systems and durable battery packs is concentrated among a few suppliers, creating potential supply chain vulnerabilities and price volatility for equipment manufacturers.
Strategic Opportunities
- Aftermarket Digital Services:Offering data analytics and predictive maintenance as a subscription service for connected equipment fleets creates a recurring revenue stream beyond initial hardware sales.
- Modular Retrofit Kits:Developing certified kits to convert existing diesel equipment to battery-electric power allows operators to meet emissions targets without a full fleet replacement, targeting mid-life assets.
- Emerging Mining Frontiers:Supplying equipment to new mining projects in regions like the African Copperbelt offers an opportunity to establish a footprint with the latest generation of automated and electric machinery from the outset.
Industry Challenges
- Skilled Labor Scarcity:A critical shortage of technicians and operators proficient in maintaining and operating sophisticated tele-remote, automated, and battery-electric systems hinders equipment deployment and uptime.
- System Interoperability:Integrating new automated equipment from one manufacturer with legacy control systems and machinery from another creates significant software and hardware compatibility challenges for mine operators.
- Regulatory Certification Hurdles:Navigating the complex and time-consuming certification processes for new equipment designs across different jurisdictions, such as CE marking in Europe and OSHA standards in the US, delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Mining Equipment Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Drilling Rigs, Load-Haul-Dump Machines, Bolters, Winches, Scoop Trams Technology: Automation, Tele-Remote Operation, Diesel Engines, Electric Drives, Hydraulic Systems Application: Ore Extraction, Tunnel Construction, Shaft Sinking, Rock Support, Material Handling End User: Mining Contractors, Mineral Processing Firms, Coal Extraction Facilities, Metal Ore Manufacturers, Quarry Operators |
| Companies Covered | Epiroc, Hitachi Construction Machinery, Caterpillar Inc., Shandong Yanmei Heibao Mining Equipment, Metso, Komatsu Mining Corp., Liebherr, Joy Global, Sandvik Mining and Rock Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Mining Equipment Market Strategic Shifts & Innovations
The evolution of underground mining equipment is defined by the twin forces of electrification and digitalization. These trends are fundamentally changing equipment architecture, operational logic, and the competitive landscape by shifting value from pure mechanical performance to software-defined capabilities and data analytics.
High-density lithium-ion battery packs are the core technology enabling zero-emission underground machinery. Mine operators developing new deposits are rapidly adopting battery-electric vehicles to eliminate diesel particulate matter and reduce ventilation costs. The continuous improvement in power density is miniaturizing the physical footprint of battery systems, allowing their integration into smaller equipment classes like utility vehicles and narrow-vein loaders.
European Union CE marking requirements, governed by the Machinery Directive, set stringent design and manufacturing standards for equipment safety. This regulation compels manufacturers to integrate advanced features like autonomous emergency braking and personnel detection systems as standard. The underground loader and truck segments are most affected, prompting redesigns of operator cabins and control interfaces to ensure compliance for access to the European market.
A shift in purchasing criteria toward total cost of ownership and data integration is altering how equipment is sold. This behavioral change disrupts the traditional model of one-time hardware sales, favoring suppliers who provide comprehensive fleet management software and operational support. This trend is most visible in Australia and Canada, where large-scale mining companies leverage telematics data to optimize haulage routes and schedule predictive maintenance.
Underground Mining Equipment Market Segmentation
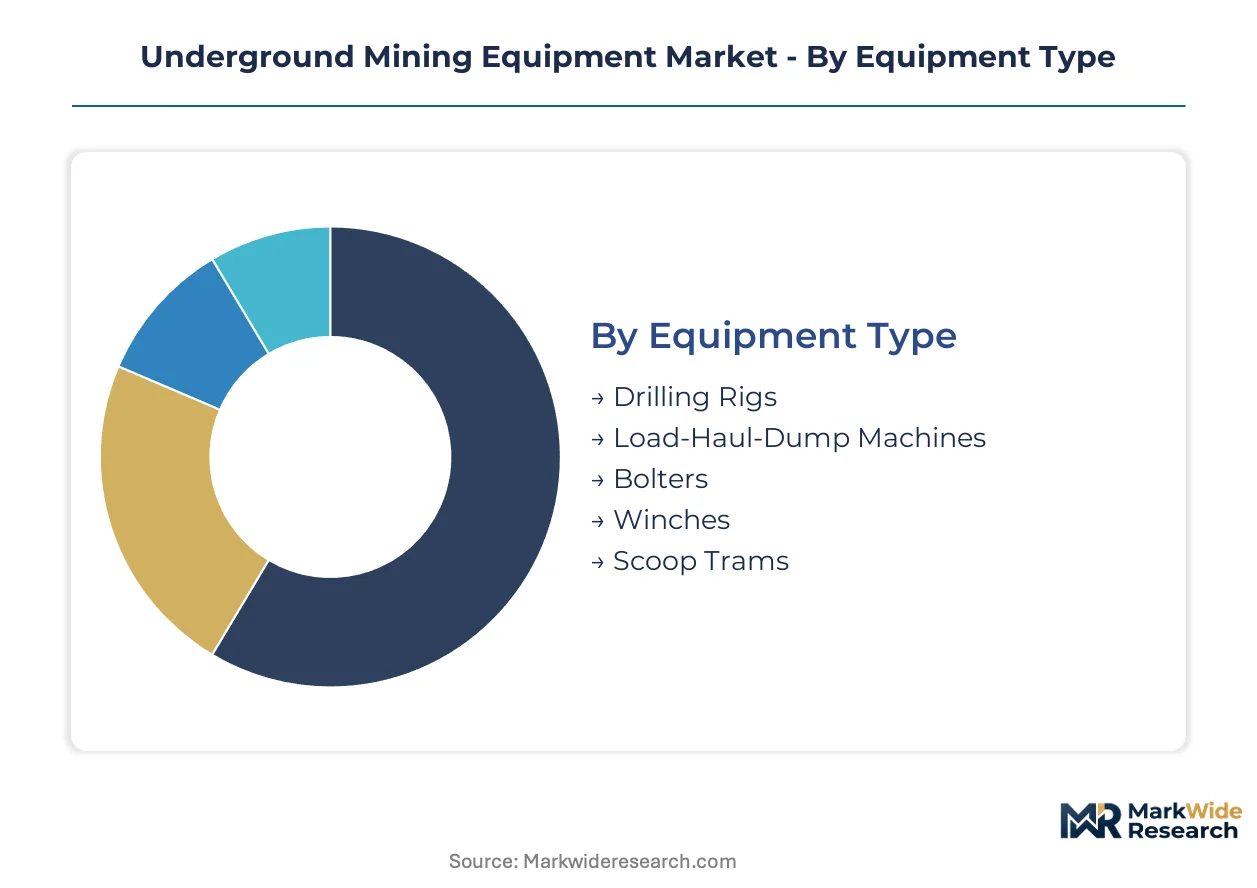
The underground mining equipment market exhibits clear segmentation across various operational facets, reflecting the diverse requirements of subterranean excavation. Understanding these distinctions helps identify where investment and technological advancements are most concentrated within the industry.
Equipment Type:
Margin pools within underground mining equipment are concentrated in specialized, high-performance machinery that addresses complex operational challenges.
- Load-Haul-Dump Machines:These robust articulated vehicles combine loading and hauling functions, essential for efficient material transfer from the face to ore passes or trucks. Demand for advanced LHDs is strong in Australia, where large-scale operations prioritize high productivity and automation.
- Drilling Rigs:Designed for precision rock excavation, these machines bore holes for blasting or rock reinforcement, ranging from face drilling to long-hole production. Deeper deposits in regions like Canada drive demand for sophisticated drilling rigs with enhanced automation features.
- Bolters:Specialized machinery installs rock bolts to stabilize mine roofs and walls, crucial for worker safety in challenging geological conditions.
- Winches:These powerful hoisting devices manage heavy loads and personnel movement within shafts and inclines, critical for vertical transport systems.
- Scoop Trams:Compact, low-profile loaders are used for mucking and hauling in narrow veins and confined spaces, particularly in smaller-scale operations.
Load-Haul-Dump Machines hold installed capacity. Drilling Rigs are rotating up the share rankings.
Technology:
Cost tiers significantly influence technology adoption, with high initial investment for advanced systems versus lower upfront costs for conventional solutions.
- Electric Drives:These battery-powered or tethered electric systems eliminate diesel emissions and reduce ventilation requirements, gaining traction in new mine developments. The European decarbonization goals significantly propel the adoption of electric drive solutions.
- Automation:This technology integrates sensors, software, and remote control for autonomous or semi-autonomous equipment operation, enhancing safety and productivity. Mines in South Africa are increasingly implementing automation to mitigate labor risks and optimize output.
- Tele-Remote Operation:Operators control machinery from a safe distance using cameras and communication systems, particularly useful in hazardous or unstable ground conditions.
- Diesel Engines:Traditional internal combustion engines power much of the existing fleet, offering robust performance in mines without extensive electrical infrastructure.
- Hydraulic Systems:High-torque hydraulic systems provide the power for heavy lifting, digging, and propulsion in most underground machinery, ensuring operational force.
The segment for Electric Drives exhibits the steepest expansion trajectory. Diesel Engines continue to command substantial operational expenditure.
Application:
Application diversity drives equipment specification, requiring tailored solutions for varied subterranean tasks.
- Ore Extraction:This primary application involves the removal of valuable minerals from underground deposits, dictating the need for powerful drilling, loading, and hauling equipment. Metal ore manufacturers globally demand specialized machinery for efficient ore extraction.
- Material Handling:This encompasses the transport of excavated rock, ore, and waste within the mine, relying heavily on Load-Haul-Dump machines and conveyor systems. Efficiency in material handling is a major focus for large-scale operations in Chile.
- Tunnel Construction:Equipment for this application creates access tunnels and drifts, requiring precise drilling, blasting, and excavation capabilities.
- Shaft Sinking:Specialized machinery and techniques are employed to excavate vertical access shafts, essential for deep mine development and ventilation.
- Rock Support:This application utilizes bolters and shotcrete machines to stabilize excavated ground, ensuring structural integrity and worker safety.
Ore Extraction represents the foundational demand. Material Handling is gaining significant traction due to specialized project requirements.
End User:
Customer type determines procurement scale, with large-scale operators prioritizing advanced fleets and smaller entities focusing on cost-effective solutions.
- Metal Ore Manufacturers:These large-scale operators extract valuable metals like copper, gold, and iron, driving demand for high-capacity, automated, and electric equipment. Major manufacturers in Peru are investing in advanced fleets for deep-seated deposits.
- Mining Contractors:These firms provide specialized mining services to various clients, often requiring flexible equipment fleets that can adapt to different project specifications. Contractors operating in Australia frequently update their machinery to meet diverse project needs.
- Mineral Processing Firms:While primarily focused on surface operations, these firms require some underground equipment for initial material handling and transport to processing plants.
- Coal Extraction Facilities:These facilities utilize specialized equipment for the excavation and transport of coal, often adapted for specific seam heights and conditions.
- Quarry Operators:Primarily surface-based, some quarry operations extend underground, necessitating equipment for localized excavation and material removal.
Procurement by Metal Ore Manufacturers increasingly emphasizes long-term efficiency. Mining Contractors maintain a consistent demand for robust, standard machinery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global underground mining equipment market exhibits a varied export-import balance across key mining regions. Countries with extensive mineral endowments often drive domestic demand and innovation, influencing global trade flows. Specialized equipment manufacturers strategically position themselves to serve these concentrated demand centers.
Australia
Australia's mining sector drives demand for high-productivity and automated equipment, particularly for large-scale metal ore operations. Work Health and Safety (WHS) regulations mandate specific safety features, influencing equipment design and adoption. Western Australia's Pilbara region sees significant investment in advanced Load-Haul-Dump machines and drilling rigs for iron ore extraction.
Canada
Canada's deep and complex deposits necessitate sophisticated drilling rigs and remote operation capabilities to ensure worker safety. Provincial mining acts, such as Ontario's Occupational Health and Safety Act, shape equipment design requirements. Sudbury, Ontario, is a hub for mining technology innovation and the rapid adoption of electric drive systems.
Chile
Chile's vast copper mines require efficient material handling and ore extraction machinery for continuous operation. The Ministry of Mining implements policies to enhance safety and environmental performance across the industry. The Antofagasta region drives demand for high-capacity Load-Haul-Dump machines crucial for its large-scale copper operations.
China
China's mining industry demands specialized equipment for both coal and metal extraction, driven by extensive domestic resource needs. The Ministry of Ecology and Environment (MEE) mandates electrification to reduce emissions in new mine developments. Inner Mongolia's mining sector is increasingly adopting automated and electric equipment to meet stringent production and environmental targets.
Underground Mining Equipment Market Key Industry Players
Listed leaders compete with private specialists across technology adoption and geographic reach. The market structure presents a tiered landscape, ranging from global full-line suppliers to niche technology providers. Three strategic archetypes include integrated machinery giants, specialized automation solution providers, and regional equipment fabricators. Dominant competitive moves include strategic partnerships for technology co-development and targeted acquisitions to expand product portfolios.
On the premium-tier vector, Caterpillar Inc. and Sandvik Mining and Rock Technology represent global industrial machinery archetypes. Caterpillar Inc., a US-based corporation, exemplifies a comprehensive equipment provider with extensive global distribution networks. Sandvik Mining and Rock Technology, a Swedish-based entity, occupies a position as a specialist in advanced rock excavation and automation solutions. Shandong Yanmei Heibao Mining Equipment, a China-based Co., Ltd., anchors the regional equipment fabricator segment, serving localized demand with robust machinery.
| Leading Market Players |
|---|
| Epiroc |
| Hitachi Construction Machinery |
| Caterpillar Inc. |
| Shandong Yanmei Heibao Mining Equipment |
| Metso |
| Komatsu Mining Corp. |
| Liebherr |
| Joy Global |
| Sandvik Mining and Rock Technology |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized drilling rigs, often exceeding 12 months, directly influence equipment pricing power and manufacturers' inventory management strategies. This dynamic creates a market where supply chain resilience directly impacts pricing stability for critical components.
Pricing Analysis
Industrial OEM buyers anchor a project-based pricing structure, particularly for high-value automated and electric fleets. Price differentiation stems from the level of automation and advanced safety certifications like CE marking in Europe. Cost compression in standard diesel-hydraulic machinery is intensifying due to lower initial capital expenditure requirements. Junior miners exhibit the highest price sensitivity, while large metal ore manufacturers prioritize long-term operational efficiency over upfront cost.
Supply Chain Analysis
Port congestion in key trade lanes for heavy machinery components directly impacts inbound logistics costs. Geographic supply of critical components concentrates in countries like China for specialized steel alloys and lithium-ion battery packs, and Sweden for advanced rock excavation technology. A structural risk exists due to single-source vulnerability for high-torque hydraulic systems. Distribution runs through extensive global dealer networks for aftermarket support and direct sales channels for large-scale mining projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The underground mining equipment market faces significant operational bottlenecks due to a critical shortage of skilled technicians proficient in automated and electric systems.
For Market Incumbents: Fortify core market positions by investing in proprietary software platforms that enhance interoperability across diverse equipment fleets. Expand global service networks, particularly in emerging mining frontiers, to counter localized support gaps. This strategy hedges against the threat of specialized automation providers and leverages certification investment for new electric drive standards.
For New Entrants and Emerging Players: Post-sales data analytics support for smaller operators represents an underserved service-layer gap. Target the modular retrofit kit market to convert mid-life diesel assets, offering a cost-effective pathway to electrification. Focus on specialized equipment for new mining projects in regions like the African Copperbelt. A subscription-based digital services model offers a compelling go-to-market angle for these solutions.
For Investors and Strategic Acquirers: Carve-out targets emerge from non-core automation divisions of large industrial conglomerates seeking to streamline operations. The market offers long-term strategic value in digital solutions and electrification technologies over a 5-10 year window. Niche software providers specializing in equipment interoperability or battery management systems represent attractive acquisition archetypes. Consolidation activity among smaller telematics or sensor manufacturers signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven Predictive Maintenance | Optimizes uptime for automated fleets, reducing operational expenditure for metal ore manufacturers. |
| Develop Modular Battery Swap Systems | Accelerates electric equipment adoption by addressing charging infrastructure deficits in existing mines. |
| Expand Operator Training Programs | Mitigates skilled labor scarcity, improving safety and productivity for mining contractors. |
| Form Strategic Partnerships for Interoperability | Addresses system integration challenges between different manufacturers' equipment for mine operators. |
| Target Retrofit Solutions for Diesel Fleets | Enables compliance with stricter emissions regulations without full fleet replacement for existing mines. |
Research Approach
A spread of perspectives from mine operators, equipment manufacturers' R&D leads, regulatory body officials, and mining contractors converged on the working assumptions for this report. This involved combining primary interviews with industry stakeholders and secondary validation from governmental mining reports, industry association publications, company annual reports, and patent databases. The approach employed both bottom-up and top-down triangulation to ensure data consistency.
The segmentation dimensions modeled include equipment type, technology, application, end user, and regional regulatory compliance across the analysis window. Quantitative outputs for value and volume were derived from historical growth patterns and projected technological adoption curves for each segment. Industry-specific forecast inputs included metal commodity price forecasts and global mining CAPEX trends.
Underlying assumptions cover current technological trajectories and regulatory frameworks, with deviation risk concentrated in unforeseen geopolitical events affecting supply chains or rapid shifts in environmental regulations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
DTH Drill Market
Mining Equipment
Rock Duster Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Pin Drilling Unit Market