
 Construction and Mining Equipment Market | 2026-2036
Construction and Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Construction and Mining Equipment Market Analysis
Buyer concentration among mining companies and infrastructure developers is broadening as state-owned enterprises consolidate procurement while rental services fragment ownership across smaller contractors. Caterpillar Inc. leverages its dealer network and remanufacturing capabilities to sustain aftermarket revenue streams. Komatsu Ltd. anchors its position through integrated autonomous haulage systems deployed across Australian iron ore operations. SANY Group competes aggressively on cost-adjusted specifications in emerging markets.
Construction and mining equipment encompasses heavy machinery engineered for earthmoving, material extraction, and site preparation, typically powered by diesel engines rated between 100 and 4,000 horsepower and built with high-strength steel frames to withstand impact loads and continuous duty cycles. Excavators dominate product type revenue due to versatility across demolition and site development tasks, while automation technology represents the fastest-expanding segment as fleet operators deploy telematics and autonomous haulage to reduce operator costs. Earthmoving applications maintain the largest installed base, though material handling grows fastest in urban construction corridors where space constraints favor compact loader configurations.
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by ECHA compel engine manufacturers to integrate selective catalytic reduction and diesel particulate filters, adding cost but creating aftermarket service opportunities for compliant retrofit providers. China's MIIT mandates national emission standards aligned with GB coding that push domestic manufacturers toward electrified powertrains in metropolitan construction zones. Stakeholders must monitor regulatory divergence across Washington, Brussels, and Beijing, as divergent compliance timelines will fragment product portfolios and test regional manufacturing flexibility.
Market Dynamics
The construction and mining equipment sector is experiencing a fundamental restructuring as emissions regulations in the United States, European Union, and China force simultaneous engine technology overhauls while autonomous haulage systems rewrite operational economics for large-scale mining operators.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V mandates:These regulations compel fleet replacement cycles, generating equipment procurement as operators retire non-compliant assets rather than retrofit older machines.
- Autonomous haulage technology:Mining operators in Australia deploy driverless truck fleets to reduce labor costs and eliminate shift-change downtime, creating pull for integrated control systems.
- China's infrastructure stimulus:State-backed project financing concentrates demand among domestic equipment manufacturers serving railway, highway, and urban development contracts.
Market Restraints
- High-strength steel and rare earth input costs:Volatility in alloy pricing compresses margin structures for equipment manufacturers already absorbing selective catalytic reduction and diesel particulate filter integration expenses.
- Engine supply concentration:A limited supplier base for Tier 4 Final and Stage V compliant powertrains creates procurement bottlenecks and extends lead times for non-integrated manufacturers.
- Electrification technical limitations:Battery energy density constraints restrict viable deployment of electric excavators and haul trucks to short-duty-cycle urban applications, excluding most mining operations.
Strategic Opportunities
- Remanufacturing and retrofit services:EPA and ECHA compliance deadlines create aftermarket revenue pools for engine rebuild specialists and emissions retrofit providers serving aging installed bases.
- Telematics convergence with predictive maintenance:Equipment-mounted sensors and cloud analytics platforms enable uptime guarantees and service contract bundling, shifting revenue from unit sales to recurring service streams.
- Rental and equipment-as-a-service models:Smaller contractors in Southeast Asia and Latin America favor short-term equipment access over ownership, fragmenting demand toward rental fleet operators.
Industry Challenges
- Autonomous systems integration complexity:Mining operators struggle to retrofit legacy fleet management infrastructure with vendor-specific autonomous haulage platforms, requiring costly site-wide control system overhauls.
- Certification timeline compression:Divergent EPA, ECHA, and MIIT compliance deadlines force manufacturers to maintain multiple engine calibration and aftertreatment configurations, testing engineering bandwidth.
- Telematics cybersecurity skill gaps:Fleet operators lack in-house expertise to secure connected equipment against remote access threats, creating liability exposure as machine connectivity expands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction and Mining Equipment Market |
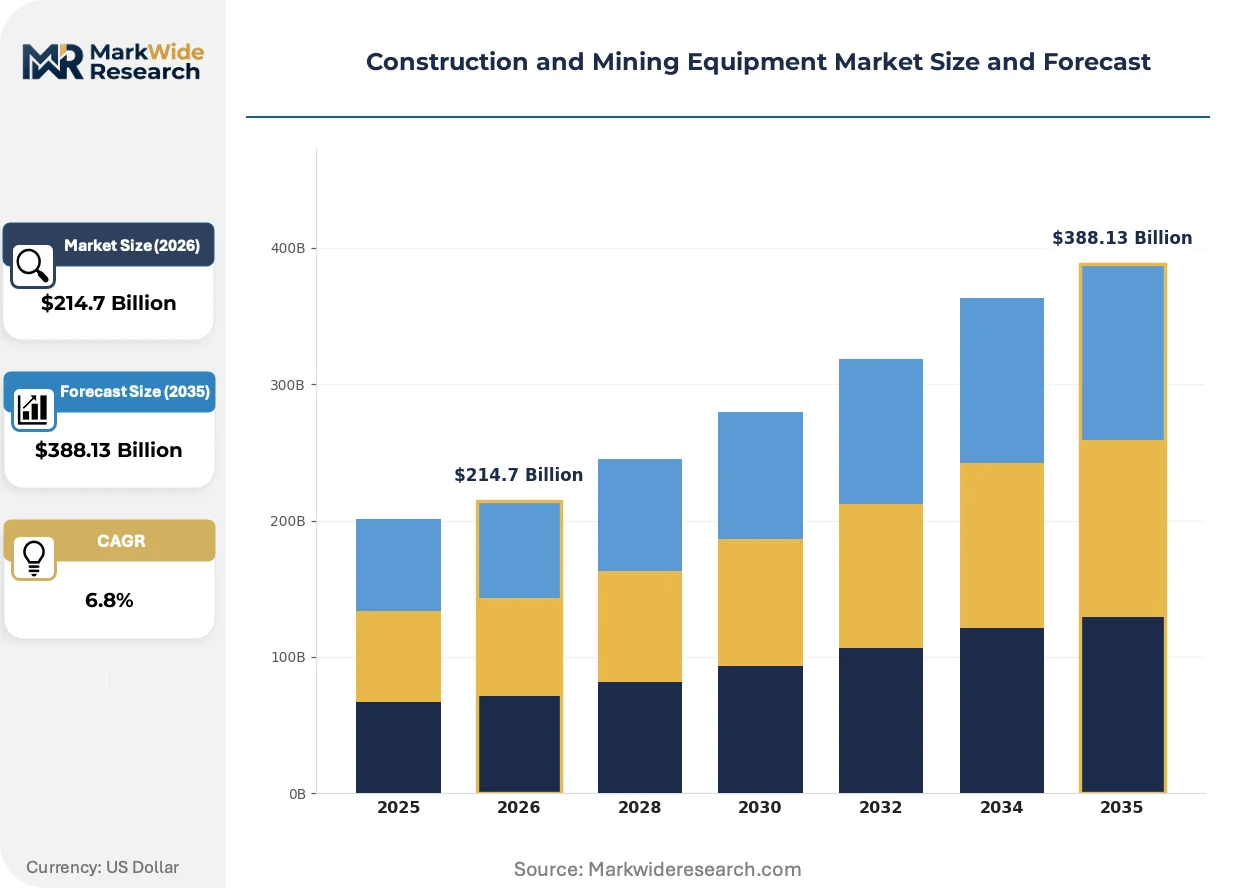
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Loaders, Dump Trucks Application: Earthmoving, Material Handling, Demolition, Site Development End User: Contractors, Mining Companies, Infrastructure Developers, Rental Services Technology: Automation, Telemetry, Hybrid, IoT |
| Companies Covered | Volvo Construction Equipment, SANY Group, Caterpillar Inc., Epiroc AB, XCMG Group, Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., Sandvik AB, Liebherr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction and Mining Equipment Market Emerging Trajectories
Technology convergence and regulatory stringency are compressing product development cycles while reshaping how equipment value is captured and delivered across construction and mining operations.
Autonomous haulage systems are consolidating operational control across mining sites by integrating GPS positioning, LiDAR obstacle detection, and centralized fleet dispatch. Major iron ore producers in Western Australia now operate substantial driverless truck populations, compressing labor cost structures and enabling continuous 24-hour production cycles without shift-change interruptions. This consolidation of control architecture is displacing traditional operator-dependent workflows and forcing equipment manufacturers to bundle hardware with proprietary software stacks.
EU Stage V emissions standards enforced by ECHA mandate particulate number limits and real-driving emissions monitoring for non-road mobile machinery. Engine manufacturers respond with dual-stage aftertreatment combining diesel oxidation catalysts, diesel particulate filters, and selective catalytic reduction, adding hardware cost and packaging complexity. Compact construction equipment faces the steepest engineering challenges as aftertreatment volume competes with operator visibility and machine maneuverability in constrained urban job sites.
Fleet procurement patterns are fragmenting as state-owned infrastructure developers consolidate bulk purchasing power while rental services disaggregate ownership among smaller contractors. Equipment-as-a-service contracts with bundled maintenance and uptime guarantees displace traditional capital expenditure models in European urban construction corridors where project duration uncertainty favors operational flexibility over asset ownership. This behavioral shift concentrates manufacturer relationships with large rental fleet operators rather than dispersed end-user accounts.
Construction and Mining Equipment Market Segmentation
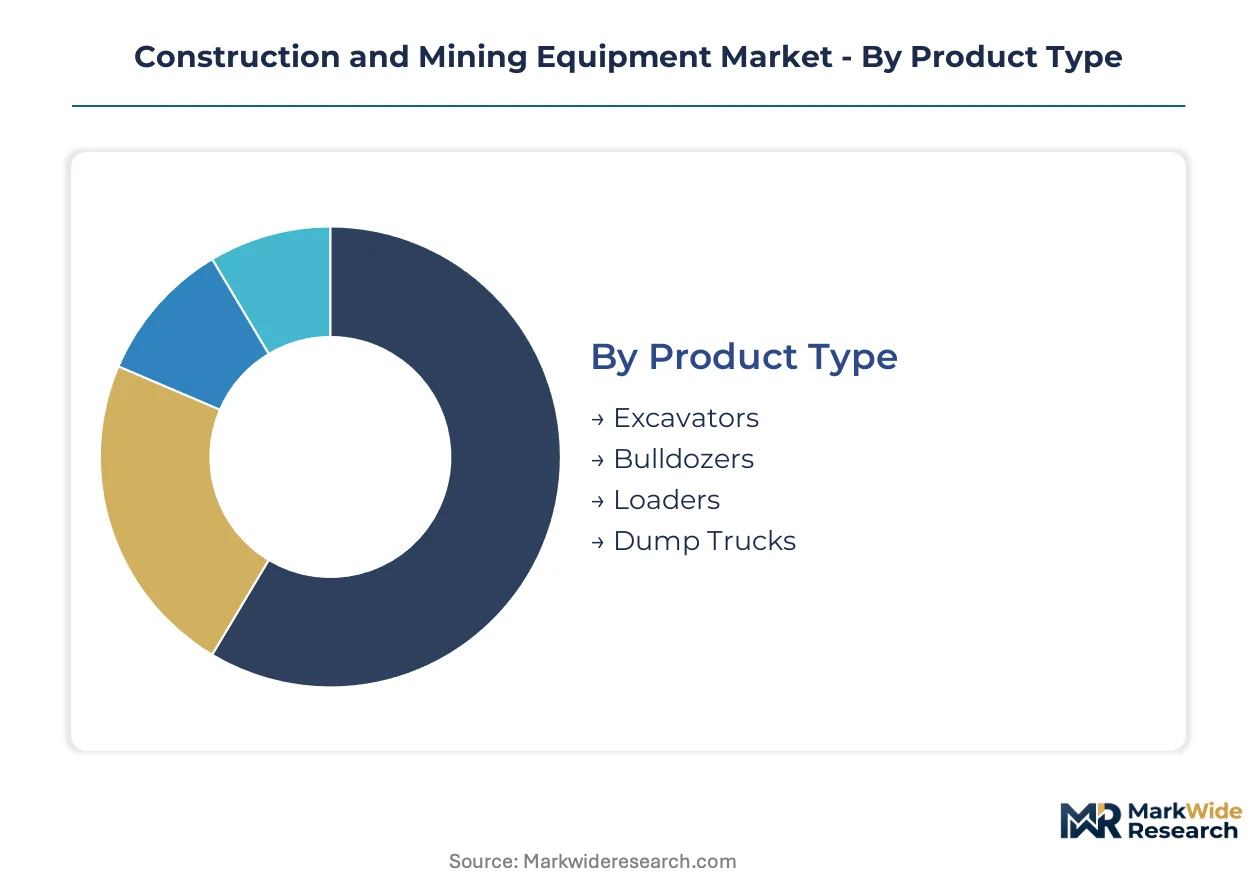
Segmentation in construction and mining equipment reveals how regulatory compliance cycles, autonomous technology deployment, and procurement consolidation reshape equipment specifications and customer relationships. Equipment manufacturers calibrate product portfolios across these dimensions to capture replacement demand while positioning for electrification transitions.
Product Type:
Equipment replacement cycles accelerate as EPA Tier 4 Final and EU Stage V deadlines force fleet turnover, with each product category facing distinct engineering constraints for emissions aftertreatment integration.
- Excavators:Hydraulic systems with boom, stick, and bucket configurations ranging from compact 3-ton models to 800-ton mining units. Demand concentrates in urban demolition and site development across China, where state-backed infrastructure contracts favor versatile machinery capable of foundation work and material loading. Tier 4 Final aftertreatment packaging challenges visibility and counterweight design in compact models.
- Bulldozers:Track-laying earthmovers with blade capacities from 3 to 70 cubic yards, engineered for continuous pushing and grading operations. Mining companies in Australia deploy large dozers for overburden removal, driving procurement of integrated GPS grading systems that reduce rework and fuel consumption. Blade hydraulics and undercarriage durability dominate total cost of ownership calculations.
- Loaders:Wheeled and tracked configurations with bucket capacities from 1 to 40 cubic yards serve material handling and stockpile management. Compact wheel loaders face the steepest Stage V packaging constraints in European urban corridors.
- Dump Trucks:Rigid and articulated haulers with payload ratings from 20 to 400 tons move overburden and ore across mining sites. Autonomous retrofit compatibility increasingly dictates procurement specifications.
Volume placements concentrate in excavators; the faster expansion belongs to dump trucks configured for autonomous haulage integration.
Application:
Application-specific duty cycles determine powertrain specifications, with continuous mining operations demanding different durability standards than intermittent construction tasks.
- Earthmoving:Mass excavation, grading, and terrain modification operations consuming the largest installed base of heavy equipment. Infrastructure developers in China concentrate bulk procurement for railway and highway corridor projects, while Australian iron ore miners prioritize 24-hour continuous operation capability. Soil abrasiveness and haul distance dictate undercarriage and engine cooling system specifications.
- Material Handling:Loading, transporting, and stockpiling bulk materials across construction sites and mining facilities. Urban construction corridors in Europe favor compact loader configurations where space constraints and emissions regulations intersect most severely. Telematics integration enables fleet utilization optimization and predictive maintenance scheduling.
- Demolition:Structure decommissioning with specialized attachments including hydraulic breakers, crushers, and shears. High-impact duty cycles accelerate frame fatigue and hydraulic system wear.
- Site Development:Land clearing, drainage installation, and preparatory grading for commercial and residential construction. Project duration uncertainty drives rental service penetration in Southeast Asian markets.
Earthmoving commands the largest equipment population; material handling is climbing the fastest as urban density intensifies.
End User:
Customer scale and procurement sophistication fragment equipment demand across capital ownership models and operational service contracts.
- Contractors:Small-to-mid-sized construction firms purchasing or leasing equipment for project-specific deployment. Rental services fragment ownership across this segment in Latin America and Southeast Asia, where project pipelines remain unpredictable.
- Mining Companies:Large-scale extractive operators with concentrated purchasing power and technical integration requirements. Australian iron ore producers lead autonomous haulage deployment, creating pull for vendor-integrated control systems and site-wide fleet management platforms.
- Infrastructure Developers:State-owned enterprises and public-private consortiums executing multi-year civil engineering projects. China's state-backed financing concentrates demand among domestic equipment manufacturers serving railway and highway contracts.
- Rental Services:Fleet operators providing short-term equipment access with bundled maintenance and uptime guarantees. European urban construction corridors favor this model as project duration uncertainty increases.
Procurement volumes concentrate with infrastructure developers; rental services are gaining share fastest among smaller contractors.
Technology:
Technology segmentation captures how digitization and electrification reshape equipment value propositions and manufacturer competitive positioning.
- Automation:Autonomous haulage systems integrating GPS positioning, LiDAR obstacle detection, and centralized fleet dispatch. Australian mining operators deploy driverless truck fleets to eliminate shift-change downtime and reduce labor cost structures, forcing equipment manufacturers to bundle proprietary software stacks with hardware.
- Telemetry:Equipment-mounted sensors transmitting operational data to cloud analytics platforms for predictive maintenance and utilization optimization. Fleet operators leverage telematics to secure uptime guarantees and service contract bundling.
- Hybrid:Diesel-electric powertrains capturing regenerative braking energy and optimizing engine load factors. Battery energy density constraints restrict viable deployment to short-duty-cycle urban applications.
- IoT:Machine-to-machine connectivity enabling remote diagnostics, software updates, and operator performance monitoring. Cybersecurity skill gaps create liability exposure as fleet connectivity expands.
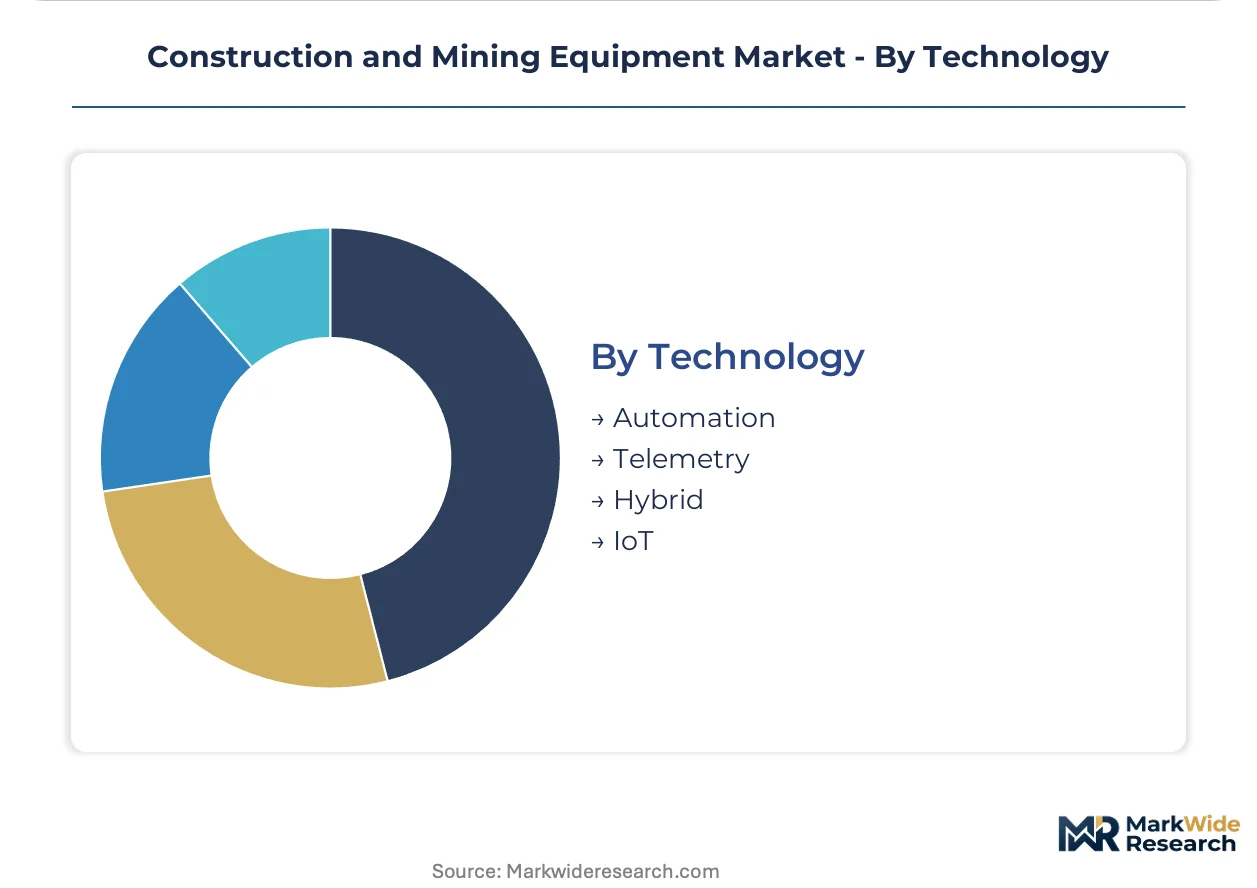
Telemetry installations dominate current equipment shipments; automation is expanding most quickly in large-scale mining deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest procurement volumes through state-backed infrastructure financing, while Australia drives autonomous technology deployment in mining corridors. Equipment demand fragments across regulatory jurisdictions with divergent emissions timelines and electrification mandates.
China
State-owned enterprises consolidate bulk purchasing for railway and highway projects under MIIT-mandated GB emission standards. Domestic manufacturers capture procurement share through cost-adjusted specifications aligned with metropolitan electrification zones. The Yangtze River Delta anchors manufacturing clusters serving urban construction stimulus contracts.
Australia
Iron ore miners in Western Australia deploy autonomous haul truck fleets to eliminate shift-change downtime and compress labor cost structures. EPA-equivalent state regulations govern diesel emissions for non-road mobile machinery across mining tenements. The Pilbara region concentrates autonomous fleet integration trials and vendor control system deployments.
United States
Infrastructure developers concentrate equipment procurement for commercial and residential site preparation under EPA Tier 4 Final mandates. Fleet operators face compliance deadlines forcing replacement cycles rather than retrofit investments. Texas and California anchor regional demand clusters for earthmoving and material handling configurations.
Germany
Construction contractors favor equipment-as-a-service contracts with bundled maintenance under EU Stage V standards enforced by ECHA. Compact loader demand concentrates in urban corridors where aftertreatment packaging competes with maneuverability requirements. Bavaria and North Rhine-Westphalia host manufacturing facilities calibrating for divergent EU and export market specifications.
India
Rental services fragment ownership among smaller contractors executing unpredictable project pipelines across highway and urban development schemes. BIS-aligned emission standards push domestic manufacturers toward localized engine calibration. Maharashtra and Gujarat concentrate equipment deployment for port infrastructure and industrial corridor construction.
Construction and Mining Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and autonomous integration as differentiation vectors. The vendor base organizes around three archetypes: integrated technology providers bundling hardware with proprietary control systems, cost-optimized manufacturers competing on specification-adjusted pricing, and specialized component suppliers serving retrofit and aftermarket channels. Consolidation pressures intensify as emissions compliance costs favor scale economies, while technology licensing partnerships accelerate autonomous capability diffusion without captive R&D investment.
Among diversified heavy machinery manufacturers, Caterpillar Inc. and Komatsu Ltd. exemplify the integrated technology archetype through bundled autonomous haulage offerings, while SANY Group anchors the cost-optimized tier competing aggressively in emerging market procurement cycles. These three entities represent distinct strategic positions: technology integration leadership, autonomous system deployment scale, and specification-adjusted manufacturing cost structures respectively.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| SANY Group |
| Caterpillar Inc. |
| Epiroc AB |
| XCMG Group |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| Sandvik AB |
| Liebherr Group |
| Others |
Supply Flow & Price Mechanics
State-owned infrastructure developers in China concentrate procurement volumes through multi-year railway and highway contracts, anchoring a transaction-based pricing model where unit costs scale with emissions compliance tier and autonomous capability integration.
Pricing Analysis
High-volume placements of excavators and dump trucks generate thin margins offset by aftermarket service contracts, while low-volume autonomous haulage systems command premium pricing tied to vendor-integrated control stacks. Price differentiation hinges on EPA Tier 4 Final certification grade and bundled telematics service tiers. Cost compression in compact loader configurations is intensifying because EU Stage V aftertreatment packaging competes with operator visibility requirements. Rental services in Southeast Asia exhibit highest price sensitivity; Australian mining companies show lowest sensitivity due to labor cost savings from autonomous deployment.
Supply Chain Analysis
Remanufacturing flows from Australian mining sites back to OEM facilities in Japan and Germany create circular supply loops for engine cores and hydraulic components. High-strength steel production concentrates in China, Japan, and South Korea; rare earth elements for electric powertrains draw from Chinese processing facilities. Single-source vulnerability in selective catalytic reduction catalyst supply creates procurement risk for Tier 4 Final compliance. Distribution runs through captive dealer networks for integrated OEMs and independent rental fleet operators for fragmented contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as emissions compliance costs favor scale economies, forcing smaller manufacturers toward specialized retrofit niches or exit.
For Market Incumbents: Lock in autonomous haulage integration partnerships with Australian iron ore operators before competitor control systems achieve site-wide deployment. Deepen backward integration into high-strength steel supply through Japanese and South Korean mill relationships to defend margin position against alloy price volatility. For New Entrants and Emerging Players: Launch via equipment-as-a-service contracts targeting European urban construction corridors where project duration uncertainty favors rental models over ownership. Penetrate the compact electric loader segment in Chinese metropolitan zones where MIIT electrification mandates create procurement preference for zero-emission configurations. For Investors and Strategic Acquirers: The window for entry favors remanufacturing specialists with EPA and ECHA compliance capabilities. Long-term viability rests on aftermarket service revenue streams rather than unit sales. Watch for autonomous haulage platform standardization as the inflection signal for control system vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Integration | Bundles Komatsu and Caterpillar control systems with hardware to capture recurring software revenue from Australian miners. |
| Emissions Retrofit Service Expansion | Creates aftermarket revenue pools for engine rebuild specialists serving Tier 4 Final compliance deadlines in the United States. |
| Backward Integration into Steel Supply | Secures high-strength alloy access from Japanese mills to buffer margin compression from rare earth input volatility. |
| Equipment-as-a-Service Launch | Shifts European contractor relationships from capital sales to bundled maintenance contracts with uptime guarantees. |
| Telematics Platform Convergence | Enables predictive maintenance scheduling for Hitachi and Volvo fleets through cloud analytics integration. |
Methodological Framework
SEC 10-K filings, ECHA regulatory submissions, and MIIT GB standard documentation formed the secondary backbone, supplemented by customs trade data and OEM production disclosures. Primary interviews with maintenance directors at Australian mining operations, procurement leads at Chinese state-owned infrastructure developers, aftermarket service heads at European rental fleet operators, and plant engineers at Japanese steel mills validated demand assumptions. Bottom-up equipment shipment tallies and top-down infrastructure investment forecasts were triangulated to anchor market sizing.
Bottom-up modeling tracked excavator, bulldozer, loader, and dump truck placements across earthmoving, material handling, demolition, and site development applications, while top-down analysis calibrated against mining capital expenditure and infrastructure stimulus disbursements. CAGRs were derived from replacement cycle acceleration under EPA Tier 4 Final and EU Stage V deadlines, autonomous haulage adoption curves in Western Australia, and electrification penetration in Chinese metropolitan construction zones.
Regulatory timeline delays, autonomous technology integration failures, and rare earth supply disruptions are the dominant revision risks. Forecasts reflect assumptions about emissions compliance enforcement consistency and mining labor cost structures. Practitioners should monitor EPA waiver announcements, Australian mining union negotiations, and Chinese rare earth export quotas for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Mining Collectors Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Mining Drills and Breakers Market