
 Brick Making Machines Market | 2026-2036
Brick Making Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Brick Making Machines Market Analysis
The EU Green Deal's embodied carbon thresholds for construction materials is pivoting European brick producers toward automated hydraulic presses with lower thermal footprints. BESS Company leverages its German engineering base to dominate high-precision hydraulic systems for the regional market. Zhengzhou Yingfeng Machinery Co., Ltd anchors its position through integrated kiln-to-press manufacturing lines serving Central Asian export corridors. Quangong Machinery (QGM) competes on scale, operating one of China's largest automated block production facilities for domestic infrastructure tenders.
Brick making machines are mechanical or hydraulic systems designed to form, compress, and cure raw materials—typically clay, fly ash, concrete, or aggregate mixtures—into standardized masonry units with dimensional tolerances of ±2 millimeters and compressive strengths ranging from 5 to 50 MPa depending on formulation and curing protocol. Their primary purpose is to replace traditional hand-molding or fired-clay kiln methods with repeatable, high-throughput production for modern construction supply chains. Automatic technology commands the dominant share of value as labor costs rise and batch consistency requirements tighten across commercial and infrastructure end users. Hollow blocks represent the fastest-expanding product category, driven by thermal efficiency mandates in residential construction across multiple climate zones. Clay-based material formulations retain entrenched positions in heritage-sensitive and rural markets where regulatory exemptions preserve traditional firing methods.
The US EPA enforces particulate emissions limits on brick manufacturing under Clean Air Act Title V permits, directly shaping equipment specifications for catalytic after-treatment and dust capture integration. China's MEE implements dual carbon goals through provincial energy-intensity quotas that restrict traditional kiln operations and incentivize electric press adoption. India's BIS certification for fly ash-lime bricks mandates minimum compressive strength and dimensional uniformity, creating compliance barriers for manual machine operators. Stakeholders must monitor how tightening carbon border adjustments in Europe and North America reshape export eligibility for brick producers in emerging manufacturing hubs.
Market Dynamics
Kiln electrification and press-based forming methods are compressing thermal footprints across brick manufacturing, driven by emissions mandates under the EU Green Deal and China's dual carbon goals. This structural pivot favors automated hydraulic systems over traditional fired-clay operations.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:European brick producers face binding limits on construction material emissions, accelerating procurement of automated hydraulic presses with lower thermal intensity.
- Urban housing programs:State-level affordable housing missions in India, Bangladesh, and Nigeria sustain continuous equipment replacement cycles for machine-made brick procurement.
- Fly ash-lime formulation standards:India's BIS certification mandates minimum compressive strength and dimensional uniformity, creating compliance pull for automated batch systems over manual operations.
Market Restraints
- Steel and hydraulic component cost volatility:Press frame fabrication depends on structural steel and precision hydraulic cylinders, exposing manufacturers to commodity price swings without long-term supply contracts.
- Traditional kiln operator concentration:Rural India and Bangladesh retain entrenched networks of small-scale fired-clay producers with regulatory exemptions and established distribution relationships.
- Electrification infrastructure gaps:Grid reliability limitations in northern Nigerian states and Bangladeshi rural districts constrain electric press deployment regardless of emissions policy intent.
Strategic Opportunities
- Central Asian export corridors:Integrated kiln-to-press manufacturing lines serve growing infrastructure demand across Kazakhstan, Uzbekistan, and Turkmenistan with limited domestic equipment production.
- Carbon border adjustment preparation:European importers of construction materials face tightening eligibility standards, creating retrofit demand for emissions-compliant machinery in emerging manufacturing hubs.
- Hollow block thermal efficiency mandates:Residential construction codes across multiple climate zones specify insulation performance, expanding specification of cavity-forming press dies and automated curing protocols.
Industry Challenges
- Electromechanical technician scarcity:Automated press maintenance requires hybrid mechanical-hydraulic-electrical competencies that vocational training systems in India and Nigeria have not scaled to match equipment deployment rates.
- Legacy kiln integration complexity:Hybrid facilities attempting partial electrification face control system incompatibilities between traditional firing automation and modern press-based forming lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brick Making Machines Market |
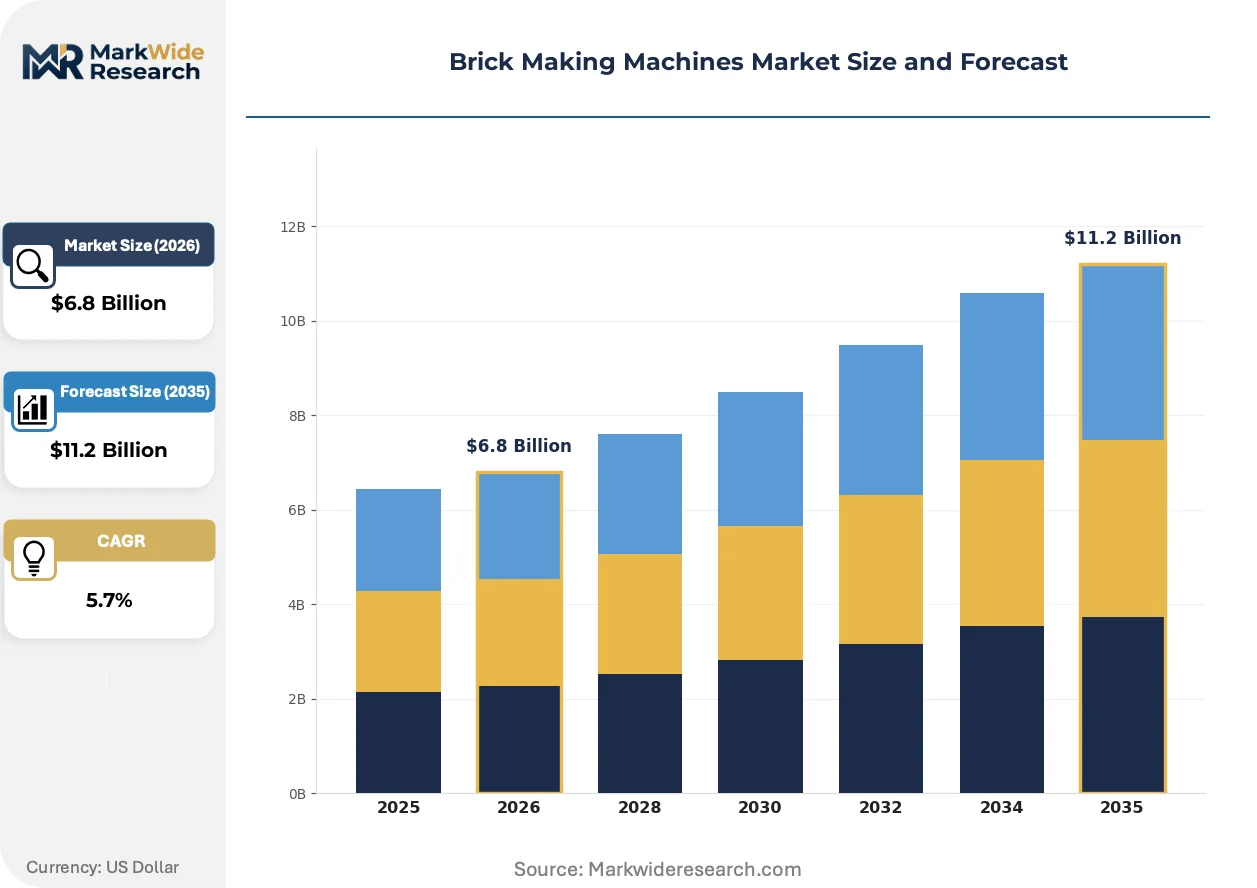
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interlocking Bricks, Hollow Blocks, Solid Bricks, Paver Blocks Technology: Automatic, Semi-Automatic, Manual, Hydraulic Material: Clay, Fly Ash, Concrete, Aggregate End User: Construction, Infrastructure, Residential, Commercial |
| Companies Covered | BESS Company, Zhengzhou Yingfeng Machinery Co., Ltd, Quangong Machinery (QGM), Aimix Group Co., Ltd., J.C. Steele & Sons Inc., Hydraform, Press Makina, Xi'an Brictec Engineering Co., Ltd., Sadhana Engineering Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brick Making Machines Market Emerging Trajectories
Electrification of forming and curing processes is rewriting equipment specifications across brick manufacturing, compressing the viable technology set toward hydraulic automation and away from thermal-intensive methods.
Servo-electric press drives with precision force feedback are rewriting energy efficiency benchmarks in clay and concrete block forming. Commercial builders in Germany and the Netherlands specify these systems for dimensional tolerance compliance in modular construction. The technology is rewriting supplier qualification criteria, excluding purely mechanical press manufacturers from premium tender pools.
China's MEE implements provincial energy-intensity quotas that restrict traditional kiln operations and incentivize electric press adoption. Industrial users in Shandong and Henan provinces face production caps unless they demonstrate electrification progress. Fly ash-lime brick producers are responding by accelerating hydraulic press procurement ahead of compliance deadlines.
Builder procurement departments now unbundle after-sales service from equipment capital contracts, negotiating separate performance-based maintenance agreements with third-party technical service providers. This pattern disrupts traditional manufacturer-captive service models across India's northern states. Mumbai and Delhi-based construction consortia lead this unbundling, treating press uptime guarantees as distinct from capital expenditure decisions.
Brick Making Machines Market Segmentation
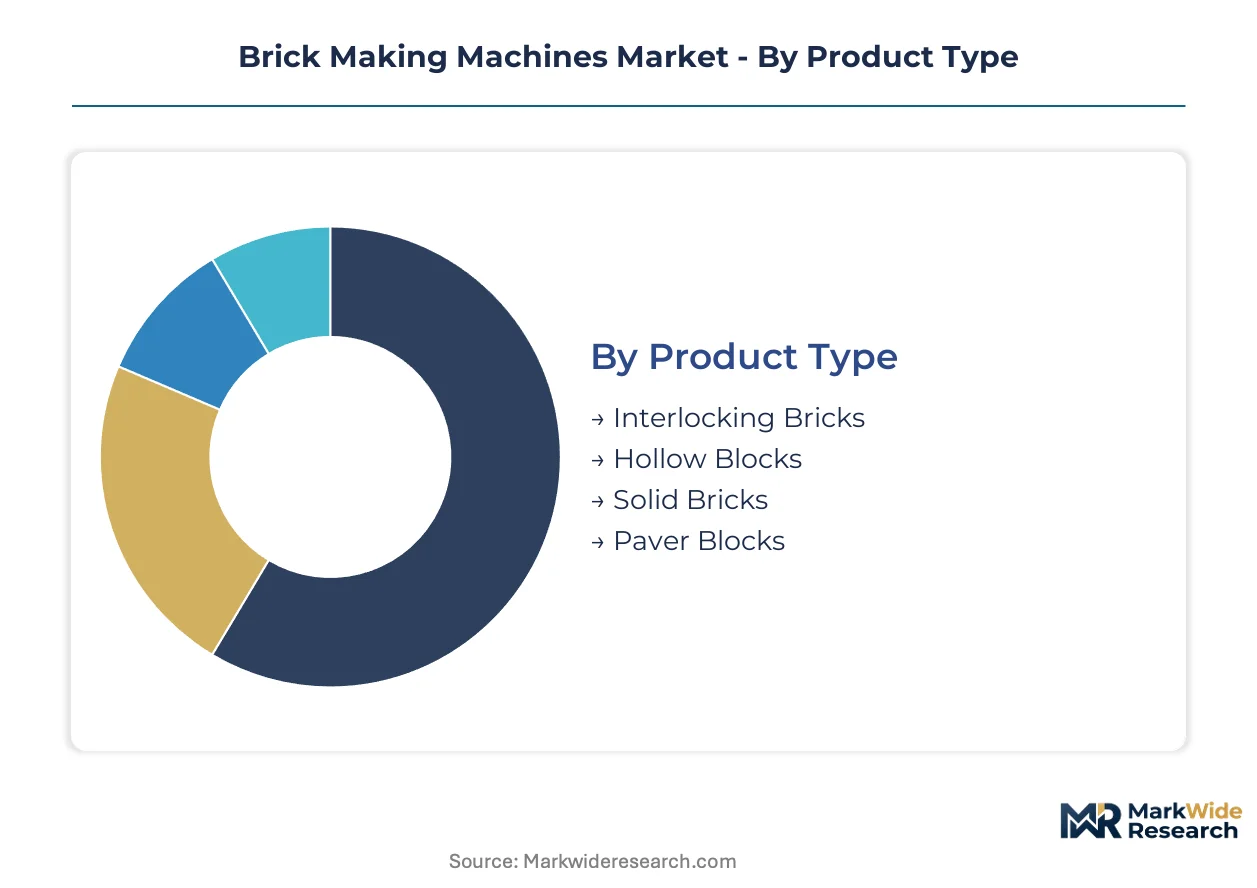
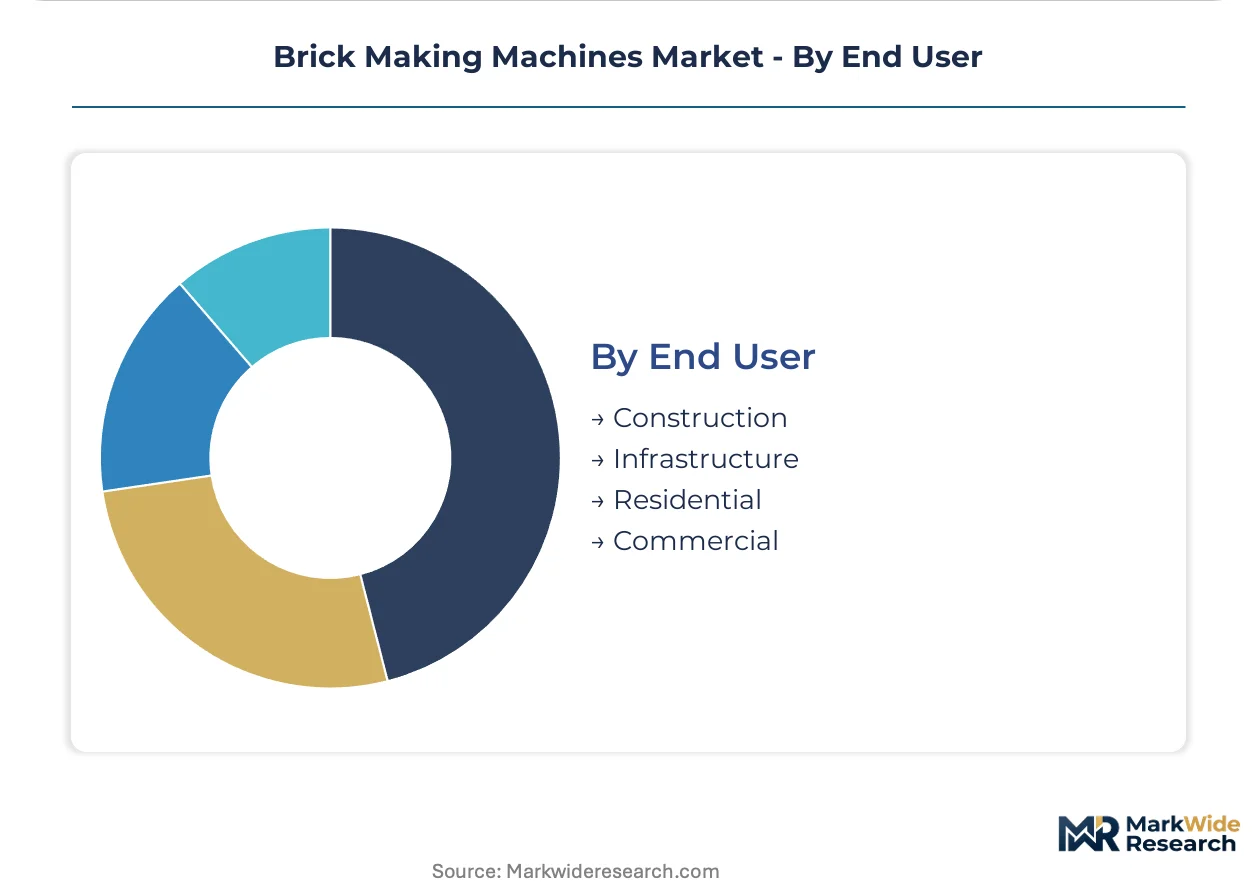
Brick making machines serve distinct production requirements across material formulations, automation levels, and end-use specifications. Equipment buyers segment procurement decisions by thermal efficiency mandates, labor cost structures, and compressive strength standards that vary by construction application and regulatory jurisdiction.
Product Type:
Specification diversity reflects competing pressures from thermal performance codes, structural load requirements, and installation labor economics.
- Hollow Blocks:Cavity-forming press dies create internal voids that reduce material weight while improving insulation R-values. Residential construction codes across Germany, the Netherlands, and India's northern states specify these units for external wall assemblies under thermal efficiency mandates. The segment is expanding most quickly as modular construction methods demand dimensional precision.
- Solid Bricks:Dense compression forming yields units with compressive strengths exceeding 30 MPa for load-bearing applications. Heritage-sensitive districts in Italy, France, and rural India specify these for aesthetic continuity with traditional masonry, preserving regulatory exemptions for fired-clay production methods.
- Interlocking Bricks:Tongue-and-groove profiles eliminate mortar requirements, reducing skilled labor dependency for low-cost housing in Bangladesh and Nigeria.
- Paver Blocks:Surface-textured dies produce load-distributing units for pedestrian and vehicular hardscaping across municipal infrastructure tenders in Brazil and South Africa.
Mature deployment sits with solid bricks. Newer deployment is concentrated in hollow blocks.
Technology:
Capital intensity and operating cost structures stratify the installed base across automation tiers.
- Automatic:Servo-electric drives with programmable logic controllers maintain ±2 millimeter tolerances across batch production. Germany's commercial builders and India's affordable housing missions specify these systems for volume consistency and reduced labor supervision.
- Hydraulic:Fluid-power actuation delivers high compression forces for dense aggregate formulations. China's Shandong and Henan provinces deploy these ahead of MEE energy-intensity quota deadlines.
- Semi-Automatic:Operator-fed material hoppers with automated compression cycles balance throughput and capital constraints for mid-scale producers in Vietnam and Indonesia.
- Manual:Lever-operated presses serve dispersed rural markets in Bangladesh and northern Nigeria where grid reliability limits electric equipment deployment.
Established capacity concentrates in hydraulic systems. Accelerating investment flows toward automatic configurations.
Material:
Feedstock selection determines curing protocol, emissions profile, and regulatory compliance pathway.
- Fly Ash:Pozzolanic waste material from thermal power generation reduces cement content in lime-based formulations. India's BIS certification mandates minimum compressive strength and dimensional uniformity, creating compliance pull for automated batch systems.
- Clay:Traditional fired-clay methods retain entrenched positions in heritage-sensitive European districts and rural Indian markets where regulatory exemptions preserve kiln operations.
- Concrete:Cement-aggregate mixtures with automated curing protocols serve infrastructure specifications in Kazakhstan and Uzbekistan.
- Aggregate:Crushed stone and sand blends with minimal cement binders address cost-sensitive commercial construction in South Africa and Kenya.
Conventional capacity centers on clay processing. Regulatory pressure is concentrating new investment in fly ash systems.
End User:
Procurement scale and specification stringency diverge across project types and ownership structures.
- Residential:Low-cost housing programs in India, Bangladesh, and Nigeria sustain continuous equipment replacement cycles with standardized block specifications and volume procurement.
- Infrastructure:Road, bridge, and utility projects in Central Asian export corridors specify high-strength pavers and retaining wall units with certified durability testing.
- Construction:General contracting consortia in Mumbai and Delhi unbundle after-sales service from capital contracts, negotiating separate uptime guarantees.
- Commercial:Retail and office developers in Germany and the Netherlands specify servo-electric presses for modular construction tolerance compliance.
Volume concentration remains with residential programs. Specification complexity is climbing fastest in commercial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi-Mumbai Industrial Corridor anchors procurement intensity for automated brick making systems, with state-level affordable housing missions sustaining continuous equipment replacement cycles across India's northern manufacturing belt.
India
Uttar Pradesh and Haryana drive equipment procurement through state affordable housing missions requiring machine-made bricks for low-cost residential construction. India's BIS certification for fly ash-lime bricks mandates minimum compressive strength standards, creating compliance barriers for manual operators. The Delhi-NCR manufacturing cluster concentrates hydraulic press deployment for fly ash brick production serving municipal infrastructure tenders.
China
Shandong and Henan provinces face production caps under MEE provincial energy-intensity quotas unless electrification progress is demonstrated. China's dual carbon goals restrict traditional kiln operations and incentivize electric press adoption among industrial brick producers. The Zhengzhou equipment manufacturing base supplies integrated kiln-to-press lines for Central Asian export corridors.
Germany
Commercial builders in Bavaria and North Rhine-Westphalia specify servo-electric presses for dimensional tolerance compliance in modular construction. The EU Green Deal's embodied carbon thresholds pivot European producers toward automated hydraulic systems with lower thermal footprints. The Stuttgart industrial corridor hosts precision engineering fabricators serving premium-tier equipment demand.
Bangladesh
Dhaka's urban housing programs expand machine-made brick procurement for low-cost residential construction despite grid reliability limitations in rural districts. Interlocking brick specifications eliminate mortar requirements, reducing skilled labor dependency for housing projects. The Chittagong port corridor channels equipment imports serving construction demand across the delta region.
Nigeria
Lagos and Abuja sustain equipment demand through federal and state-level housing programs targeting informal settlement upgrades. Electrification infrastructure gaps in northern states constrain electric press deployment regardless of emissions policy intent. The Kano industrial cluster retains entrenched networks of small-scale fired-clay producers with regulatory exemptions.
Brick Making Machines Market Vendor Landscape
The competitive structure tilts toward engineering-intensive specialists with captive hydraulic system capabilities. Equipment fabricators cluster around three strategic archetypes: German precision engineering houses dominating high-tolerance automated presses, Chinese integrated manufacturers controlling full production line ecosystems, and regional assemblers serving cost-sensitive emerging markets. Dominant competitive moves include backward integration into precision component manufacturing and technology licensing partnerships for servo-electric drive systems.
Among German-based precision engineering specialists, BESS Company exemplifies the high-tolerance automated press archetype serving EU Green Deal compliance requirements. Zhengzhou Yingfeng Machinery Co., Ltd and Xi'an Brictec Engineering Co., Ltd occupy positions within the integrated manufacturing line tier, anchoring Chinese supply for Central Asian infrastructure corridors. Quangong Machinery (QGM) sits within the scale-driven manufacturing segment, representing large-facility automated block production serving domestic infrastructure tenders.
| Leading Market Players |
|---|
| BESS Company |
| Zhengzhou Yingfeng Machinery Co., Ltd |
| Quangong Machinery (QGM) |
| Aimix Group Co., Ltd. |
| J.C. Steele & Sons Inc. |
| Hydraform |
| Press Makina |
| Xi'an Brictec Engineering Co., Ltd. |
| Sadhana Engineering Industries |
| Others |
Supply Flow & Price Mechanics
Precision hydraulics specialists concentrated in Germany's Stuttgart industrial corridor command wage premiums that widen spreads between servo-electric press tiers and standard hydraulic configurations. Labor-cost differentials between German engineering clusters and Chinese manufacturing bases translate into three-tier pricing architecture across premium automated systems, mid-range hydraulic lines, and economy-grade manual equipment.
Pricing Analysis
Throughput-guarantee contracts anchor pricing for automated brick making systems, with buyers paying premiums tied to verified production uptime rather than capital expenditure alone. Three-tier pricing structure across premium, standard, and economy levels separates German servo-electric systems with ±2 millimeter tolerance guarantees from Chinese hydraulic lines serving BIS certification compliance, with manual lever presses occupying the price-sensitive rural India and Bangladesh segments. Cost compression in mid-range hydraulic tiers is intensifying because Shandong and Henan province producers accelerate procurement ahead of MEE energy-intensity quota deadlines. State affordable housing missions in Uttar Pradesh and Haryana exhibit highest price sensitivity, while German commercial builders specifying modular construction tolerance compliance show least elasticity.
Supply Chain Analysis
India's PLI scheme for capital goods manufacturing and China's domestic-content requirements for infrastructure procurement are reshaping component sourcing toward localized foundry and precision machining capacity. Manufacturing concentration draws from Germany for high-tolerance hydraulic systems, China for integrated kiln-to-press lines, and India for mid-scale semi-automatic assemblies serving South Asian demand. Structural steel feedstock, precision hydraulic cylinders, and servo-electric drive modules constitute critical input dependencies. Single-source vulnerability sits with German-engineered force-feedback control systems that lack qualified second-source suppliers. Distribution runs through equipment financing consortia in Mumbai and Delhi that unbundle after-sales service from capital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brick manufacturing equipment is transitioning from thermal-intensive kiln methods to electrified press-based forming, with servo-electric drives displacing traditional fired-clay operations under emissions mandates.
For Market Incumbents: Anchor market position through backward integration into precision hydraulic component manufacturing, capturing margin that currently leaks to specialized cylinder fabricators. Invest in certification engineering for EU Green Deal embodied carbon compliance before carbon border adjustments tighten eligibility for emerging hub exports. Defend against Chinese integrated manufacturers by locking long-term service contracts with Indian state housing missions. For New Entrants and Emerging Players: Mid-scale semi-automatic buyers in Vietnam and Indonesia represent the most penetrable white-space segment, balancing throughput requirements against capital constraints that exclude full automation. Target fly ash-lime formulation specialists in India's Delhi-NCR cluster seeking BIS certification compliance without German price premiums. Pursue technology licensing partnerships for servo-electric drive systems rather than ground-up R&D. For Investors and Strategic Acquirers: The window for entry favors precision engineering specialists with captive hydraulic capabilities and existing EU regulatory compliance infrastructure. Long-term viability hinges on electrification technology portfolios that align with tightening emissions thresholds across multiple jurisdictions. Monitor MEE provincial quota enforcement intensity in Shandong and Henan as inflection indicator for Chinese equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captures hydraulic cylinder margins and reduces exposure to steel price volatility. |
| Servo-Electric Drive Technology Licensing | Accelerates compliance with EU Green Deal embodied carbon thresholds for German builders. |
| Central Asian Export Corridor Expansion | Positions integrated kiln-to-press lines for Kazakhstan and Uzbekistan infrastructure tenders. |
| Performance-Based Maintenance Unbundling | Aligns with Mumbai and Delhi construction consortia procurement patterns separating uptime guarantees from capex. |
| Fly Ash Formulation Certification Engineering | Creates compliance pull for automated batch systems under India's BIS compressive strength mandates. |
Methodological Framework
Document review covered customs and trade data, SEC filings from capital goods manufacturers, and MEE provincial energy-intensity quota disclosures, complemented by interviews with plant engineers at Indian fly ash brick facilities, procurement leads at German commercial construction consortia, and aftermarket service heads at Chinese integrated equipment manufacturers. Secondary validation drew from EU Green Deal regulatory texts, BIS certification standards for lime-based masonry units, and Central Asian infrastructure tender databases. Bottom-up equipment deployment estimates triangulated against top-down construction spending forecasts across the analysis window.
Installed base projections and replacement cycle timing emerged from modeling across automation tier, material formulation type, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included MEE enforcement intensity trajectories, state affordable housing mission budget allocations, and carbon border adjustment implementation schedules.
Revisions become necessary when MEE quota enforcement accelerates beyond modeled trajectories, EU carbon border adjustment scope expands to include embodied brick emissions, or grid reliability improvements in northern Nigeria and rural Bangladesh unlock electric press deployment ahead of baseline assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Europe Die Casting Machines Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market