
 Borehole Enlargement System Market | 2026-2036
Borehole Enlargement System Market Size, Share, and Industry Trends Forecast 2026-2036
Borehole Enlargement System Market Analysis
Independent operators and national oil companies is rotating toward premium borehole enlargement services as integrated majors trim discretionary spending. Schlumberger Ltd. leverages its drilling engineering heritage to anchor high-specification reamer deployments in deepwater basins. Baker Hughes Co. competes through integrated drillbit-to-reamer workflows that reduce non-productive time. NOV Inc. dominates the expandable tool segment with manufacturing scale across North American service centers.
A borehole enlargement system encompasses downhole tools engineered to mechanically or hydraulically increase wellbore diameter beyond the pilot hole size, typically operating at rotational speeds of 60-300 RPM and tolerating downhole temperatures exceeding 150°C in high-pressure formations. These systems stabilize wellbore geometry, eliminate tight spots, and prepare casing runs in extended-reach and horizontal drilling programs. PDC Bits and Expandable Tools command the deepest margin pools where proprietary cutter metallurgy and activation mechanisms create differentiation. Mechanical and Hybrid technologies lead volume deployment, though Chemical enlargement methods are gaining traction in geothermal and mining applications where thermal stress cracking aids underreaming efficiency.
API Specification 7-1 governs tool dimensional tolerances and materials certification, while ISO 10424-1 establishes international benchmarks for rotary drilling equipment interchangeability. OSHA and BSEE well control regulations in the United States indirectly shape demand by mandating redundant annular pathways that reliable enlargement systems must preserve. Stakeholders must monitor how evolving carbon-intensity disclosure rules from the EU and Gulf national regulators alter contractor qualification criteria for borehole conditioning services.
Market Dynamics
Expandable reamer technology is concentrating procurement power among national oil companies in the Middle East and offshore Latin America, compressing margins for tier-two service contractors while elevating API-certified hybrid systems as baseline qualification requirements.
Growth Catalysts
- Pre-salt basin complexity:Brazil's deepwater salt formations demand specialized borehole conditioning tools that stabilize reactive shale and prevent tight spots during extended-reach drilling programs.
- API Specification 7-1 certification mandates:Tighter dimensional tolerance standards push operators toward certified mechanical and hybrid enlargement systems that guarantee interchangeability across rig fleets.
- Geothermal sector expansion:Chemical enlargement methods gain traction in high-temperature hard-rock drilling where thermal stress cracking improves underreaming efficiency beyond conventional mechanical approaches.
Market Restraints
- Tungsten carbide supply concentration:Proprietary PDC cutter metallurgy depends on concentrated rare earth processing capacity, exposing tool manufacturers to input cost volatility and geopolitical supply disruption.
- Deepwater capex intensity:High-specification expandable reamer deployments require substantial upfront investment in activation mechanism R&D, limiting participation to capital-rich integrated service providers.
- ISO 10424-1 compliance friction:International equipment interchangeability standards create certification bottlenecks for regional tool fabricators attempting to enter premium offshore basins.
Strategic Opportunities
- Mining underreaming applications:Hard-rock extraction operations in Australia and Canada present untapped demand for chemical and thermal enlargement technologies adapted from oilfield tool heritage.
- EU carbon-intensity disclosure rules:Evolving contractor qualification criteria from Gulf national regulators create first-mover advantage for service companies with verified low-emission borehole conditioning workflows.
- Real-time downhole telemetry integration:Convergence of expandable tool activation mechanisms with MWD/LWD systems enables predictive reamer deployment based on formation evaluation data streams.
Industry Challenges
- Deepwater drilling engineering talent scarcity:Specialized expertise in high-pressure high-temperature tool design remains concentrated among legacy field engineers approaching retirement age.
- Legacy rig fleet integration complexity:Hybrid enlargement systems require retrofit compatibility with existing top-drive and BHA configurations, extending deployment timelines and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borehole Enlargement System Market |
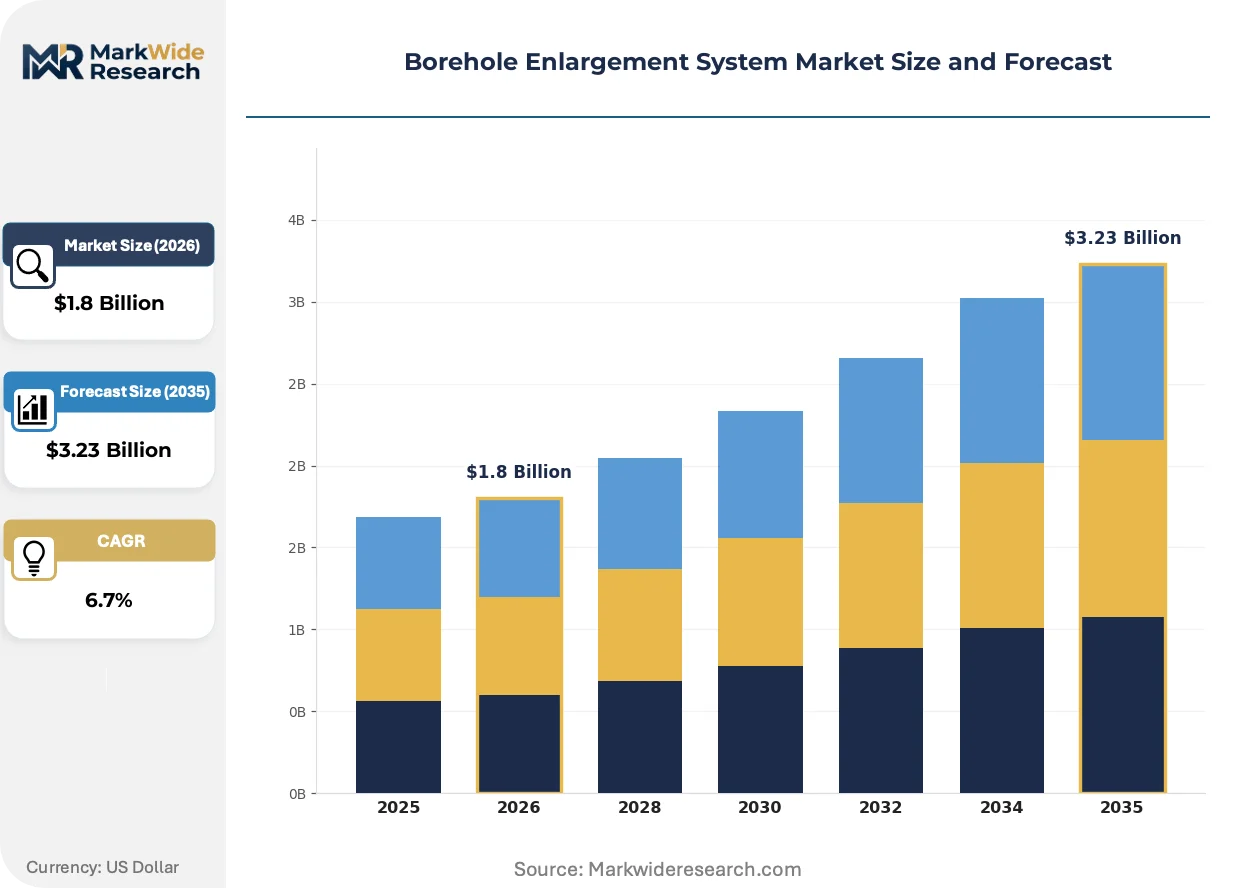
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond Bits, PDC Bits, Reamers, Expandable Tools Technology: Mechanical, Hydraulic, Chemical, Hybrid End User: Mining, Oil & Gas, Construction, Water Wells Application: Geotechnical, Environmental, Oilfield Development, Infrastructure |
| Companies Covered | Weatherford International Plc, Atlas Copco AB, Schlumberger Ltd., Drillstar Industries, Sandvik AB, Halliburton Co., NOV Inc., Paradigm Group BV, Baker Hughes Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borehole Enlargement System Market Emerging Trajectories
Downhole tool intelligence and materials science are converging to reshape competitive positioning in borehole conditioning services, with differentiation shifting from mechanical reliability to data-enabled formation response.
Self-adjusting expandable reamer technology is fragmenting the traditional fixed-blade market by enabling real-time diameter modulation based on downhole torque feedback. Offshore operators in Brazil and West Africa are adopting these systems at accelerated pace to reduce tripping frequency in heterogeneous formations. The technology is fragmenting procurement patterns as integrated majors demand outcome-based performance guarantees rather than tool rental rates.
OSHA and BSEE well control regulations in the United States mandate redundant annular pathways that certified enlargement systems must preserve during managed pressure drilling operations. These rules compress allowable non-productive time windows and elevate documentation requirements for tool activation sequences. Deepwater Gulf of Mexico operators respond by specifying API-certified hybrid systems with embedded pressure integrity verification.
Service contract unbundling is disrupting traditional bundled drilling packages as national oil companies separate borehole conditioning from integrated drilling services. Independent operators in the Middle East now procure expandable reamer technology through direct tool rentals rather than major contractor intermediaries. This pattern is most visible in Saudi Arabia and the UAE, where ADNOC and Aramco procurement frameworks favor discrete service qualification over integrated vendor relationships.
Borehole Enlargement System Market Segmentation
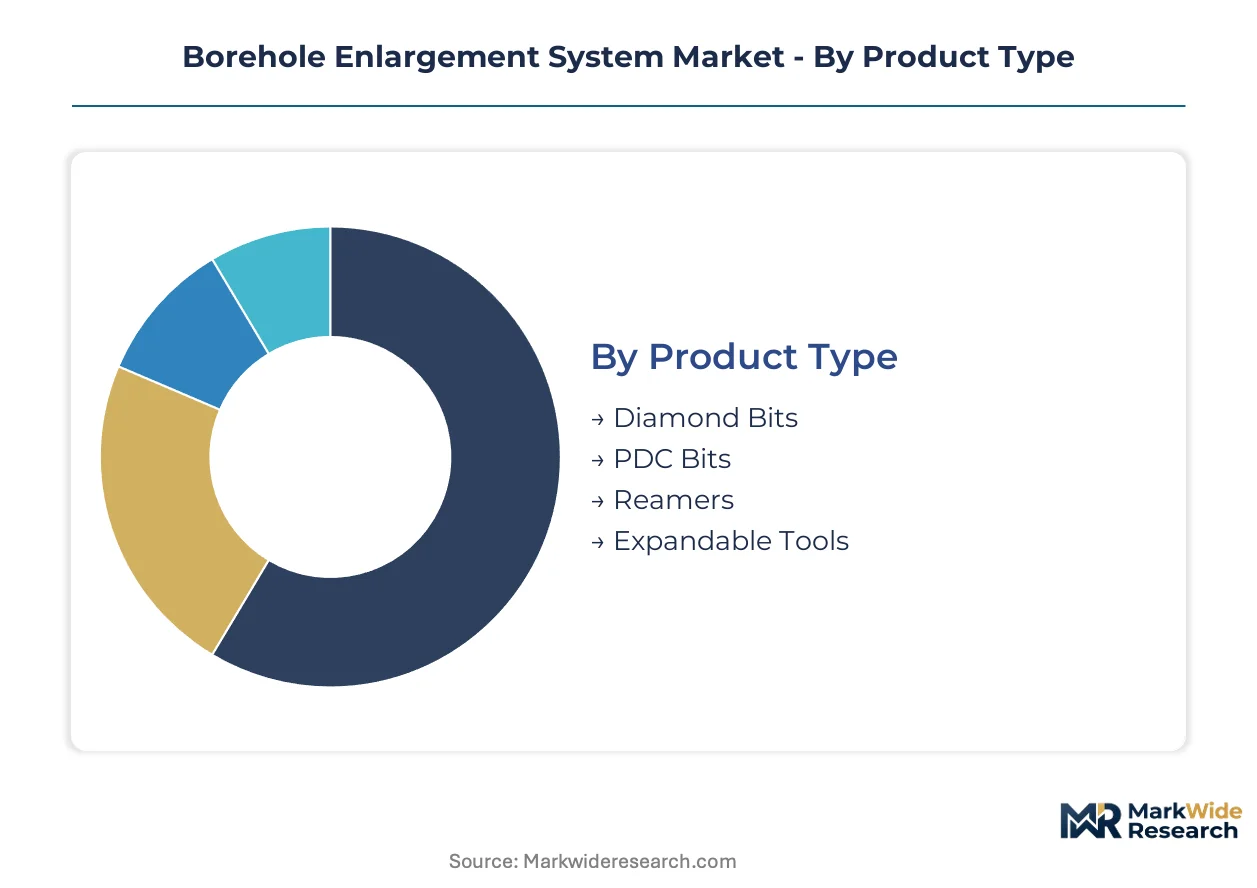
Borehole enlargement systems serve distinct operational regimes where tool specification directly determines drilling economics. Segmentation reveals how API certification tiers, formation hardness, and end-use capex cycles fragment procurement patterns across service contractors and national oil companies.
Product Type:
API Specification 7-1 dimensional tolerances separate premium-certified tools from standard-grade alternatives, with certification status determining interchangeability across rig fleets and basin qualification.
- PDC Bits:Polycrystalline diamond compact cutters bonded to tungsten carbide substrates deliver sustained penetration rates in abrasive formations. Brazil's pre-salt basins concentrate demand where proprietary metallurgy resists thermal degradation in high-pressure salt zones.
- Expandable Tools:Activation mechanisms enable downhole diameter modulation without tripping, preserving annular integrity during managed pressure drilling. Middle East national oil companies specify these for extended-reach laterals where tight-spot elimination reduces non-productive time.
- Diamond Bits:Natural and synthetic diamond matrices excel in geothermal hard-rock applications where thermal stress cracking complements mechanical cutting action.
- Reamers:Fixed-blade and bi-center configurations stabilize wellbore geometry in horizontal shale programs across North American unconventional basins.
PDC Bits handle the majority of throughput; Expandable Tools is the fastest mover on share.
Technology:
Cost tier stratification separates capital-intensive hybrid systems from rental mechanical tools, with operator size and drilling intensity determining technology selection.
- Hybrid:Combines mechanical cutting with hydraulic activation and real-time telemetry feedback, commanding premium day rates in deepwater Gulf of Mexico and West Africa. BSEE well control mandates elevate these to baseline qualification for managed pressure drilling.
- Mechanical:Conventional fixed-cutter and roller-cone systems dominate land rig deployments where simpler logistics and lower capital exposure match independent operator budgets. Permian Basin drilling programs represent the largest installed base.
- Hydraulic:Fluid-powered underreaming tools reduce torque fluctuations in reactive shale formations across the Vaca Muerta and Duvernay plays.
- Chemical:Thermal stress cracking methods gain traction in Australian and Canadian hard-rock mining where high-temperature drilling exceeds mechanical tool limits.
Mechanical technology retains volume leadership; Hybrid systems are climbing the fastest on contractor qualification requirements.
End User:
Application maturity and drilling intensity create divergent procurement cycles, with oilfield development capex volatility contrasting mining's steady equipment replacement schedules.
- Oil & Gas:Exploration and production companies drive specification innovation through pre-salt, deepwater, and unconventional shale programs. ADNOC and Aramco procurement frameworks now favor discrete borehole conditioning services over bundled drilling packages.
- Mining:Hard-rock extraction operations in Australia's Pilbara and Canada's Athabasca oil sands present untapped demand for chemical and thermal enlargement adapted from oilfield heritage.
- Construction:Foundation drilling and tunneling applications specify robust mechanical reamers for urban geotechnical projects with strict vibration and settlement constraints.
- Water Wells:Municipal and agricultural groundwater development favors cost-optimized mechanical systems with standardized API threading for rapid mobilization.
Oil & Gas commands the deepest specification tiers; Mining is expanding most quickly as technology transfer accelerates.
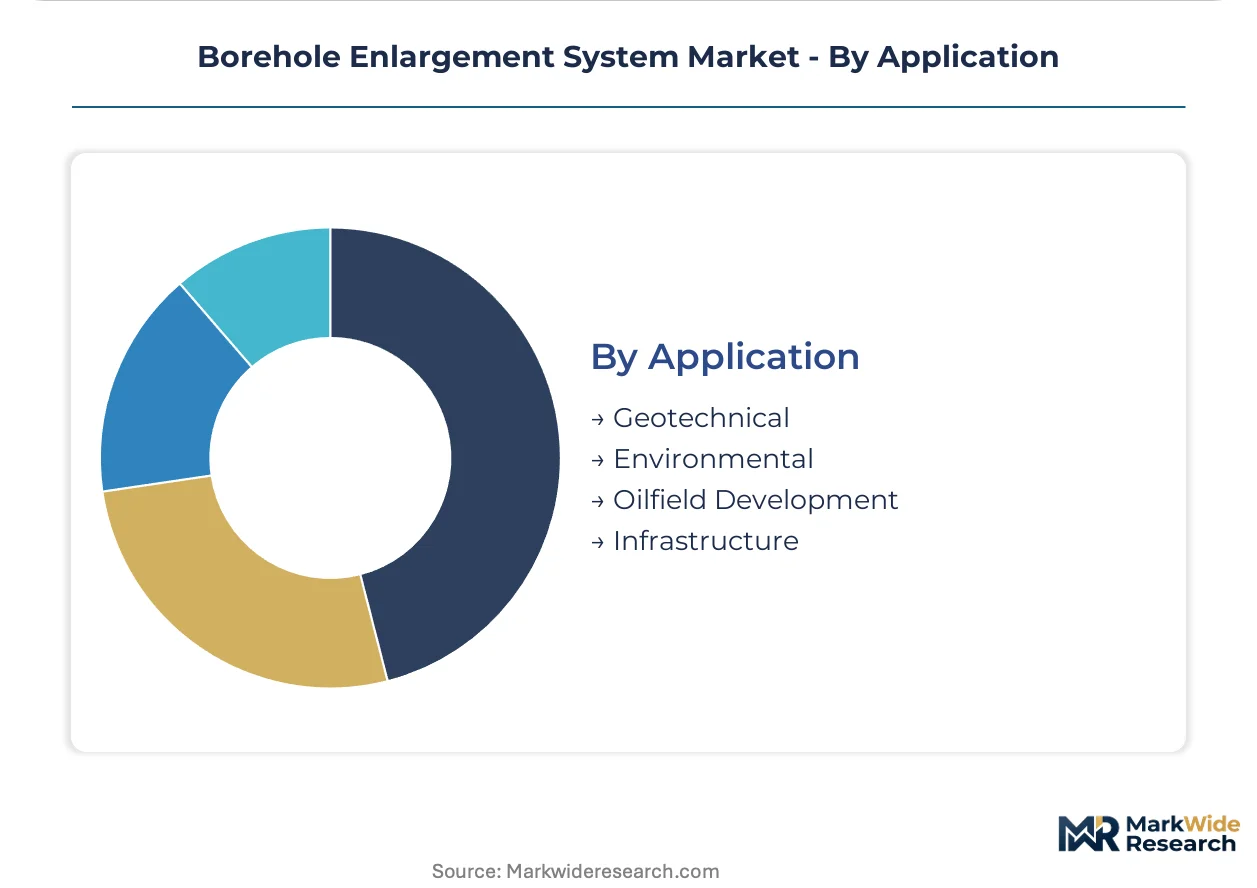
Application:
Geographic concentration of drilling activity and regulatory stringency shape segment performance, with offshore qualification standards filtering tool selection.
- Oilfield Development:Reservoir access drilling in Brazil, Guyana, and West Africa demands certified hybrid systems with embedded pressure integrity verification. ISO 10424-1 interchangeability standards create certification bottlenecks for non-compliant fabricators.
- Geotechnical:Site investigation and foundation engineering in urban corridors from Houston to Singapore specify precision reaming for soil sampling and instrumentation placement.
- Infrastructure:Tunnel boring machine pre-drilling and utility installation across European and East Asian metropolitan areas require vibration-controlled enlargement tools.
- Environmental:Remediation well drilling and groundwater monitoring in the United States follows EPA guidance on annular seal integrity, favoring reliable mechanical systems with documented activation sequences.
Oilfield Development absorbs the largest equipment investment; Geotechnical is gaining share fastest on infrastructure stimulus cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National oil companies in Saudi Arabia and Brazil concentrate procurement power for expandable reamer systems, while independent operators in North American shale basins drive mechanical tool replacement cycles. Regulatory tightening across multiple jurisdictions is elevating certified hybrid systems to baseline qualification status.
United States
Deepwater Gulf of Mexico operators specify API-certified hybrid enlargement systems with embedded pressure integrity verification to satisfy BSEE well control mandates. OSHA regulations compress allowable non-productive time windows and elevate documentation requirements for tool activation sequences. Houston anchors the largest concentration of drilling engineering talent and service contractor headquarters for high-specification reamer deployments.
Brazil
Pre-salt basin complexity drives specialized borehole conditioning demand as Petrobras and international partners stabilize reactive salt formations during extended-reach drilling programs. ANVISA and national petroleum regulator ANP enforce stringent equipment certification for subsea installations. Rio de Janeiro hosts the primary procurement decision-making for deepwater tool specifications across the Santos and Campos basins.
Saudi Arabia
Aramco procurement frameworks favor discrete borehole conditioning services over bundled drilling packages, compressing margins for tier-two contractors while elevating API-certified hybrid systems. SFDA and national standards body SASO align equipment import requirements with ISO 10424-1 interchangeability benchmarks. Dhahran concentrates engineering specification authority for extended-reach lateral programs in the Ghawar and Khurais fields.
United Arab Emirates
ADNOC procurement frameworks mandate certified expandable reamer technology for offshore development in the Upper Zakum and Lower Zakum fields. MOHAP and national oil company technical standards require redundant annular pathway preservation during managed pressure drilling operations. Abu Dhabi anchors regional specification authority for Middle East national oil company tool qualification.
Norway
North Sea operators deploy high-specification hybrid systems to satisfy Petroleum Safety Authority Norway well integrity requirements in high-pressure high-temperature formations. PSA regulations mandate real-time downhole telemetry integration for predictive reamer deployment in heterogeneous reservoirs. Stavanger concentrates subsea engineering expertise and contractor technical centers for North Atlantic deepwater programs.
Borehole Enlargement System Market Vendor Landscape
Player mix skews toward integrated oilfield service conglomerates with drilling heritage, creating a tiered structure where capital-rich majors control premium expandable tool segments and regional fabricators compete on mechanical system rental rates. Three strategic archetypes dominate: full-service drilling contractors with proprietary reamer integration, standalone tool specialists with manufacturing scale, and emerging technology licensors with activation mechanism IP. Competitive moves concentrate on strategic partnerships for telemetry convergence and geographic expansion into pre-salt and geothermal basins.
Among North American-based service providers, Schlumberger Ltd., Baker Hughes Co., and NOV Inc. occupy positions that exemplify the integrated-to-specialist spectrum. Schlumberger Ltd. anchors high-specification reamer deployments through drilling engineering heritage. Baker Hughes Co. represents integrated drillbit-to-reamer workflow positioning. NOV Inc. sits within the expandable tool manufacturing scale tier with North American service center concentration.
| Leading Market Players |
|---|
| Weatherford International Plc |
| Atlas Copco AB |
| Schlumberger Ltd. |
| Drillstar Industries |
| Sandvik AB |
| Halliburton Co. |
| NOV Inc. |
| Paradigm Group BV |
| Baker Hughes Co. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for tungsten carbide substrate deliveries concentrate procurement leverage among integrated service providers with captive raw-material positions, compressing rental-rate margins for independent mechanical-tool fabricators while elevating premium pricing power for API-certified hybrid system manufacturers.
Pricing Analysis
Current-generation hybrid expandable reamer systems command day-rate premiums of three-to-four times over prior-generation fixed-blade mechanical tools, while next-generation self-adjusting diameter modulation platforms in field trials promise further pricing separation through outcome-based performance guarantees. Pricing stratifies across premium-certified, standard-grade, and economy-rental tiers, with API Specification 7-1 certification and proprietary PDC cutter metallurgy as the primary differentiation drivers. Cost compression in the standard-grade tier is intensifying because Middle East national oil companies now procure expandable tools through direct rental channels rather than bundled drilling packages. Independent operators in North American shale basins exhibit the highest price sensitivity, prioritizing mechanical tool rental economics over telemetry-enabled hybrid capabilities.
Supply Chain Analysis
Inbound logistics costs from Asian tungsten processing centers through Houston and Rotterdam port complexes expose tool manufacturers to container availability volatility and trans-Pacific lane congestion, particularly for rare-earth-dependent PDC cutter substrates. Manufacturing concentration in the United States, Norway, and China anchors the upstream supply base, with tungsten carbide powder, synthetic diamond crystals, and high-strength alloy steels as critical input dependencies. Single-source vulnerability in Chinese rare-earth processing capacity represents the dominant structural supply risk. Distribution runs through North American and Middle East service center networks that stage finished tools adjacent to Permian Basin and Ghawar field drilling operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent service providers must defend against substitution from chemical and thermal enlargement technologies migrating out of geothermal and mining applications, as these methods bypass mechanical tool supply chains entirely in high-temperature hard-rock environments.
For Market Incumbents: Consolidate manufacturing scale in expandable tool activation mechanisms through backward integration into tungsten carbide substrate production, securing input cost stability against Chinese rare-earth export volatility. Anchor API-certified hybrid system portfolios with embedded real-time telemetry to meet BSEE well control mandates in the Gulf of Mexico and PSA Norway requirements, raising qualification barriers for non-integrated competitors. For New Entrants and Emerging Players: Differentiate on chemical enlargement technology adapted from oilfield heritage for Australian and Canadian hard-rock mining underreaming applications, where thermal stress cracking methods exceed mechanical tool temperature limits. Target mining sector procurement cycles as the most penetrable vertical, leveraging steadier equipment replacement schedules against oilfield capex volatility. Pursue direct equipment sales with aftermarket service contracts rather than rental-rate competition against entrenched majors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement power concentration among Saudi Aramco, ADNOC, and Petrobras favors capital-rich integrated service providers with manufacturing scale and certification depth. Acquisition target archetypes include standalone expandable tool specialists with proprietary activation mechanism IP and established Middle East or Brazil qualification status. Monitor geothermal sector drilling intensity as the critical inflection signal for chemical enlargement technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Production | Captive substrate supply insulates margins from Chinese rare-earth export volatility affecting PDC cutter costs. |
| Real-Time Telemetry Convergence with MWD/LWD Systems | Predictive reamer deployment based on formation evaluation data satisfies PSA Norway well integrity mandates. |
| Direct Mining Sector Equipment Sales Expansion | Australian Pilbara hard-rock extraction demand transfers oilfield chemical enlargement technology to steady replacement cycles. |
| API Specification 7-1 Certification Investment | Dimensional tolerance guarantees unlock interchangeability contracts across Aramco and ADNOC rig fleets. |
| Outcome-Based Performance Guarantee Structuring | Integrated majors in Brazil pre-salt basins now demand tool effectiveness commitments rather than day-rate pricing. |
Methodological Framework
Operator-level perspectives from drilling engineering directors, procurement managers at national oil companies, expandable tool product line managers, and aftermarket service heads anchored the qualitative base, cross-referenced against API certification databases, BSEE incident reports, SEC 10-K filings from listed service providers, and customs trade data for tungsten carbide import flows. Bottom-up rig-count and tool-deployment estimates triangulated with top-down service revenue attribution across product lines.
Sensitivity analysis around tungsten price volatility, pre-salt drilling activity trajectories, and geothermal sector penetration rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type certification tier, technology generation, end-use sector capex cyclicality, and regional regulatory stringency cluster. CAGRs derived from equipment replacement cycle analysis and basin-specific drilling intensity projections, with PDC cutter metallurgy advancement rates and expandable tool activation mechanism reliability curves as industry-specific forecast inputs.
Material uncertainties — abrupt rare-earth export restrictions, deepwater drilling moratoria, or step-change chemical enlargement efficiency breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about continued API and ISO standard convergence and national oil company procurement framework stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Logging Cable Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Auger Drilling Market