
 Autonomous Cranes Market | 2026-2036
Autonomous Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Cranes Market Analysis
Single-source component procurement for sensor arrays and hydraulic control modules is rebalancing toward multi-source strategies as OEMs seek supply resilience. Konecranes leverages its Nordic engineering heritage to dominate intelligent port crane retrofits across Baltic and North Sea terminals. Liebherr sustains family-owned manufacturing scale in all-terrain chassis production from its Ehingen complex. SANY competes aggressively on integrated electric drive systems for crawler configurations in domestic Chinese infrastructure projects.
Autonomous cranes denote self-propelled or fixed lifting equipment capable of executing load cycles without direct human operator intervention, typically integrating LiDAR, GPS-RTK positioning, and programmable logic controllers to achieve millimeter-grade placement accuracy in dynamic environments. Their primary purpose centers on eliminating operator exposure to hazardous heights, blind lifts, and repetitive musculoskeletal strain in continuous-duty material handling. The all-terrain product category anchors premium pricing due to combined highway mobility and rough-site deployment, while crawler configurations dominate mining applications where ground pressure limits apply. Artificial Intelligence as a technology layer represents the fastest-expanding margin pool, particularly in predictive load-sway compensation and real-time path optimization, whereas telematics functions as the mature baseline connectivity standard across installed fleet retrofits.
The EU Machinery Directive and CE marking requirements enforce functional safety validation for autonomous crane control systems entering European terminal and construction sites. OSHA crane operator certification rules in the United States create compliance complexity that automation suppliers must address through documented fail-safe protocols and remote supervisory interfaces. China's GB standards for construction machinery safety, administered by SAMR, mandate type-testing of autonomous functions before domestic deployment. Stakeholders must monitor how divergent regional safety-integrity level expectations reshape R&D allocation and product platform architecture decisions across geographies.
Market Dynamics
The collision avoidance software stack is modularizing faster than hardware refresh cycles, forcing crane OEMs to decouple sensor procurement from control system architecture and reshaping how terminal operators negotiate retrofit contracts.
Growth Catalysts
- EU Machinery Directive compliance deadlines:Terminal operators in Hamburg and Antwerp accelerate gantry crane upgrades to meet functional safety validation requirements before enforcement windows tighten.
- 5G private network deployment:China's MIIT spectrum allocations enable real-time kinematic positioning with sub-centimeter accuracy in Yangtze River Delta container terminals.
- Port labor contract renegotiations:Collective bargaining outcomes in Rotterdam and Long Beach embed automation clauses that mandate unmanned crane deployment for new berth construction.
Market Restraints
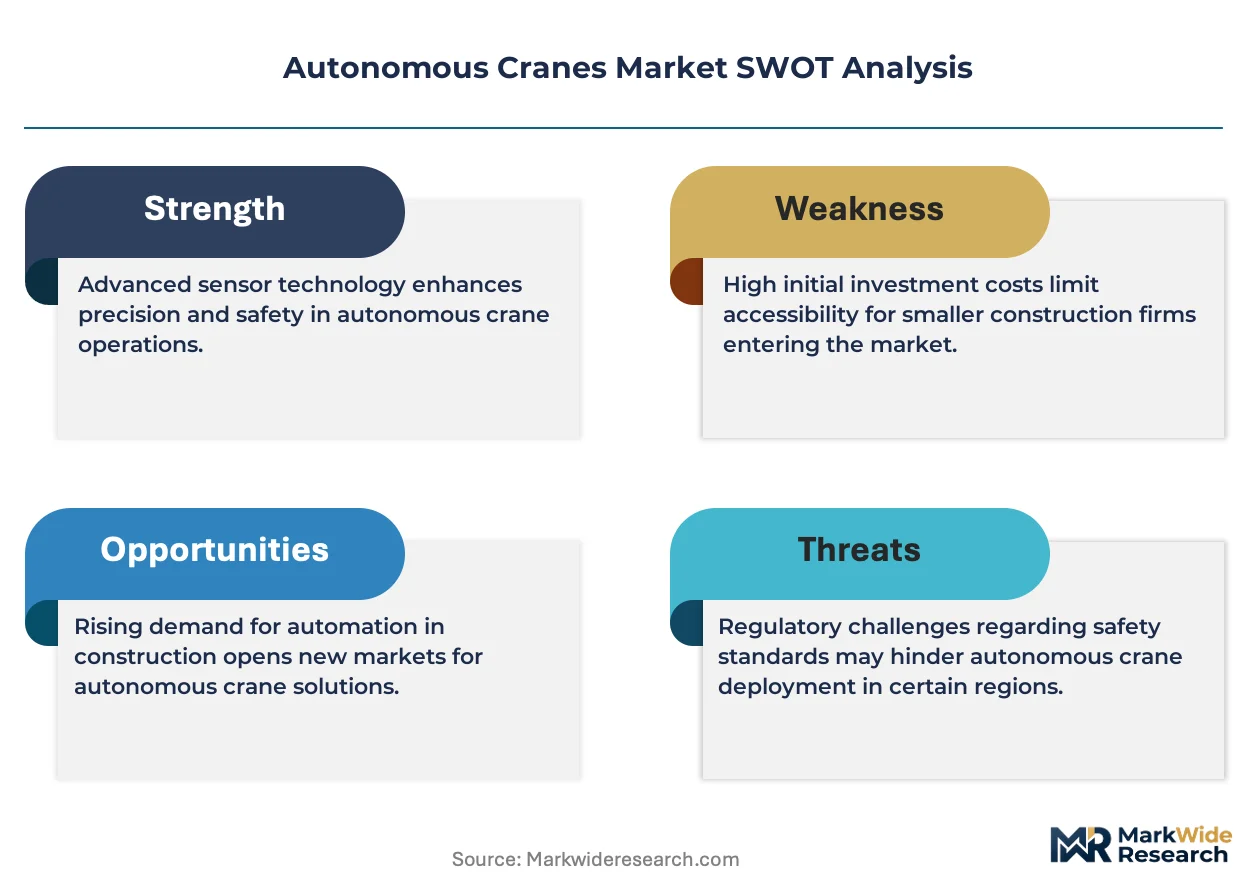
- LiDAR sensor supply concentration:German and Japanese photonics suppliers control high-specification scanning modules, creating single-source vulnerability for OEMs scaling production.
- OSHA crane operator certification persistence:US regulatory frameworks require human supervisory presence even in fully automated cycles, limiting labor cost reduction potential.
- Legacy fleet mechanical heterogeneity:Pre-2015 crawler crane hydraulic architectures resist standardized control retrofits, fragmenting addressable installed base.
Strategic Opportunities
- India port privatization wave:Adani Ports and JSW Infrastructure tenders specify autonomous quay crane requirements for greenfield terminals at Mundra and Hazira.
- EU AI Act liability frameworks:Machinery manufacturers gain clarity on algorithmic fault attribution, accelerating insurance product development for autonomous lifting systems.
- Telematics-to-AI convergence:Fleet data aggregation platforms from construction equipment OEMs now train predictive load-sway models for crane-specific applications.
Industry Challenges
- Functional safety engineer scarcity:IEC 61508 certification expertise concentrates in Nordic and German engineering consultancies, constraining validation throughput for new market entrants.
- Retrofit integration complexity:Siemens and Rockwell PLC architectures from 2005-2015 era terminals require custom gateway development to interface with modern perception stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Cranes Market |
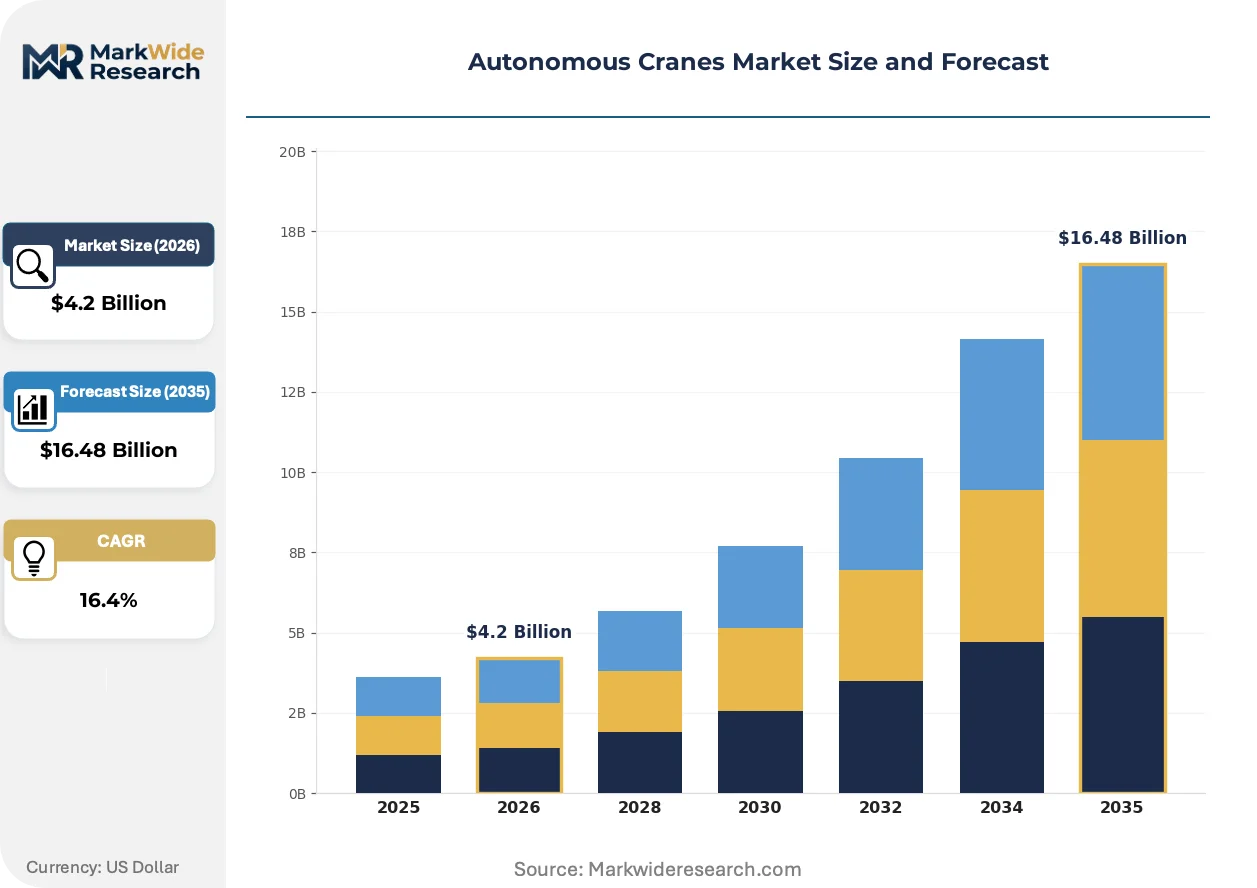
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $16.48 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rough Terrain, Truck-Mounted, Crawler, All-Terrain Technology: Telematics, Robotics, Artificial Intelligence, Sensors End User: Construction, Mining, Shipping, Infrastructure Installation: Fixed, Mobile, Semi-Fixed, Temporary |
| Companies Covered | Columbus McKinnon Corporation, Manitowoc, Konecranes, ZPMC, SANY, Liebherr, PALFINGER, Komatsu, XCMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Cranes Market Emerging Trajectories
Machine learning inference is migrating from cloud to edge compute nodes mounted directly on crane trolleys, eliminating latency in dynamic obstacle detection and enabling closed-loop control decisions without ground station dependency.
Edge AI accelerators from NVIDIA and Qualcomm are modularizing crane perception systems, allowing port operators to upgrade object detection models without replacing entire sensor suites. Baltic Sea terminal operators pilot this architecture for ice and fog conditions. The technology is modularizing procurement decisions, separating hardware lifecycles from software capability roadmaps.
China's GB standards for construction machinery safety now mandate type-testing of autonomous functions before domestic deployment, administered by SAMR. This creates a two-track certification burden for multinational OEMs seeking to serve Chinese infrastructure projects. Crawler crane configurations face extended validation timelines compared to fixed gantry systems.
Terminal operators increasingly unbundle crane maintenance contracts from original equipment suppliers, engaging third-party industrial service firms for predictive analytics and spare parts logistics. This procurement pattern shift compresses OEM aftermarket margins while expanding addressable market for specialized telematics providers. The trend is most pronounced in Singapore and UAE port clusters where operator consolidation has strengthened buyer bargaining power.
Autonomous Cranes Market Segmentation
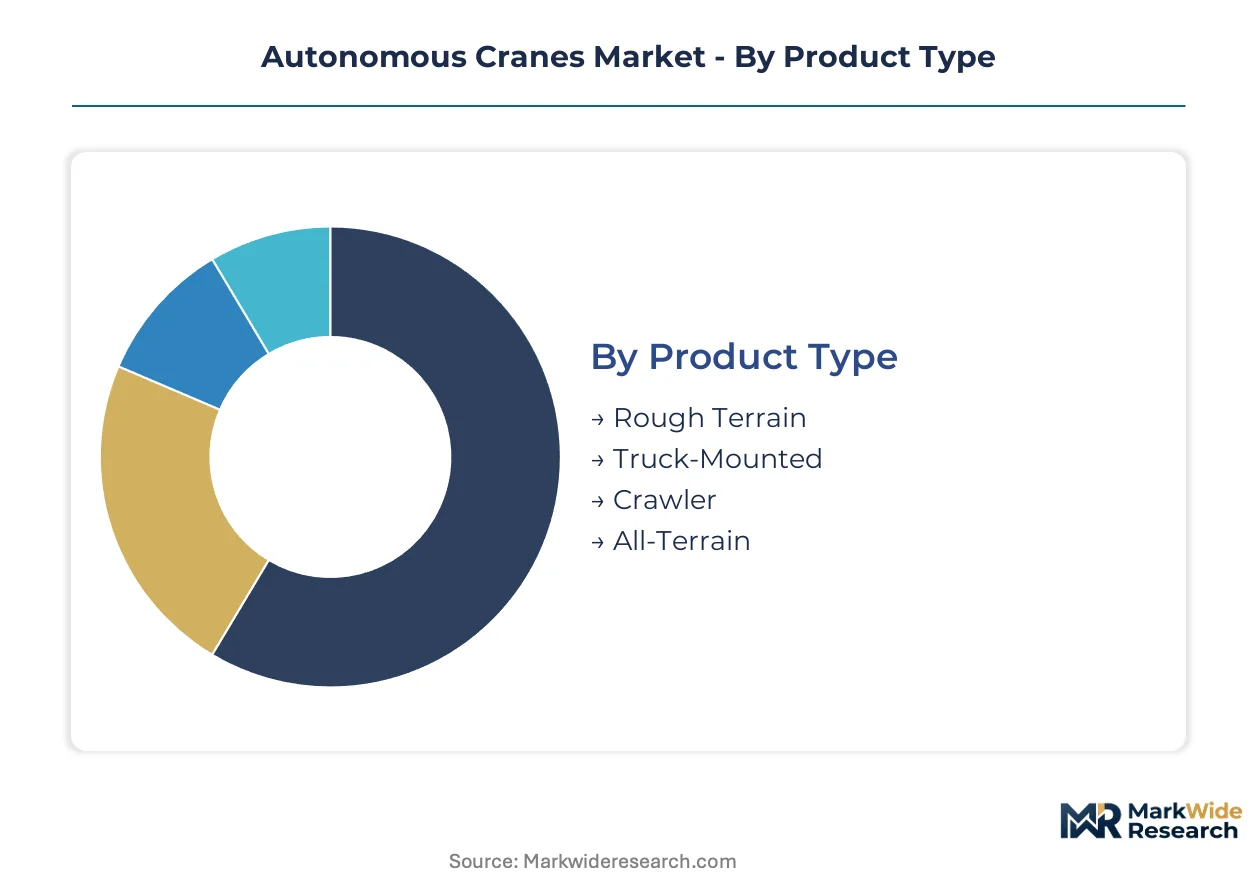
Segmentation in autonomous cranes reveals divergent technology readiness across mobility configurations and installation permanence. Product type and technology layer decisions determine capital intensity, retrofit feasibility, and regulatory validation burden for terminal operators and construction firms.
Product Type:
Volume concentration favors mobile configurations for multi-site deployment flexibility, while premium pricing attaches to highway-capable all-terrain variants.
- All-Terrain:Combines rough-site flotation with highway travel speeds up to 80 km/h, eliminating transport logistics that idle crawler fleets. Demand clusters in German wind farm construction and North Sea offshore component staging, where rapid inter-site repositioning justifies 40-60% capital premiums over fixed gantry alternatives. Mature deployment sits with all-terrain configurations in European renewable energy corridors.
- Crawler:Distributes machine weight across broad track footprints, enabling lifts on unprepared ground with sub-5 psi ground pressure. Mining operators in Western Australia and Chilean copper belts specify these for pit slope maintenance where soil bearing capacity limits apply. Newer deployment is concentrated in crawler systems for autonomous mining haul road maintenance.
- Rough Terrain:Four-wheel steer and oscillating axles navigate unimproved construction sites without crane mat deployment. Compact outrigger spans suit confined urban infill projects in Dubai and Singapore.
- Truck-Mounted:Integrates boom systems onto commercial chassis for rapid mobilization on paved road networks. Utility contractors in Texas and Florida deploy these for distribution line maintenance where speed-to-site dominates lift capacity.
Fixed-base gantry systems anchor established port automation, while crawler and all-terrain variants capture greenfield mining and renewable energy construction.
Technology:
Technology layering separates baseline connectivity from predictive intelligence, with margin accumulation shifting toward algorithmic control systems.
- Artificial Intelligence:Enables predictive load-sway compensation and real-time path optimization through machine learning models trained on fleet telemetry archives. Edge inference deployment on crane trolleys eliminates ground station latency for dynamic obstacle response. Demand concentrates in Yangtze River Delta container terminals where 5G infrastructure supports sub-50ms control loops. AI represents the steepest expansion trajectory among technology layers.
- Sensors:LiDAR, radar, and camera arrays generate 3D point clouds for millimeter-grade positioning in GPS-denied environments. Cold-climate ports in Rotterdam and Hamburg prioritize multi-spectral redundancy for ice and fog penetration.
- Telematics:Functions as the mature connectivity baseline across installed fleet retrofits, transmitting operational hours, fault codes, and geofence violations to fleet management platforms. Standardized on construction equipment since 2015.
- Robotics:Encompasses automated luffing, trolley traverse, and hoisting actuation without human cabin occupancy. Integration complexity limits deployment to greenfield terminal builds with purpose-designed electrical architectures.
Telematics penetration approaches saturation in container handling fleets. Robotics and AI integration accelerate most quickly in new-build mining and port automation.
End User:
End-use concentration reflects infrastructure investment cycles and labor cost structures across heavy industry verticals.
- Shipping:Container terminal operators in Singapore and Rotterdam deploy unmanned gantry systems to reduce accident rates and renegotiate labor contracts. Berth automation mandates in collective bargaining agreements accelerate replacement timelines.
- Construction:General contractors face fragmented project durations and site conditions that complicate autonomous system amortization. Tower crane automation progresses faster in markets with elevated operator wages.
- Mining:Pit maintenance and haul road construction applications favor crawler autonomy for 24-hour continuous operation in remote locations. Australian iron ore operators lead fleet conversion.
- Infrastructure:Bridge and highway agencies specify truck-mounted and all-terrain units for emergency response and maintenance window constraints. Public procurement emphasizes interoperability with existing fleet management systems.
Shipping terminals concentrate mature autonomous deployment. Mining and infrastructure sectors present the largest untapped addressable base for retrofit suppliers.
Installation:
Installation permanence determines sensor infrastructure investment and control system architecture choices.
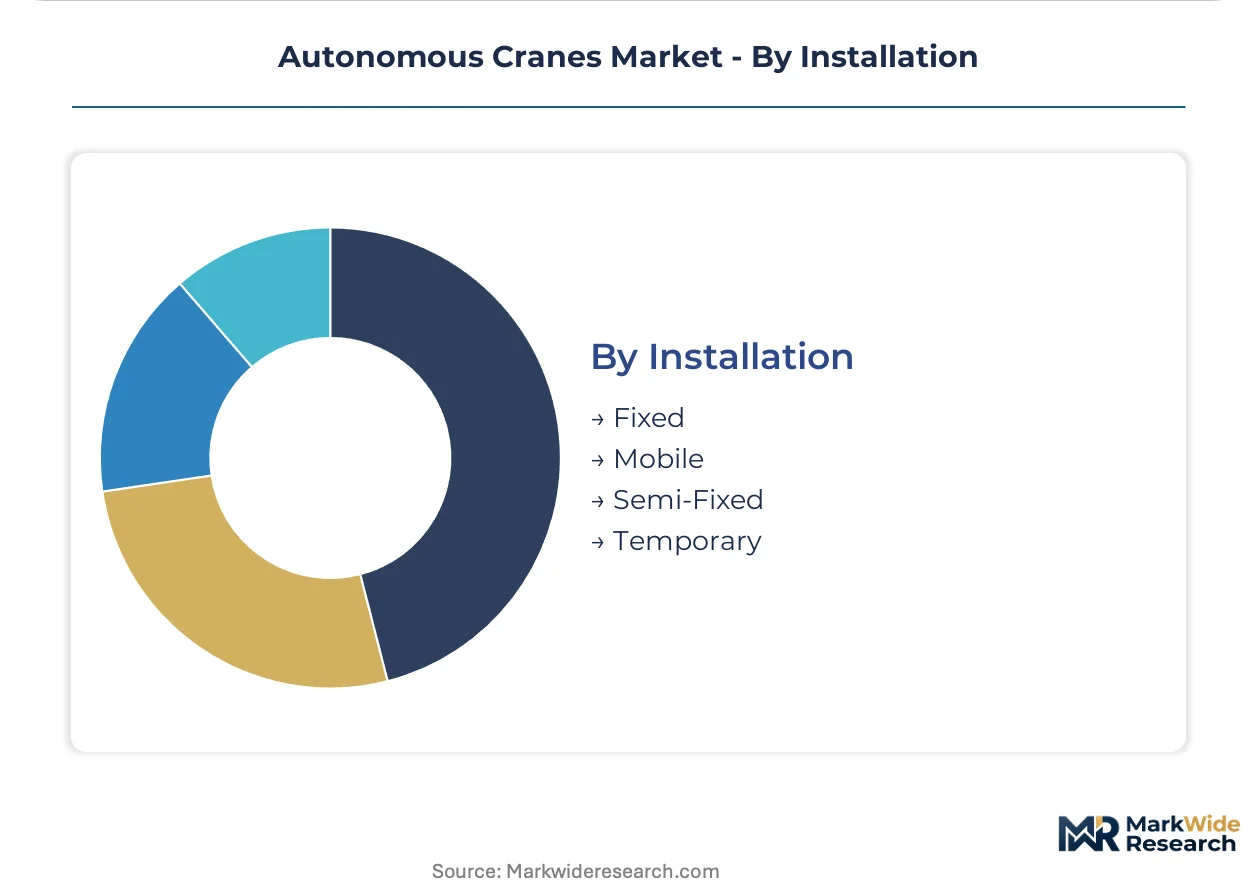
- Fixed:Rail-mounted gantry cranes at container terminals integrate ground-based positioning infrastructure and dedicated fiber networks. Capital intensity supports full autonomy with remote supervisory stations.
- Mobile:Crawler and all-terrain units carry complete perception and compute payloads, enabling autonomous operation without site preparation. Battery-electric powertrains from SANY and XCMG extend silent operating windows in urban construction.
- Semi-Fixed:Modular gantry systems relocate on rail or skid foundations between construction phases. Infrastructure projects in India and Southeast Asia favor this configuration for multi-year site evolution.
- Temporary:Rental fleet operators test autonomous retrofits on select units for high-value industrial maintenance contracts. Short deployment horizons limit sensor specification to telematics and collision avoidance.
Fixed installations anchor revenue concentration in port automation. Mobile and semi-fixed configurations expand most quickly into construction and mining applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta port cluster concentrates the heaviest near-term deployment of autonomous gantry systems, with state-backed automation mandates converging with 5G infrastructure investments to compress procurement timelines for terminal operators.
China
MIIT spectrum allocations enable real-time kinematic positioning with sub-centimeter accuracy across Shanghai and Ningbo-Zhoushan terminals. SAMR-administered GB standards mandate type-testing of autonomous functions before domestic deployment, creating extended validation timelines for crawler configurations. Yangtze River Delta operators accelerate unmanned quay crane procurement ahead of collective bargaining renegotiations.
United States
OSHA crane operator certification rules require human supervisory presence even in fully automated cycles, constraining labor cost reduction potential for port automation projects. Long Beach terminal operators embed automation clauses in labor contracts that mandate unmanned crane deployment for new berth construction. Texas utility contractors deploy truck-mounted units for distribution line maintenance where speed-to-site dominates capacity metrics.
Germany
EU Machinery Directive compliance deadlines accelerate gantry crane upgrades in Hamburg and Bremerhaven to meet functional safety validation requirements. KBA and federal state authorities coordinate on autonomous vehicle interface standards for all-terrain crane highway travel. Wind farm construction corridors in Lower Saxony and Schleswig-Holstein anchor premium pricing for rapid inter-site repositioning capabilities.
Singapore
Port operator consolidation strengthens buyer bargaining power for maintenance contract unbundling from original equipment suppliers. PSA Corporation and Jurong Port tenders specify autonomous quay crane requirements with predictive analytics integration. Maritime and Port Authority regulations align with IMO guidelines on autonomous vessel-to-shore cargo handling interoperability.
Australia
Western Australian iron ore operators lead fleet conversion for pit maintenance and haul road construction applications favoring crawler autonomy. Work Health and Safety regulations in Queensland and Western Australia drive operator exposure reduction mandates for remote mining locations. Pilbara region operators specify 24-hour continuous operation capabilities for autonomous crawler deployments.
Autonomous Cranes Market Vendor Landscape
Strategic partnerships dominate the current landscape as crane OEMs decouple sensor procurement from control system architecture to accelerate retrofit contract capture. The vendor base separates into three distinct tiers: integrated port system specialists, mobile crane chassis manufacturers, and emerging perception stack suppliers. Nordic engineering heritage anchors premium positioning for intelligent retrofits, while Chinese state-backed OEMs compete on integrated electric drive systems. Portfolio diversification and technology licensing represent the two dominant competitive moves reshaping procurement negotiations.
Among Nordic-based system integrators, Konecranes exemplifies the intelligent port crane retrofit archetype through its heritage positioning across Baltic and North Sea terminals. Liebherr occupies a position within the family-owned manufacturing tier, with its Ehingen complex sustaining scale in all-terrain chassis production. SANY represents the state-backed integrated systems archetype, competing on electric drive configurations for domestic infrastructure projects. These three anchors illustrate how geographic origin and capital structure determine competitive positioning across the technology layering transition.
| Leading Market Players |
|---|
| Columbus McKinnon Corporation |
| Manitowoc |
| Konecranes |
| ZPMC |
| SANY |
| Liebherr |
| PALFINGER |
| Komatsu |
| XCMG |
| Others |
Supply Flow & Price Mechanics
Terminal operator consolidation in Singapore and UAE port clusters is forcing maintenance contract unbundling from original equipment suppliers, compressing OEM aftermarket margins and compelling suppliers to absorb sensor integration costs into upfront crane pricing. This procurement pattern shift feeds back into multi-source strategies for LiDAR arrays and hydraulic control modules as buyers demand supply resilience premiums.
Pricing Analysis
Volume concentrates in telematics-enabled retrofit packages while margin accumulates in AI-driven predictive load-sway systems. Three-tier pricing structure across premium, standard, and economy levels separates fully autonomous gantry deployments from collision-avoidance retrofits and basic connectivity upgrades. Cost compression in standard-tier crawler configurations is intensifying because Chinese electric drive OEMs compete aggressively on integrated systems. Construction contractors exhibit highest price sensitivity due to fragmented project durations, whereas mining operators prioritize 24-hour continuous operation capabilities over unit cost.
Supply Chain Analysis
Functional safety engineer scarcity in Nordic and German engineering consultancies constrains validation throughput, forcing OEMs to relocate IEC 61508 certification activities or extend lead times. Component manufacturing concentrates in Germany for high-specification photonics, Japan for precision scanning modules, and China for electric drive systems. Raw material dependencies span rare earth elements for motor magnets, high-purity silicon for LiDAR receivers, and specialized steel alloys for crawler track systems. Single-source vulnerability in German and Japanese photonics suppliers creates structural risk for OEMs scaling production. Distribution runs through terminal operator procurement consortia and construction equipment rental fleets with integrated fleet management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive and OSHA crane operator certification rules create a cost-of-compliance moat where functional safety validation expertise concentrates among incumbent Nordic and German engineering consultancies, raising barriers for unvalidated market entrants.
For Market Incumbents: Extend certification investment into Chinese GB standards administered by SAMR to capture Yangtze River Delta port automation mandates before state-backed OEMs dominate domestic retrofits. Deepen backward integration into edge AI accelerators from NVIDIA and Qualcomm to modularize perception systems and separate hardware lifecycles from software roadmaps, defending margin position against third-party industrial service firms entering predictive analytics. For New Entrants and Emerging Players: Begin with crawler autonomy for Australian iron ore pit maintenance, where Work Health and Safety regulations drive operator exposure reduction mandates and 24-hour continuous operation specifications outpace incumbent response capacity. Target India's port privatization wave at Mundra and Hazira, where Adani Ports and JSW Infrastructure tenders specify autonomous quay crane requirements without legacy fleet mechanical heterogeneity constraints. Pursue telematics-to-AI convergence partnerships with construction equipment OEMs possessing fleet data aggregation platforms. For Investors and Strategic Acquirers: The window for entry favors perception stack suppliers with edge compute deployment experience and existing relationships with Baltic Sea terminal operators piloting ice and fog condition architectures. Long-term viability hinges on algorithmic fault attribution clarity under EU AI Act liability frameworks accelerating insurance product development. Watch for collective bargaining outcomes in Rotterdam and Long Beach embedding automation clauses that mandate unmanned crane deployment for new berth construction as inflection indicator for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Expansion | EU Machinery Directive compliance deadlines in Hamburg and Antwerp accelerate gantry crane upgrade procurement for validated suppliers. |
| Edge AI Accelerator Integration | NVIDIA and Qualcomm modules mounted on crane trolleys eliminate ground station latency for dynamic obstacle response. |
| Multi-Source Sensor Procurement | Decoupling LiDAR procurement from control architecture reduces single-source vulnerability to German and Japanese photonics suppliers. |
| Telematics-to-AI Convergence | Fleet data aggregation platforms from construction equipment OEMs train predictive load-sway models for crane-specific applications. |
| Maintenance Contract Unbundling | Third-party industrial service firms capture predictive analytics and spare parts logistics from compressed OEM aftermarket margins. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with port automation directors, terminal procurement managers, crane OEM engineering leads, aftermarket service heads, and functional safety certification consultants. Secondary validation drew from EU Machinery Directive enforcement notices, OSHA crane operator certification rulemakings, SAMR GB standard type-testing records, and MIIT spectrum allocation disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across product type, technology layer, end-use vertical, and installation permanence dimensions.
Data-stream reconciliation merged equipment shipment records with terminal operator capital expenditure disclosures and mining fleet conversion announcements. Segmentation dimensions modeled include mobility configuration, autonomy technology tier, end-use industry vertical, and regional regulatory cluster throughout the forecast period. CAGRs derived from fitted growth curves applied to validated baseline volumes, with cross-reference to 5G private network deployment timelines and port labor contract renegotiation schedules as industry-specific demand timing inputs.
Underlying measurement precision varies by segment; fixed gantry port automation carries tighter precision than mobile construction deployments given consolidated operator reporting. Forecasts reflect documented assumptions regarding enforcement timeline adherence, spectrum allocation implementation, and collective bargaining outcome patterns. Material deviation in EU Machinery Directive compliance deadlines, OSHA regulatory relaxation, or Chinese state-backed automation mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Piles Turner Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Global Vibratory Hammer Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Jackhammer Market
Construction Equipment
Winch Market